
 Animal Feed Market | 2026-2036
Animal Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Market Intelligence
The market for value-added, functional feed additives is decoupling from the commodity-driven bulk feed segment, creating distinct competitive arenas. Archer Daniels Midland specializes in developing and marketing high-margin specialty ingredients like amino acids and enzymes. In contrast, Cargill leverages its extensive global logistics and grain sourcing network to compete on scale in compound feed. New Hope Group dominates the vast Chinese market by integrating feed production with its extensive livestock farming operations.
Animal feed comprises scientifically formulated nutritional products designed for livestock, aquaculture, and companion animals. These formulations contain a precise balance of macronutrients like proteins and fats, alongside essential micronutrients including vitamins and minerals, to optimize animal health and productivity. While compound feed for poultry and swine constitutes the largest volume segment, the feed additives category represents the fastest-growing area. Formulations in pellet and crumble forms are standard for large-scale operations, ensuring consistent intake and minimal waste.
Regulatory frameworks are a primary force shaping product development and market access. In the United States, the FDA enforces strict controls on the use of antibiotics in medicated feeds. Similarly, the European Food Safety Authority (EFSA) sets rigorous standards for feed additives to ensure animal welfare and food safety. Consequently, feed manufacturers must navigate a complex landscape of compliance, balancing formulation efficacy with evolving legal requirements for traceability and ingredient transparency.
Market Dynamics
The central dynamic in the animal feed market is the bifurcation between high-volume, low-margin compound feed and high-margin, science-intensive functional additives. This split is driven by global regulatory clampdowns on antibiotic use and consumer demand for sustainably sourced animal protein.
Growth Catalysts
- Regulatory Mandates:The European Union's prohibition on antibiotic growth promoters creates sustained demand for alternative feed additives, such as probiotics and organic acids, to maintain animal health and productivity in intensive farming systems.
- Aquaculture Expansion:Rapid growth in the aquaculture sector, particularly for shrimp and tilapia farming in Southeast Asian countries, requires specialized aquafeed formulations that support high-density production and disease resistance.
- Precision Nutrition:The adoption of precision feeding technologies in large-scale swine and poultry operations improves feed conversion ratios, reduces waste, and lowers overall production costs, justifying investment in more sophisticated feed products.
Market Restraints
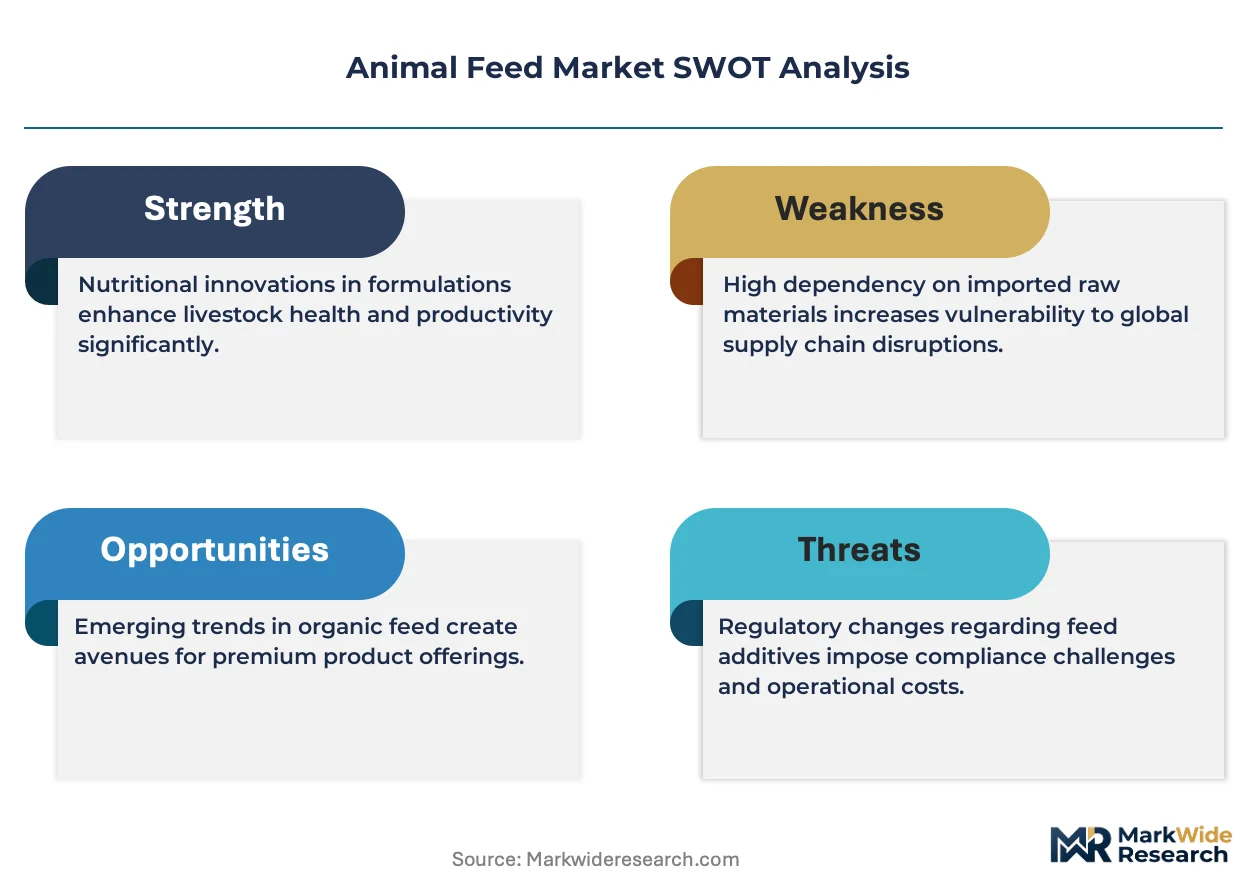
- Input Cost Volatility:The market's profitability is highly sensitive to price fluctuations in core agricultural commodities like corn and soybean meal, which can erode margins for feed manufacturers without effective hedging strategies.
- Supply Chain Bottlenecks:A high concentration of production for essential amino acids and vitamins in China creates significant supply chain vulnerability, exposing global feed producers to geopolitical risks and shipping disruptions.
- Additive Approval Delays:The rigorous, multi-year approval process for novel feed additives by regulatory bodies like the FDA and EFSA creates a significant barrier to entry and slows down the commercialization of innovative products.
Strategic Opportunities
- Alternative Proteins:Developing and scaling up the production of insect-based proteins and single-cell proteins offers a sustainable, high-value alternative to conventional fishmeal and soy, addressing both cost and environmental concerns.
- Digital Feed Management:The creation of software platforms that integrate with on-farm sensors allows for real-time optimization of feed rations based on animal performance data, creating a new service-based revenue stream.
- African Market Development:As livestock farming in Sub-Saharan Africa transitions from subsistence to commercial models, there is a significant opportunity to introduce compound feed and basic functional additives to an underpenetrated market.
Industry Challenges
- Traceability and Compliance:Ensuring and documenting full traceability of all ingredients from source to finished feed is a major operational challenge, particularly for companies operating with complex global supply chains.
- Capital-Intensive Modernization:Upgrading or building new feed mills to meet modern standards for biosecurity, precision mixing, and pelleting quality requires substantial capital investment that can be a barrier for smaller producers.
- Nutritional Expertise Gap:A shortage of highly trained animal nutritionists capable of formulating complex diets with novel additives limits the ability of some manufacturers to compete in the value-added segment of the market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Market |
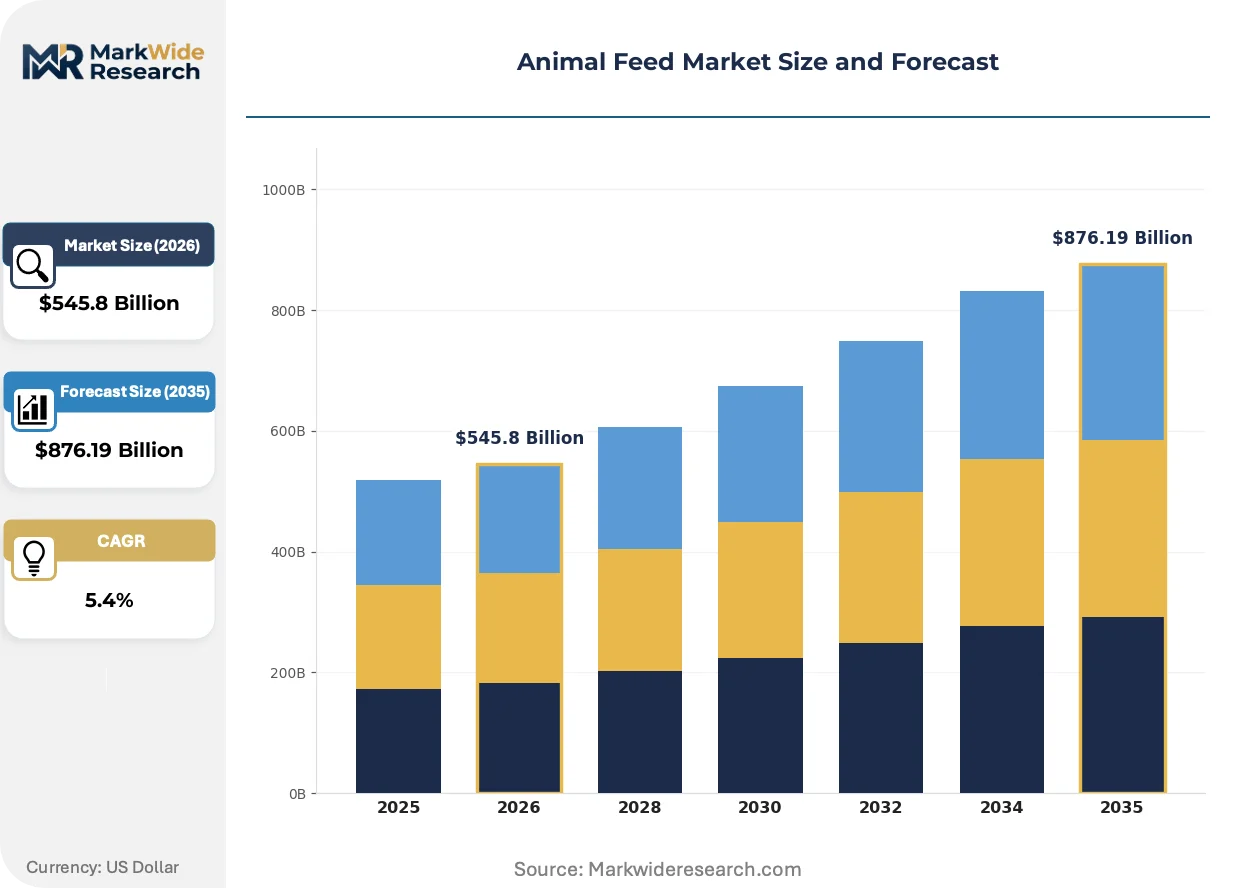
| Market Size in 2026 | $545.8 Billion |
| Market Size in 2035 | $876.19 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Compound Feed, Forage, Concentrates, Additives, Premixes Animal Type: Cattle, Poultry, Swine, Aquaculture, Equine, Pet Animals Formulation Type: Pellets, Mash, Crumble, Liquid, Extruded Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesalers, Cooperatives |
| Companies Covered | Archer Daniels Midland, New Hope Group, Cargill, Muyuan Foodstuff, Haid Group, Land O'Lakes, Tyson Foods, Wayne-Sanderson Farms, CHS Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Market Strategic Shifts & Innovations
Data-driven nutritional science is reshaping the animal feed industry's competitive landscape. The focus is shifting from simply delivering bulk calories to providing targeted health and performance solutions, driven by sustainability goals and food safety regulations.
Functional feed additives, including probiotics, prebiotics, and enzymes, are designed to enhance gut health and immune function. Large-scale swine and poultry producers are rapidly adopting these ingredients to maintain performance in antibiotic-free systems. This development is modularizing feed formulation, enabling nutritionists to assemble specific health and performance packages independent of the base energy and protein mix.
Regulatory frameworks like the US FDA's Veterinary Feed Directive (VFD) strictly control the use of medically important antimicrobials in livestock feed. This policy is forcing a fundamental shift in animal health management, moving producers toward prevention-focused strategies. The poultry and swine sectors are most affected, accelerating investment in biosecurity and non-medicated feed solutions to compensate for the removal of antibiotics.
Downstream food companies and retailers are increasingly setting private standards for animal welfare and antibiotic usage that exceed government regulations. This behavior disrupts the traditional B2B relationship between feed mills and farmers by making the food brand a key specifier of feed content. This trend is most prominent in North American and European markets where consumer awareness and brand accountability are highest.
Animal Feed Market Segmentation
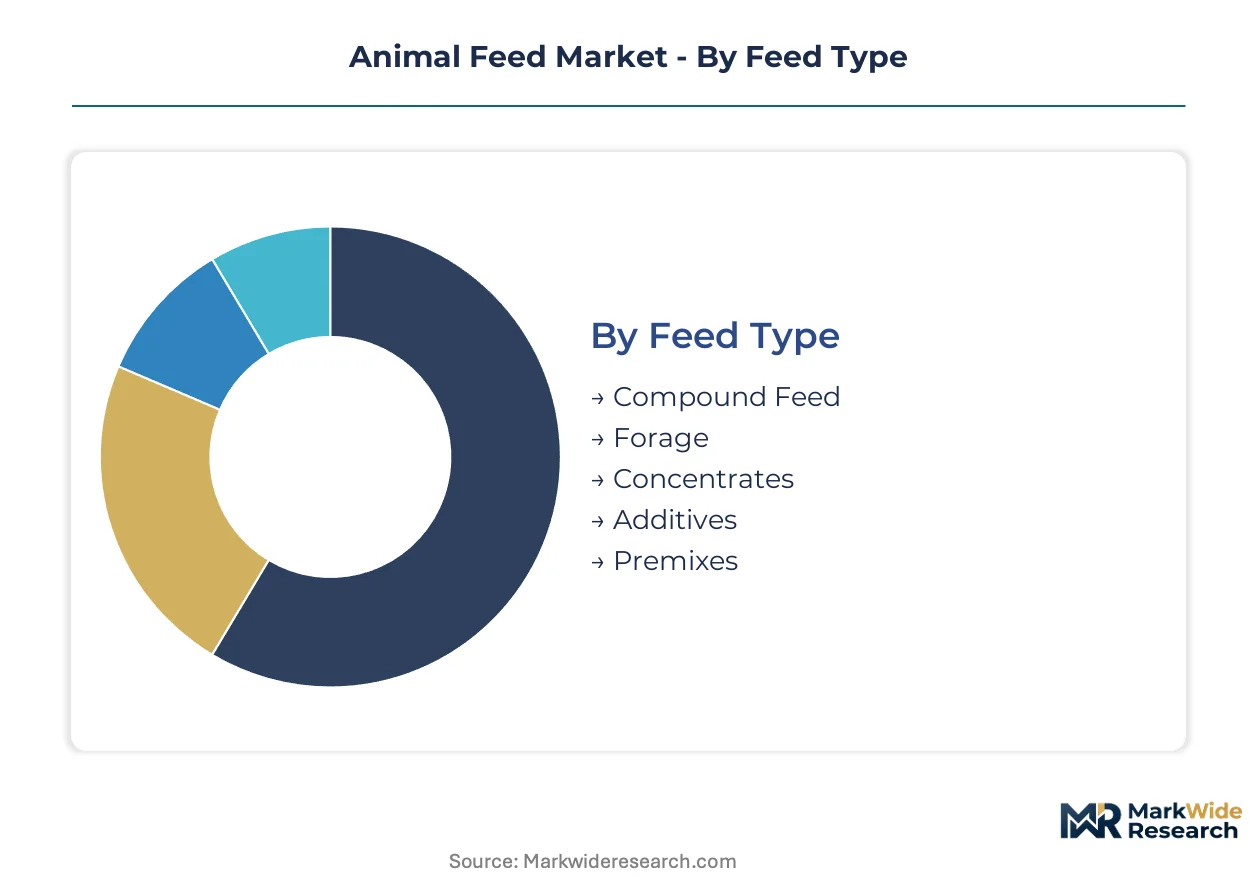
Understanding the segmentation of the animal feed market is critical for identifying specific demand pockets and strategic investment areas. Each category reflects distinct production methodologies, animal nutritional requirements, and distribution dynamics, influencing product development and market access strategies.
Feed Type:
Buyer differentiation in this category centers on the level of nutritional completeness and functional benefits sought for animal health and performance.
- Compound Feed:These are complete, scientifically formulated nutritional products containing a balanced mix of macronutrients and micronutrients, designed to meet the full dietary needs of specific animal species. Demand concentrates in large-scale swine and poultry operations across China and the United States, driven by the need for consistent growth and feed conversion efficiency.
- Additives:Functional ingredients such as probiotics, enzymes, amino acids, and organic acids are incorporated into feed to enhance digestion, improve gut health, or replace antibiotics. Demand is particularly high in the European Union and for aquaculture in Southeast Asia, propelled by stricter regulations on antimicrobial use and the pursuit of disease resistance.
- Forage:This segment includes bulk fibrous plant material like hay, silage, and pasture, primarily consumed by ruminants such as cattle and sheep.
- Concentrates:Nutrient-dense feed ingredients, typically high in protein or energy, are mixed with forage to supplement an animal's diet.
- Premixes:These are concentrated blends of micronutrients, including vitamins, minerals, and trace elements, designed to be added to larger feed batches.
Volume sits with Compound Feed; growth tilts toward Additives.
Animal Type:
The specific nutritional requirements and production goals for different animal species dictate product formulations and market focus within this category.
- Poultry:Feed formulations for chickens, turkeys, and other fowl focus on rapid growth, egg production, and feed conversion efficiency in intensive farming systems. Demand is substantial in China and the United States, driven by high consumer protein demand and large-scale commercial operations.
- Aquaculture:Specialized aquafeed supports the growth and health of fish, shrimp, and other aquatic species, often formulated for water stability and disease resistance in high-density environments. Rapid expansion of shrimp and tilapia farming in Southeast Asian countries drives significant demand for these tailored products.
- Cattle:This segment includes feed for beef and dairy cattle, focusing on growth, milk production, and reproductive health.
- Swine:Feed for pigs targets efficient weight gain, reproductive performance, and overall health in commercial pig farming.
- Equine:Specialized feed for horses addresses their unique digestive systems and energy requirements based on activity levels.
- Pet Animals:Formulations for companion animals like dogs and cats prioritize balanced nutrition, palatability, and specific health benefits.
Profitability within this category varies significantly based on production scale and regulatory demands.
Formulation Type:
The physical form of animal feed directly impacts handling, storage, nutrient delivery, and animal consumption efficiency.
- Pellets:These are compact, cylindrical forms of feed created by compressing mash, offering uniform nutrient distribution and reduced waste. Large-scale poultry and swine operations widely adopt pellets in the United States and Brazil, ensuring consistent intake and improved digestibility.
- Extruded:Produced by processing ingredients under high heat and pressure, extruded feeds are often buoyant and highly digestible, particularly critical for aquatic species. Aquaculture in Vietnam and pet food manufacturers in Germany extensively use extruded formulations for their stability and nutrient absorption properties.
- Mash:This is a finely ground mixture of feed ingredients, the simplest form to produce, often used for poultry and swine.
- Crumble:Mash feed that has been pelleted and then broken into smaller, coarse particles, suitable for young birds or animals.
- Liquid:Liquid feed supplements, often containing molasses or other liquid ingredients, are used to enhance palatability or deliver specific nutrients.
Efficiency and consistency drive adoption in this category.
Distribution Channel:
Market access for animal feed is shaped by the scale of farming operations, geographic reach, and the need for specialized services.
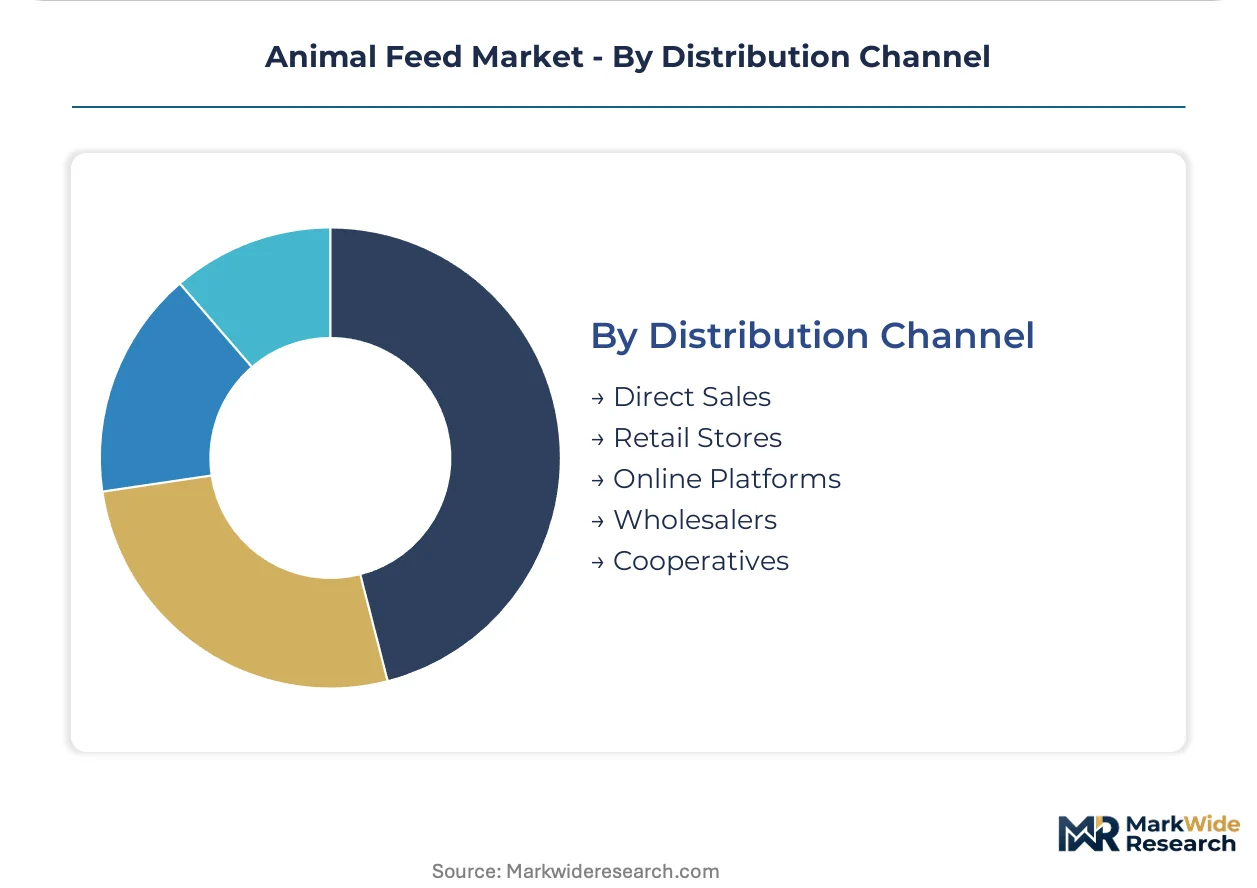
- Direct Sales:Manufacturers sell directly to large commercial farms, integrated livestock operations, or corporate accounts, bypassing intermediaries. This channel is prevalent among major feed producers in China and the Netherlands, allowing for customized solutions and direct technical support.
- Wholesalers:These intermediaries purchase feed in bulk from manufacturers and distribute it to smaller retailers, local cooperatives, or individual farmers. Wholesalers play a vital role in reaching fragmented agricultural markets in India and parts of Africa, providing logistical efficiency.
- Retail Stores:Pet supply stores, agricultural co-ops, and general retail outlets serve smaller farmers and pet owners.
- Online Platforms:E-commerce channels provide convenience for purchasing specialized or smaller quantities of feed, expanding reach for niche products.
- Cooperatives:Farmer-owned organizations collectively purchase feed, leveraging bulk buying power and providing local distribution points.
Channel selection reflects customer scale and geographic reach requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's extensive port infrastructure facilitates massive grain imports, underpinning China's position as the world's largest animal feed producer and consumer. This concentration supports large-scale swine and poultry operations, driving significant demand for compound feed. Regulatory shifts globally influence product development and market access across various regions.
China
Demand for compound feed in China is substantial, driven by immense swine and poultry production systems. The government's dual carbon goals influence sustainable ingredient sourcing and feed formulation practices. Extensive feed mills and livestock farms in the Pearl River Delta region integrate feed production with farming operations.
United States
High consumer protein demand and large-scale commercial operations drive significant feed consumption in the United States. The FDA enforces strict controls on medicated feeds, compelling a shift towards non-antibiotic additives. The Midwest, with its vast corn and soybean production, anchors numerous feed mills and livestock farms.
Germany
Germany's animal feed sector responds to stringent animal welfare standards and consumer demand for antibiotic-free animal products. The European Food Safety Authority (EFSA) sets rigorous standards for feed additives, influencing product innovation. North Rhine-Westphalia hosts numerous feed additive manufacturers and advanced research facilities for precision nutrition.
Brazil
Brazil's animal feed demand stems from its massive beef, poultry, and swine production, much of which is for export markets. The Ministry of Agriculture, Livestock, and Food Supply (MAPA) regulates feed quality and safety standards. The state of Mato Grosso, a key agricultural region, supports extensive feed mills catering to large-scale livestock operations.
Vietnam
Rapid growth in aquaculture, especially shrimp and tilapia farming, drives significant specialized aquafeed demand in Vietnam. The Ministry of Agriculture and Rural Development (MARD) oversees aquafeed quality and safety regulations. The Mekong Delta region serves as a central hub for aquafeed manufacturing and intensive aquaculture production.
Animal Feed Market Key Industry Players
Premium-margin players sit above commodity-margin players across the animal feed market, reflecting a fundamental bifurcation in product offerings and strategic focus. The industry encompasses both highly integrated global giants and specialized regional manufacturers, creating distinct competitive arenas. Strategic archetypes include diversified agri-food conglomerates, dedicated feed additive innovators, and regionally focused compound feed producers. Geographic expansion and portfolio diversification represent dominant competitive moves among larger entities seeking to capture market share.
At the scale-driven end of the market, Archer Daniels Midland and Cargill, Inc., exemplify large-scale agri-food conglomerates leveraging extensive global logistics and grain sourcing networks. These US-based entities occupy positions across both commodity feed and specialty ingredients. New Hope Group, a Chinese-based conglomerate, anchors a significant position as a vertically integrated player within the vast Chinese market, combining feed production with extensive livestock farming operations. These companies represent the trend towards consolidating supply chains and expanding geographic reach through their established operational footprints and diversified portfolios.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| New Hope Group |
| Cargill |
| Muyuan Foodstuff |
| Haid Group |
| Land O'Lakes |
| Tyson Foods |
| Wayne-Sanderson Farms |
| CHS Inc. |
| Others |
Cost & Logistics Intelligence
The bifurcation between high-margin functional additives and low-margin bulk compound feed dictates distinct pricing strategies and supply chain configurations. This split reflects varying input complexities and market demand pressures.
Pricing Analysis
Outcome-based pricing anchors the functional additives segment, where efficacy in gut health or feed conversion drives value. Price differentiation stems from proven performance data, certification levels, and volume scale, with specialized formulations commanding premiums. Pricing pressure impacts the high-volume compound feed segment due to volatile commodity input costs. Large-scale commercial farms purchasing bulk compound feed exhibit high price sensitivity, while specialized aquaculture producers prioritize performance for tailored aquafeed.
Supply Chain Analysis
Single-source vulnerability sits with China for essential amino acids and vitamins, creating significant global supply chain exposure. The market depends on core agricultural commodities like corn and soybean meal, primarily sourced from the United States and Brazil. Geopolitical risks and shipping disruptions pose structural risks to ingredient availability and cost stability. Distribution runs through direct sales to large commercial farms and wholesalers serving fragmented agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The animal feed market is a vertical-integration race, with established players pursuing upstream control over grain sourcing and processing. This strategy aims to secure input stability, optimize operational costs, and manage quality consistently.
For Market Incumbents: Extend specialized additive portfolios to address evolving regulatory mandates, particularly in antibiotic-free production systems. Invest in advanced biosecurity solutions and digital feed management platforms to counter margin pressure from input cost volatility. Diversify raw material sourcing beyond traditional commodities to mitigate geopolitical risks. Consolidate market share through strategic acquisitions of regional additive manufacturers or technology providers.
For New Entrants and Emerging Players: Small to medium-sized commercial farms in Sub-Saharan Africa represent an underserved buyer archetype for basic functional additives. Target niche aquaculture species requiring specialized, disease-resistant feed formulations in Southeast Asia. Develop sustainable alternative protein ingredients for premium markets with strong environmental mandates. Partner with regional distributors to offer localized technical support and precise formulation expertise.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized feed additive innovators given the global shift towards antibiotic-free animal production. Focus on companies developing alternative proteins like insect-based meals or single-cell proteins for sustainable sourcing. Monitor regulatory approvals from the FDA and EFSA for novel, performance-enhancing additives. Invest in digital feed management platforms offering data-driven nutritional optimization to improve efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Alternative Proteins | Addresses sustainability concerns and reduces reliance on conventional feed ingredients. |
| Investment in Precision Nutrition Software | Optimizes feed conversion ratios and minimizes waste for large-scale operations. |
| Strategic Partnerships for Biosecurity Solutions | Enhances animal health and productivity in antibiotic-free farming systems. |
| Geographic Expansion into African Markets | Captures demand from transitioning subsistence to commercial livestock farming. |
| R&D for Novel Functional Additives | Develops high-margin products that comply with evolving food safety regulations. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic research underwrites the qualitative findings. Primary interviews with animal nutritionists, feed mill operators, livestock producers, and regulatory experts informed market dynamics. Secondary validation drew from FDA and EFSA publications, alongside trade association data. This approach ensured robust bottom-up and top-down triangulation for comprehensive analysis.
The forecast window was anchored to comparable historical periods, establishing baseline market performance. The analytical framework integrated historical data trends with identified market drivers, restraints, and opportunities. Segmentation dimensions included feed type, animal type, formulation type, and distribution channel. Compound annual growth rates were derived through regression analysis and expert consensus, considering livestock population growth and regulatory policy shifts.
Revisions become necessary when unforeseen geopolitical events, major disease outbreaks, or significant shifts in global commodity prices materialize. Forecasts reflect underlying assumptions regarding regulatory stability and technological adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Pure Plant Oil Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
GCC Compound Feed Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
South Africa Compound Feed Market