
 Pure Plant Oil Market | 2026-2036
Pure Plant Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Pure Plant Oil Market Outlook
Specialty ingredient distribution channels are reshaping how pure plant oils reach cosmetics and pharmaceutical formulators. Bunge Limited leverages its global oilseed processing infrastructure to secure feedstock consistency across multiple geographies. Cargill competes through integrated supply chains that span crushing, refining, and customized lipid formulations for industrial buyers. Wilmar International anchors Asia-Pacific sourcing networks with deep origination ties to palm, coconut, and other tropical oil crops.
Pure plant oil denotes lipid extracts derived from botanical sources through mechanical pressing or solvent methods, typically retaining triglyceride compositions of C16-C18 fatty acids along with native phytosterols and tocopherols that confer oxidative stability and functional activity in topical and nutritional applications. Cold-Pressed Oils command premium positioning in cosmetics and nutraceutical channels where heat-sensitive bioactive retention justifies higher unit economics, while Essential Oils concentrate value in aromatherapy and personal care segments despite smaller volume throughput. Carrier Oils sustain broader industrial absorption across food processing and pharmaceutical excipient applications where cost efficiency and scale availability predominate over extraction method provenance.
EU REACH registration requirements govern chemical safety documentation for imported botanical extracts, while FDA oversight through GRAS determinations and cosmetic ingredient reviews shapes US market access protocols for novel oil sources. EFSA Novel Food regulations create pre-market authorization hurdles for emerging plant species entering European food applications, effectively filtering supplier pipelines. Stakeholders must monitor evolving EU Deforestation Regulation traceability mandates and California Proposition 65 litigation trends as these frameworks increasingly dictate sourcing geography decisions and compliance cost structures.
Market Dynamics
Cold-pressing technology advances and EU Deforestation Regulation traceability mandates are restructuring how botanical feedstocks move through cosmetics and nutraceutical supply chains, compressing supplier margins while rewarding vertically integrated processors.
Growth Catalysts
- EU REACH compliance:Chemical safety documentation requirements for imported botanical extracts filter out non-compliant suppliers, concentrating market share among registered processors with established regulatory infrastructure.
- Cosmetics formulators:Natural ingredient mandates from major beauty brands drive cold-pressed oil procurement for heat-sensitive bioactive retention in premium skincare lines.
- German pharmaceutical cluster:Excipient-grade carrier oil demand from Mannheim-Ludwigshafen manufacturing corridors anchors industrial volume absorption for refined triglyceride formulations.
Market Restraints
- Input cost volatility:Palm kernel and coconut oil feedstock prices fluctuate with Southeast Asian weather patterns, squeezing crush margins for European refiners dependent on tropical origination.
- Supply concentration risk:Indonesia and Malaysia control over 80 percent of global palm oil output, creating single-origination vulnerability for lauric acid-dependent formulations.
- Substitution threat:Synthetic squalane and fermented lipid alternatives displace olive-derived squalene in mid-tier cosmetic applications where provenance premiums do not apply.
Strategic Opportunities
- Underpenetrated geography:Poland and Romania present white-space potential for cold-pressed specialty oils as regional cosmetics manufacturing expands beyond established German and French hubs.
- Regulatory tailwind:EU Green Deal bioeconomy incentives favor domestic oilseed cultivation, creating origination subsidies for sunflower and rapeseed processors within the trading bloc.
- Technology convergence:Near-infrared spectroscopy and blockchain traceability platforms hybridize to provide real-time fatty acid profiling and chain-of-custody verification for deforestation-compliant supply chains.
Industry Challenges
- Certification timeline compression:EFSA Novel Food authorization processes stretch 18-24 months for emerging botanical species, delaying commercialization of novel oil sources with functional claims.
- Talent scarcity in lipid analytics:Specialized chromatography and oxidative stability testing expertise concentrates among retiring generation chemists, constraining quality control scaling for mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pure Plant Oil Market |
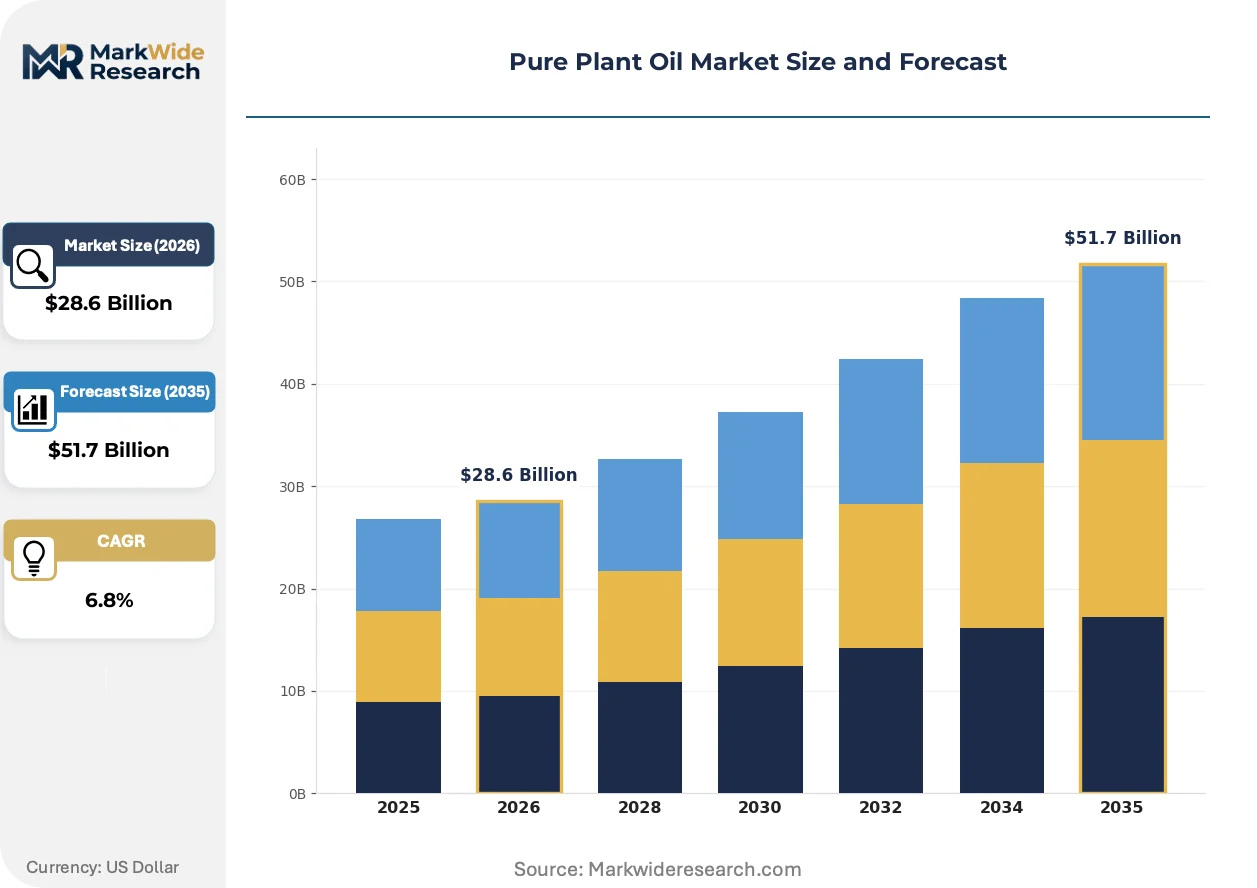
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Carrier Oils, Cold-Pressed Oils, Extracts End Use Industry: Cosmetics, Food & Beverage, Pharmaceuticals, Aromatherapy Extraction Method: Steam Distillation, Solvent Extraction, Cold Pressing, CO2 Extraction Packaging Type: Glass Bottles, Plastic Containers, Aluminum Cans, Drums |
| Companies Covered | Bunge Limited, Oils and Fats International, Cargill, COFCO Group, Kerry Group, Archer Daniels Midland, BASF, Louis Dreyfus Company, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pure Plant Oil Market Strategic Shifts
Mechanical extraction methods are converging with digital quality assurance systems to redefine how botanical lipids retain bioactive integrity through processing, while regulatory traceability mandates force supply chain transparency investments.
Supercritical CO2 extraction is hybridizing with traditional cold-pressing protocols to capture heat-sensitive phytosterols and tocopherols that degrade under conventional thermal desolventization. Cosmetics laboratories in France and Switzerland adopt these hybrid systems at pilot scale, seeking to bridge the yield gap between artisanal pressing and industrial solvent extraction. The technology is hybridizing unit economics across premium and mid-tier product tiers, enabling processors to command cold-pressed premiums while achieving solvent-grade throughput volumes.
EU Deforestation Regulation geolocation and traceability requirements mandate satellite-verified farm polygon data for all palm, soy, and cattle-linked commodities entering European markets after December 2024. This policy compresses supplier qualification timelines and disqualifies smallholder-dependent origination networks lacking digital mapping infrastructure. Cosmetics and food-grade oil importers in Germany and the Netherlands face the steepest compliance ramps, accelerating third-party audit platform adoption.
Direct-procurement contracts between cosmetics formulators and crush facilities are displacing traditional multi-tier distribution through commodity brokers and regional traders. Specialty ingredient buyers in the United Kingdom and Scandinavia negotiate origin-specific fatty acid profiles and harvest-date documentation, unbundling quality assurance from volume aggregation. This pattern concentrates most visibly in jojoba and argan oil segments where single-origin provenance commands measurable formulation premiums.
Pure Plant Oil Market Segmentation
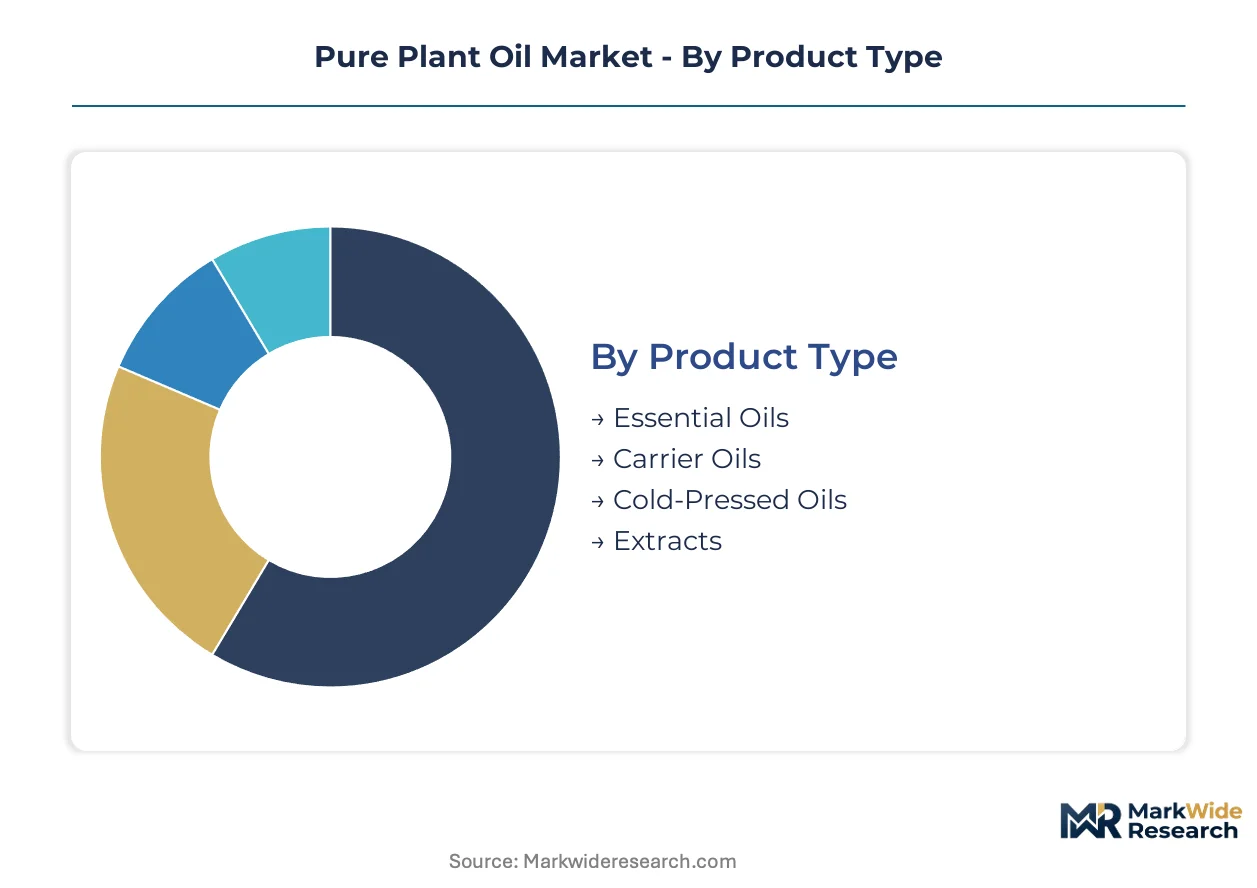
Segmentation in the pure plant oil market separates premium-positioned bioactive products from commodity-grade industrial inputs. Distinct extraction technologies, packaging formats, and end-use specifications create divergent margin structures and compliance requirements across each category.
Product Type:
Mature segments dominate volume flows while emerging formats capture formulation innovation premiums.
- Cold-Pressed Oils:Mechanical extraction at temperatures below 40°C preserves heat-sensitive tocopherols and phytosterols in triglyceride matrices. Cosmetics formulators in Germany and France pay provenance premiums for these oils in premium skincare lines where bioactive retention justifies unit economics.
- Essential Oils:Highly concentrated volatile compounds extracted through distillation or expression, containing terpenes and phenylpropanoids responsible for aromatic and functional properties. Aromatherapy applications in the United Kingdom and Scandinavian markets drive procurement, though smaller batch volumes constrain processor scale economies.
- Carrier Oils:Refined triglyceride bases dilute essential oils for topical application; pharmaceutical excipient demand from Mannheim-Ludwigshafen manufacturing corridors anchors industrial absorption.
- Extracts:Solvent-derived or supercritical fluid concentrates standardize active compound content for nutraceutical encapsulation and functional food fortification.
Carrier Oils handles the majority of throughput; Cold-Pressed Oils is the fastest mover on share.
End Use Industry:
Application concentration varies by margin tier, with premium personal care commanding price multiples over bulk food processing.
- Cosmetics:Natural ingredient mandates from major beauty brands drive cold-pressed procurement for sensitive-skin formulations and clean-label positioning. EU REACH documentation requirements filter supplier pools to registered processors with established regulatory infrastructure.
- Pharmaceuticals:Excipient-grade specifications demand oxidative stability testing and chromatographic purity verification that concentrates supply among certified refiners.
- Food & Beverage:EFSA Novel Food authorization creates 18-24 month commercialization delays for emerging botanical species entering European food applications.
- Aromatherapy:Wellness retail channels in the United Kingdom and Germany absorb lavender, tea tree, and eucalyptus oil volumes through direct-to-consumer and practitioner distribution.
Cosmetics generates the highest margin per liter; Pharmaceuticals is expanding most quickly on regulatory tailwinds for natural excipients.
Extraction Method:
Technology selection balances yield efficiency against bioactive preservation, with hybrid protocols emerging at pilot scale.
- Cold Pressing:Mechanical screw pressing without thermal desolventization retains native antioxidant profiles; cosmetics laboratories specify harvest-date documentation and origin-verified fatty acid profiles.
- CO2 Extraction:Supercritical fluid systems capture heat-sensitive phytosterols at solvent-grade throughput volumes; French and Swiss processors adopt these hybrid configurations to bridge artisanal and industrial economics.
- Steam Distillation:Thermal vapor separation dominates essential oil production for lavender, peppermint, and citrus derivatives where volatile compound recovery takes priority.
- Solvent Extraction:Hexane or ethanol methods maximize lipid yield for commodity food and feed applications where cost efficiency supersedes extraction method provenance.
Solvent Extraction handles the majority of throughput; CO2 Extraction is gaining share fastest on technology convergence with cold-pressing protocols.
Packaging Type:
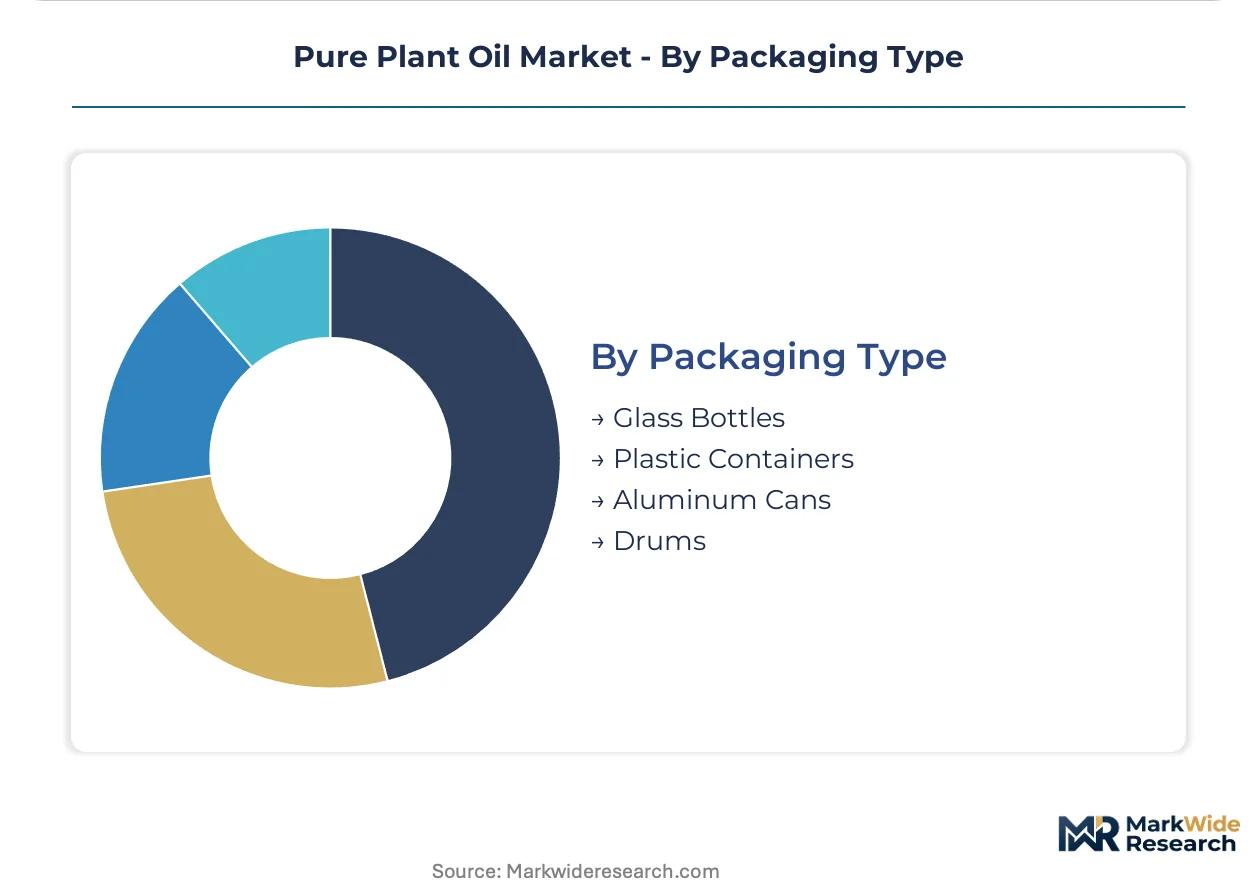
Material selection tracks shelf-life requirements, handling scale, and sustainability positioning across distribution channels.
- Glass Bottles:Amber and cobalt glass blocks UV degradation for retail cosmetic and aromatherapy channels; premium positioning justifies higher logistics costs versus flexible formats.
- Drums:Stainless steel and lined steel containers serve pharmaceutical and food manufacturing bulk procurement with integrated pumping and nitrogen blankling systems.
- Plastic Containers:HDPE and PET formats reduce unit costs for mid-tier food and personal care applications where oxygen barrier requirements permit polymer contact.
- Aluminum Cans:Lightweight, recyclable metal packaging gains traction in specialty food and beverage applications with sustainability-forward brand positioning.
Drums handles the majority of throughput; Glass Bottles is climbing the fastest on clean-label retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and French cosmetics corridors while Southeast Asian origination networks face margin compression from EU Deforestation Regulation compliance costs. This asymmetry reshapes procurement geography for cold-pressed specialty oils.
Germany
Mannheim-Ludwigshafen pharmaceutical clusters absorb refined carrier oils for excipient formulations, while Hamburg and Frankfurt cosmetics laboratories drive cold-pressed procurement premiums. ECHA REACH registration requirements filter supplier pools to established chemical documentation holders. Bavarian oilseed processors leverage EU Green Deal bioeconomy subsidies to expand domestic sunflower and rapeseed crushing capacity.
France
Grasse fragrance corridors and Parisian skincare formulators anchor essential oil and cold-pressed carrier demand for luxury cosmetic houses. ANSM cosmetic ingredient oversight aligns with EU REACH documentation mandates for botanical extract safety. Provence lavender distillers and Occitanie jojoba cooperatives supply traceable-origin feedstocks to L'Oréal and LVMH supply chains.
United Kingdom
London and Manchester wellness retail channels absorb aromatherapy oil volumes through direct-to-consumer and practitioner distribution networks. FSA novel food consultations create pre-market authorization pathways for emerging botanical species entering functional food applications. Somerset and Norfolk cold-press facilities serve Scandinavian export markets with organic-certified specialty oils.
Indonesia
Sumatra and Kalimantan palm oil estates face EU Deforestation Regulation geolocation mandates requiring satellite-verified farm polygon documentation by December 2024. Ministry of Agriculture traceability infrastructure investments seek to retain European cosmetics and food-grade market access. Smallholder-dependent origination networks without digital mapping capability face disqualification from German and Dutch importer supply chains.
United States
California clean beauty formulators and New Jersey pharmaceutical excipient manufacturers drive differentiated demand for GRAS-certified and cosmetic-grade botanical oils. FDA cosmetic ingredient reviews and California Proposition 65 litigation trends shape sourcing geography decisions for imported extracts. Oregon and Washington state hemp and specialty seed oil processors supply domestic natural products channels.
Pure Plant Oil Market Competitive Environment
Agribusiness conglomerates and specialty ingredient distributors split the market into upstream origination and downstream formulation service tiers. The structure concentrates crushing and refining capacity among oilseed processors with integrated supply chains spanning multiple geographies. Three archetypes dominate: tropical oil estate operators with origination control, North American and European traders with regulatory infrastructure, and Asia-Pacific integrated processors with deep feedstock ties. Competitive moves center on backward integration into plantation assets and blockchain traceability platform partnerships.
Among agribusiness conglomerates, Bunge Limited, Cargill, and Wilmar International exemplify the scale-driven archetype with multinational oilseed processing footprints. Bunge Limited anchors North and South American origination networks. Cargill occupies a position bridging commodity trading and customized lipid formulation services. Wilmar International sits within the Asia-Pacific integrated processor tier with established ties to Indonesian and Malaysian palm oil supply bases.
| Leading Market Players |
|---|
| Bunge Limited |
| Oils and Fats International |
| Cargill |
| COFCO Group |
| Kerry Group |
| Archer Daniels Midland |
| BASF |
| Louis Dreyfus Company |
| Wilmar International |
| Others |
Value Chain & Pricing Dynamics
Sumatra and Kalimantan palm oil estates anchor global lauric acid feedstock flows, with their crushing capacity concentration translating directly into pricing leverage for European refiners dependent on tropical origination networks.
Pricing Analysis
Customization-premium spreads separate cold-pressed specialty oils from commodity-grade refined triglycerides in cosmetics procurement. Three-tier pricing structure across premium, standard, and economy levels tracks extraction method provenance, with harvest-date documentation and origin-verified fatty acid profiles commanding measurable formulation premiums from German and French laboratories. Price erosion runs through mid-tier carrier oil segments as synthetic squalane alternatives displace olive-derived squalene. Pharmaceutical excipient buyers exhibit lowest price sensitivity due to chromatographic purity requirements, while food processing channels absorb volume at tightest margins.
Supply Chain Analysis
EU Deforestation Regulation geolocation mandates function as de facto export controls, restricting European market access for palm and soy-linked commodities lacking satellite-verified farm polygon documentation. Supply concentrates in Indonesia and Malaysia for tropical oils, with Germany and France anchoring downstream refining and formulation. Feedstock draws from palm kernel, coconut, and sunflower seed inputs. Single-origination vulnerability in lauric acid-dependent formulations creates structural risk exposure. Distribution runs through direct-procurement contracts between cosmetics formulators and crush facilities, displacing traditional multi-tier brokerage channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
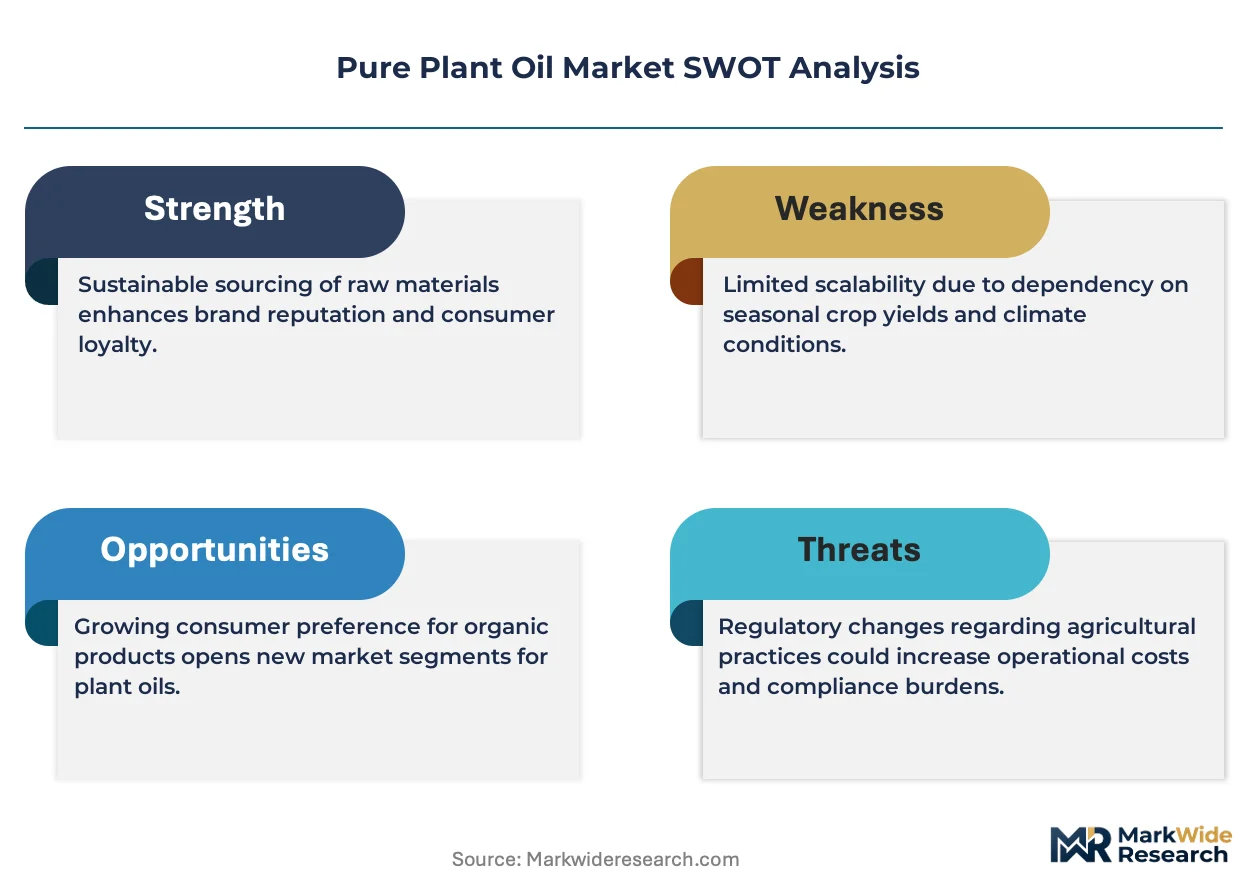
Synthetic lipid substitutes and fermented alternatives threaten displacement of botanical-derived ingredients, forcing incumbents to defend provenance premiums through traceability investments and bioactive retention certification.
For Market Incumbents: Pre-empt synthetic substitution by embedding blockchain traceability platforms into supply chain infrastructure, securing deforestation-compliant origination networks before December 2024 EUDR enforcement locks in supplier qualification timelines. Backward integration into plantation assets in Indonesia and Malaysia reduces feedstock volatility exposure. Cold-pressing technology R&D preserves bioactive differentiation against solvent-grade competitors. For New Entrants and Emerging Players: Establish a beachhead in Poland and Romania cold-pressed specialty oil segments, where regional cosmetics manufacturing expansion outpaces established German and French supplier coverage. White-space potential concentrates in organic-certified sunflower and rapeseed channels serving Scandinavian export markets. Go-to-market leverage rests on EU Green Deal bioeconomy subsidy capture for domestic oilseed cultivation. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core specialty ingredient divisions, particularly Asia-Pacific integrated processors with deep palm oil ties seeking portfolio simplification. Five-to-ten year viability hinges on regulatory compliance infrastructure amortization. Signal to monitor: EFSA Novel Food authorization timeline compression for emerging botanical species, indicating pipeline velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive supply of EUDR-compliant palm kernel feedstock secures European cosmetics channel access. |
| Blockchain Traceability Platform Partnership | Real-time geolocation verification satisfies German and Dutch importer qualification requirements. |
| Cold-Pressing Technology Scale-Up | Hybrid supercritical CO2 systems bridge artisanal yield gaps for French and Swiss cosmetics laboratories. |
| EFSA Novel Food Authorization Investment | Pre-market clearance for emerging botanical species unlocks functional food fortification channels. |
| Direct-Procurement Contract Expansion | Unbundled quality assurance from volume aggregation concentrates margin capture with UK formulators. |
Study Parameters
Operator-level perspectives from crushing facility managers, cosmetics formulator procurement leads, pharmaceutical excipient quality directors, and specialty oil distribution channel partners anchored the qualitative base. Secondary validation drew from ECHA REACH registration databases, EU Deforestation Regulation implementation guidance, EFSA Novel Food authorization records, and customs trade flow documentation. Bottom-up volume triangulation across extraction method, end-use industry, and packaging format segments converged with top-down macroeconomic anchoring.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, extraction technology, end-use application, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to baseline volume estimates, incorporating input cost volatility assumptions for palm kernel and coconut oil feedstocks. Cold-pressing adoption curves and EUDR compliance cost pass-through rates served as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in energy costs, currency exchange rates, or Southeast Asian weather patterns would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology adoption rates. Material shifts in EUDR implementation scope or synthetic lipid substitution velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Compound Horse Feedstuff Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Cut Flower Market