
 Global Medicated Feed Market | 2026-2036
Global Medicated Feed Market Size, Share, and Industry Trends Forecast 2026-2036
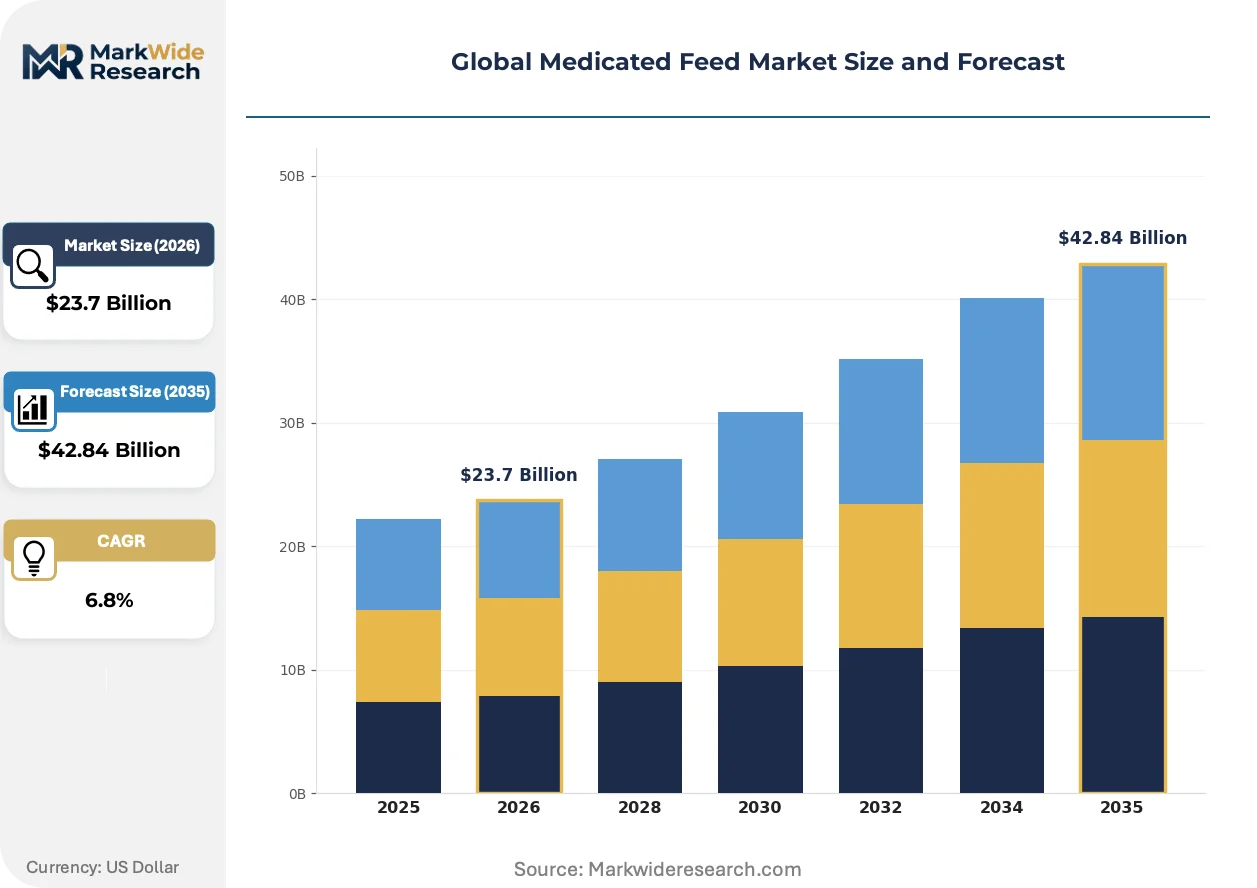
Global Medicated Feed Market Outlook
A widening capital-intensity divergence between integrated feed compounders and standalone additive suppliers is rotating competitive advantage toward in-house milling and formulation infrastructure. Cargill, Incorporated leverages its grain origination networks to control input costs across multiple continents. Zoetis anchors its position through veterinary pharmaceutical expertise that extends into medicated feed partnerships. Alltech differentiates via yeast-based additive platforms that reduce reliance on conventional antibiotics.
Medicated feed comprises nutritionally complete rations containing pharmacologically active substances administered to food-producing and companion animals for disease prevention, treatment, or growth promotion, typically formulated at concentrations between 10 and 500 grams per ton depending on the active ingredient and target species. Antibiotic segments face structural pressure from regulatory restrictions in Europe and North America, while antiparasitic premixes sustain stronger margin pools in ruminant and aquaculture applications. Poultry remains the dominant animal type by volume, though aquaculture formulation demand is accelerating fastest as shrimp and salmon producers intensify health management protocols.
The FDA's Veterinary Feed Directive governs antibiotic use in US livestock, while the EMA and national regulators across Germany, France, and the Netherlands enforce the EU's ban on antibiotic growth promoters through residue monitoring and farm audits. China's NMPA and Ministry of Agriculture are tightening import registration requirements for medicated premixes, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving antimicrobial resistance policies and pivot formulation portfolios before regulatory deadlines eliminate legacy product categories.
Market Dynamics
The European Union's Veterinary Medicines Regulation is forcing a wholesale reformulation of active ingredient portfolios as antibiotic growth promoters face systematic phase-out across member states.
Growth Catalysts
- Preventive Health Protocols:Intensive shrimp farming in Vietnam and Indonesia is accelerating demand for antiparasitic premixes as stocking densities rise in coastal aquaculture zones.
- EMA Regulatory Clarity:Streamlined centralized marketing authorization pathways for reduced-antibiotic formulations are shortening product launch timelines for qualified applicants.
- Phytogenic Additive Platforms:Essential oil and botanical extract formulations are gaining traction as direct replacements for conventional antimicrobials in poultry starter feeds.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for tetracycline and macrolide classes remains concentrated among Chinese manufacturers, exposing formulators to export license volatility.
- Cross-Contamination Controls:Dedicated production lines for non-medicated feed sequences require capital outlays that smaller compounders cannot absorb without facility consolidation.
- Residue Testing Costs:Mandatory withdrawal period verification and tissue residue monitoring under FDA Veterinary Feed Directive protocols add per-ton compliance burdens that compress margin pools.
Strategic Opportunities
- Precision Delivery Systems:Microencapsulation technologies enabling targeted release in ruminant rumen environments are opening premium pricing tiers for dairy nutrition programs.
- Brazilian Integration Wave:Vertically integrated poultry processors in Paraná and Santa Catarina states are internalizing premix formulation capabilities, creating partnership openings for technology licensors.
- Digital Prescription Platforms:Veterinary telemedicine integration with feed mill ordering systems is streamlining compliance documentation for antibiotic-containing rations in North American operations.
Industry Challenges
- Formulation Talent Scarcity:Veterinary pharmacologists with dual expertise in feed manufacturing and regulatory submission writing command compensation premiums that mid-tier compounders struggle to match.
- Legacy Equipment Retrofit:Existing pelleting and coating infrastructure often lacks the temperature control precision required for heat-sensitive probiotic and enzyme additive incorporation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medicated Feed Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiparasitics, Antifungals, Vitamins Animal Type: Poultry, Swine, Aquaculture, Ruminants Formulation: Premix, Liquid, Medicated Feed Blocks, Granules Distribution Channel: Online, Offline, Retail, Direct Sales |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Phibro Animal Health Corporation, Elanco Animal Health Incorporated, Adisseo, Kemin Industries, Zoetis, Nutreco, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medicated Feed Market Strategic Shifts
Active ingredient delivery mechanisms and regulatory compliance architectures are diverging sharply between antibiotic-dependent legacy portfolios and next-generation functional feed additive platforms.
Postbiotic fermentation metabolites are decomposing the traditional binary split between nutritional and pharmaceutical feed categories. Salmon producers in Norway are adopting these formulations at commercial scale to reduce reliance on bath treatments for sea lice management. The technology is decomposing established veterinary-pharmaceutical distribution channels by positioning functional additives as nutrition products rather than regulated drugs.
REACH authorization requirements for zinc oxide and copper sulfate usage in piglet feeds are compelling European formulators to seek alternative growth-promoting mechanisms before 2025 deadline enforcement. The industrial consequence is a surge in organic acid and medium-chain fatty acid blend development targeting gastric pH modulation. Weaner pig operations in Denmark and the Netherlands are most affected, with several integrated producers already completing full zinc-free diet transitions.
Direct contracting between protein processors and feed additive suppliers is compressing traditional distribution layers that previously managed technical sales and regulatory documentation. Large poultry integrators in Thailand and Mexico are building in-house veterinary advisory functions that bypass external nutrition consultants. This pattern is most visible in Southeast Asian markets where vertical coordination between hatcheries and slaughter facilities has advanced furthest.
Global Medicated Feed Market Segmentation
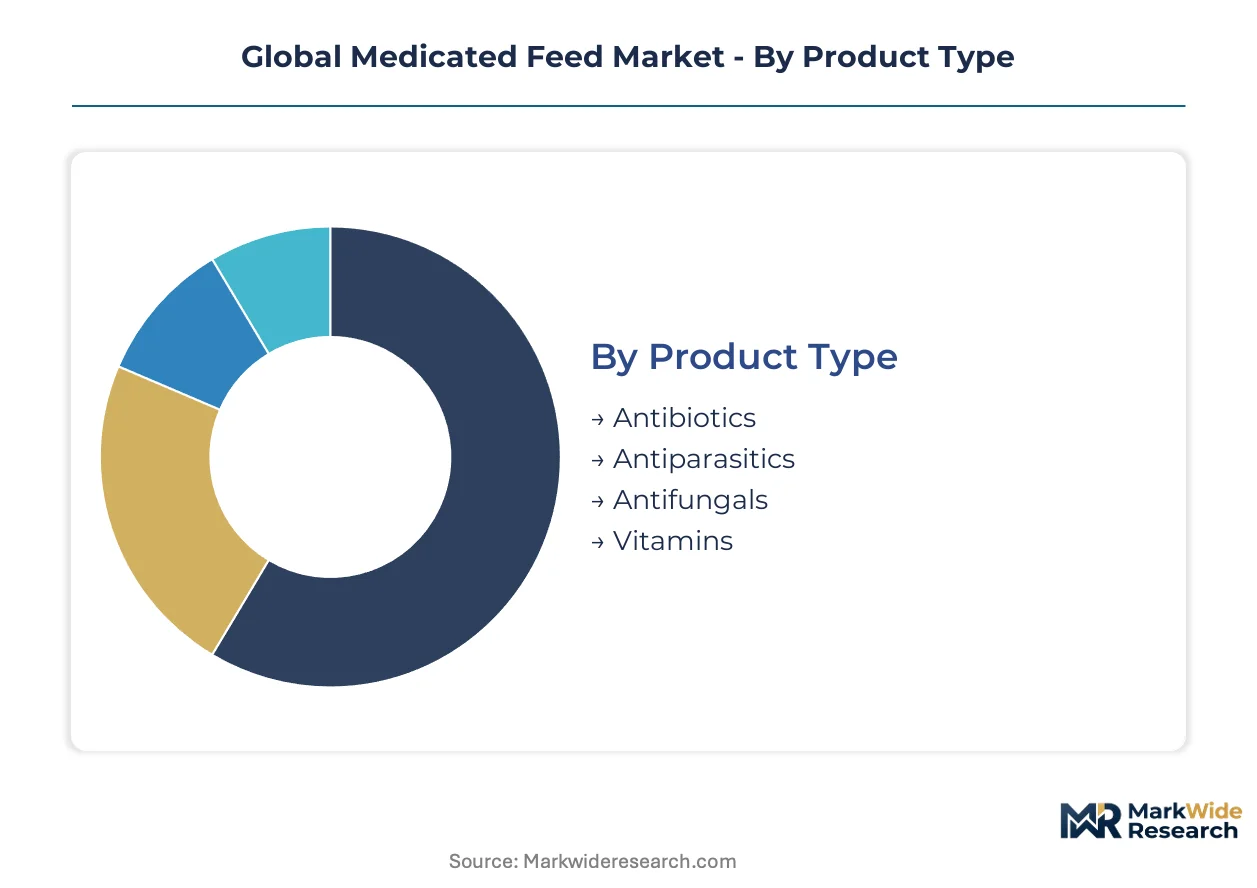
Medicated feed segmentation reflects divergent regulatory pathways across active ingredient classes and the operational requirements of intensive livestock systems. Formulation choices and distribution channels are reshaping as compliance burdens intensify and producer scale concentrates procurement authority.
Product Type:
EMA's phased ban on antibiotic growth promoters and FDA Veterinary Feed Directive documentation requirements are fragmenting competitive advantage across pharmacological categories.
- Antibiotics:Tetracycline and macrolide formulations face systematic phase-out across EU member states under Veterinary Medicines Regulation timelines. Danish and Dutch piglet producers have accelerated zinc-free diet transitions ahead of REACH enforcement deadlines, compressing legacy product margin pools.
- Antiparasitics:Benzimidazole and macrocyclic lactone premixes sustain stronger pricing power in ruminant and aquaculture applications where regulatory pressure remains less severe. Vietnamese shrimp farming operations are scaling antiparasitic programs as coastal stocking densities intensify disease pressure.
- Antifungals:Nystatin and amphotericin B formulations target mycotoxin mitigation in humid tropical storage conditions.
- Vitamins:Stabilized fat-soluble vitamin premixes support immune function as antibiotic alternatives in poultry starter feeds.
Established volume favors antibiotics; emerging adoption favors antiparasitics.
Animal Type:
Species-specific physiology and production intensity determine formulation complexity and active ingredient concentration requirements.
- Poultry:Broiler and layer operations in Brazil's Paraná and Santa Catarina states consume the largest premix volumes globally, with integrated processors internalizing formulation capabilities to manage coccidiosis pressure in high-density houses.
- Swine:Weaner pig operations in Denmark and the Netherlands are completing full zinc-free diet transitions, driving demand for organic acid and medium-chain fatty acid alternatives to gastric pH modulation.
- Aquaculture:Norwegian salmon producers are adopting postbiotic fermentation metabolites at commercial scale to reduce sea lice bath treatment dependency.
- Ruminants:Dairy nutrition programs in Germany and France are testing microencapsulated precision delivery systems for rumen-protected active release.
Volume leadership sits with poultry; steepest expansion trajectory belongs to aquaculture.
Formulation:
Physical form factor determines manufacturing capital requirements, stability profiles, and on-farm administration labor intensity.
- Premix:Concentrated carrier-based formulations at 0.5-2% inclusion rates dominate commercial feed mill operations, requiring dedicated production lines to prevent cross-contamination with non-medicated sequences.
- Liquid:Water-soluble concentrates enable precise dosing in automated drinking systems for swine and poultry operations with advanced infrastructure.
- Medicated Feed Blocks:Molasses-based compressed formulations support pasture-based ruminant supplementation with extended intake duration.
- Granules:Coated particle technologies improve heat stability during pelleting processes for temperature-sensitive probiotic incorporation.
Operational scale favors premix; infrastructure flexibility favors liquid.
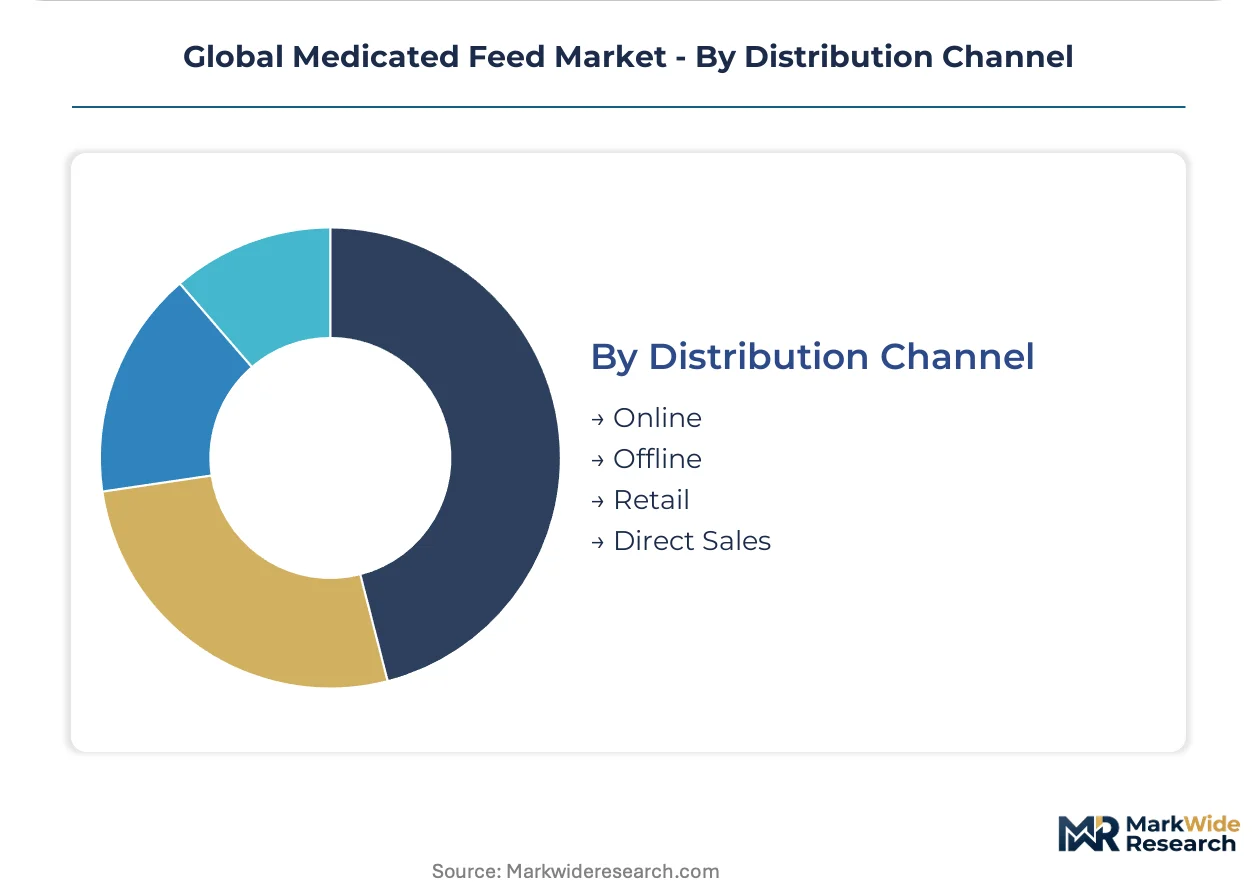
Distribution Channel:
Procurement authority is shifting from independent nutrition consultants toward vertically integrated protein processors with captive veterinary advisory functions.
- Online:Veterinary telemedicine platforms integrated with feed mill ordering systems are streamlining FDA compliance documentation for antibiotic-containing rations in US operations.
- Offline:Traditional technical sales relationships persist in mid-tier compounder segments where formulation expertise remains outsourced.
- Retail:Agricultural supply cooperatives serve smaller independent livestock producers with standardized premix SKUs.
- Direct Sales:Thai and Mexican poultry integrators are building in-house procurement functions that bypass external distribution layers entirely.
Relationship density favors offline; margin compression favors direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European formulators facing REACH zinc oxide deadlines, while Brazilian producers leverage scale economies in antibiotic premix volumes to offset margin compression elsewhere.
United States
Poultry integrators in Georgia and Arkansas are expanding in-house premix capabilities to manage coccidiosis pressure under FDA Veterinary Feed Directive documentation requirements. The directive mandates veterinary oversight for all medically important antibiotics in feed, driving consolidation toward operations with captive veterinary advisory functions. Iowa and North Carolina swine operations are retrofitting liquid dosing infrastructure to comply with residue testing protocols.
Brazil
Integrated processors in Paraná and Santa Catarina states are internalizing formulation capabilities to control disease pressure in high-density broiler houses exceeding 50,000 birds per facility. ANVISA registration pathways for reduced-antibiotic premixes are accelerating product launch timelines for qualified applicants. São Paulo-based compounders are backward integrating into grain origination to secure corn and soybean meal supply chains against currency volatility.
Germany
Dairy nutrition programs in Bavaria and Lower Saxony are testing microencapsulated precision delivery systems for rumen-protected active release ahead of EMA antibiotic growth promoter phase-out deadlines. The Federal Office of Consumer Protection and Food Safety enforces residue monitoring through farm audit protocols. Rhineland-Palatinate feed mills are consolidating dedicated production lines to prevent cross-contamination with non-medicated sequences.
China
Shrimp farming operations in Guangdong and Hainan provinces are scaling antiparasitic premix programs as coastal stocking densities intensify disease pressure in intensive aquaculture zones. The NMPA and Ministry of Agriculture are tightening import registration requirements for medicated premixes, creating compliance barriers for non-domestic suppliers. Yangtze River Delta feed compounders are securing domestic API sourcing for tetracycline classes to reduce export license exposure.
Norway
Salmon producers in Vestland and Trøndelag counties are adopting postbiotic fermentation metabolites at commercial scale to reduce sea lice bath treatment dependency. The Norwegian Medicines Agency regulates functional additives under veterinary pharmaceutical frameworks when therapeutic claims are asserted. Bergen-area nutrition technology firms are licensing microencapsulation platforms to Scottish and Chilean aquaculture operations.
Global Medicated Feed Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with veterinary pharmaceutical specialists commanding premium positioning in regulated antibiotic categories while grain-trading conglomerates dominate volume economics in standard premix formulations. The market structure concentrates procurement authority among vertically integrated protein processors with captive milling infrastructure, displacing traditional distribution layers. Three archetypes define competitive positioning: multinational nutrition conglomerates with origination networks, veterinary pharmaceutical specialists with regulatory submission expertise, and regional compounders with species-specific formulation capabilities. Dominant competitive moves include backward integration into API sourcing and technology licensing partnerships for precision delivery systems.
Within the veterinary pharmaceutical tier, Zoetis and Elanco Animal Health Incorporated exemplify regulatory-driven positioning, while Cargill, Incorporated anchors the grain-origination archetype with multi-continent input cost control. These three entities represent divergent strategic pathways: pharmaceutical expertise extending into feed partnerships versus commodity infrastructure capturing formulation margin.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Phibro Animal Health Corporation |
| Elanco Animal Health Incorporated |
| Adisseo |
| Kemin Industries |
| Zoetis |
| Nutreco |
| Alltech |
| Others |
Value Chain & Pricing Dynamics
Yeast-based additive platforms replacing conventional antibiotic premixes are redrawing raw material sourcing maps from Chinese API clusters toward European fermentation facilities while compressing legacy tetracycline pricing bands. This substitution dynamic simultaneously elevates logistics costs for temperature-sensitive biological inputs and creates premium capture opportunities for formulation houses with cold-chain infrastructure.
Pricing Analysis
The customization-premium spread separates configured-to-order phytogenic blends from standard macrolide premixes. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under EMA Veterinary Medicines Regulation and volume scale at Brazilian integrated processors. Pricing pressure stems from REACH zinc oxide phase-out deadlines compressing margin pools in European weaner pig formulations. Mid-tier compounders exhibit highest price sensitivity due to residue testing cost burdens, while Norwegian salmon producers show lowest sensitivity for sea lice alternative technologies.
Supply Chain Analysis
Inventory lead times for heat-sensitive probiotic additives stretch beyond stable antibiotic premix cycles due to cold-chain requirements. Active pharmaceutical ingredient sourcing draws from China, India, and domestic European fermentation capacity. Tetracycline and macrolide classes hinge on concentrated Chinese manufacturers. Single-source vulnerability from export license volatility creates supply interruption exposure. Distribution runs through vertically integrated poultry processors in Brazil and Thailand that internalize procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary pharmacologists capable of bridging feed manufacturing and regulatory submission writing command compensation premiums that mid-tier compounders cannot match, creating acquisition scarcity for talent-rich targets.
For Market Incumbents: Consolidate formulation talent pools through targeted acquisitions of regional compounders with species-specific expertise in aquaculture or ruminant applications. Build captive API sourcing relationships in India to reduce Chinese export license exposure. ANVISA registration acceleration in Brazil demands preemptive compliance investment before competitor lock-in. For New Entrants and Emerging Players: Lead with postbiotic fermentation metabolite platforms targeting Norwegian salmon producers seeking sea lice treatment alternatives. Vietnamese shrimp farming operations present the most penetrable geography for antiparasitic premix partnerships. Digital prescription platform integration offers a differentiated go-to-market angle for North American compliance automation. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors technology-licensing specialists over commodity premix compounders. Long-term viability centers on precision delivery system IP and reduced-antibiotic formulation pipelines. Target acquisition archetypes include microencapsulation technology holders and Brazilian grain-origination integrated compounders. Monitor EMA antibiotic growth promoter phase-out enforcement as the critical inflection signal for portfolio reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | Secures tetracycline supply chains against Chinese export license volatility for European formulators. |
| Microencapsulation Technology Licensing | Opens premium pricing tiers in German dairy nutrition programs for rumen-protected active release. |
| Digital Prescription Platform Integration | Streamlines FDA Veterinary Feed Directive compliance documentation for US poultry integrators. |
| Postbiotic Fermentation Scale-Up | Reduces Norwegian salmon producer dependency on sea lice bath treatments at commercial scale. |
| Grain Origination Network Expansion | Controls input costs for São Paulo compounders facing Brazilian currency volatility. |
Study Parameters
Operator-level perspectives from feed mill managers, veterinary pharmacologists, regulatory affairs specialists, and integrated poultry procurement directors anchored the qualitative base. Secondary validation drew from FDA Veterinary Feed Directive filings, EMA centralized marketing authorization databases, ANVISA registration records, and Brazilian agricultural trade statistics. Bottom-up volume estimates triangulated against top-down industry value reconstructions.
Sensitivity analysis tested forecast outputs against alternative regulatory enforcement timelines and API supply disruption scenarios. Segmentation dimensions modeled include active ingredient class, animal type, physical formulation, and distribution channel across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for structural shifts in antimicrobial resistance policy. Industry-specific inputs encompassed shrimp stocking density trends in Vietnam and zinc-free diet transition completion rates in Denmark.
Underlying assumptions cover REACH enforcement adherence, FDA veterinary oversight compliance rates, and Chinese API export license stability, with deviation risk concentrated in regulatory deadline acceleration and trade policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
United States Floriculture Market