
 Africa Poultry Feed Market | 2026-2036
Africa Poultry Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Poultry Feed Market Outlook
ISO 22000 certification for feed safety management is unwinding competitive access across the Africa poultry feed landscape, favoring operators with capital to implement hazard analysis protocols. Cargill Inc. leverages its integrated grain-trading infrastructure to secure maize and soybean supply chains from South Africa into neighboring markets. Nutreco N.V. anchors its position through premix and concentrate specialization, while Alltech Inc. differentiates via yeast-based mycotoxin mitigation technologies tailored to tropical storage conditions.
Africa poultry feed comprises formulated rations designed to deliver metabolizable energy of 2,800–3,200 kcal/kg and crude protein levels of 16–22% for broiler and layer life-stage requirements, manufactured through grinding, mixing, pelleting, and extrusion processes to optimize feed conversion ratios. Pellet formulations command premium positioning among commercial integrators due to reduced feed wastage and improved nutrient density relative to mash alternatives. Protein Meals derived from soybean cake and fishmeal represent the fastest-growing ingredient category as local oilseed crushing capacity expands, while Additives targeting gut health and enzyme supplementation capture expanding margin pools from antibiotic-reduction mandates.
Nigeria's National Agency for Food and Drug Administration and Control (NAFDAC) enforces feed additive registration and maximum residue limits, while South Africa's Department of Agriculture, Land Reform and Rural Development (DALRRD) administers veterinary stock remedy controls that shape product formulation requirements. The FAO/WHO Codex Alimentarius feed safety guidelines increasingly influence national standards adoption across Ghana, Kenya, and Ethiopia, creating compliance convergence pressure. Stakeholders must monitor harmonization between national feed safety regimes and emerging regional economic community protocols to anticipate market access barriers and formulation adaptation costs.
Market Dynamics
ISO 22000 certification requirements are consolidating procurement relationships around compound feed suppliers capable of implementing hazard analysis protocols, squeezing smaller operators without capital for laboratory infrastructure and documented critical control points.
Growth Catalysts
- FAO Codex Alimentarius adoption:Ghana, Kenya, and Ethiopia are harmonizing national feed safety standards with FAO/WHO guidelines, creating regulatory clarity that accelerates commercial integrator investment in standardized supply chains.
- Lagos-Ibadan corridor demand concentration:Nigerian layer farm consolidation is generating procurement scale sufficient to justify pelleting investments by compound feed manufacturers seeking feed conversion ratio improvements.
- Antibiotic reduction mandates:Enzyme supplementation and gut health additives capture expanding formulation budgets as regulators tighten veterinary stock remedy controls across East and West Africa.
Market Restraints
- Maize supply volatility:Regional grain trading infrastructure concentrates in South African silo networks, exposing Nigerian and Ghanaian feed mills to transport cost spikes during harvest compression periods.
- Mycotoxin contamination risk:Tropical storage conditions elevate aflatoxin prevalence in groundnut cake and maize, forcing integrators to absorb binding agent costs or face layer flock mortality.
- Local oilseed crushing undercapacity:Insufficient soybean processing infrastructure in Ethiopia and Tanzania traps feed formulators between imported meal prices and protein meal specification requirements.
Strategic Opportunities
- Ethiopian commercial poultry emergence:Addis Ababa and Hawassa integrators are scaling from backyard systems to controlled-environment housing, creating first-mover advantage for premix suppliers establishing technical service presence.
- Regional economic community protocol alignment:ECOWAS and EAC feed safety harmonization initiatives promise cross-border registration reciprocity, reducing formulation adaptation costs for multi-country operators.
- Yeast-based mycotoxin mitigation:Biotechnological detoxification approaches tailored to high-temperature, high-humidity storage regimes offer differentiation where chemical binders underperform.
Industry Challenges
- ISO 22000 implementation timeline:Small and mid-scale feed mills lack trained food safety management system auditors, stretching certification preparation across 18-24 month cycles while competitors secure integrator contracts.
- Specialized nutritionist scarcity:Poultry feed formulation expertise concentrates with multinational premix suppliers, constraining independent mill capacity to optimize metabolizable energy and amino acid matrices for local ingredient availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Poultry Feed Market |
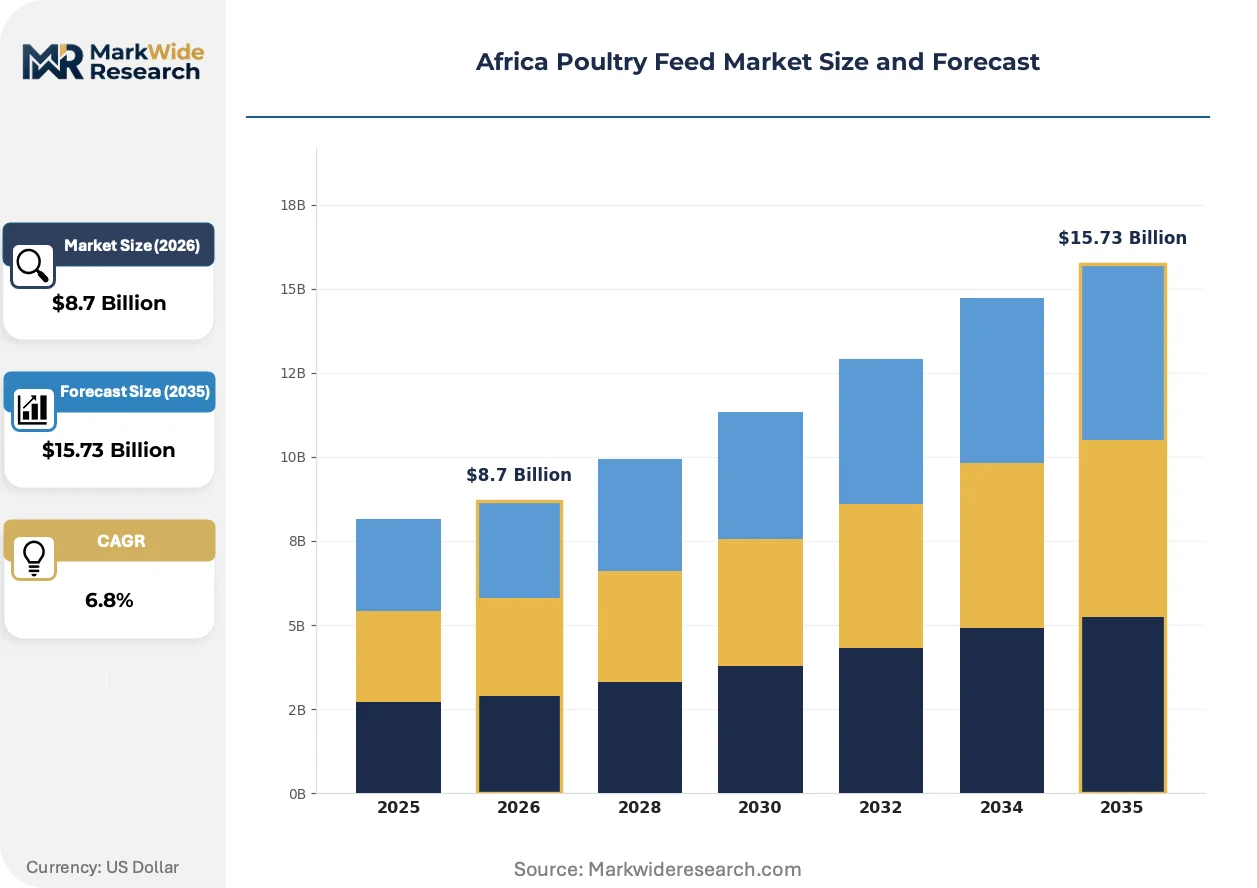
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Crumbles, Mash, Liquid Feed Ingredient Type: Cereal Grains, Protein Meals, Vitamins, Additives End User: Commercial Farms, Backyard Poultry, Integrators, Feed Mills Distribution Channel: Online Retail, Department Stores, Direct Sales, Wholesalers |
| Companies Covered | Cargill Inc., Nutreco N.V., Alltech Inc., Kemin Industries Inc., Novus International, Inc., Nova Feeds, Serfco, Adisseo, Astral Foods Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Poultry Feed Market Strategic Shifts
Pelleting technology adoption is compressing feed conversion economics for commercial integrators while regulatory convergence around Codex standards reshapes competitive access requirements across the continent.
Extrusion processing for full-fat soybean meal is miniaturizing capital requirements for on-farm heat treatment, enabling mid-scale layer operations in Ogun State and Gauteng to bypass oilseed crushing bottlenecks. These operators are retrofitting existing hammer mill infrastructure with single-screw extruders at one-third the capital intensity of commercial crushing plants. The technology is miniaturizing the minimum efficient scale for protein meal security, fragmenting procurement concentration previously held by integrated trading houses.
Kenya's Agriculture and Food Authority is enforcing mycotoxin maximum limits for maize-based feeds under standards aligned with FAO/WHO Codex Alimentarius guidelines, triggering laboratory investment requirements across commercial millers. This regulatory tightening is disqualifying informal sector suppliers from formal sector integrator contracts. Layer operations in Kiambu and Nakuru counties are responding by consolidating supplier relationships around ISO-certified compound feed manufacturers with documented hazard analysis protocols.
Compound feed procurement is consolidating around annual volume contracts with technical service attachments, displacing spot market purchasing among commercial integrators seeking ration consistency and veterinary support integration. This contractual shift is compressing working capital cycles for smaller mills lacking balance sheet depth to extend trade credit. The transformation is most visible in Nigeria's Southwest zone, where Shagamu and Ibadan integrators are locking in three-year supply agreements with premix-anchored formulation partners.
Africa Poultry Feed Market Segmentation
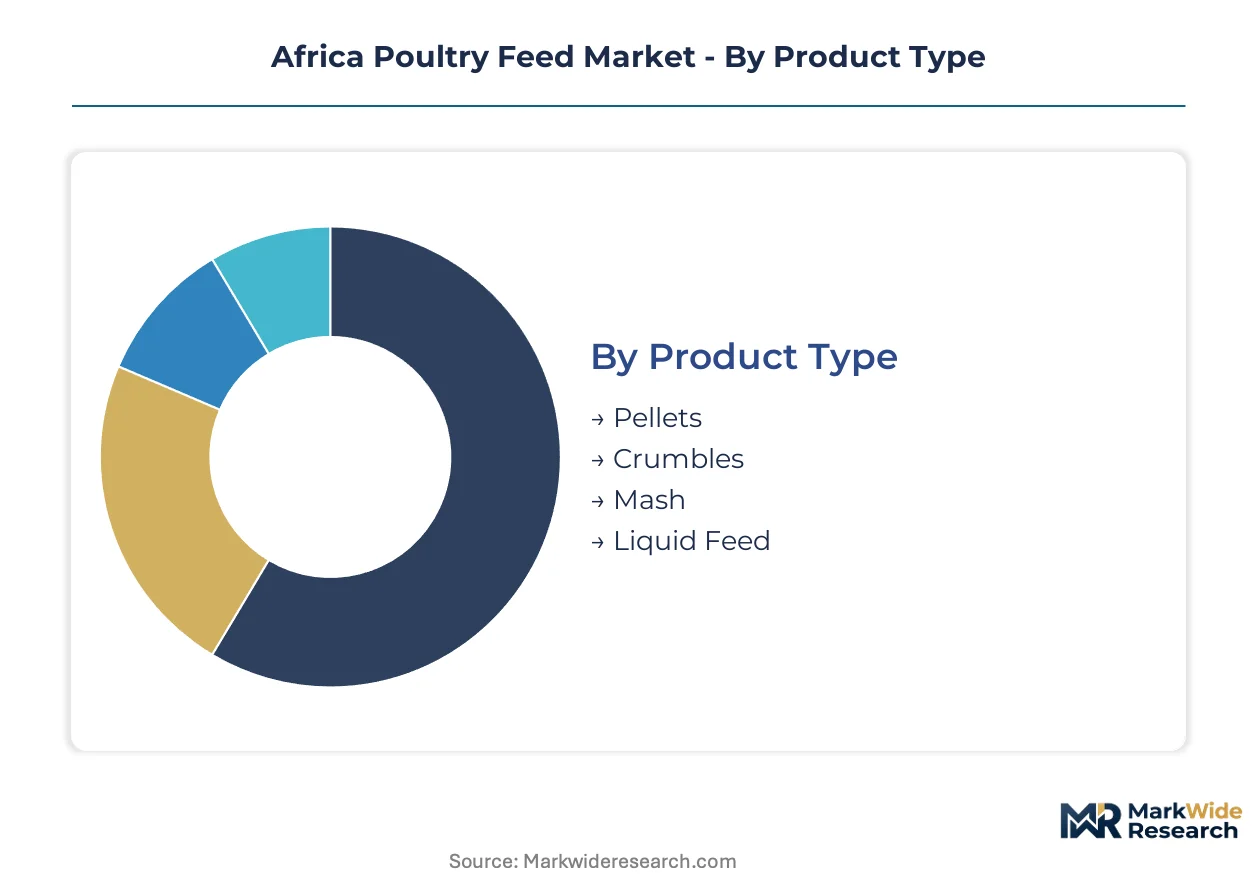
Feed formulators in Africa navigate divergent procurement patterns across commercial integrators and backyard producers, with product specifications and channel access determining margin capture. Segmentation reveals where capital-intensive pelleting investments concentrate versus where price-sensitive mash formulations retain volume dominance.
Product Type:
Pellet formulations flow through integrator procurement contracts, while mash and liquid alternatives serve fragmented backyard channels with minimal technical service attachment.
- Pellets:Compressed cylindrical formulations manufactured through steam conditioning and die extrusion, achieving 2,800–3,200 kcal/kg metabolizable energy density with 16–22% crude protein. Nigerian layer operations in Lagos-Ibadan corridor are locking in three-year supply agreements with ISO-certified compound feed manufacturers, prioritizing feed conversion ratio improvements over unit cost.
- Crumble:Intermediate particle size produced by grinding pellets, bridging mash and pellet formats for pullet rearing and breeder flocks. Kenyan integrators in Kiambu and Nakuru counties are consolidating supplier relationships around crumble-capable mills with documented Codex-aligned hazard analysis protocols.
- Mash:Ground and mixed but unprocessed feed retaining ingredient particle integrity, commanding price positioning among backyard poultry operators lacking pelleting infrastructure.
- Liquid Feed:Suspended nutrient solutions delivered through automated drinking systems, penetrating controlled-environment housing installations in Gauteng and Addis Ababa with precision dosing requirements.
Pellets dominate installed base among commercial integrators. Crumbles is where expansion concentrates as pullet rearing scales in East African markets.
Ingredient Type:
Cost tier stratification separates commodity cereal flows from value-captured additive categories, with protein meals occupying the contested middle ground.
- Protein Meals:Soybean cake and fishmeal derivatives supplying essential amino acid profiles for broiler and layer life-stage requirements. Ethiopian and Tanzanian feed formulators remain trapped between imported meal prices and local oilseed crushing undercapacity, constraining formulation flexibility.
- Additives:Enzyme supplementation, gut health promoters, and mycotoxin binders capturing expanding formulation budgets as NAFDAC and DALRRD tighten veterinary stock remedy controls. Alltech's yeast-based detoxification technologies are gaining differentiation in high-temperature, high-humidity storage regimes where chemical binders underperform.
- Cereal Grains:Maize and sorghum providing basal metabolizable energy, with supply volatility concentrated in South African silo networks exposing Nigerian mills to transport cost spikes.
- Vitamins:Premix-concentrated micronutrient packages, with formulation expertise concentrating among multinational suppliers constraining independent mill optimization capacity.
Cereal Grains dominate installed base by volume. Additives is where margin expansion concentrates as antibiotic-reduction mandates reshape formulation economics.
End User:
Customer type determines technical service intensity and contract structure, with procurement scale separating annual volume agreements from spot market purchasing.
- Integrators:Vertically controlled operations spanning breeding through processing, demanding ration consistency and veterinary support integration. Southwest Nigeria's Shagamu and Ibadan operations are displacing spot market purchasing with premix-anchored formulation partnerships.
- Commercial Farms:Standalone layer and broiler operations scaling from semi-intensive to controlled-environment housing, creating first-mover advantage for premix suppliers establishing technical service presence in Hawassa and Addis Ababa.
- Feed Mills:Independent compound feed manufacturers lacking ISO 22000 certification, facing 18-24 month preparation cycles while competitors secure integrator contracts.
- Backyard Poultry:Small-scale household operations retaining mash preference due to capital constraints and informal sector regulatory exemption.
Backyard Poultry dominates installed base by operation count. Integrators is where procurement consolidation concentrates.
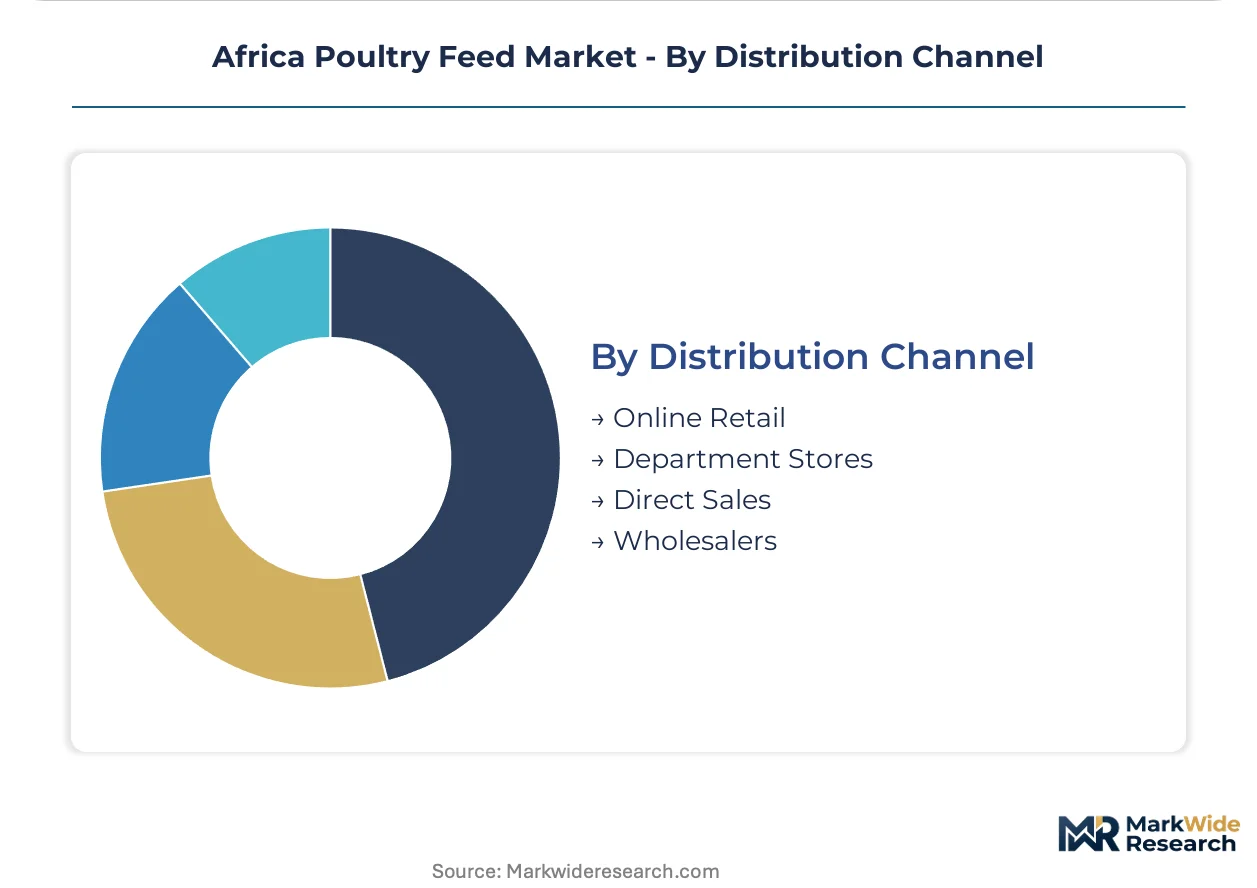
Distribution Channel:
Channel maturity separates credit-extending wholesale networks from emerging direct sales relationships with technical service attachments.
- Direct Sales:Manufacturer-to-integrator relationships with annual volume contracts and formulation customization, compressing working capital cycles for smaller mills lacking balance sheet depth.
- Wholesalers:Aggregated distribution through regional feed depots serving fragmented commercial farms and feed mills, retaining volume dominance in Ghana and Ethiopia.
- Online Retail:Emerging platform-based procurement for premix concentrates and specialty additives, penetrating Nairobi and Lagos metropolitan areas with delivery logistics constraints.
- Department Stores:Limited penetration for packaged supplements and small-scale premix, constrained by cold chain requirements for certain vitamin formulations.
Wholesalers dominate installed base. Direct Sales is where relationship value concentrates as procurement shifts toward technical service-anchored contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial integrators across the continent are consolidating procurement relationships around ISO-certified compound feed manufacturers, with demand concentrating in specific urban corridors and agricultural zones where layer farm density justifies pelleting investments.
Nigeria
Lagos-Ibadan corridor integrators are locking in three-year supply agreements with premix-anchored formulation partners. NAFDAC enforces feed additive registration and maximum residue limits that disqualify informal sector suppliers from formal contracts. Shagamu and Ibadan operations are displacing spot market purchasing with technical service-integrated annual volume contracts.
South Africa
Gauteng's controlled-environment housing installations are driving liquid feed penetration through automated drinking systems with precision dosing requirements. DALRRD administers veterinary stock remedy controls that shape product formulation requirements for antibiotic reduction. Cape Town and Durban feed mills leverage integrated grain-trading infrastructure to secure maize supply chains into neighboring markets.
Kenya
Kiambu and Nakuru county layer operations are consolidating supplier relationships around ISO-certified mills with documented Codex-aligned hazard analysis protocols. The Agriculture and Food Authority enforces mycotoxin maximum limits for maize-based feeds under standards aligned with FAO/WHO guidelines. Nairobi metropolitan premix demand is fragmenting procurement concentration previously held by integrated trading houses.
Ethiopia
Addis Ababa and Hawassa integrators are scaling from backyard systems to controlled-environment housing, creating first-mover advantage for premix suppliers establishing technical service presence. National feed safety standards adoption is converging toward FAO/WHO Codex Alimentarius guidelines. Hawassa industrial park proximity is compressing transport cost spikes for commercial mills sourcing protein meals.
Ghana
Accra-Tema corridor commercial farms are demanding ration consistency and veterinary support integration through contractual procurement shifts. FAO Codex Alimentarius adoption is harmonizing national feed safety standards with regional economic community protocols. Kumasi feed mills face working capital cycle compression as integrators extend trade credit requirements.
Africa Poultry Feed Market Competitive Environment
Player mix skews toward multinational grain traders and premix specialists with capital for ISO 22000 certification infrastructure. Market structure concentrates procurement relationships around compound feed suppliers capable of implementing hazard analysis protocols, squeezing smaller operators without laboratory infrastructure. Two strategic archetypes dominate: integrated grain-trading houses leveraging captive supply chains, and premix-concentrate specialists anchoring formulation partnerships. Competitive moves center on backward integration into oilseed crushing capacity and geographic expansion through technical service presence establishment.
Within the integrated trading tier, Cargill Inc. and Nutreco N.V. exemplify archetypes combining grain origination with formulation expertise. Among biotechnology-focused operators, Alltech Inc. occupies a position representing yeast-based mycotoxin mitigation differentiation. These three anchors illustrate how capital depth for certification infrastructure and tropical-adapted technology development determines competitive access across procurement consolidation trends.
| Leading Market Players |
|---|
| Cargill Inc. |
| Nutreco N.V. |
| Alltech Inc. |
| Kemin Industries Inc. |
| Novus International, Inc. |
| Nova Feeds |
| Serfco |
| Adisseo |
| Astral Foods Limited |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day maize inventory cycles at Nigerian feed mills tether working capital requirements to South African silo origination, compressing margin capture when Lagos-Ibadan corridor integrators demand extended trade credit. This lead-time exposure concentrates pricing power with grain-trading houses controlling inland logistics, while compound feed manufacturers absorb binding agent cost volatility from tropical mycotoxin prevalence.
Pricing Analysis
Cost-plus contracts indexed to South African Futures Exchange white maize prices dominate procurement between Nigerian integrators and compound feed suppliers, with premium tiers attaching ISO 22000 certification and technical service bundles. Price differentiation separates Codex-aligned formulations from informal sector mash, with antibiotic-free additive packages commanding formulation premiums. Pricing pressure stems from soybean meal import dependency as local crushing undercapacity persists in Ethiopia and Tanzania. Backyard poultry operators retain highest price sensitivity, while Lagos-Ibadan corridor integrators prioritize feed conversion ratio consistency over unit cost.
Supply Chain Analysis
South Africa and Argentina anchor global maize supply into West African feed mills, with Nigerian and Ghanaian formulators drawing from these origins to compensate for domestic harvest shortfalls. Soybean cake, fishmeal, and vitamin premix constitute critical input dependencies, with protein meal specifications often requiring cross-hemisphere sourcing. Single-source vulnerability concentrates in South African silo network chokepoints during harvest compression periods. Distribution runs through wholesale feed depots in Kumasi and Accra-Tema corridor, though direct manufacturer-to-integrator contracts with technical service attachments are displacing spot market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise scarcity constrains independent mill capacity to optimize amino acid matrices, locking margin capture with multinational premix suppliers possessing laboratory infrastructure and documented hazard analysis protocols.
For Market Incumbents: Fortify backward integration into oilseed crushing capacity in Ethiopia and Tanzania to bypass imported meal price volatility, while accelerating ISO 22000 certification timelines to preempt competitor access to integrator contracts. Cargill Inc. and Nutreco N.V. anchor positions through captive grain origination and premix specialization respectively; smaller operators must defend against this consolidation through technical service density in emerging commercial poultry zones like Hawassa. For New Entrants and Emerging Players: Lead with yeast-based mycotoxin mitigation technologies tailored to high-temperature, high-humidity storage regimes, where chemical binders underperform and Alltech Inc. has established differentiation precedent. Ethiopian commercial poultry emergence from backyard systems presents the most penetrable geography, with Addis Ababa and Hawassa integrators scaling controlled-environment housing and requiring first-mover premix suppliers. Establish technical service presence before compound feed procurement relationships crystallize around incumbent formulation partners. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pelleting infrastructure and laboratory certification requirements, favoring acquisition targets with existing ISO 22000 documentation and integrator contract backlogs. Long-term viability across the projection horizon rests on backward integration into protein meal security and regulatory convergence positioning. Watch for ECOWAS and EAC feed safety harmonization implementation as signal of cross-border registration reciprocity enabling multi-country operator scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Ethiopian and Tanzanian crushing capacity reduces imported soybean meal price exposure for regional formulators. |
| ISO 22000 Certification Acceleration | NAFDAC-aligned hazard analysis protocols unlock Lagos-Ibadan corridor integrator procurement contracts. |
| Technical Service Presence Establishment | Addis Ababa and Hawassa premix demand creates first-mover advantage before procurement consolidation. |
| Yeast-Based Mycotoxin Mitigation R&D | Tropical storage adaptation differentiates from chemical binders underperforming in high-humidity regimes. |
| Regional Economic Community Protocol Alignment | ECOWAS and EAC harmonization reduces formulation adaptation costs for multi-country operators. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with feed mill operations managers, poultry integrator procurement heads, veterinary nutritionists, and NAFDAC regulatory affairs officers; and secondary validation through FAO/WHO Codex Alimentarius guidelines, DALRRD veterinary stock remedy filings, South African Futures Exchange grain trade data, and compound feed industry association reports. Bottom-up demand modeling from layer and broiler flock projections triangulated against top-down supply capacity assessments across Nigerian, South African, Kenyan, Ethiopian, and Ghanaian milling infrastructure.
Across the analysis window, forecasts applied segment-specific growth trajectories by product type, ingredient category, end-user procurement scale, and distribution channel maturity, with CAGRs derived from regression against protein meal import dependency ratios and commercial poultry housing investment cycles. Model inputs incorporated mycotoxin maximum limit enforcement intensity, antibiotic reduction mandate progression, and regional economic community protocol adoption timelines.
Forecasts assume regulatory continuity in NAFDAC feed additive registration regimes and DALRRD veterinary stock remedy controls; material policy shifts or FAO/WHO guideline adoption acceleration would require re-modeling. Recalibration cycles align with material shifts in commercial integrator procurement contract structures and regional feed safety harmonization implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Saudi Arabia Eggs Market