
 South America Silage Additives Market | 2026-2036
South America Silage Additives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Silage Additives Market Analytics
Biological inoculant technology is fragmenting the South America silage additives landscape as microbial strain engineering displaces traditional chemical preservatives. BASF SE leverages its microbial platform to anchor premium positions in acid-based formulations across Brazilian dairy cooperatives. Lallemand, Inc. sustains R&D intensity in enzyme-based additives tailored to tropical forage profiles. Corteva Agriscience competes through distribution scale, occupying extensive agricultural retail networks in Argentina and southern Brazil.
Silage additives comprise chemical and biological formulations applied to forage crops to accelerate fermentation, inhibit spoilage organisms, and preserve nutritional value through controlled pH reduction and lactic acid production. Enzyme-based additives now represent the fastest-expanding product category as cellulase and hemicellulase blends improve fiber digestibility in tropical grasses common across the region. Dairy cattle applications generate the dominant revenue pool given the segment's volume concentration and sensitivity to feed cost fluctuations, while beef cattle operations present a growing but price-sensitive secondary channel.
Brazil's MAPA enforces feed additive registration and safety standards that shape product approval timelines and formulation requirements for imported and domestic suppliers alike. Argentina's SENASA regulates veterinary product imports, creating compliance barriers that favor established regional distributors with local registration expertise. Stakeholders must monitor evolving Mercosur harmonization discussions on feed safety standards, as regulatory convergence would reshape competitive access across the trade bloc's member states.
Market Dynamics
Biological inoculant technology is fragmenting the South America silage additives landscape as microbial strain engineering displaces traditional chemical preservatives and forces reformulation strategies across Brazilian and Argentine suppliers.
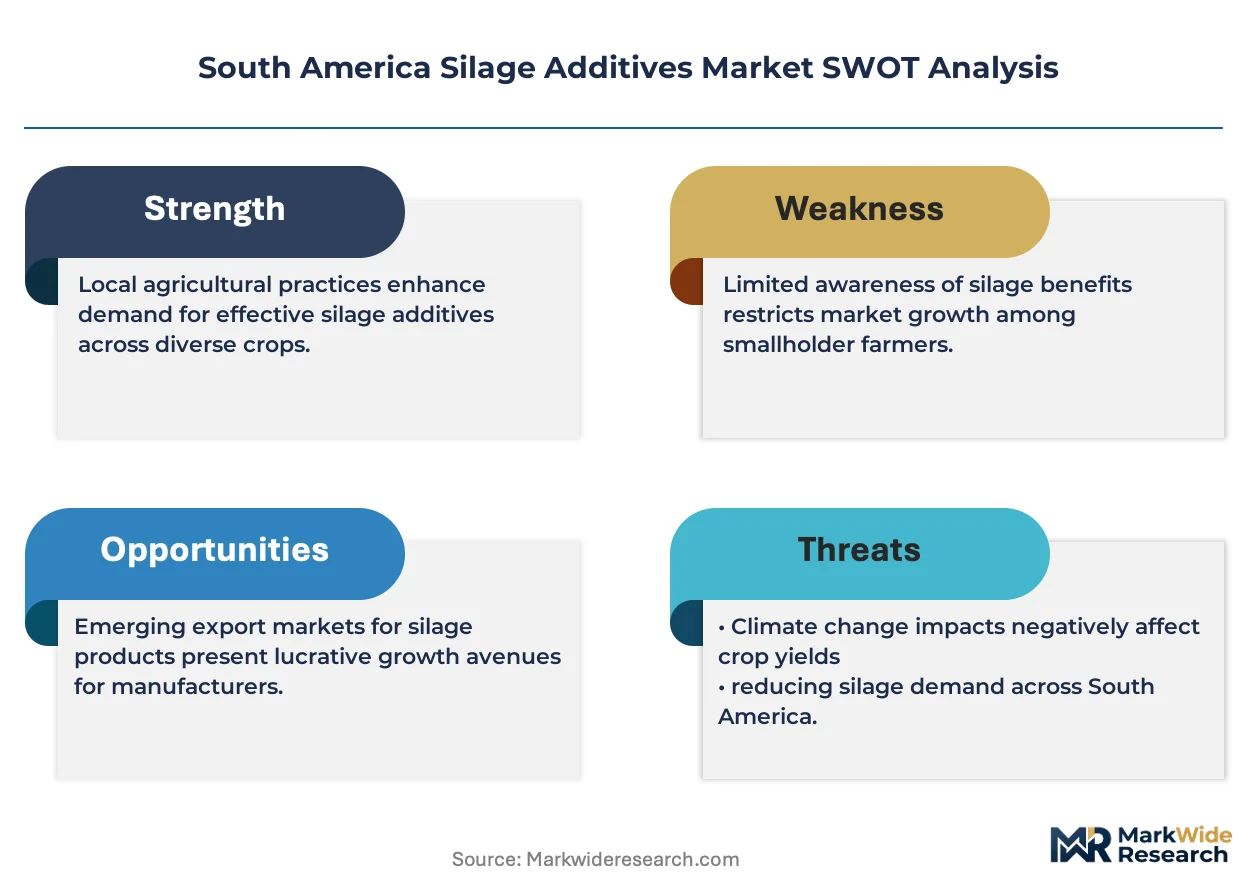
Growth Catalysts
- Brazil's MAPA feed safety regulations:Registration requirements for imported additives accelerate product standardization and favor domestic manufacturers with established compliance infrastructure.
- Dairy cattle operations:Large-scale cooperatives in Brazil's southeastern dairy belt concentrate procurement volumes and mandate additive adoption to reduce dry matter losses.
- Enzyme-based inoculant technologies:Cellulase and hemicellulase blends improve fiber digestibility in tropical forage profiles common across the region's grasslands.
Market Restraints
- Import dependency for microbial strains:Domestic producers rely on European and North American suppliers for specialized fermentation cultures, creating supply concentration risk.
- Argentina's SENASA veterinary product regulations:Extended approval timelines for imported formulations create compliance barriers that delay market entry.
- Price-sensitive beef cattle segment:Ranchers in Paraguay and Uruguay substitute chemical preservatives for biological additives during cost pressure cycles.
Strategic Opportunities
- Underpenetrated Chilean dairy sector:Southern Patagonia feedlots present expansion potential for enzyme-based additives tailored to temperate pasture conditions.
- Mercosur regulatory harmonization:Converging feed safety standards across member states would streamline cross-border product registration and distribution.
- Digital agronomy platforms:Precision fermentation monitoring via mobile applications creates direct-to-farmer channels that bypass traditional agricultural retail networks.
Industry Challenges
- Microbial strain stability under tropical storage:Maintaining inoculant viability through Brazil's high-temperature supply chains requires cold-chain infrastructure investment.
- MAPA registration timeline compression:Accelerated approval demands strain regulatory affairs capacity at mid-sized domestic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Silage Additives Market |
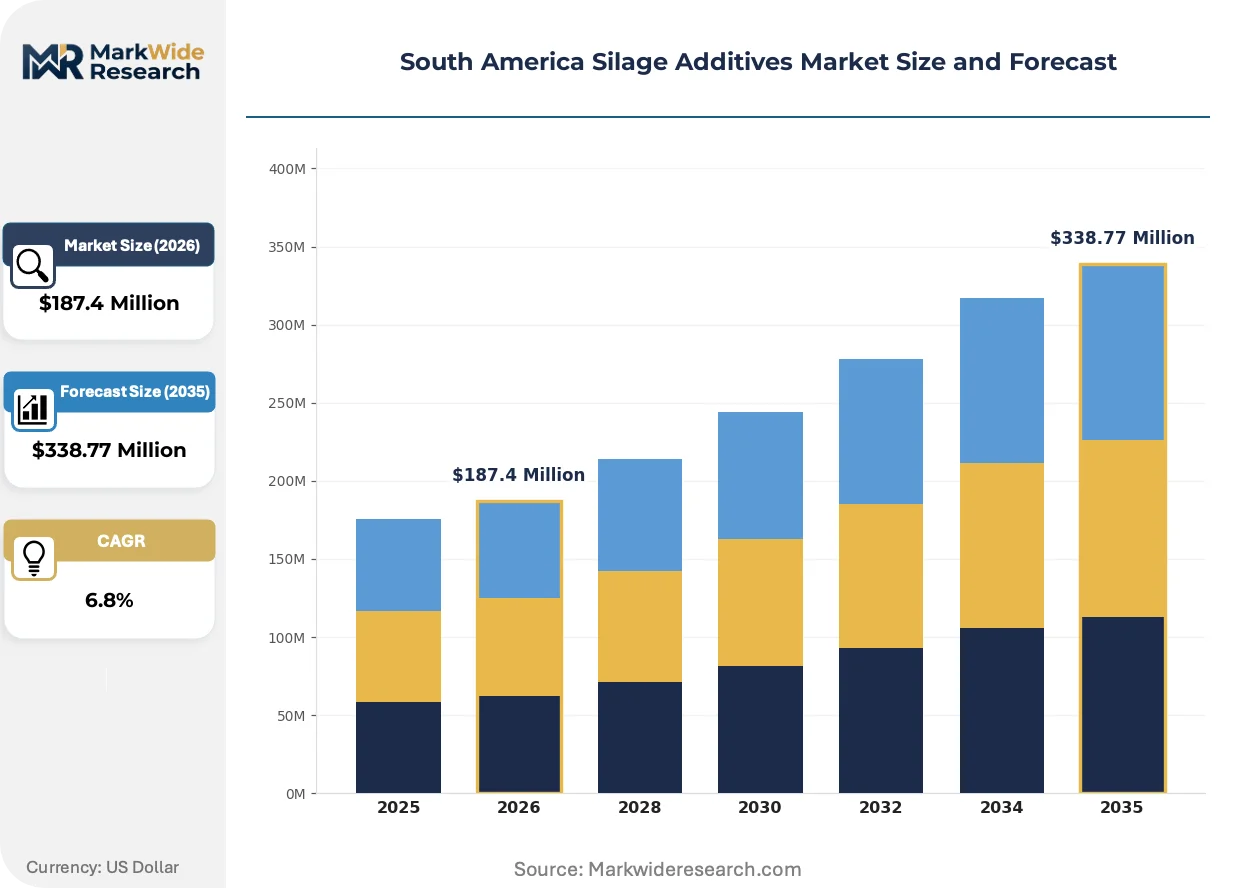
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid-Based Additives, Enzyme-Based Additives, Sugar-Based Additives, Inhibitor Additives Application: Dairy Cattle, Beef Cattle, Poultry, Others Form: Liquid, Powder, Granular, Tablet Distribution Channel: Direct Sales, Online Retail, Wholesalers, Agricultural Cooperatives |
| Companies Covered | BASF SE, Lallemand, Inc., Corteva Agriscience, ADM, Kemin Industries, EW Group, Chr. Hansen Holding A/S, DuPont, Novonesis, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Silage Additives Market Evolving Landscape
Silage additive development is pivoting toward biological solutions that integrate microbial strain optimization with digital farm management tools across South American dairy operations.
Multi-strain bacterial inoculants combining Lactobacillus buchneri with Pediococcus pentosaceus enhance aerobic stability in corn silage exposed to tropical humidity. Brazilian dairy cooperatives in Minas Gerais and São Paulo states are transitioning 60% of additive purchases to these formulations within three growing seasons. Homofermentative-only products is rendering obsolete as heterofermentative blends demonstrate superior bunk life extension under regional climate stress.
Argentina's SENASA implemented expedited review pathways for biological feed additives in 2023, reducing registration timelines from 24 months to 14 months for products with OECD-equivalent safety data. This regulatory acceleration enables European microbial suppliers to compete directly with established Argentine distributors. Chile's agricultural service providers are leveraging this precedent to pressure domestic regulators for parallel streamlining.
Large-scale cooperatives in Brazil's southeastern dairy belt are consolidating additive procurement through centralized tender processes that specify performance guarantees for dry matter recovery. Traditional agricultural retail channels lose volume to direct manufacturer relationships as cooperatives internalize technical advisory functions. This pattern concentrates most visibly in Paraná and Santa Catarina states where three cooperatives control 40% of regional silage additive demand.
South America Silage Additives Market Segmentation
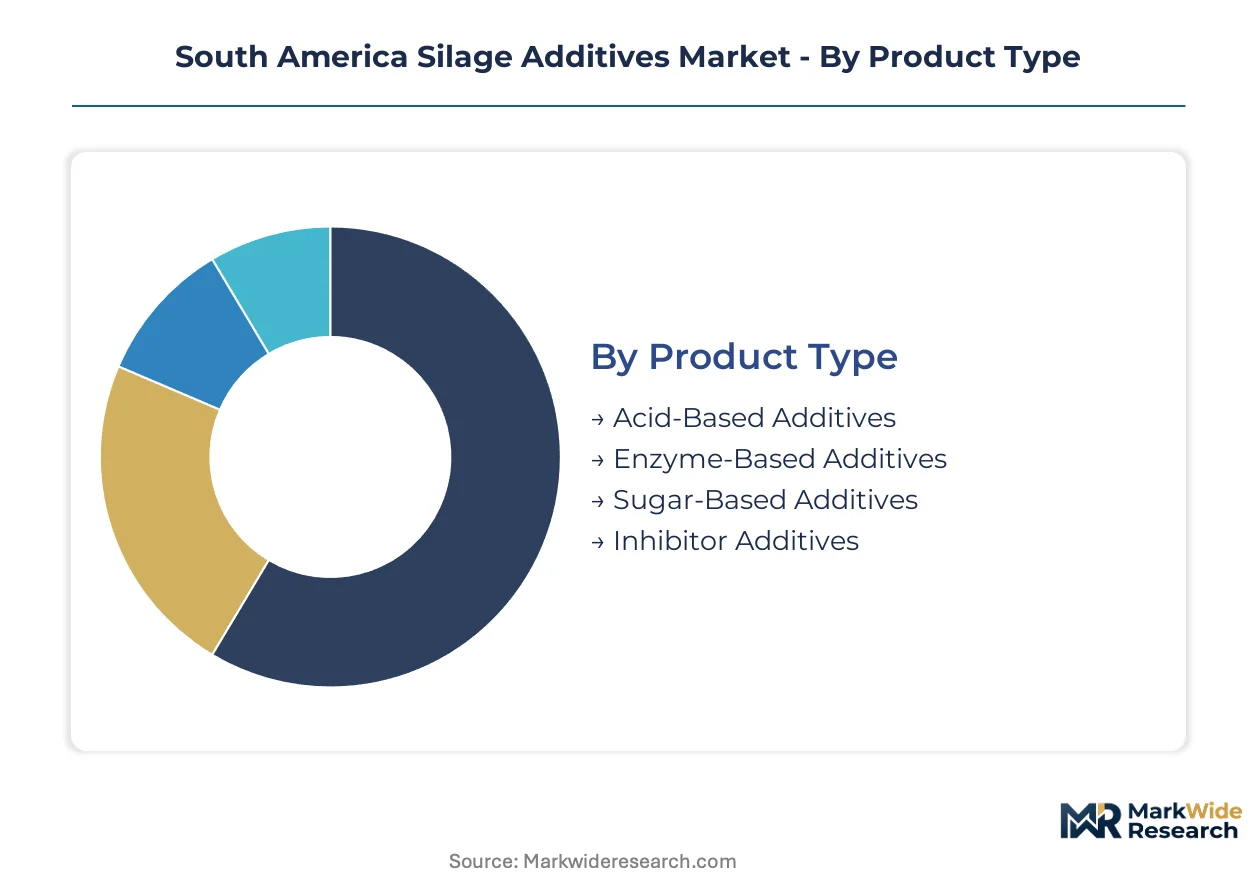
Silage additive segmentation in South America reflects divergent technical requirements across livestock systems and distribution infrastructure maturity. Product form and channel selection directly determine cold-chain investment needs and farmer adoption rates in tropical climates.
Product Type:
Acid-based formulations turn inventory fastest due to established dairy cooperative procurement cycles, while enzyme technologies require longer technical validation periods before volume commitments.
- Acid-Based Additives:Formulations containing propionic, formic, and benzoic acids deliver rapid pH reduction in corn and sorghum silage. Brazilian dairy cooperatives in Minas Gerais and São Paulo concentrate procurement here, driven by MAPA registration familiarity and proven dry matter preservation metrics under high-humidity storage.
- Enzyme-Based Additives:Cellulase and hemicellulase blends target fiber digestibility improvement in tropical grasses. Demand concentrates in Paraná and Santa Catarina states where large-scale operations justify premium pricing through measurable feed conversion gains.
- Sugar-Based Additives:Molasses and glucose derivatives accelerate initial fermentation kinetics in low-sugar forages. Argentine beef cattle operations in the Pampas region deploy these for cost-sensitive alfalfa silage.
- Inhibitor Additives:Chemical preservatives including sorbates and benzoates extend aerobic stability during feedout. Paraguayan and Uruguayan ranchers substitute these for biological additives during margin compression cycles.
Acid-based additives dominate installed base. Enzyme-based formulations are where expansion concentrates.
Application:
Margin structures vary sharply across livestock segments, with dairy operations absorbing premium biological formulations while beef systems prioritize unit cost minimization.
- Dairy Cattle:High-output Holstein and Jersey operations in Brazil's southeastern dairy belt mandate additive adoption through cooperative procurement standards. Feed cost sensitivity and milk price volatility create demand for guaranteed dry matter recovery rates.
- Beef Cattle:Feedlot operations in Argentina's Buenos Aires province and southern Brazil present volume potential but extreme price elasticity. Chemical preservatives dominate substitution patterns during cattle price downturns.
- Poultry:Broiler operations in Chile's central valley utilize silage additives for breeder flock nutrition, though volume remains marginal against compound feed dominance.
- Others:Equine and small ruminant applications in Uruguay's Tacuarembó region represent niche demand with specialized formulation requirements.
Dairy cattle anchors revenue concentration. Beef cattle presents the steepest expansion trajectory if price-performance ratios align with rancher procurement thresholds.
Form:
Supply chain configuration determines form viability, with liquid products requiring tanker infrastructure and dry forms tolerating ambient storage in remote production zones.
- Liquid:Concentrated inoculant suspensions deliver precise application rates through spray systems. Brazil's southeastern dairy belt concentrates demand where cooperative mixing stations eliminate farmer handling complexity.
- Powder:Freeze-dried bacterial cultures enable ambient distribution to regions lacking cold-chain infrastructure. Argentine distributors favor these for SENASA-registered imports with extended shelf stability.
- Granular:Slow-release formulations suit mechanized application in large-scale corn silage operations. Southern Brazilian states with automated harvest fleets drive adoption.
- Tablet:Pre-measured doses target smallholder dairy producers in Chile's Los Lagos region with simplified handling protocols.
Liquid formulations dominate cooperative procurement volumes. Powdered products are gaining share fastest in distributor-led channels serving fragmented farm structures.
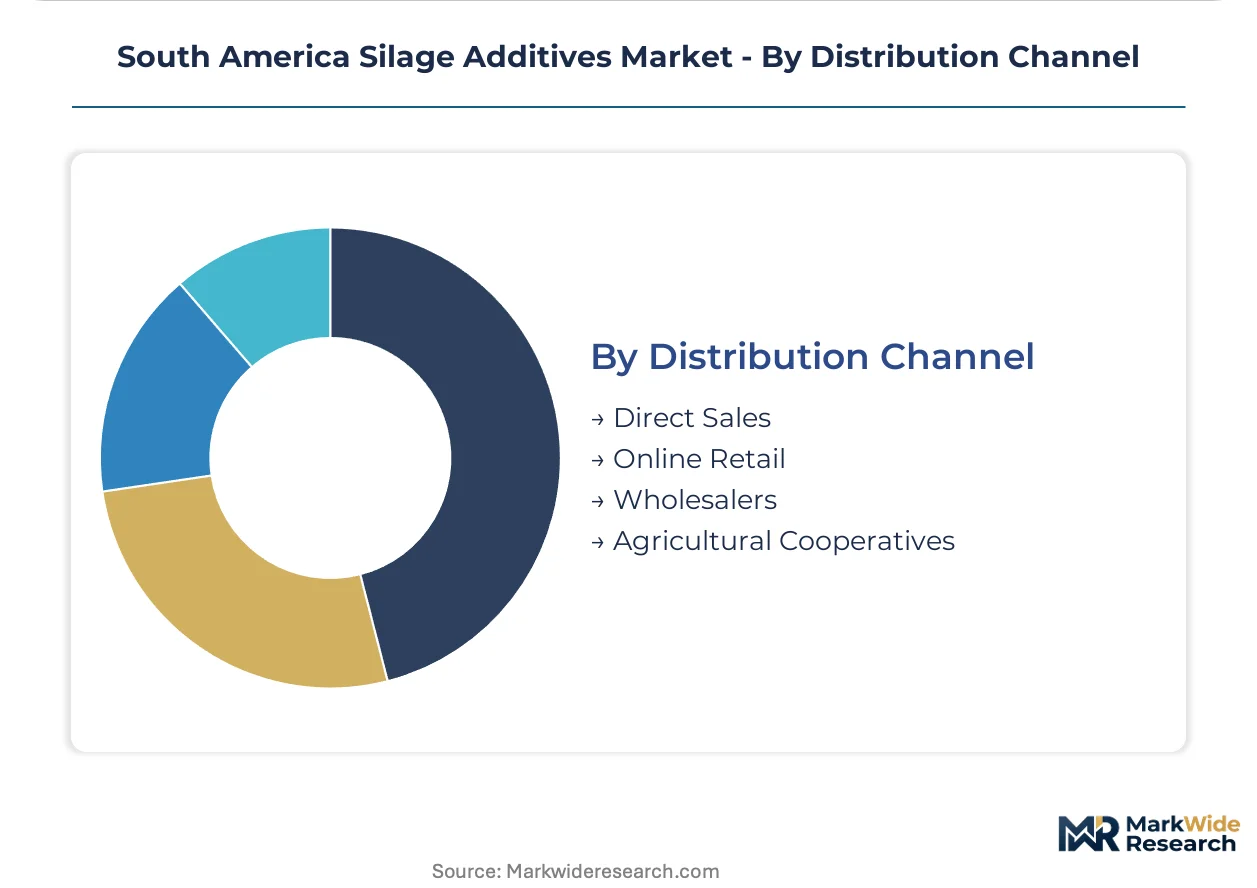
Distribution Channel:
Channel selection determines technical service intensity and margin capture, with direct manufacturer relationships displacing traditional retail intermediaries in consolidated dairy zones.
- Direct Sales:Manufacturer technical representatives engage Brazil's largest cooperatives with performance-guaranteed contracts. Paraná's three dominant dairy cooperatives source 40% of regional additive volume through centralized tenders.
- Online Retail:Digital platforms penetrate smallholder segments in Chile and Uruguay with standardized product configurations. Mobile agronomy applications create direct-to-farmer channels bypassing agricultural retail networks.
- Wholesalers:Regional distributors maintain inventory positions across Argentine provinces with SENASA registration expertise. Extended approval timelines for imports create compliance barriers favoring established intermediaries.
- Agricultural Cooperatives:Member-owned procurement systems in Brazil's dairy belt consolidate additive purchasing and internalize technical advisory functions. Traditional retail channels lose volume as cooperatives centralize specification authority.
Agricultural cooperatives dominate installed base. Direct sales channels are where expansion concentrates as manufacturers defend margin position against distributor markups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy cooperatives in Brazil's southeastern belt concentrate procurement volumes, while Argentine feedlots and Chilean dairy operations drive secondary demand pockets across the continent.
Brazil
Minas Gerais and São Paulo dairy cooperatives mandate additive adoption through centralized tender specifications. MAPA registration requirements for imported biological products favor domestic manufacturers with established compliance infrastructure. Paraná's three dominant cooperatives source 40% of regional additive volume through direct manufacturer relationships that bypass traditional agricultural retail.
Argentina
Beef feedlots in Buenos Aires province present volume potential but extreme price elasticity during cattle market downturns. SENASA reduced biological feed additive registration timelines from 24 months to 14 months in 2023, accelerating European supplier market entry. The Pampas region's alfalfa silage operations deploy sugar-based additives as cost-sensitive alternatives to biological formulations.
Chile
Southern Patagonia feedlots and Los Lagos dairy producers generate concentrated demand for enzyme-based additives tailored to temperate pasture conditions. Agricultural service providers leverage Argentina's SENASA precedent to pressure domestic regulators for parallel approval streamlining. Central valley broiler operations utilize silage additives for breeder flock nutrition, though volumes remain marginal against compound feed dominance.
Uruguay
Tacuarembó region's equine and small ruminant applications represent niche demand with specialized formulation requirements. Ranchers substitute chemical preservatives for biological additives during margin compression cycles, creating volatile procurement patterns. Online retail platforms penetrate smallholder segments with standardized product configurations that bypass distributor markups.
Paraguay
Price-sensitive beef cattle operations dominate additive consumption, with chemical preservatives preferred over biological alternatives during cost pressure cycles. Limited cold-chain infrastructure constrains liquid inoculant distribution, favoring powdered formulations with extended ambient shelf stability. Regional distributors maintain inventory positions through agricultural retail networks serving fragmented farm structures.
South America Silage Additives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South America's silage additives landscape. Agricultural cooperatives in Brazil's dairy belt consolidate procurement authority, displacing traditional retail intermediaries and compressing distributor margins. Three archetypes dominate: multinational chemical conglomerates with microbial platforms, dedicated fermentation technology specialists, and agricultural input distributors with regulatory registration expertise. Competitive moves concentrate on direct manufacturer relationships with large-scale cooperatives and expedited regulatory approval pathways for biological formulations.
Among multinational conglomerates, BASF SE anchors positions in acid-based formulations through its microbial platform capabilities. Lallemand, Inc. exemplifies the fermentation technology specialist archetype with sustained research intensity in enzyme-based additives. Corteva Agriscience occupies the agricultural distribution scale position, leveraging extensive retail networks across Argentina and southern Brazil. These three companies represent divergent strategic approaches to capturing share in a market where cooperative procurement centralization is displacing traditional channel structures.
| Leading Market Players |
|---|
| BASF SE |
| Lallemand, Inc. |
| Corteva Agriscience |
| ADM |
| Kemin Industries |
| EW Group |
| Chr. Hansen Holding A/S |
| DuPont |
| Novonesis |
| Others |
Value Network & Pricing Analysis
Import dependency for specialized microbial fermentation cultures determines both the premium-to-economy pricing spread across Brazilian and Argentine additive tiers and the cold-chain infrastructure investments required to maintain inoculant viability through tropical distribution networks.
Pricing Analysis
Cost-plus contracts indexed to European fermentation culture spot prices dominate procurement between Brazilian dairy cooperatives and domestic formulators. Three-tier pricing structure across premium biological inoculants, standard acid-based formulations, and economy chemical preservatives reflects MAPA registration tier and guaranteed dry matter recovery rates. Pricing pressure stems from Argentine ranchers substituting sugar-based additives for biological formulations during cattle price downturns. Beef cattle operators in Paraguay and Uruguay exhibit the highest price elasticity, while Brazilian southeastern dairy cooperatives absorb premium tiers through volume-guaranteed offtake agreements.
Supply Chain Analysis
Upstream feedstock for microbial inoculants draws from specialized fermentation facilities in Germany, the Netherlands, and the United States, with Brazilian distributors maintaining six-month inventory buffers to offset trans-Atlantic lead times. Active ingredient inputs center on Lactobacillus buchneri and Pediococcus pentosaceus strains, cellulase enzyme blends, and propionic acid derivatives. Single-source vulnerability concentrates in European culture suppliers, where any regulatory restriction on biological exports would disrupt Brazilian formulation capacity. Distribution runs through agricultural cooperatives in Minas Gerais and São Paulo, with direct manufacturer relationships displacing traditional retail intermediaries in Paraná's consolidated dairy belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American silage additive procurement is approaching a platform-economics inflection as digital agronomy applications enable direct-to-farmer channels that bypass established agricultural retail networks and reshape cooperative tender specifications.
For Market Incumbents: Insulate cooperative relationships by embedding technical advisory functions within Paraná and Santa Catarina procurement committees, while accelerating backward integration into captive fermentation capacity to offset European culture supply risk. Cold-chain infrastructure investments in Brazil's northeastern distribution corridors defend margin position against emerging domestic formulators with ambient-stable powdered alternatives. For New Entrants and Emerging Players: Build out digital agronomy platforms targeting Chile's Los Lagos smallholder dairy producers, where tablet-form pre-measured doses and mobile fermentation monitoring create white-space penetration before cooperative consolidation reaches southern markets. Underpenetrated equine and small ruminant applications in Uruguay's Tacuarembó region offer secondary expansion with specialized formulation protocols. For Investors and Strategic Acquirers: Regional distributors with SENASA registration expertise and established Argentine provincial coverage represent the most defensible acquisition archetype as regulatory approval timelines compress and European suppliers seek compliant market entry vehicles. Watch for MAPA expedited review pathway announcements as the inflection signal indicating domestic manufacturer consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Lactobacillus culture production insulates Brazilian formulators from European supply concentration risk. |
| Direct-to-Farmer Digital Platform Launch | Mobile agronomy applications bypass agricultural retail markups in Chile's fragmented dairy belt. |
| MAPA Registration Acceleration Investment | Expedited approval pathways compress domestic manufacturer competitive moats against European entrants. |
| Enzyme-Based Additive Manufacturing Scale-Up | Cellulase blend capacity expansion targets Paraná cooperative demand for tropical grass digestibility improvement. |
| Cold-Chain Infrastructure Partnership | Temperature-controlled distribution networks maintain inoculant viability through Brazil's high-humidity supply corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy cooperative procurement directors, agricultural retail channel managers, MAPA regulatory affairs specialists, and fermentation technology R&D leads at domestic and multinational formulators. Secondary validation drew from MAPA feed additive registration databases, SENASA veterinary product filings, Brazilian agricultural cooperative financial disclosures, and Mercosur harmonization working papers. Bottom-up volume estimates from state-level silage production statistics were triangulated against top-down additive consumption projections derived from dairy herd expansion models.
Calibration against historical MAPA approval timelines and cooperative procurement tender patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, livestock application, formulation form, and distribution channel concentration, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from trend extrapolation of enzyme-based additive penetration rates and cooperative procurement centralization indices, incorporating dairy feed cost sensitivity and biological inoculant efficacy validation cycles as forecast inputs.
Sensitivities concentrate around Mercosur regulatory harmonization progress, European microbial culture export restrictions, and Brazilian cooperative merger activity that could accelerate or delay direct manufacturer relationship formation. Cross-checking against Brazilian dairy sector feed cost benchmarks and Argentine cattle price cycles is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Agricultural Antibacterials Market