
 Canada Bamboos Market | 2026-2036
Canada Bamboos Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Bamboos Market Insights
Market Context
Canada is narrowing its reliance on imported bamboo products through domestic distribution partnerships and regional warehousing expansion. Greenington leverages its North American supply chain to serve Canadian retailers with finished flooring and furniture components. MOSO International anchors European-engineered bamboo imports into Vancouver and Toronto distribution channels. Smith & Fong Company specializes in plywood and veneer products targeting Canadian architectural specification markets.
Technical Definition and Segment Structure
Bamboos are perennial evergreen grasses in the subfamily Bambusoideae, characterized by rapid culm growth rates reaching maturity within three to five years and tensile strength comparable to steel by weight, making them suitable for structural composites, textile fibers, and activated carbon production. Engineered bamboo dominates Canadian commercial procurement due to dimensional stability and moisture resistance required in climate-variable construction zones. Natural bamboo poles sustain demand in furniture and decorative applications where aesthetic grain visibility commands premium positioning.
Regulatory Framework and Outlook
Health Canada and the Canadian Wood Council establish product safety and performance benchmarks for interior finish materials, while the Canadian Standards Association certifies structural bamboo composites under CSA O86 engineering standards. The Competition Bureau monitors environmental marketing claims under greenwashing enforcement guidelines, pressuring suppliers to substantiate sustainability credentials. Stakeholders must track evolving federal procurement policies favoring low-carbon building materials and provincial carbon accounting rules affecting embodied emissions in construction supply chains.
Market Dynamics
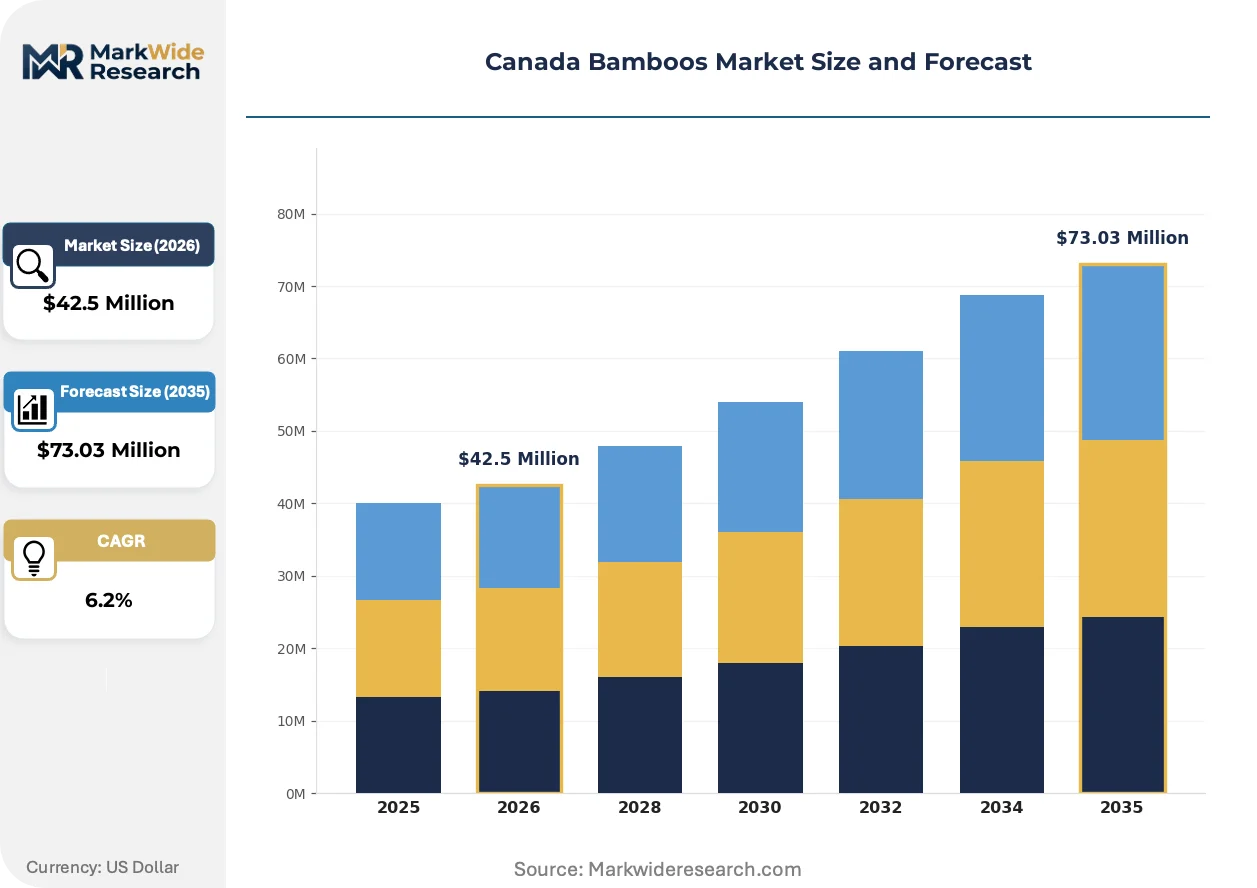
Canada's bamboo market is compressing supply chains through regional warehousing expansion while Health Canada's greenwashing enforcement tightens substantiation requirements for sustainability claims.
Growth Catalysts
- CSA O86 Engineering Standards:Structural certification for bamboo composites unlocks commercial construction procurement in climate-variable zones across British Columbia and Quebec.
- Low-Carbon Federal Procurement Policies:Embodied carbon accounting rules favor bamboo as a hardwood alternative in government building projects.
- Cross-Laminated Timber Integration:Hybrid engineered bamboo-wood panels gain specification traction among Canadian architectural firms seeking material diversification.
Market Restraints
- Import Dependency Concentration:European-engineered bamboo flows through Vancouver and Toronto distribution channels create single-point vulnerability.
- Moisture Resistance Limitations:Natural bamboo poles face dimensional instability in Canadian freeze-thaw cycles, restricting exterior structural applications.
- Competition Bureau Scrutiny:Environmental marketing claim enforcement raises compliance costs for sustainability credential verification.
Strategic Opportunities
- Alberta and Prairie Provinces:Underpenetrated residential markets offer flooring and panel expansion beyond British Columbia and Quebec concentration.
- Provincial Carbon Accounting Rules:Evolving construction emission tracking creates preference tailwinds for bamboo's lower embodied carbon profile.
- Direct-to-Specifier Digital Platforms:Architectural specification bypass of traditional distribution accelerates material selection for commercial projects.
Industry Challenges
- CSA Certification Timeline:Structural product approval cycles delay market entry for innovative engineered bamboo formats.
- Specialized Installation Labor:Shortage of certified installers for engineered bamboo flooring constrains residential rollout velocity.
- Legacy Hardwood Specification Inertia:Architect and builder familiarity with oak and maple slows material substitution in premium projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Bamboos Market |
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $73.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Bamboo, Engineered Bamboo, Bamboo Charcoal, Bamboo Fibers End Use Industry: Construction, Furniture, Paper, Textile Form: Poles, Sheets, Planks, Strips Grade: High-Grade, Medium-Grade, Low-Grade, Specialty Grade |
| Companies Covered | Greenington, dasso, MOSO International, Xiamen Yihong Bamboo Products Co., Bamboo Flooring China, Smith & Fong Company, Simply Bamboo, Bumboo, Bamboo Village, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Bamboos Market Trends and Innovations
Digital specification tools and hybrid material engineering are compressing traditional procurement cycles while regulatory pressure on embodied carbon accelerates material substitution.
Cross-laminated bamboo (CLB) is virtualizing structural panel procurement for mid-rise commercial construction. Canadian architectural firms specify CLB floor and roof systems at expanding rates. The technology is virtualizing project timelines by reducing on-site assembly labor and enabling prefabrication workflows.
Health Canada's greenwashing enforcement guidelines tighten substantiation requirements for environmental marketing claims. Suppliers must document lifecycle carbon data and chain-of-custody certification. Engineered bamboo importers face elevated compliance investment to maintain retail and specification channel access.
Specification-driven procurement now dominates commercial and institutional segments. Architects and sustainability consultants displace general contractors as primary material gatekeepers. British Columbia multi-family residential and Toronto commercial office projects exhibit the strongest specification-led bamboo adoption patterns.
Canada Bamboos Market Segmentation
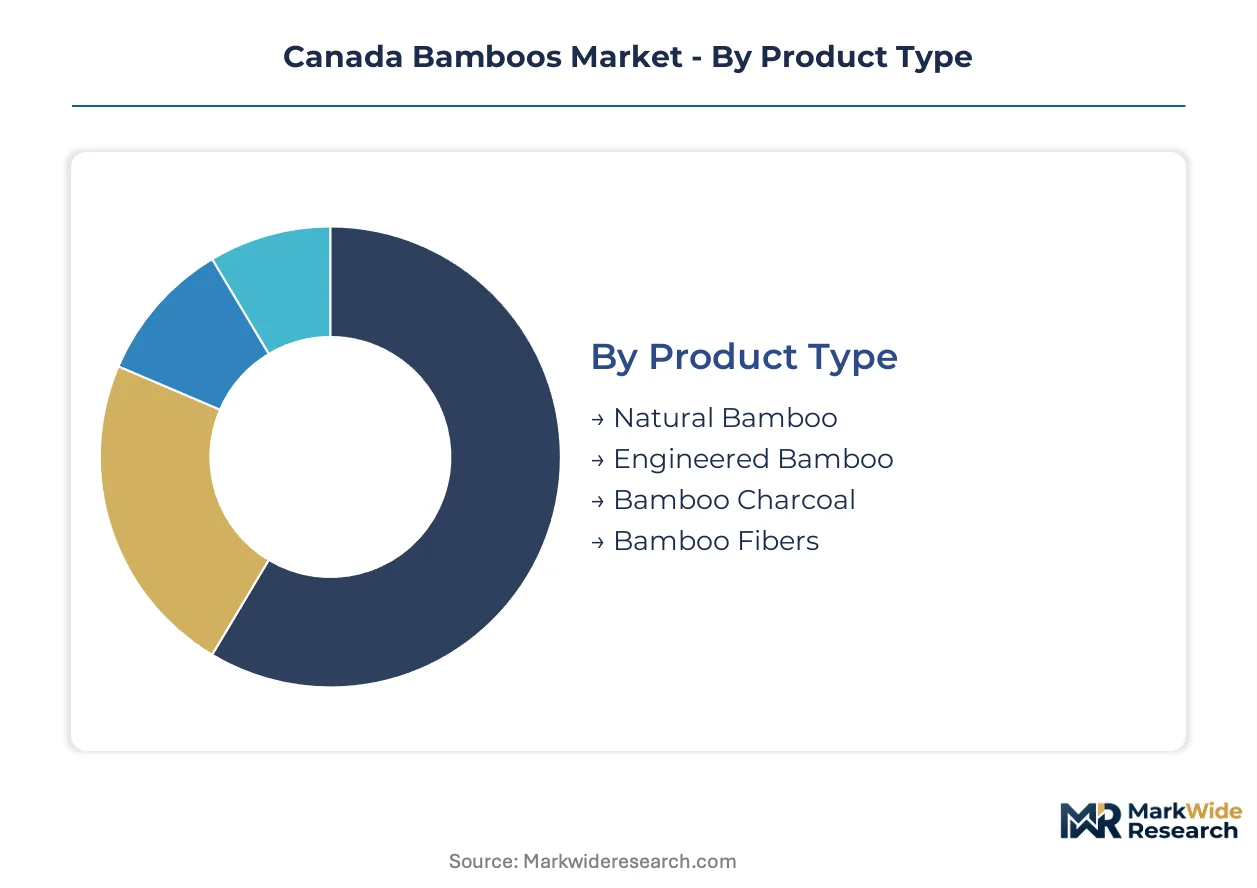
Canada's bamboo market segments reflect divergent procurement cycles, with engineered materials commanding multi-year specification timelines while raw poles turn over rapidly through retail channels. Understanding these velocity differences shapes inventory positioning and customer engagement strategies for suppliers.
Product Type:
Cycle times vary dramatically across product types, with processed materials requiring extended certification periods versus raw commodities that move through distribution within weeks.
- Engineered Bamboo:Cross-laminated and strand-woven composites deliver dimensional stability for flooring and structural panels. Demand concentrates in Vancouver and Toronto commercial construction, where CSA O86 certification unlocks specification access for mid-rise projects.
- Natural Bamboo:Raw culms and split poles serve furniture makers and decorative installers. Quebec residential renovators drive procurement through big-box retail channels, though freeze-thaw vulnerability limits exterior structural use.
- Bamboo Charcoal:Activated carbon products target air purification and water filtration applications. Health Canada PMRA registration requirements govern import and distribution.
- Bamboo Fibers:Textile-grade pulp feeds specialty paper and fabric production. British Columbia eco-apparel manufacturers represent the primary offtake channel.
Engineered bamboo dominates installed base. Bamboo fibers is where expansion concentrates.
End Use Industry:
Cost tiers separate these segments, with construction commanding premium pricing for certified structural materials versus commoditized paper and textile applications.
- Construction:Commercial and institutional builders specify engineered bamboo for flooring, cladding, and hybrid timber systems. Federal procurement policies favoring low-carbon materials accelerate substitution against hardwood and steel in British Columbia and Quebec government projects.
- Furniture:Residential and hospitality manufacturers source poles and veneer for tables, seating, and cabinetry. Toronto and Montreal design studios prize aesthetic grain visibility for premium positioning.
- Paper:Pulp mills blend bamboo fiber with wood pulp for specialty packaging and printing grades. Cost competition with recycled content constrains volume growth.
- Textile:Apparel brands weave bamboo-derived rayon for activewear and base layers. Alberta and Saskatchewan retailers expand distribution beyond coastal concentration.
Construction commands the premium tier. Furniture offers the steepest expansion trajectory.
Form:
Volume concentration favors standardized formats that integrate with existing fabrication equipment and installation workflows.
- Planks:Tongue-and-groove flooring boards and panel substrates constitute the highest-volume format. Toronto distribution centers stock engineered planks for same-day contractor pickup.
- Sheets:Plywood and veneer panels serve architectural millwork and commercial interior applications. Quebec cabinet shops specify cross-laminated sheet goods for moisture-resistant casework.
- Poles:Whole and split culms supply furniture frames and decorative structural elements. British Columbia landscape architects specify treated poles for interior atrium installations.
- Strips:Narrow dimensional pieces feed parquet flooring and craft manufacturing. Limited standardization constrains scale.
Planks anchor volume throughput. Sheets is where specification value concentrates.
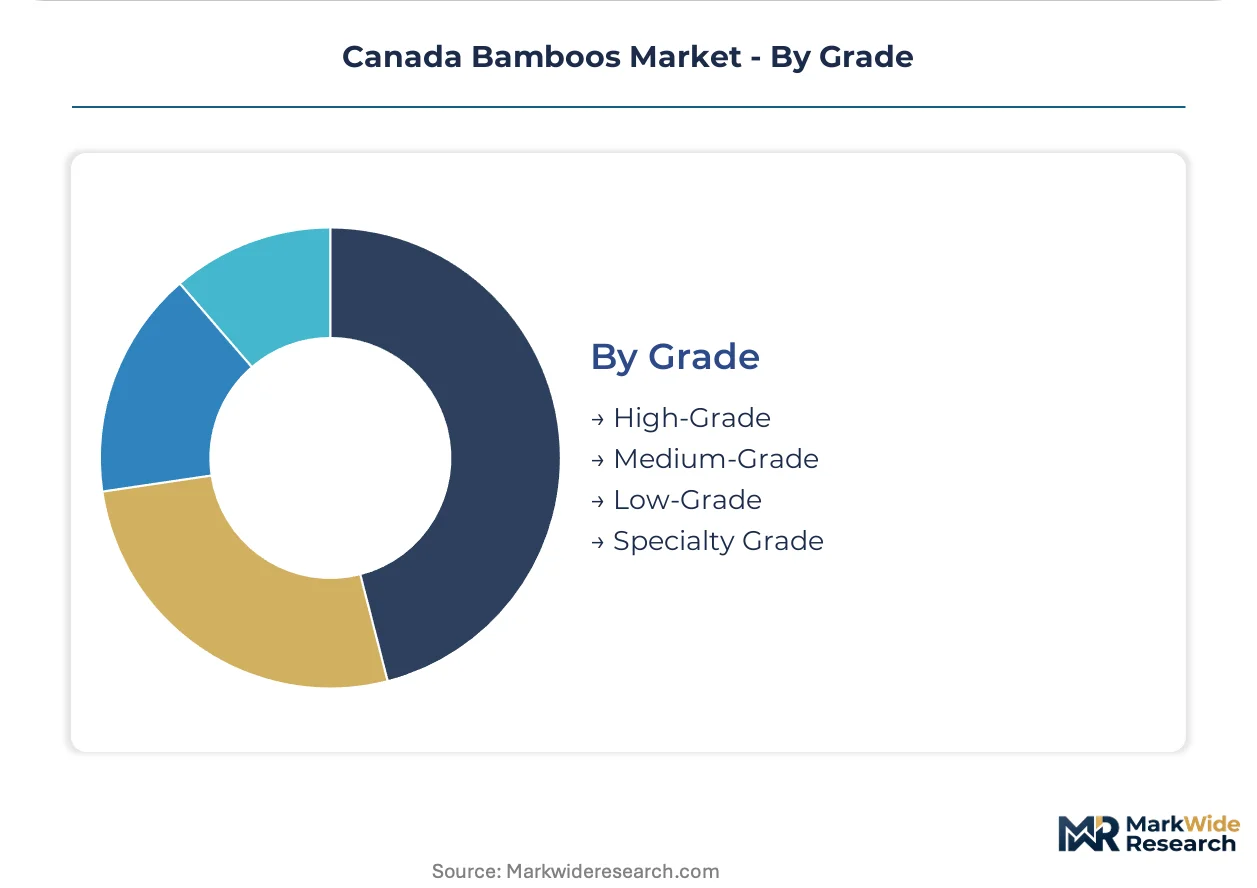
Grade:
Margin structure stratifies sharply across grades, with specialty and high-grade products capturing value through certification and aesthetic differentiation.
- High-Grade:Select culms with uniform density and minimal visual defects command specification in premium architectural projects. Toronto and Vancouver commercial offices specify high-grade veneer for reception and boardroom finishes.
- Specialty Grade:Custom-engineered composites with enhanced fire resistance or acoustic properties target institutional buyers. Canadian Wood Council certification programs validate performance claims for healthcare and education procurement.
- Medium-Grade:Standard commercial flooring and panel materials balance cost and performance. Big-box retailers stock medium-grade engineered products for residential renovation.
- Low-Grade:Utility poles and industrial fiber feedstock serve cost-sensitive applications. Paper mills and charcoal producers absorb volume with minimal quality requirements.
High-Grade dominates specification value. Specialty Grade is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian bamboo distribution concentrates in coastal gateway cities where import infrastructure and specification-grade architectural demand intersect. Provincial carbon accounting frameworks and federal procurement policies create divergent adoption velocities across sub-regional markets.
British Columbia
Vancouver commercial builders specify engineered bamboo flooring and hybrid timber systems for mid-rise residential and office projects. The province's carbon-neutral government building mandate accelerates material substitution against traditional hardwoods. Local architectural firms in the Lower Mainland specify cross-laminated bamboo panels for institutional clients seeking embodied carbon reductions.
Ontario
Toronto distribution centers stock engineered planks for same-day contractor pickup across the Greater Toronto Area. Federal procurement policies favoring low-carbon materials drive specification in Ottawa government building renovations. The province's evolving building code amendments create compliance pathways for structural bamboo composites in commercial construction.
Quebec
Montreal design studios prize natural bamboo poles and veneer for premium furniture and interior finish applications. The province's heritage building restoration sector sources specialty-grade materials through established European import channels. Quebec City residential renovators drive big-box retail procurement of medium-grade engineered flooring products.
Alberta
Calgary and Edmonton markets remain underpenetrated relative to coastal provinces, offering expansion runway for flooring and panel distributors. The province's energy sector office construction presents specification opportunities for sustainable interior materials. Local retailers are expanding bamboo textile and apparel distribution beyond traditional coastal concentration zones.
Canada Bamboos Market Competitive Landscape
North American supply chain specialists and European-engineered import anchors split the market into distinct procurement channels. The vendor base organizes around finished goods distribution versus raw material specification expertise. Three archetypes dominate: domestic warehousing and fulfillment operators, European manufacturing representatives with Canadian distribution rights, and Asian direct exporters serving price-sensitive retail segments. Competitive moves concentrate on regional warehousing expansion and digital specification platform development.
Among North American supply chain operators, Greenington leverages its established distribution infrastructure to serve Canadian retailers with finished flooring and furniture components. MOSO International anchors European-engineered bamboo imports into Vancouver and Toronto distribution channels, exemplifying the manufacturing-representative archetype. Smith & Fong Company occupies a position within the specification-grade materials tier, targeting Canadian architectural markets with plywood and veneer products.
| Leading Market Players |
|---|
| Greenington |
| dasso |
| MOSO International |
| Xiamen Yihong Bamboo Products Co. |
| Bamboo Flooring China |
| Smith & Fong Company |
| Simply Bamboo |
| Bumboo |
| Bamboo Village |
| Others |
Pricing and Supply Chain Analysis
Vancouver distribution clusters concentrate engineered bamboo inventory for cross-country fulfillment, creating pricing leverage for warehousing operators who capture margin through regional staging rather than manufacturing value-add. Health Canada's greenwashing enforcement and CSA certification requirements filter price-sensitive buyers toward documented supply chains, compressing spot-market alternatives.
Pricing Analysis
CSA O86 engineering standards dictate the pricing tier structure across structural and non-structural applications. Three-tier pricing structure across premium, standard, and economy levels separates certified cross-laminated panels from medium-grade flooring and utility fiber feedstock. Price differentiation centers on certification investment and grain uniformity. Cost compression in medium-grade engineered flooring is intensifying because big-box retailers negotiate volume commitments. Residential renovators exhibit highest price sensitivity; institutional specifiers show lowest.
Supply Chain Analysis
Extended payment terms from European manufacturing representatives ease working capital burdens for Canadian distributors managing long ocean freight cycles. Supply draws from China, Vietnam, and the Netherlands for raw poles, textile fiber, and engineered composites respectively. Raw material dependencies include Moso culm harvests, phenolic resins for strand-woven binding, and activated carbon feedstock. Single-source vulnerability concentrates in Vancouver and Toronto import channels. Distribution runs through specification-grade architectural representatives for commercial projects and retail warehousing for residential renovation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CSA structural certification unlocks mid-rise commercial construction procurement, transforming bamboo from decorative alternative to code-compliant structural material. Federal low-carbon procurement policies accelerate this inflection by embedding embodied carbon accounting into government project specifications.
For Market Incumbents: Pre-empt specification-channel displacement by securing CSA O86 pre-approval for next-generation cross-laminated formats before European competitors complete Canadian certification cycles. Backward integration into Vancouver warehousing capacity locks in distribution control against Asian direct exporters targeting price-sensitive retail tiers. Certification investment represents the critical defensive lever against hardwood specification inertia in premium architectural projects. For New Entrants and Emerging Players: Build out digital specification platforms that bypass traditional distribution and connect directly with British Columbia and Ontario architectural firms seeking material carbon data for client presentations. Alberta and Prairie Provinces offer the most penetrable geography, with underdeveloped engineered flooring distribution relative to coastal concentration. Lead with lifecycle carbon documentation to satisfy Health Canada substantiation requirements and differentiate against legacy hardwood suppliers lacking comparable environmental credentials. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specification-grade material distributors with multi-year architectural firm relationships and CSA certification maintenance contracts. Long-term viability hinges on federal procurement policy durability and provincial carbon accounting rule expansion beyond British Columbia. Acquisition target archetype: regional warehousing operators with established Vancouver or Toronto distribution infrastructure and existing CSA O86 product approvals. Watch for Competition Bureau greenwashing enforcement actions as signal of compliance-cost escalation that favors scaled players with dedicated certification resources.| Strategic Initiative | Industry Significance |
|---|---|
| CSA O86 Certification Investment | Unlocks structural specification access for mid-rise commercial projects in climate-variable zones. |
| Regional Warehousing Expansion | Compresses fulfillment timelines for Toronto and Vancouver contractor same-day pickup requirements. |
| Digital Specification Platform Development | Bypasses traditional distribution to connect engineered bamboo suppliers directly with architectural gatekeepers. |
| Lifecycle Carbon Documentation Systems | Satisfies Health Canada substantiation requirements for environmental marketing claims compliance. |
| Hybrid Timber-Bamboo Panel Engineering | Captures specification traction among Canadian firms seeking material diversification in cross-laminated systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Canadian Wood Council technical bulletins, Health Canada product safety databases, and provincial building code amendment records. Primary interviews engaged bamboo flooring distributors, architectural specification consultants, commercial contractors, and CSA certification engineers. Secondary validation drew from customs import records, federal procurement disclosure filings, and Canadian Standards Association engineering documentation. Bottom-up demand modeling triangulated against top-down construction sector material flow estimates.
Forecast inputs span product type segmentation across engineered, natural, charcoal, and fiber grades; end-use industry disaggregation between construction, furniture, paper, and textile applications; and form-factor analysis of planks, sheets, poles, and strips. CAGRs derive from regression analysis against construction sector output indices and federal green procurement policy implementation trajectories across the analysis window. Modeled variables include embodied carbon accounting rule adoption velocity and CSA certification timeline compression.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian direct exporters or European manufacturing representatives would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Middle East Animal Protein Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Algae-Based Animal Feed Market