
 Poultry Fat Market | 2026-2036
Poultry Fat Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Fat Market Insights
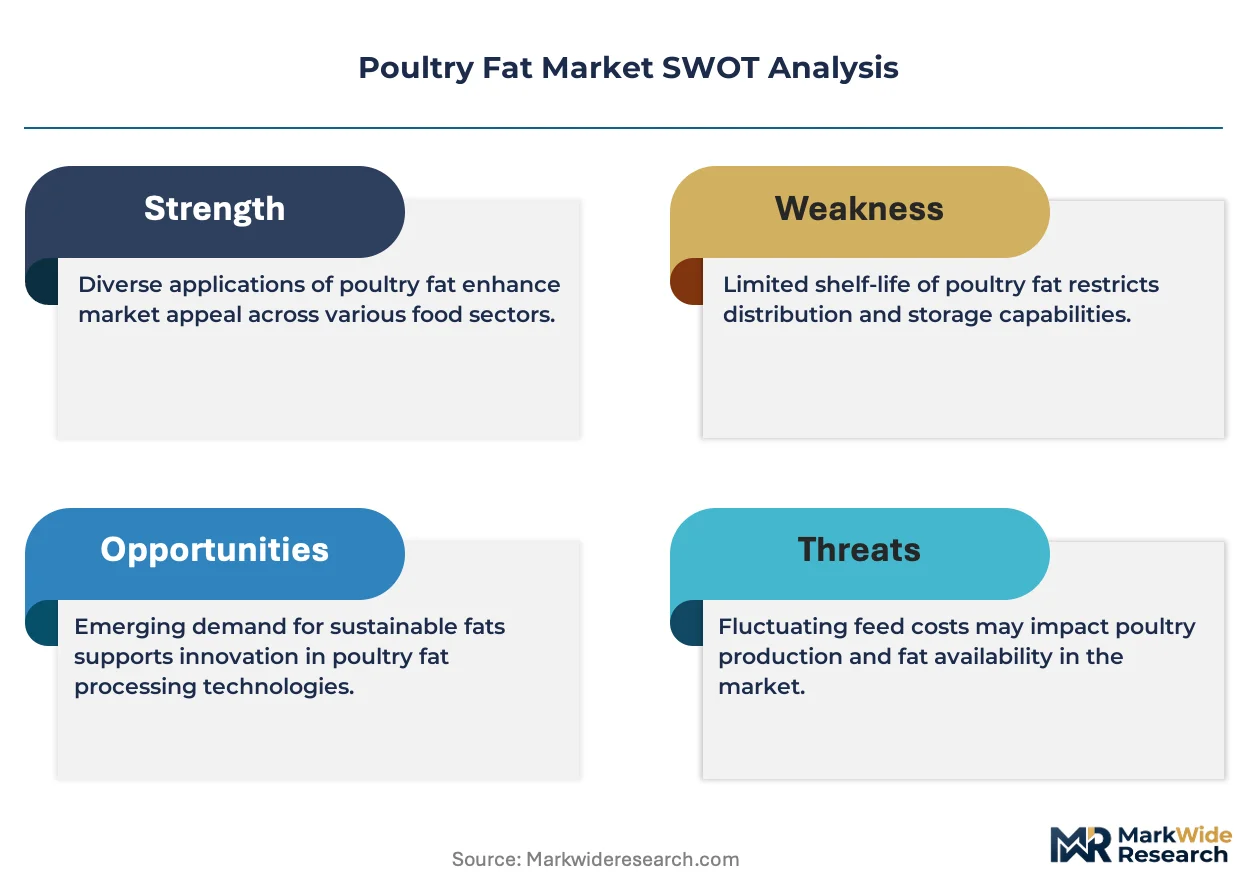
Modular fat blending and custom emulsion packaging is realigning how pet food producers and bakeries configure procurement contracts. Tyson Foods leverages vertical integration from slaughter to rendering, securing captive supply chains across the US Southeast. Darling Ingredients specializes in multi-species rendering infrastructure, converting by-product streams into standardized feed-grade outputs. Perdue Farms anchors its position through brand strength in food-grade poultry oil, targeting food manufacturers with certified kosher and halal lines.
Poultry fat comprises triglycerides extracted from chicken and turkey tissue through wet or dry rendering at temperatures between 115°C and 140°C, yielding a yellow lipid with a melting point near 30°C and a fatty acid profile dominated by oleic, linoleic, and palmitic acids. Rendered fat occupies the largest volume share, serving industrial food processing and animal feed compounding with consistent oxidative stability. Poultry oil competes in premium food-grade segments where lower free fatty acid content commands price premiums from bakeries and food manufacturers. Emulsified fat represents the fastest-growing configuration, as pet food producers demand homogeneous lipid distribution in extruded kibble and wet food matrices.
The US FDA enforces BSE feed regulations that restrict ruminant protein in rendering, while the EPA monitors wastewater and air emissions from thermal processing facilities, collectively raising compliance thresholds for market entry. Brazil's ANVISA and the EU's EFSA maintain divergent maximum residue limits for dioxins and PCBs in animal fats, fragmenting export qualification requirements. Feed-grade specifications from the Association of American Feed Control Officials further stratify product tiers, pressuring non-integrated renderers to invest in laboratory certification or exit higher-margin channels. Stakeholders must monitor evolving renewable fuel mandates, as biofuel qualification pathways for poultry-derived lipids remain contested between ASTM biodiesel standards and emerging sustainable aviation fuel protocols.
Market Dynamics
Integrated poultry processors in Brazil and the US Southeast are consolidating rendering capacity, locking in captive fat supplies and forcing independent renderers to absorb higher compliance costs or exit feed-grade channels entirely.
Growth Catalysts
- Sustainable Aviation Fuel Mandates:ASTM International and emerging SAF protocols are creating qualification pathways for poultry-derived lipids, opening fuel-grade offtake contracts previously reserved for vegetable oils.
- Pet Food Premiumization:Pet food producers are expanding poultry fat inclusion in extruded kibble and wet food matrices, driving demand for emulsified fat configurations with homogeneous lipid distribution.
- Brazil's Integrated Model:Brazilian poultry processors command captive fat supply chains from slaughter through rendering, securing volume commitments that stabilize processor margins.
Market Restraints
- FDA and EPA Compliance Costs:BSE feed regulations and thermal processing emissions monitoring raise fixed-cost thresholds for rendering facility upgrades, squeezing smaller operators.
- Divergent Residue Limits:ANVISA, EFSA, and FDA maintain non-aligned maximum thresholds for dioxins and PCBs in animal fats, fragmenting export qualification requirements and multiplying testing burdens.
- Vegetable Oil Substitution:Rapeseed and soybean oil price volatility creates intermittent substitution pressure in industrial food processing, compressing poultry fat price premiums during oil gluts.
Strategic Opportunities
- Modular Fat Blending Services:Custom emulsion packaging for bakeries and pet food producers is realigning procurement contracts toward specification-based rather than commodity-based purchasing.
- Kosher and Halal Certification:Food-grade poultry oil with religious certification commands price premiums from food manufacturers serving demographic markets in the US and Europe.
- Renewable Fuel Incentives:US Inflation Reduction Act credits for advanced biofuels are accelerating renderers' investments in lipid upgrading for fuel-grade qualification.
Industry Challenges
- Laboratory Certification Timelines:AAFCO feed-grade specifications and multi-jurisdiction residue testing require 12-18 month validation cycles, delaying market entry for new rendering facilities.
- Rendering Technology Retrofits:Wet-to-dry rendering conversions and emissions control installations demand capital deployment that stretches payback periods for mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Fat Market |
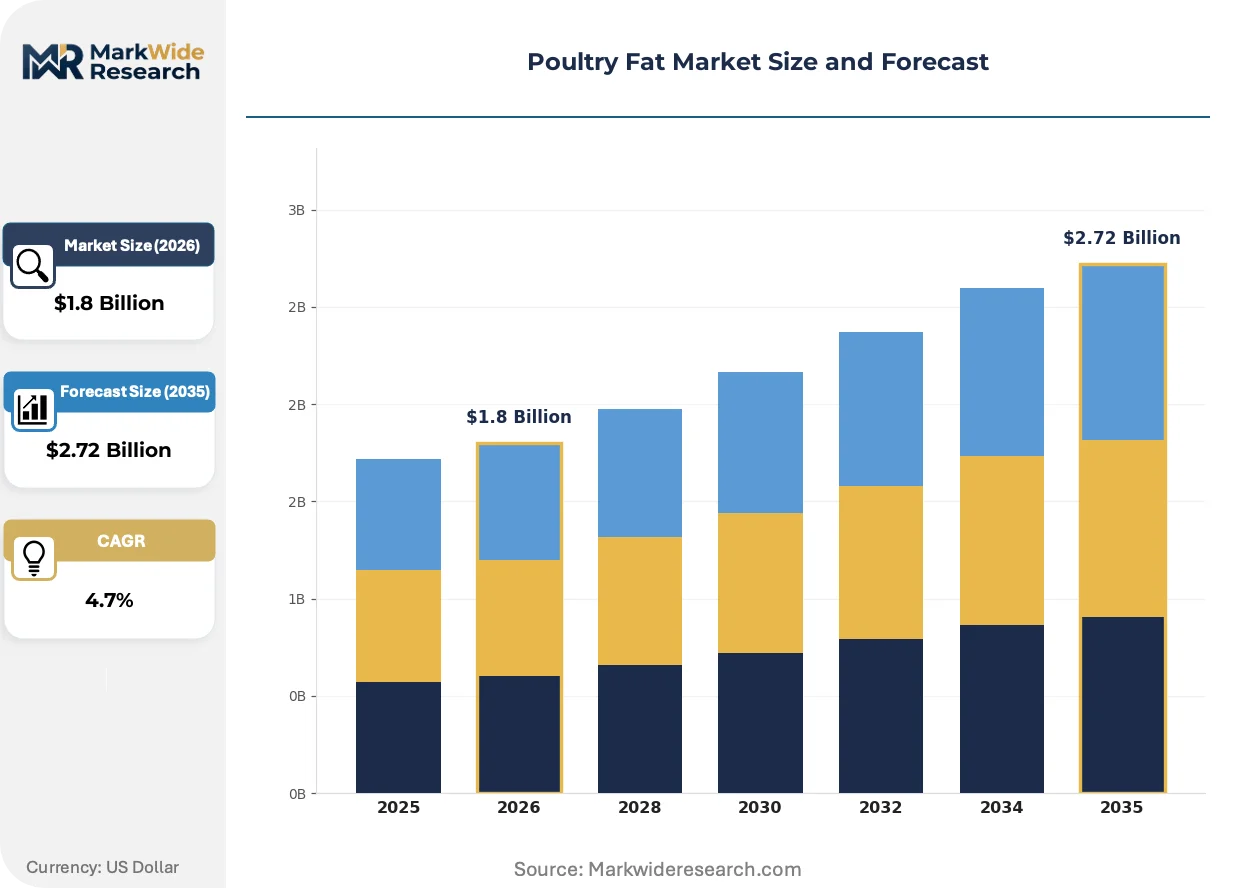
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rendered Fat, Poultry Oil, Emulsified Fat, By-Product Fat Application: Food Processing, Animal Feed, Cookware, Biofuel Distribution Channel: Wholesale, Retail, Direct Sales, Online Sales End User: Food Manufacturers, Bakeries, Restaurants, Pet Food Producers |
| Companies Covered | Perdue Farms, Maple Leaf Foods, Tyson Foods, Valley Proteins, Essex Food Ingredients, Pilgrim's Pride Corporation, Wayne Farms, Darling Ingredients, JBS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Fat Market Trends and Innovations
Automation of rendering processes and modular processing units are compressing batch cycle times while regulatory divergence is forcing multi-jurisdiction certification strategies. Demand-side procurement is fragmenting toward specification-driven contracts.
Continuous rendering systems with automated temperature control and real-time free fatty acid monitoring are automating quality consistency previously dependent on operator judgment. Pet food manufacturers adopting these systems are reducing specification rejection rates and compressing supplier qualification timelines from months to weeks. This automation is enabling smaller renderers to compete on consistency metrics previously dominated by integrated processors.
The EU's F-Gas Regulation and REACH chemical safety frameworks are tightening emissions and substance restrictions on thermal processing facilities, forcing European renderers to invest in closed-loop solvent recovery and alternative extraction chemistries. Industrial food processors sourcing from EU rendering facilities are demanding chain-of-custody documentation that traces lipid batches to specific slaughter and rendering sites. This regulatory pressure is segmenting the European supply base into compliance-certified and commodity-tier suppliers.
Pet food producers and industrial bakeries are abandoning long-term volume contracts in favor of specification-based spot purchasing with modular blending requirements. This procurement fragmentation is displacing traditional rendering offtake agreements and forcing suppliers to maintain flexible emulsion and packaging configurations. The shift is most visible in the US Southeast, where Tyson Foods' integrated rendering capacity competes with independent processors offering custom fat blends with 48-hour turnaround.
Poultry Fat Market Segmentation
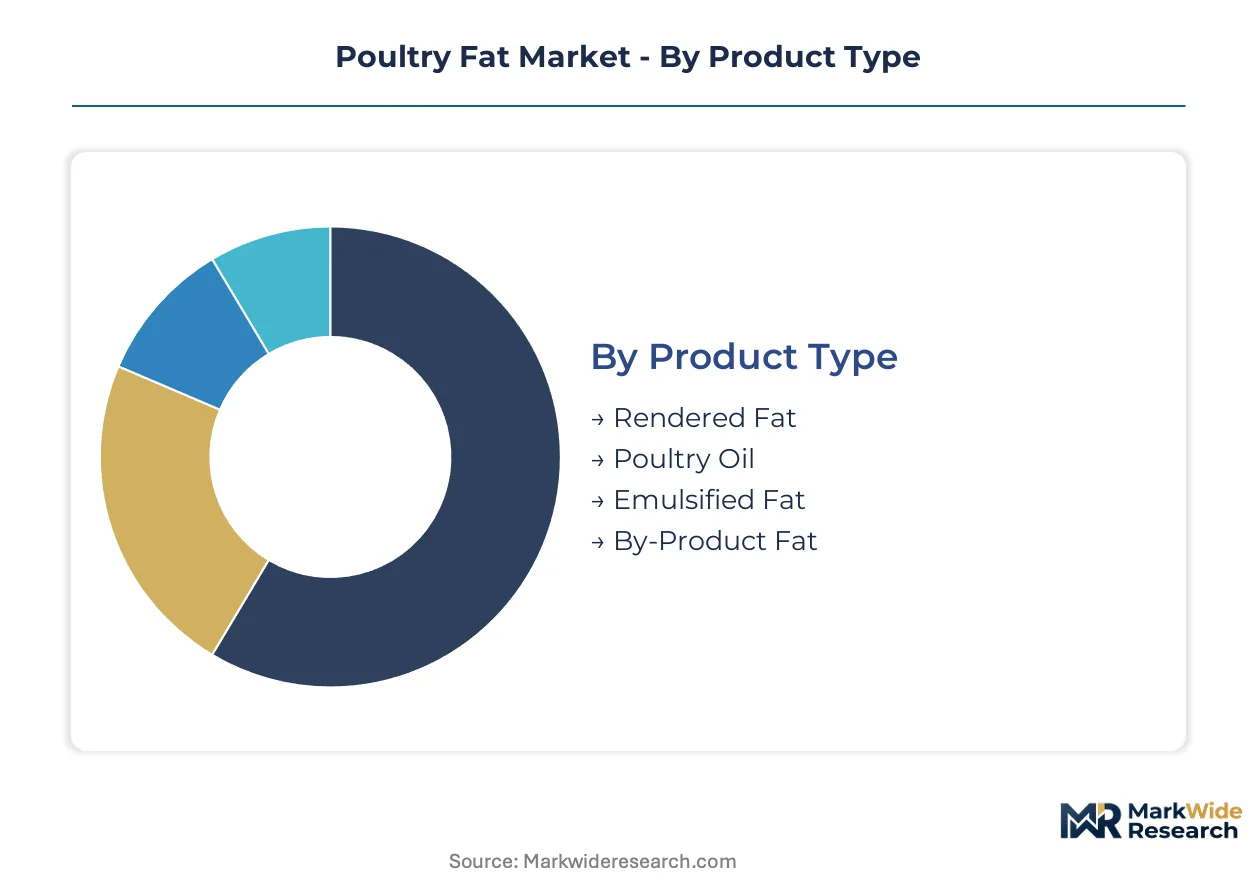
Poultry fat segmentation reflects divergent processing intensities and certification thresholds that separate commodity feed-grade streams from premium food-grade outputs. Specification requirements from end-users are fragmenting procurement patterns across temperature stability, free fatty acid content, and emulsion homogeneity.
Product Type:
Temperature control and extraction chemistry differentiate product tiers across wet and dry rendering protocols.
- Rendered Fat:Extracted through thermal processing at 115°C to 140°C, this yellow lipid delivers consistent oxidative stability for industrial food processing and bulk feed compounding. Demand concentrates in Brazil's integrated poultry processors, where captive rendering infrastructure locks in volume supply chains.
- Poultry Oil:Refined to lower free fatty acid specifications, this premium-grade output targets bakeries and food manufacturers seeking kosher and halal certification compliance. US Southeast processors leverage brand strength to command price premiums from demographic markets.
- Emulsified Fat:Homogeneous lipid distribution in extruded matrices is expanding most quickly as pet food producers abandon commodity purchasing for specification-driven contracts.
- By-Product Fat:Recovered from feather meal and offal processing streams, this lower-tier output serves cost-sensitive feed channels with minimal refinement.
Mature deployment sits with Rendered Fat. Newer deployment is concentrated in Emulsified Fat.
Application:
End-use specifications range from human food safety thresholds to ASTM fuel qualification protocols.
- Food Processing:Industrial bakeries and snack manufacturers demand consistent melting points near 30°C and fatty acid profiles dominated by oleic, linoleic, and palmitic acids. US FDA BSE feed regulations and EPA emissions monitoring raise compliance costs for suppliers targeting this channel.
- Animal Feed:AAFCO feed-grade specifications stratify product tiers, pressuring non-integrated renderers to invest in laboratory certification or exit higher-margin channels entirely.
- Cookware:High smoke point requirements from restaurant chains drive demand for clarified poultry oil with minimal moisture content.
- Biofuel:ASTM International and emerging sustainable aviation fuel protocols are creating contested qualification pathways for poultry-derived lipids.
Volume concentration remains in Food Processing. Specification complexity is climbing fastest in Biofuel.
Distribution Channel:
Procurement fragmentation is displacing traditional offtake agreements across all channel configurations.
- Wholesale:Bulk tanker shipments dominate industrial feed and food manufacturing procurement, with 48-hour turnaround contracts replacing annual volume commitments.
- Retail:Packaged poultry fat for consumer cookware applications remains a niche channel concentrated in specialty grocers.
- Direct Sales:Integrated processors like Tyson Foods leverage captive supply chains to bypass intermediary margins.
- Online Sales:Custom emulsion packaging for small-batch pet food producers is gaining traction through specification-based digital procurement platforms.
Contract stability sits with Wholesale. Channel experimentation is concentrated in Online Sales.
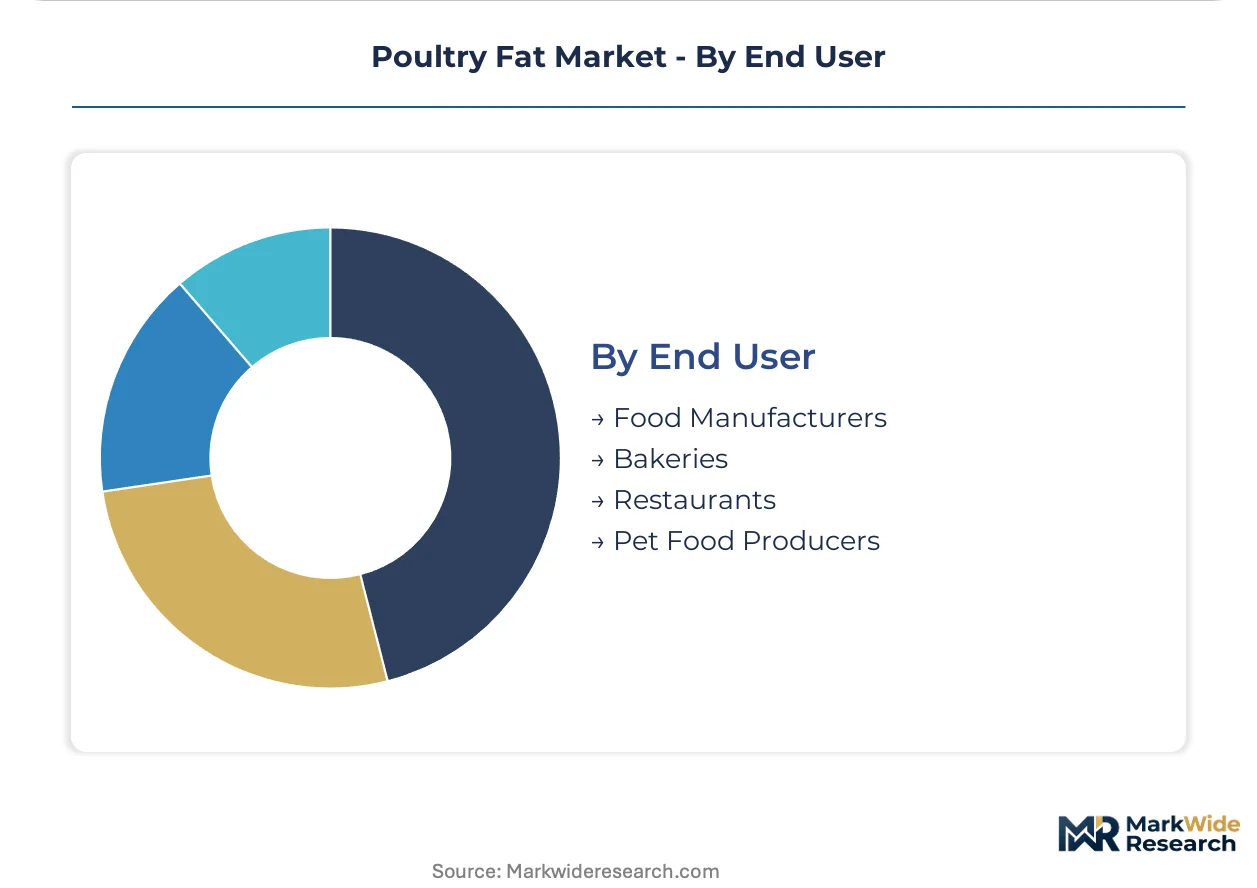
End User:
Religious certification and emulsion homogeneity are splitting demand patterns across user categories.
- Food Manufacturers:Kosher and halal certification commands price premiums from processors serving US and European demographic markets.
- Bakeries:Consistent oxidative stability and low free fatty acid content drive specification rejection rates that compress supplier qualification timelines.
- Restaurants:High-volume frying applications prioritize smoke point performance and cost efficiency over certification tiers.
- Pet Food Producers:Modular fat blending with homogeneous lipid distribution is realigning procurement toward specification-based purchasing with 48-hour turnaround requirements.
Procurement maturity sits with Food Manufacturers. Contract restructuring is concentrated in Pet Food Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and the United States generate surplus poultry fat volumes that exceed domestic absorption, while European and Asian markets rely on imports to bridge supply gaps. This production-consumption divide shapes trade flows and regulatory arbitrage strategies across the value chain.
Brazil
Integrated processors in São Paulo and Paraná command captive rendering infrastructure from slaughter through finished fat output. ANVISA maintains residue limits for dioxins and PCBs that diverge from EFSA thresholds, forcing exporters to maintain dual certification protocols. The southern cluster around Chapecó anchors volume production for both domestic feed compounding and Asian export markets.
United States
Southeastern processing corridors in Georgia and Alabama concentrate rendering capacity tied to poultry slaughter volumes. FDA BSE feed regulations and EPA emissions monitoring raise fixed-cost thresholds that squeeze independent operators. Tyson Foods leverages backward integration across this region to lock in captive fat supplies for food-grade and feed-grade channels.
China
Provincial processors in Shandong and Guangdong are expanding rendering capacity to absorb domestic poultry slaughter by-product streams. SAMR and GB standards for food-grade animal fats are tightening certification requirements for bakeries and snack manufacturers. The Yangtze River Delta cluster is experimenting with emulsified fat configurations for pet food producers.
Germany
Specialized renderers in Lower Saxony and North Rhine-Westphalia serve food manufacturers with kosher and halal certified poultry oil. ECHA REACH frameworks and the EU F-Gas Regulation impose solvent recovery and emissions control investments that segment the supply base. The Cologne-Düsseldorf corridor concentrates premium-grade output for industrial bakery chains.
Netherlands
Rotterdam and Eindhoven-based processors function as trade intermediaries connecting Brazilian surplus to European food and feed channels. EFSA maximum residue limits for contaminants in animal fats require laboratory validation cycles that delay new supplier qualification. The Randstad logistics hub enables 48-hour turnaround contracts for specification-based procurement.
Poultry Fat Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: integrated poultry processors with captive rendering assets, multi-species rendering specialists converting heterogeneous by-product streams, and independent processors offering modular blending services. Consolidation pressure is accelerating through backward integration into slaughter operations and capacity expansion in high-growth emulsified fat configurations.
Among US-based integrated processors, Tyson Foods, Perdue Farms, and Pilgrim's Pride Corporation exemplify the captive supply chain archetype, leveraging in-house rendering to control fat quality from slaughter through finished output. Darling Ingredients occupies a distinct position as a multi-species rendering specialist, converting diverse animal by-product streams into standardized feed-grade and fuel-grade lipids. These three entities represent the dominant competitive vectors shaping procurement relationships with pet food manufacturers and industrial bakeries.
| Leading Market Players |
|---|
| Perdue Farms |
| Maple Leaf Foods |
| Tyson Foods |
| Valley Proteins |
| Essex Food Ingredients |
| Pilgrim's Pride Corporation |
| Wayne Farms |
| Darling Ingredients |
| JBS |
| Others |
Pricing and Supply Chain Analysis
Pet food producers concentrating procurement decisions in the US Southeast and Brazil drive contract-based long-term offtake pricing with 48-hour turnaround clauses. This buyer concentration forces suppliers to absorb certification costs or exit feed-grade channels entirely.
Pricing Analysis
Margin tightening in feed-grade tiers reflects EPA emissions compliance investments and AAFCO laboratory certification timelines. Three-tier pricing structure across premium, standard, and economy levels separates kosher-certified food-grade oil from feed-grade rendered fat and unrefined by-product streams. Price differentiation hinges on free fatty acid thresholds and emulsion homogeneity specifications. Smaller renderers face acute price sensitivity as integrated processors like Tyson Foods leverage captive supply to undercut spot market bids.
Supply Chain Analysis
Dual-sourcing mandates from industrial bakeries and pet food manufacturers require qualification of Brazilian and US Southeast suppliers simultaneously. Raw material flows draw from Georgia and Alabama slaughter corridors, Paraná integrated processing clusters, and Lower Saxony specialty renderers. Single-source vulnerability concentrates in wet rendering capacity dependent on continuous poultry slaughter volumes. Distribution runs through Rotterdam trade intermediaries and bulk tanker networks serving feed compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The poultry fat market functions as a vertical-integration race where backward integration into rendering assets determines margin capture. Players securing captive slaughter-to-fat supply chains outcompete spot-market dependent rivals.
For Market Incumbents: Acquire wet-to-dry rendering conversion assets in the US Southeast to lock in EPA-compliant capacity before independent operators exit. Consolidate multi-species rendering infrastructure to diversify beyond poultry-dependent revenue streams. Vegetable oil substitution pressure in industrial food processing threatens price premiums during oil gluts. For New Entrants and Emerging Players: Launch via modular fat blending services targeting pet food producers abandoning commodity contracts for specification-based procurement. Penetrate the emulsified fat segment fastest-growing configuration with 48-hour turnaround capabilities. Digital procurement platforms enable direct qualification bypassing traditional distributor margins. For Investors and Strategic Acquirers: The window for entry favors mid-scale renderers with existing AAFCO certification and emissions control infrastructure already deployed. Long-term viability over a multi-year horizon rests on renewable fuel qualification pathways opening ASTM biodiesel and sustainable aviation fuel offtake contracts. Watch for EPA enforcement actions accelerating independent operator exits as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Tyson Foods' captive supply chains demonstrate margin protection against spot price volatility. |
| Modular Emulsion Packaging Investment | Custom fat blending capabilities attract pet food producers restructuring procurement contracts. |
| Renewable Fuel Qualification | ASTM biodiesel and SAF protocol alignment opens fuel-grade offtake previously reserved for vegetable oils. |
| Dual Certification Protocol | ANVISA and EFSA residue limit compliance enables Brazilian exporters to access European food manufacturers. |
| Continuous Rendering Automation | Real-time free fatty acid monitoring compresses supplier qualification timelines from months to weeks. |
Research Methodology
Document review covered FDA BSE feed regulations, EPA emissions monitoring guidelines, ANVISA residue limit protocols, and AAFCO feed-grade specifications, complemented by interviews with rendering plant managers, pet food procurement directors, industrial bakery supply chain leads, and Brazilian integrated processor executives. Secondary sources included customs and trade data, SEC 10-K filings from publicly traded protein processors, and EFSA contaminant threshold documentation. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, and end-user segments.
Cross-reference between historical price series and panel input from procurement officers anchored CAGR derivation across the analysis window. Segmentation dimensions modeled included rendering protocol, certification tier, distribution channel configuration, and regional regulatory cluster. Industry-specific forecast inputs incorporated poultry slaughter volume projections and renewable fuel mandate adoption curves.
The model assumes a particular technology adoption path for continuous rendering automation; alternative pathways for batch processing retention would alter the outlook for smaller operator competitiveness. Forecasts reflect assumptions regarding EPA enforcement consistency and ASTM biodiesel qualification timelines. Deviation in sustainable aviation fuel protocol finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Mushroom Substrate Market