
 Greenhouse Market | 2026-2036
Greenhouse Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse Market Intelligence
Climate control automation is fragmenting the traditional greenhouse technology stack into modular hardware-software bundles. Certhon leverages its Dutch engineering heritage to dominate high-complexity glass greenhouse installations across Europe. Netafim anchors precision irrigation technology leadership, while Priva B.V. competes through deep software integration with building management systems.
A greenhouse is an enclosed structure with transparent or semi-transparent covering materials—typically glass, polycarbonate panels, or polyethylene film—engineered to transmit solar radiation while trapping thermal energy, thereby creating a controlled microclimate for plant cultivation with regulated temperature, humidity, CO₂ concentration, and light exposure. Film greenhouses occupy the largest installed base globally due to lower capital requirements per hectare, while glass structures command premium margin pools in research-intensive and pharmaceutical crop applications. Hydroponic technology leads commercial expansion as water-scarce regions abandon soil-based systems, and aeroponics differentiates within high-value herb and pharmaceutical flower segments where root-zone oxygen precision determines active compound yields.
The EU Green Deal and F-Gas Regulation constrain synthetic refrigerant choices in climate-controlled operations, while the EPA's Clean Air Act standards shape American growers' heating technology procurement. BIS greenhouse structural standards in India affect import eligibility for foreign equipment suppliers. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting structure type and automation tier for new installations.
Market Dynamics
The greenhouse sector is contending with a structural pivot from passive solar structures to active climate-engineered environments, as energy costs and crop quality standards force growers to automate ventilation, lighting, and nutrient delivery systems rather than rely on manual intervention.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants accelerates adoption of CO₂ heat pumps and geothermal climate systems in Dutch and Spanish glasshouse operations.
- Hydroponic substrate innovation:Mineral wool and coconut coir replacements for peat-based media reduce water consumption per kilogram of tomato yield in water-stressed Mediterranean growing regions.
- Almería cluster expansion:Concentrated solar thermal integration with polyethylene film installations supplies year-round vegetable output to German and British retail procurement networks.
Market Restraints
- Steel and aluminum input volatility:Greenhouse frame and gutter systems remain exposed to commodity price swings that compress project margins for turnkey installation contractors.
- Glass supply concentration:European horticultural glass production centers on a limited number of specialized float-glass furnaces, creating lead-time vulnerability for premium research-grade structures.
- Technical limitation of passive ventilation:Conventional ridge-and-side vent designs fail to maintain VPD setpoints during humid subtropical summers, restricting geographic deployment without mechanical dehumidification retrofit.
Strategic Opportunities
- Underpenetrated Indian protected cultivation:BIS structural certification requirements and PLI scheme subsidies for precision agriculture equipment create entry pathways for foreign technology licensors in Maharashtra and Karnataka.
- Pharmaceutical flower aeroponics:Root-zone oxygen precision requirements for cannabinoid and alkaloid extraction feedstock favor high-pressure misting systems over substrate-based alternatives.
- Retail chain captive sourcing:Direct contracting between Northern European supermarket groups and Iberian greenhouse cooperatives is compressing traditional wholesale auction channels.
Industry Challenges
- Climate engineer skill scarcity:Integration of HVAC, irrigation, and lighting control systems requires cross-trained technicians that vocational programs in producing regions have not yet scaled to supply.
- Capex intensity of automation retrofits:Existing polyethylene film structures face prohibitive rewiring and structural reinforcement costs to support LED top-lighting and sensor networks.
- CE marking timeline compression:Machinery directive compliance for robotic harvesting equipment delays commercial deployment of autonomous de-leafing and truss-cutting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse Market |
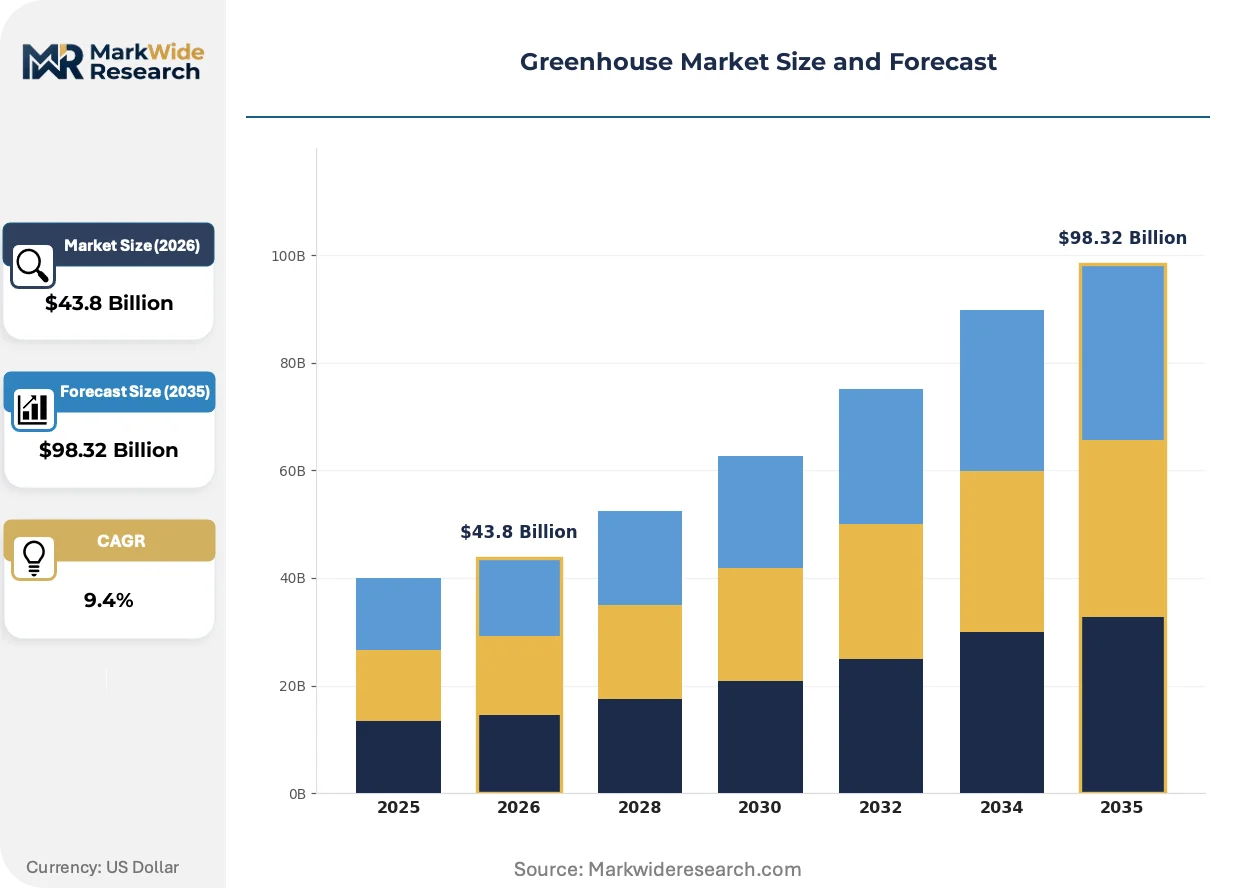
| Market Size in 2026 | $43.8 Billion |
| Market Size in 2035 | $98.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Structure Type: Glass Greenhouses, Polycarbonate Greenhouses, Film Greenhouses, Tunnel Greenhouses Crop Type: Vegetables, Fruits, Flowers, Herbs Technology: Hydroponics, Aeroponics, Soil-based, Aquaponics End User: Commercial Growers, Hobbyists, Research Institutions, Nurseries |
| Companies Covered | Certhon, Richel Group, Argus Control Systems Ltd, Rough Brothers Inc, Netafim, Logiqs B.V., Nexus Corporation, Priva B.V., Agra Tech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse Market Strategic Shifts & Innovations
Greenhouse technology stacks are fragmenting into interoperable hardware-software bundles that allow growers to swap individual control layers without full system replacement, reducing vendor lock-in and accelerating upgrade cycles.
Dynamic LED spectrum tuning is collapsing the traditional distinction between vegetative and generative growth phases in tomato and cucumber cultivation. Large-scale Spanish and Dutch glasshouse operators are retrofitting adjustable red-white-far-red arrays to compress crop cycles and reduce chemical growth regulator applications. The structural consequence is collapsing demand for high-pressure sodium legacy installations and the ballast infrastructure that supported them.
The EU Green Deal's carbon border adjustment mechanism and national building energy performance standards are tightening thermal envelope requirements for new greenhouse permits. Dutch environmental agencies now mandate minimum U-value thresholds for cladding materials in commercial expansions. German growers are responding with double-layer inflated polyethylene systems and thermal screens that reduce heating degree-day consumption.
Direct procurement contracts between supermarket chains and greenhouse consortia are displacing traditional spot-market auction participation for vine crops. British and Scandinavian retail buyers now specify varietal, packaging, and carbon accounting requirements in multi-year supply agreements. This pattern is most visible in the Netherlands, where Royal FloraHolland auction volumes for tomatoes have declined while direct-to-retail contract acreage expands.
Greenhouse Market Segmentation
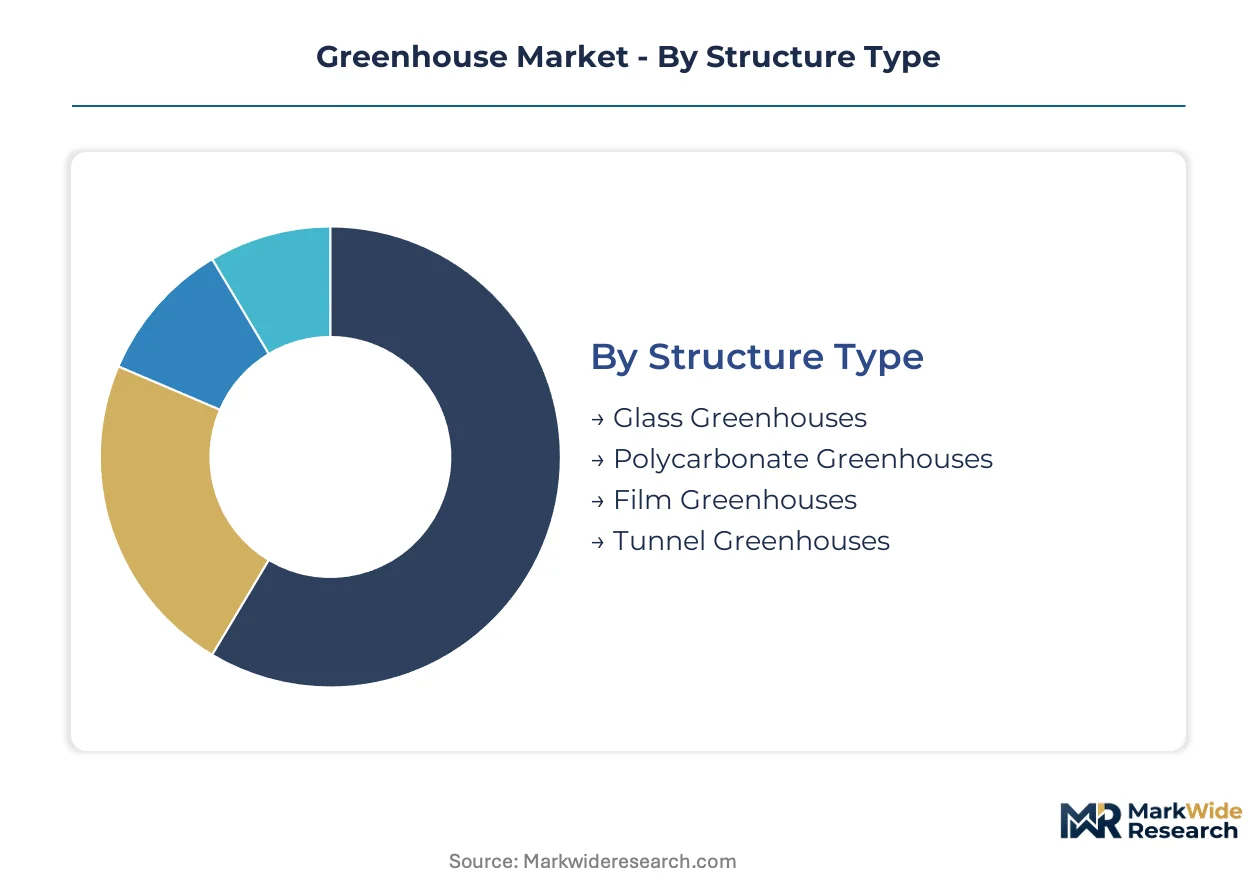
Greenhouse market segmentation reflects divergent capital intensity and automation requirements across structure materials, crop economics, cultivation technology, and buyer sophistication. Each dimension shapes procurement patterns and vendor competitive positioning differently.
Structure Type:
Mature glass installations dominate premium horticulture while film structures anchor volume expansion in emerging protected cultivation regions.
- Glass Greenhouses:Horticultural float-glass construction with integrated thermal breaks and aluminum gutter systems delivers maximum light transmission for high-value vine crops. Dutch and Spanish commercial operators under EU Green Deal thermal envelope mandates drive specification intensity for double-glazed research-grade structures.
- Film Greenhouses:Single or double-layer polyethylene membrane systems mounted on galvanized steel hoops minimize capital expenditure per hectare. Almería province clustered installations supply Northern European retail chains through concentrated solar thermal integration, though passive ventilation limitations restrict humid subtropical deployment without mechanical retrofit.
- Polycarbonate Greenhouses:Multi-wall extruded panels balance impact resistance with moderate insulation values for nursery and hobbyist applications.
- Tunnel Greenhouses:Quonset or gothic arch polyethylene structures without permanent foundations serve seasonal season-extension needs in temperate climates.
Film greenhouses handle the majority of global installed hectares; glass structures are gaining share fastest in pharmaceutical and research crop applications.
Crop Type:
Commercial returns vary sharply by perishability, input intensity, and retail procurement contract availability.
- Vegetables:Vine crops—tomatoes, cucumbers, peppers—dominate hydroponic glasshouse economics with year-round production cycles. German and British supermarket direct contracting specifications now mandate varietal, packaging, and carbon accounting compliance for Iberian and Dutch suppliers.
- Flowers:Ornamental production concentrates in Dutch auction and direct-retail channels with extreme sensitivity to stem length and vase-life specifications. Royal FloraHolland auction volumes decline as supermarket captive sourcing expands contract acreage.
- Fruits:Soft-fruit strawberries and raspberries in substrate systems command premium pricing in off-season Northern European markets.
- Herbs:Basil, cilantro, and pharmaceutical-grade botanicals favor controlled-environment precision for active compound consistency.
Vegetable cultivation commands the largest revenue pool; flowers show steepest margin compression from retail procurement consolidation.
Technology:
Cultivation method selection determines water efficiency, root-zone control precision, and capital recovery timelines.
- Hydroponics:Substrate-based systems using mineral wool or coconut coir deliver nutrient solution directly to root zones without soil. Mediterranean water-stressed regions abandon peat-based media as EU emissions rules tighten, with Dutch and Spanish operators leading substrate innovation adoption.
- Aeroponics:High-pressure misting systems suspend roots in oxygen-rich environments for maximum nutrient uptake efficiency. Pharmaceutical flower alkaloid and cannabinoid extraction feedstock requirements favor this technology where root-zone oxygen precision determines active compound yields.
- Soil-based:Traditional ground-culture systems persist in low-automation regions with adequate water availability and lower capital constraints.
- Aquaponics:Integrated fish-waste nutrient cycling remains niche due to biological system complexity and pH management requirements.
Hydroponics carries the dominant installed base; aeroponics is climbing the fastest in high-value pharmaceutical and nutraceutical applications.
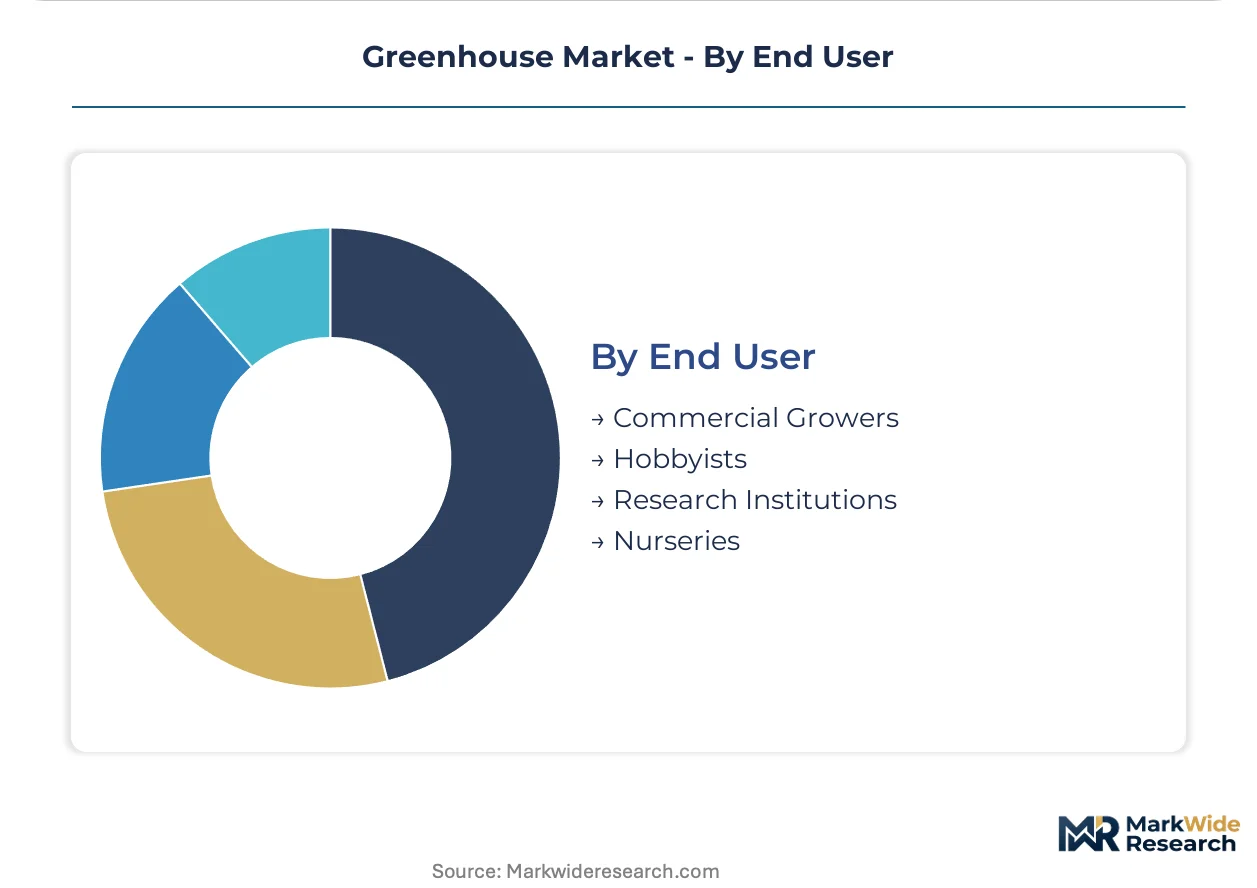
End User:
Buyer sophistication and procurement scale create distinct equipment specification and service requirement tiers.
- Commercial Growers:Large-scale operations with integrated climate control, irrigation automation, and direct retail contracting capability. Dutch engineering heritage dominates high-complexity glass greenhouse installations across European commercial expansions.
- Research Institutions:Universities and agricultural stations require precise environmental replicability and data logging for cultivar development protocols.
- Nurseries:Propagation-focused operations prioritize bench systems and humidity control for seedling establishment.
- Hobbyists:Residential and small-scale commercial operators drive demand for kit structures and simplified control systems.
Commercial growers absorb the majority of industry revenue; research institutions are expanding most quickly in pharmaceutical crop and gene-editing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement managers in Northern Europe drive specification intensity for Dutch and Spanish greenhouse operators, while Indian commercial growers absorb precision agriculture subsidies and Chinese pharmaceutical cultivators scale controlled-environment infrastructure.
Netherlands
Commercial glasshouse operators supply German and British retail chains through direct contracting agreements that mandate carbon accounting compliance. The EU F-Gas Regulation accelerates CO₂ heat pump adoption across South Holland and North Brabant growing regions. Westland municipality clusters host concentrated horticultural engineering expertise serving export markets.
Spain
Almería province polyethylene film installations integrate concentrated solar thermal systems to maintain year-round tomato and pepper output for Northern European buyers. National building energy performance standards tighten thermal envelope requirements for new commercial permits. El Ejido and Níjar municipal zones concentrate the world's largest clustered greenhouse complex.
United States
California and Arizona desert operations expand pharmaceutical flower aeroponics capacity for cannabinoid extraction feedstock. The EPA's Clean Air Act standards shape heating technology procurement decisions in commercial expansions. Salinas Valley vegetable growers retrofit existing structures with LED top-lighting arrays.
India
Maharashtra and Karnataka protected cultivation projects absorb PLI scheme subsidies for precision agriculture equipment imports. BIS structural certification requirements filter foreign equipment supplier eligibility for commercial installations. Nashik district clusters emerge as domestic vine crop supply hubs for Mumbai and Pune retail networks.
China
Shandong and Hebei provinces scale automated glasshouse construction for domestic pharmaceutical botanical cultivation. National dual carbon goals constrain heating fuel choices in new commercial permits. Weifang municipality engineering fabricators export turnkey film structures to Belt and Road markets.
Greenhouse Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered technology bundles. The vendor base organizes around three strategic archetypes: Dutch engineering heritage firms dominating high-complexity glass installations, Israeli precision irrigation specialists, and modular automation software integrators. Competitive moves concentrate on technology licensing partnerships and geographic expansion through turnkey installation contracting.
Within the Dutch engineering tier, Certhon and Priva B.V. exemplify heritage-rooted positioning in European commercial expansions. Netafim anchors the precision irrigation specialist archetype with global technology licensing reach. Logiqs B.V. occupies a position bridging hardware fabrication with software integration for mid-scale commercial operators.
| Leading Market Players |
|---|
| Certhon |
| Richel Group |
| Argus Control Systems Ltd |
| Rough Brothers Inc |
| Netafim |
| Logiqs B.V. |
| Nexus Corporation |
| Priva B.V. |
| Agra Tech Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in European horticultural glass furnaces is tightening supplier pricing power while forcing turnkey contractors toward extended lead-time premiums and alternative cladding specifications. Dutch and Spanish commercial operators absorb these cost transfers through indexed supply agreements that pass aluminum and steel volatility to retail procurement networks.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate large-scale greenhouse installations, insulating Dutch engineering firms from commodity swings while compressing margins for fixed-price bidders. Three-tier pricing structure across premium glass, standard film, and economy tunnel configurations reflects CE marking complexity and thermal envelope performance. Cost compression in polyethylene film tiers is intensifying because Almería cluster expansions concentrate procurement volume among cooperative buyers. Research institutions exhibit lowest price sensitivity due to grant-funded capital cycles, while Indian commercial growers under PLI subsidy schemes drive hardest bargain on imported automation bundles.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Dutch horticultural engineering firms anchor working capital structures for Spanish and Indian installation projects. Glass production concentrates in Belgium and Germany, aluminum extrusion in the Netherlands, and galvanized steel framing in China. Raw material dependencies rest on horticultural float-glass, aluminum gutter systems, and semiconductor components for climate control sensors. Single-source vulnerability in specialized float-glass furnaces creates lead-time risk for research-grade structures. Distribution runs through turnkey installation contractors who bundle structural, mechanical, and automation subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The greenhouse sector exhibits acute scarcity of cross-trained climate engineers capable of integrating HVAC, irrigation, and lighting control systems, constraining expansion velocity for automation-intensive operators.
For Market Incumbents: Insulate margin pools by backward integration into aluminum gutter fabrication and climate control software stacks. Certhon and Priva B.V. should deepen captive supply of sensor networks to reduce exposure to semiconductor lead-time volatility. Defensive patenting around CO₂ heat pump integration with glasshouse thermal systems creates barriers against Israeli irrigation specialists expanding into climate engineering. For New Entrants and Emerging Players: Establish a beachhead in Indian protected cultivation by licensing Dutch engineering designs to Maharashtra-based fabricators qualified under BIS structural certification. Pharmaceutical flower aeroponics in California and Arizona offers penetrable white-space with less incumbent saturation than European vine crop automation. Go-to-market leverage rests on supply-chain finance facilities that match Dutch payment terms for capital-constrained Western US cultivators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among climate-control software integrators with multi-year service contracts tied to Dutch and Spanish glasshouse expansions. Long-term viability favors targets with demonstrated EU F-Gas Regulation compliance pathways and established retail procurement relationships. The signal to watch is Royal FloraHolland auction volume decline as direct-to-retail contracting accelerates, indicating consolidation leverage among captive-sourced operators.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Dutch engineering firms monetize design IP in Indian BIS-certified fabrication networks. |
| Backward Integration into Thermal Systems | CO₂ heat pump manufacturing captures margin pools from EU F-Gas Regulation compliance. |
| Direct Retail Contracting Expansion | German supermarket procurement specifications displace traditional auction channels for Iberian tomatoes. |
| Climate Engineer Training Program | Vocational scaling addresses skill scarcity constraining automation retrofit velocity. |
| Pharmaceutical Aeroponics Scale-Up | California cannabinoid extraction feedstock demand favors high-pressure misting system deployment. |
Research Approach
Cross-validation between primary interviews with greenhouse operators and secondary trade data anchors the qualitative findings on automation adoption patterns. This study combined discussions with Dutch commercial growers, Spanish cooperative procurement managers, Indian precision agriculture subsidy administrators, and California pharmaceutical cultivators with validation against EU customs records, BIS certification registries, and EPA Clean Air Act compliance filings. Bottom-up project pipeline analysis and top-down equipment shipment triangulation produced convergent market sizing.
Calibration against historical glasshouse installation permits and climate control equipment import data refined the projection framework. Segmentation dimensions modeled include structure material, cultivation technology, crop economics, and buyer sophistication tier across the analysis window. CAGRs were derived from equipment replacement cycles and regulatory compliance timelines. Key inputs incorporated EU Green Deal thermal envelope mandates and Indian PLI scheme disbursement trajectories.
Stress conditions across steel and aluminum price bands, semiconductor lead times, and EU F-Gas Regulation phase-down schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about subsidy continuity and retail procurement contract expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
United Kingdom Commercial Greenhouse Market
Agriculture and Agri Products
Faba Beans Flour Market