
 France Alfalfa Hay Market | 2026-2036
France Alfalfa Hay Market Size, Share, and Industry Trends Forecast 2026-2036
France Alfalfa Hay Market Foresight
The EU Green Deal is realigning French forage production incentives toward lower-input cropping systems, redirecting acreage toward certified alfalfa hay. Doulière Hay France SAS leverages its vertically integrated drying and baling infrastructure across the Poitou-Charentes basin. Gilles Baudot French Hay sustains premium positioning through geographic concentration in the Champagne-Ardenne grasslands. Cérience SAS specializes in varietal selection services that anchor seed-to-hay traceability for export-bound producers.
Alfalfa hay denotes the dried aerial biomass of Medicago sativa, typically harvested at early bloom stage with crude protein content ranging from 15% to 22% on a dry matter basis, then cured and baled for use as a high-fiber, high-protein roughage in ruminant and monogastric diets. Compressed bales dominate volume throughput due to freight efficiency and storage density advantages over loose hay, while pellets capture premium margins from equine feed compounders seeking dust-reduced formulations. Dairy livestock applications absorb the largest share of domestic output, though pet food supplements represent the fastest-expanding demand channel as urban pet ownership climbs.
ANSM oversees veterinary feed safety standards, while France's national implementation of EU REACH and the F-Gas Regulation shapes drying energy choices and preservative approvals. The national agricultural regulator enforces GAEC standards that condition subsidy eligibility on crop rotation including leguminous forages. Stakeholders must monitor evolving eco-score labeling requirements and their downstream effects on procurement specifications across feed mill customers.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is redirecting French forage subsidies toward leguminous crop rotations, compressing chemical-dependent hay production margins while elevating certified alfalfa acreage in Normandy and Brittany dairy corridors.
Growth Catalysts
- EU Green Deal alignment:France's national implementation of Farm to Fork incentives rewards farmers who substitute nitrogen-fixing alfalfa for fertilizer-intensive grasses, expanding eligible hectarage in Pays de la Loire.
- Dairy protein specifications:Feed mills serving Brittany's expanding livestock operations specify crude protein thresholds that only early-bloom alfalfa hay reliably satisfies, locking in contract volumes.
- Compressed bale logistics:Freight density advantages of double-compressed bales enable Poitou-Charentes producers to reach export buyers in Italy and Benelux at viable unit economics.
Market Restraints
- Natural gas price volatility:Mechanical drying operations in Champagne-Ardenne face margin compression when benchmark TTF prices spike, forcing seasonal shutdowns.
- Single-region supply concentration:Premium hay production clusters geographically in limited grassland zones, exposing buyers to weather-driven harvest variability.
- Silage substitution:Corn silage and wrapped grass bales compete for dairy ration inclusion, particularly when alfalfa hay prices exceed protein-equivalent feed values.
Strategic Opportunities
- Pet food channel expansion:Urban pet ownership growth in Île-de-France creates demand for dust-reduced alfalfa pellets as rabbit and guinea pig supplements.
- Eco-score procurement mandates:French retail feed brands are beginning to screen suppliers on carbon intensity metrics, favoring hay from reduced-tillage systems.
- Seed-to-hay traceability:Blockchain-enabled certification platforms allow export-oriented producers in Centre-Val de Loire to command premiums in Swiss and German equine markets.
Industry Challenges
- GAEC compliance timelines:Farmers must document three-year crop rotation sequences to maintain subsidy eligibility, creating administrative bottlenecks during conversion periods.
- Drying infrastructure capex:Natural gas-to-biomass burner retrofits require capital outlays that smaller cooperatives in Limousin struggle to finance without regional aid.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Alfalfa Hay Market |
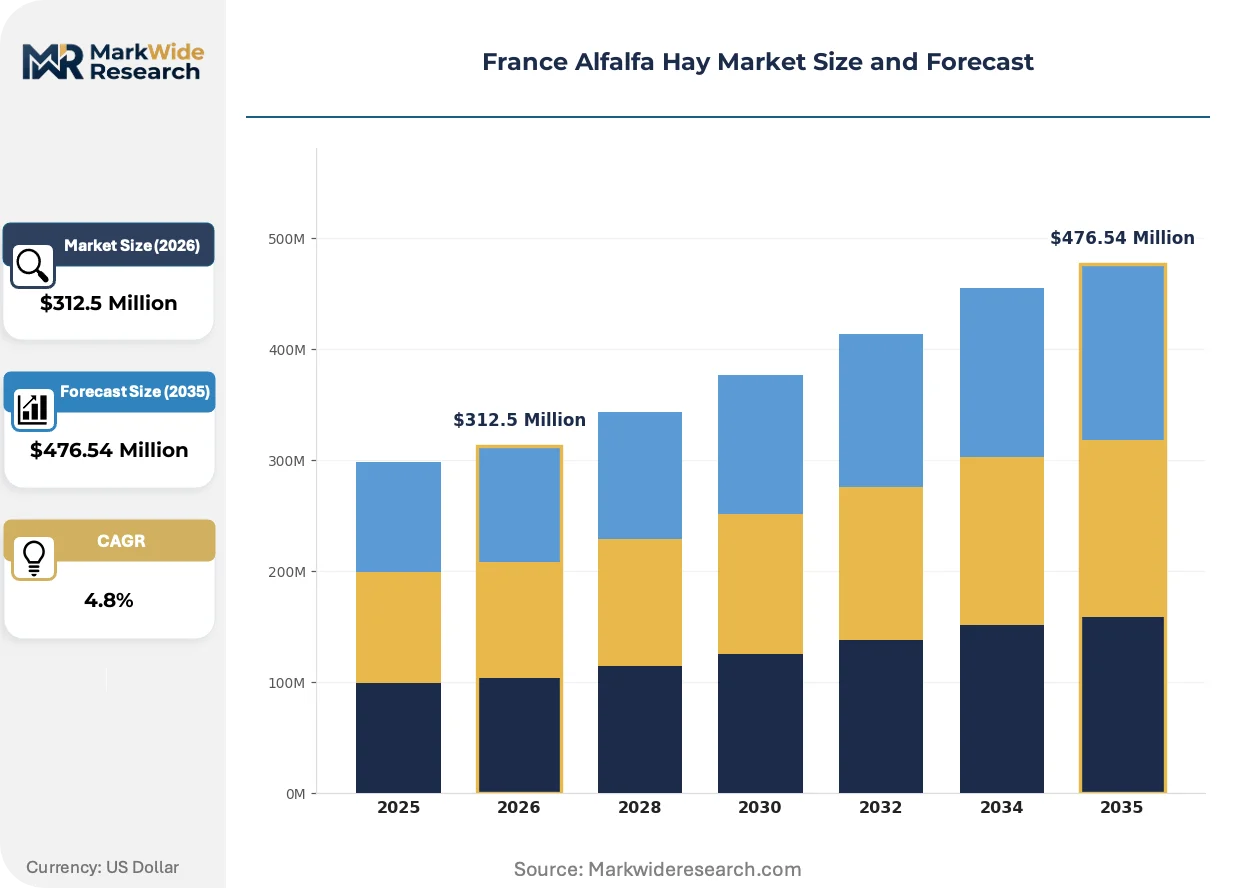
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Hay, Compressed Bales, Pellets, Cubes Application: Dairy Livestock, Equine Feed, Poultry Nutrition, Pet Food Supplements Packaging Type: Plastic Wrap, Jute Bags, Cardboard Boxes, Bulk Containers End User: Feed Mills, Animal Farms, Pet Stores, Agricultural Cooperatives |
| Companies Covered | Doulière Hay France SAS, Gilles Baudot French Hay, Cubeit Hay Company, Anderson Hay & Grain Co, S&S Agrisource Holding LLC, Al Dahra ACX Global Inc, Coaba Group, SL Follen Company, Cérience SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Alfalfa Hay Market Shifts & Advancements
Mechanical drying technology, regulatory carbon accounting, and buyer procurement centralization are simultaneously reshaping how French alfalfa hay moves from field to ration.
Solar-thermal hybrid drying systems are modularizing field-level processing capacity across the Poitou-Charentes basin. Mid-scale cooperatives are piloting these units to reduce natural gas dependence during peak harvest windows. This distributed infrastructure is compressing the historical advantage of centralized fossil-fuel dryers owned by large integrated operators.
France's enforcement of EU REACH and the F-Gas Regulation is restricting preservative chemistries and refrigerant choices in hay conditioning equipment. Drying facility operators must now submit extended safety dossiers for novel mold inhibitors, slowing product registration cycles. Feed compounders in Normandy are responding by tightening supplier qualification protocols to preempt downstream liability exposure.
Equine feed brands are consolidating procurement decisions at headquarters level, displacing regional mill autonomy. Centralized buying desks in Paris and Lyon now specify certified weed-free grades that only traceable supply chains can document. This concentration is most visible in the competition for contracts with national pet retail chains expanding their private-label hay offerings.
France Alfalfa Hay Market Segmentation
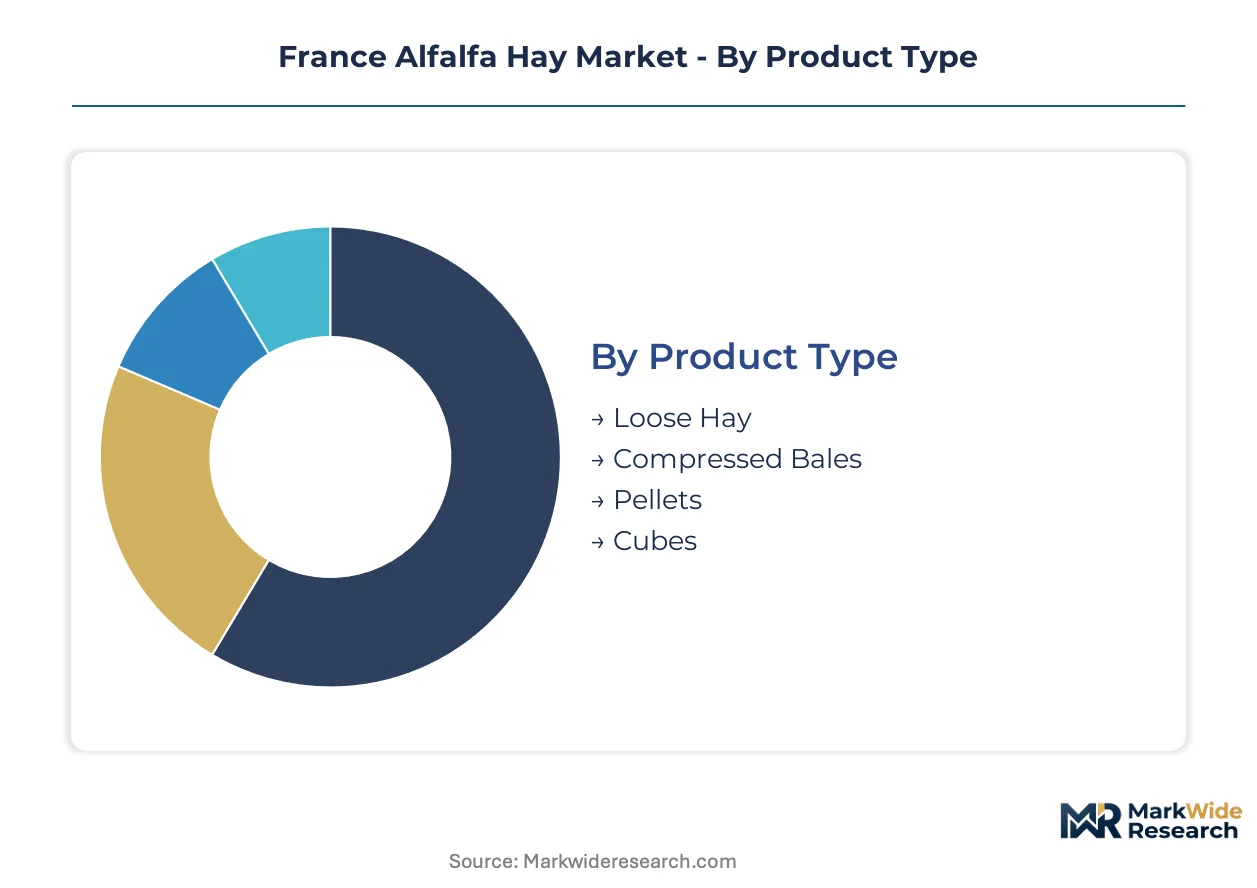
Product form, application channel, and packaging configuration each impose distinct logistics constraints and margin structures on French alfalfa hay suppliers. Understanding how these axes intersect reveals where volume concentrates versus where premiums accumulate across the value chain.
Product Type:
Mechanical processing intensity separates commodity hay from value-added formats, with drying technology and compression density determining freight economics and storage efficiency.
- Compressed Bales:Double-compressed rectangular bales achieve freight densities of 200-250 kg per cubic meter, enabling Poitou-Charentes producers to serve Italian and Benelux buyers at viable unit economics. Dairy feed mills in Brittany specify compressed formats for automated handling systems.
- Pellets:Dust-reduced formulations produced via hammer-milling and steam conditioning command premium positioning from equine feed compounders and urban pet retailers. Île-de-France pet store chains increasingly mandate pellet specifications for rabbit and guinea pig supplement lines.
- Loose Hay:Unprocessed dried biomass retains highest fiber integrity for traditional dairy farms with manual feeding protocols, though handling labor limits adoption among larger operations.
- Cubes:Alfalfa hay cubes combine moderate compression with reduced fines generation, serving niche equine markets where controlled intake rates matter.
Compressed bales lead on scale; pellets lead on momentum.
Application:
Protein specification stringency and ration formulation complexity vary sharply across livestock categories, directing procurement behavior toward either commodity contracts or premium supply agreements.
- Dairy Livestock:Early-bloom alfalfa hay delivers crude protein levels of 18-22% on dry matter basis, satisfying Pays de la Loire feed mill specifications for high-producing herds. Contract volumes lock in when protein premiums over corn silage justify inclusion rates.
- Equine Feed:Weed-free certification and low-mold guarantees dominate thoroughbred and sport horse segment procurement, with traceable Champagne-Ardenne sourcing commanding price premiums in Swiss and German export markets.
- Pet Food Supplements:Small mammal dietary fiber demand from urban pet owners in Lyon and Marseille is expanding most quickly as rabbit and guinea pig ownership climbs in apartment-dwelling households.
- Poultry Nutrition:Layer hen rations incorporate limited alfalfa hay for yolk color enhancement, though volume remains constrained by cost-competitive synthetic pigment alternatives.
Dairy livestock anchors volume throughput; pet food supplements exhibit steepest expansion trajectory.
Packaging Type:
Protection requirements against moisture intrusion and handling damage scale with distribution distance and end-user sophistication, creating tiered cost structures across the supply base.
- Plastic Wrap:UV-stabilized stretch film dominates field-level baling operations across Normandy, offering weather protection during outdoor storage periods before mill delivery.
- Jute Bags:Breathable natural fiber packaging serves equine specialty retailers seeking aesthetic differentiation and mold resistance in humid stable environments.
- Cardboard Boxes:Retail-ready formats with printed branding specifications capture pet store shelf space in Paris and Bordeaux urban corridors.
- Bulk Containers:Tote bags and unwrapped trailer loads minimize per-unit packaging cost for feed mill direct procurement at scale.
Plastic wrap commands farmgate volume; cardboard boxes concentrate margin capture.
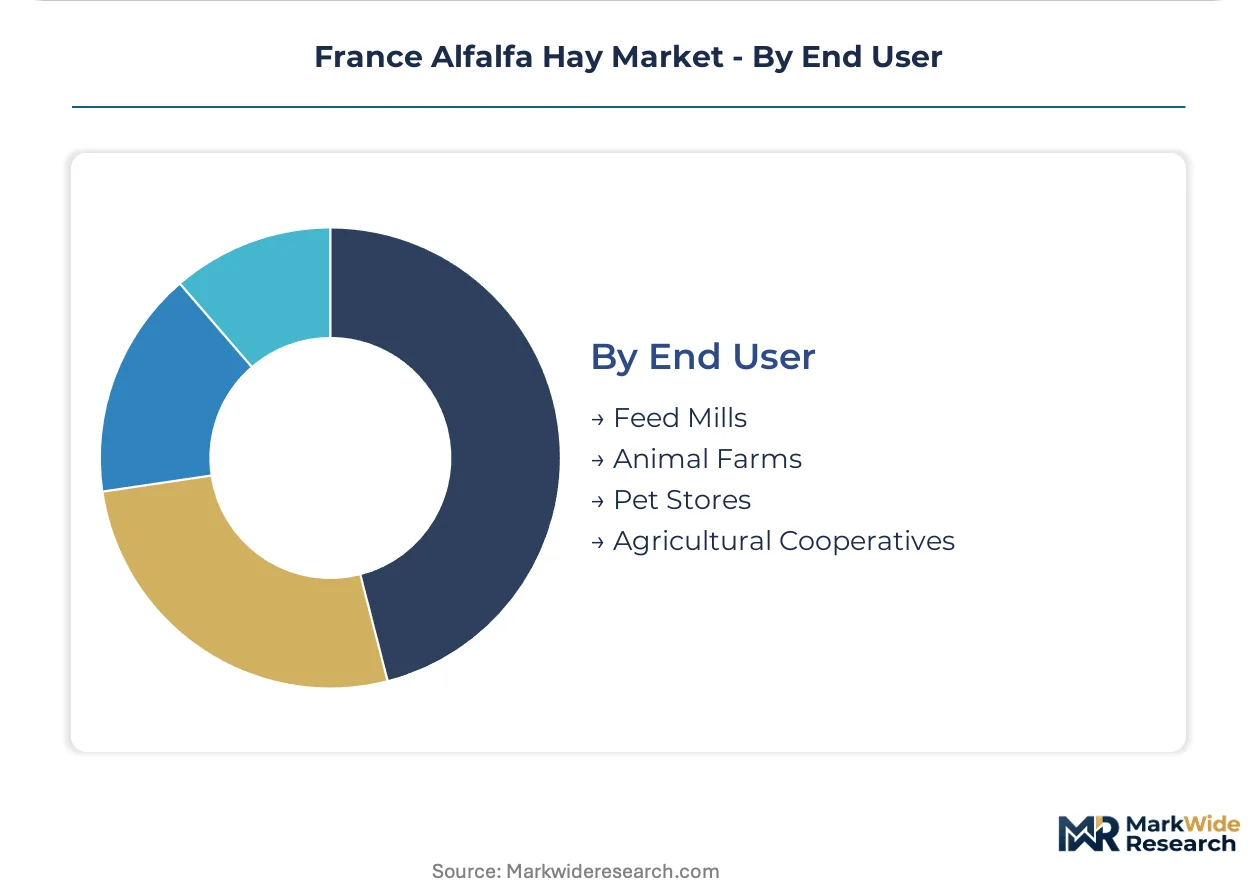
End User:
Procurement centralization and technical specification authority diverge between consolidated feed manufacturing and fragmented farm-level purchasing, reshaping supplier relationship economics.
- Feed Mills:Brittany and Pays de la Loire compounders consolidate multi-year contracts with drying cooperatives, specifying protein minimums and moisture maximums that filter back to field-level harvest timing decisions.
- Animal Farms:Direct farm procurement in Limousin and Auvergne-Rhône-Alpes retains flexibility for seasonal spot purchases, though GAEC subsidy documentation requirements add administrative overhead.
- Pet Stores:National retail chains centralizing buying decisions in Lyon and Paris now screen suppliers on eco-score metrics, favoring reduced-tillage hay sourcing for private-label offerings.
- Agricultural Cooperatives:Member-owned purchasing bodies in Centre-Val de Loire aggregate smallholder demand to achieve compressed bale volume thresholds for export logistics.
Feed mills dominate contract value; pet stores are gaining specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alfalfa hay cultivation in France traces its commercial scaling to the post-war modernization of dairy cooperatives in Normandy and Brittany during the 1960s, when protein self-sufficiency became a national agricultural priority. Regional specialization has since hardened around distinct grassland ecologies and processing infrastructure.
Normandy
Dairy feed mills in Caen and Rouen specify early-bloom protein thresholds that anchor contract volumes with local drying cooperatives. France's GAEC standards enforce three-year leguminous rotations that expand eligible alfalfa hectarage across the Cotentin Peninsula. The Pays d'Auge grasslands concentrate premium hay production for export to Swiss equine markets.
Brittany
Expanding livestock operations in Finistère and Côtes-d'Armor drive protein demand that outpaces regional grass silage capacity. ANSM veterinary feed safety protocols shape preservative approvals for hay conditioning facilities in Saint-Brieuc. Compressed bale logistics from Rennes-area cooperatives reach Italian buyers through Nantes-Atlantic port corridors.
Pays de la Loire
Feed compounders in Angers and Le Mans consolidate procurement decisions that filter back to harvest timing across the Loire Valley. The EU Green Deal's Farm to Fork incentives redirect subsidy eligibility toward reduced-tillage alfalfa systems in Sarthe and Mayenne. Solar-thermal drying pilots in Cholet are modularizing field-level processing capacity.
Champagne-Ardenne
Mechanical drying infrastructure in Reims and Châlons-en-Champagne faces margin compression during TTF natural gas price spikes. The F-Gas Regulation restricts refrigerant choices in conditioning equipment, forcing burner retrofits. Premium positioning in this zone relies on geographic concentration in the Champagne grasslands for traceable export grades.
Poitou-Charentes
Double-compressed bale exports from Niort and Poitiers serve Benelux dairy operations at freight densities of 200-250 kg per cubic meter. Vertically integrated drying and baling infrastructure here enables mid-scale cooperatives to compete with centralized fossil-fuel operators. The basin's solar-thermal hybrid adoption is compressing historical scale advantages.
France Alfalfa Hay Market Competitive Landscape
Capital-heavy producers with captive drying infrastructure compete with asset-light traders who source through seasonal contracting networks. Market structure tilts toward regional consolidation, with three to four integrated operators controlling volume throughput in each major grassland basin alongside fragmented smallholder cooperatives. Two strategic archetypes dominate: vertically integrated drying-and-export specialists and varietal-selection seed-to-hay traceability platforms. Competitive moves concentrate on biomass burner retrofits for carbon accounting compliance and blockchain-enabled certification for Swiss and German premium channels.
Within the integrated processing tier, Doulière Hay France SAS and Gilles Baudot French Hay occupy positions anchored to distinct regional infrastructures. Doulière represents the Poitou-Charentes basin model of vertically combined drying and baling capacity. Baudot exemplifies geographic concentration strategies in Champagne-Ardenne grasslands. Cérience SAS sits within the specialized seed-to-hay traceability archetype, anchoring varietal selection services for export-bound producers rather than direct hay processing.
| Leading Market Players |
|---|
| Doulière Hay France SAS |
| Gilles Baudot French Hay |
| Cubeit Hay Company |
| Anderson Hay & Grain Co |
| S&S Agrisource Holding LLC |
| Al Dahra ACX Global Inc |
| Coaba Group |
| SL Follen Company |
| Cérience SAS |
| Others |
Supply & Pricing Matrix
The EU Green Deal's Farm to Fork strategy gates both qualified supply and premium-tier pricing access, conditioning subsidy eligibility on reduced-tillage leguminous rotations that compress chemical-dependent hay margins while elevating certified alfalfa premiums in Normandy and Brittany dairy corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates export-certified early-bloom hay from domestic dairy grades and unconditioned field-run material. Price differentiation hinges on crude protein certification and GAEC-compliant rotation documentation, with natural gas price spikes forcing margin compression in mechanical drying tiers. Dairy feed mills in Pays de la Loire exhibit highest price sensitivity, while Swiss and German equine buyers absorb premiums for traceable Champagne-Ardenne sourcing.
Supply Chain Analysis
Natural gas supply rests on Norwegian pipeline flows and global LNG spot markets, with hay drying operations drawing from biomass pellet alternatives and solar-thermal hybrid pilots. Preservative chemistries hinge on EU REACH registration cycles, while baling equipment feeds from Italian and German agricultural machinery specialists. Single-region concentration in Champagne-Ardenne grasslands exposes buyers to weather-driven harvest variability. Distribution runs through drying cooperative networks to feed mill compounders, with compressed bale exports reaching Benelux via Nantes-Atlantic corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France alfalfa hay market functions as a stable compounder, with EU Green Deal subsidy realignment providing durable acreage expansion incentives that underpin steady volume growth through the projection horizon.
For Market Incumbents: Hedge natural gas exposure through biomass burner retrofits and solar-thermal hybrid pilots in Poitou-Charentes, while deepening backward integration into seed-to-hay traceability platforms to preempt Swiss and German equine procurement consolidation. Defend contract volumes with Pays de la Loire feed mills by locking in early-bloom protein specifications ahead of silage substitution pressure. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels targeting Île-de-France pet owners offer the most penetrable white-space, with dust-reduced pellet formulations for rabbit and guinea pig supplements commanding premium positioning absent from incumbent dairy-focused portfolios. Pursue eco-score certification partnerships with national retail chains centralizing buying decisions in Lyon and Paris. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale drying cooperatives because GAEC compliance documentation requirements create administrative barriers that fragment smallholder supply and reward consolidated procurement platforms. Monitor solar-thermal hybrid adoption rates as the inflection signal for distributed infrastructure displacing centralized fossil-fuel drying advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Burner Retrofit | Natural gas-to-biomass conversions in Champagne-Ardenne reduce TTF price exposure and align with F-Gas Regulation compliance timelines. |
| Seed-to-Hay Traceability Platform | Blockchain-enabled certification allows Centre-Val de Loire producers to command Swiss and German equine market premiums. |
| Solar-Thermal Hybrid Pilot | Modular field-level drying capacity in Poitou-Charentes compresses historical scale advantages of centralized fossil-fuel operators. |
| Eco-Score Certification Partnership | Reduced-tillage sourcing documentation meets Paris and Lyon retail chain procurement mandates for private-label hay offerings. |
| Compressed Bale Export Logistics | Double-compressed formats achieving 200-250 kg per cubic meter freight density enable viable unit economics to Italian and Benelux buyers. |
Research Methodology
Multiple input streams — cooperative drying facility managers, feed mill procurement directors, agricultural cooperative board members, and ANSM regulatory affairs specialists — were reconciled with customs export records, GAEC subsidy disbursement databases, EU REACH registration filings, and F-Gas Regulation implementation guidance. Bottom-up field-level acreage estimates and top-down feed ration formulation demand models were cross-validated to establish volume baselines.
Data-stream reconciliation across product type, application channel, packaging configuration, and regional production basin dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate synthesis, with natural gas price scenario modeling and EU Green Deal incentive trajectory assumptions informing the forecast envelope.
The model assumes a particular technology adoption path; alternative pathways for solar-thermal hybrid drying would alter the outlook if modular unit economics compress faster than projected. Forecasts reflect documented assumptions on subsidy continuity and protein premium sustainability. A small set of named triggers — TTF price volatility spikes, REACH preservative registration delays, and retail eco-score mandate acceleration — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Swine Feed Premix Market