
 Centella Asiatica Market | 2026-2036
Centella Asiatica Market Size, Share, and Industry Trends Forecast 2026-2036
Centella Asiatica Market Outlook
Direct-to-consumer e-commerce is rewriting how Centella Asiatica extracts reach end users, with dedicated skincare platforms and brand-owned storefronts displacing traditional wholesale distribution. COSRX leverages its digital-native positioning to control pricing and customer data across Asian and North American markets. BASF sustains upstream supply security through captive cultivation partnerships in Madagascar and Southeast Asia. Innisfree differentiates via Jeju Island sourcing narratives that command shelf-space premiums in duty-free retail.
Centella Asiatica, commonly called gotu kola, is a perennial herb containing triterpenoid saponins—asiaticoside, madecassoside, asiatic acid, and madecassic acid—typically extracted through hydroalcoholic or supercritical CO2 methods for use in wound healing, collagen synthesis, and anti-inflammatory formulations. Extracts dominate current value capture due to higher active concentration and formulation flexibility across premium skincare lines, while serums represent the fastest-growing form segment as consumers prioritize targeted, high-efficacy delivery systems over basic creams. Oils retain niche positioning within K-beauty haircare and scalp treatment protocols where lipid-soluble actives penetrate follicular tissue.
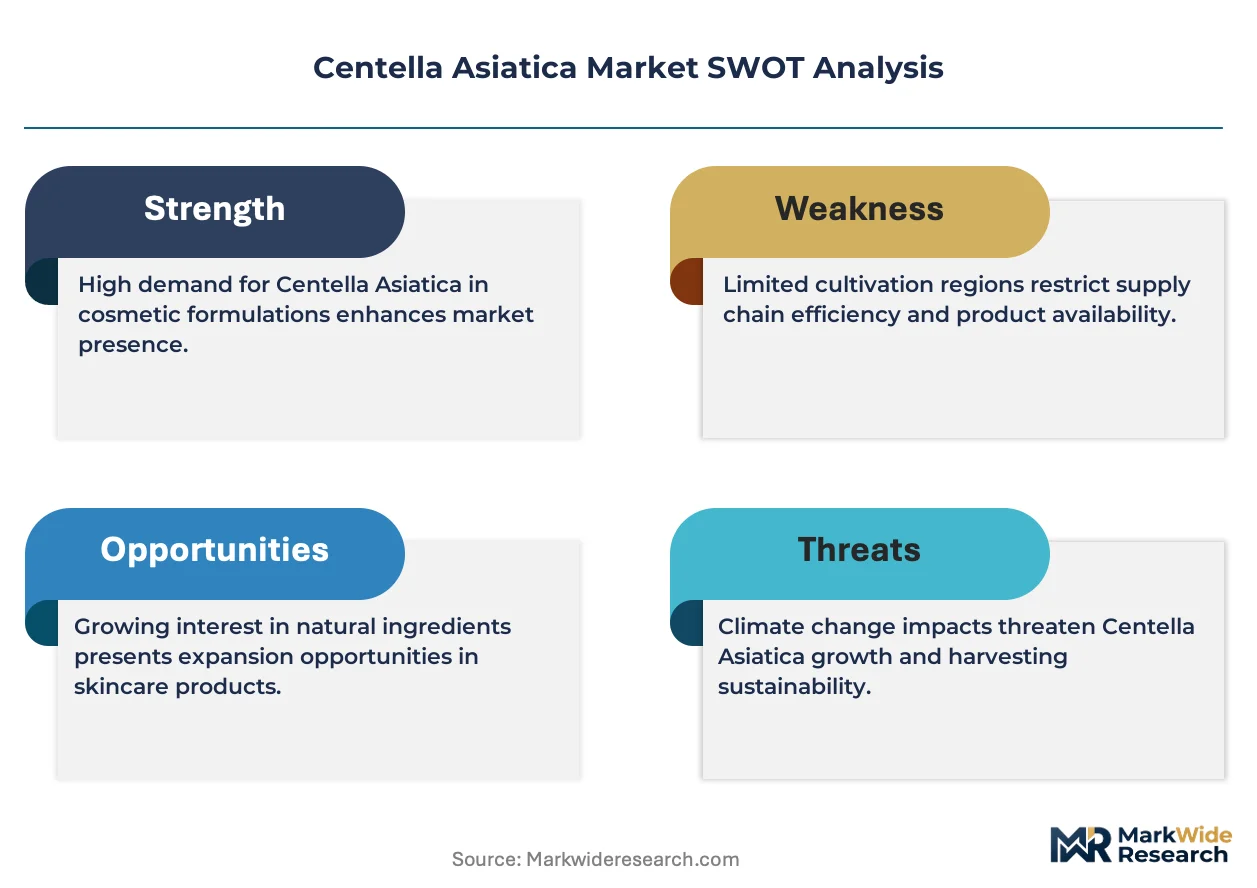
FDA cosmetic ingredient oversight and ECHA REACH substance evaluation both mandate documented safety profiles for botanical extracts used in topical applications, compelling suppliers to invest in standardized chromatographic fingerprinting and heavy-metal testing. South Korea's MFDS and China's NMPA impose additional microbial and pesticide residue thresholds that filter smaller raw-material traders from qualified vendor lists. Stakeholders must weigh regulatory compliance costs against the margin compression risk of undifferentiated commodity supply as certification requirements proliferate across target markets.
Market Dynamics
ECHA REACH substance evaluation on botanical cosmetic ingredients is forcing raw material suppliers to invest in standardized chromatographic fingerprinting and heavy-metal documentation, compressing margins for undifferentiated traders while rewarding certified producers.
Growth Catalysts
- Cosmetic ingredient safety mandates:ECHA REACH compliance requirements in Europe are accelerating procurement of documented Centella extracts by premium skincare formulators seeking qualified vendor status.
- Supercritical CO2 extraction adoption:This solvent-free processing technology is expanding active compound yields while meeting clean-label demands from K-beauty and Western natural cosmetics brands.
- Madagascar cultivation expansion:Captive farming partnerships in this Indian Ocean island nation are securing upstream supply of wild-harvested gotu kola for major active ingredient producers.
Market Restraints
- Wild harvest dependency:Raw material sourcing concentrates in Southeast Asian and Madagascar wild populations, exposing supply continuity to climate variability and collection permit restrictions.
- Triterpenoid standardization costs:Achieving consistent asiaticoside and madecassoside concentrations requires HPLC validation investments that filter smaller extract suppliers from commercial viability.
- Synthetic peptide substitution:Lab-produced collagen stimulants and anti-inflammatory compounds are capturing formulation slots in mass-market skincare where botanical provenance commands less price premium.
Strategic Opportunities
- Scalp care application expansion:Lipid-soluble Centella actives in hair oil formats are penetrating K-beauty follicular treatment protocols previously dominated by chemical growth agents.
- China NMPA botanical registration pathway:Simplified documentation for traditionally used plant extracts is opening qualified entry for standardized gotu kola ingredients into domestic Chinese cosmetic manufacturing.
- Direct-to-consumer serum platforms:Brand-owned digital storefronts are collapsing wholesale distribution layers, enabling margin capture and first-party customer data accumulation for extract-integrated skincare lines.
Industry Challenges
- Chromatographic fingerprinting talent scarcity:Analytical chemists capable of validating triterpenoid saponin profiles per ISO botanical standards command salary premiums that strain mid-tier supplier economics.
- Multi-jurisdiction certification timelines:Parallel MFDS, NMPA, and FDA cosmetic ingredient dossier preparation extends product commercialization cycles by 18-24 months for global market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centella Asiatica Market |
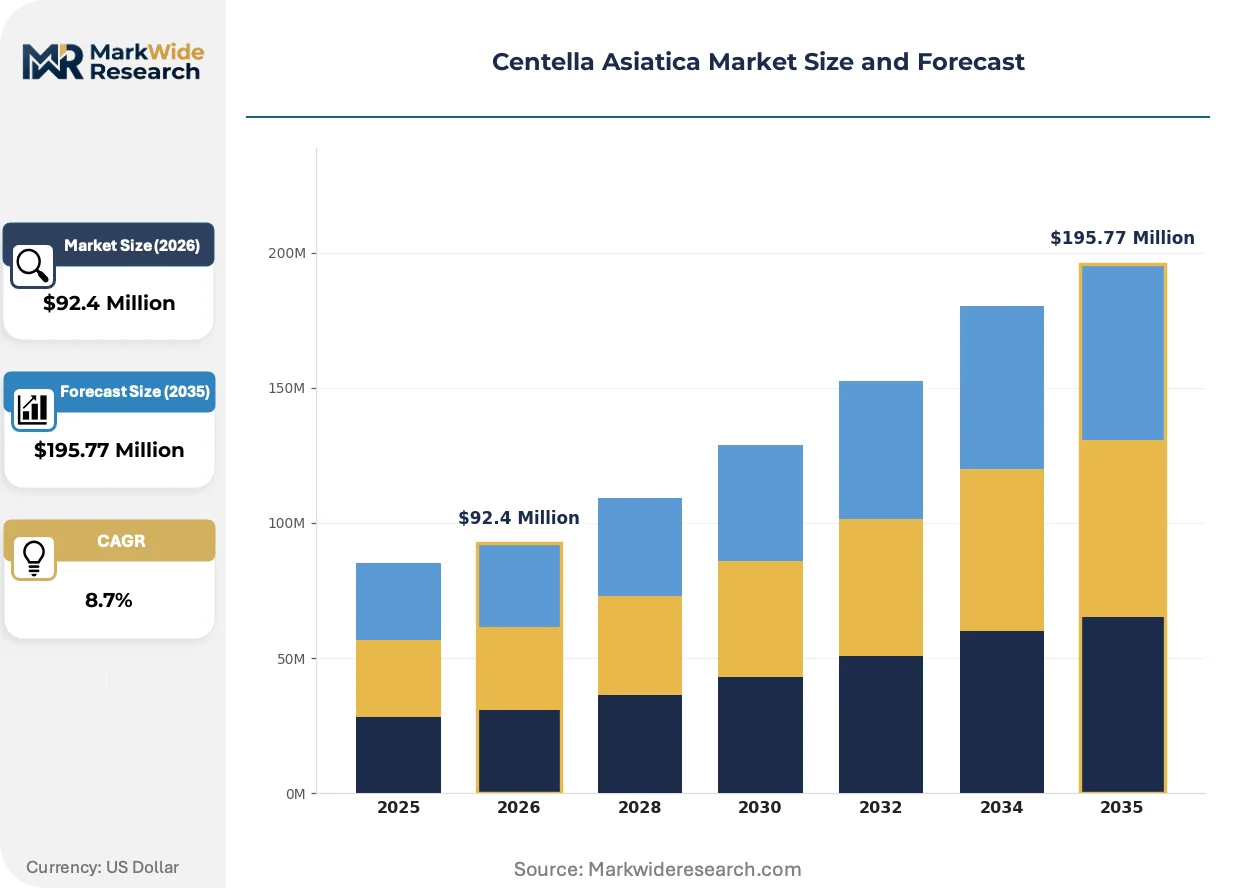
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $195.77 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Oils, Powders, Creams Application: Skincare, Haircare, Pharmaceuticals, Nutraceuticals Form: Topical, Oral, Capsules, Serums End User: Cosmetics Manufacturers, Health Food Companies, Pharmacies, Retailers |
| Companies Covered | COSRX, Alchem International Pvt. Ltd., BASF, The Face Shop, Earth Rhythm, L'Oreal, Innisfree, Youth Biotech CO., Ltd., Himalaya Wellness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centella Asiatica Market Strategic Shifts
Formulation science and distribution architecture are both undergoing compression as biotechnology advances meet channel disintermediation, reshaping how Centella actives reach end consumers.
Supercritical CO2 extraction is collapsing the traditional solvent-based processing infrastructure. This technology preserves heat-sensitive triterpenoid saponins while eliminating residual ethanol concerns. Premium skincare manufacturers in South Korea and France are adopting it for clean-label positioning. The capital intensity of this equipment is collapsing small-batch artisan producers from commercial relevance.
REACH substance evaluation deadlines for botanical extracts are tightening documentary requirements across EU cosmetic supply chains. ECHA mandates standardized safety dossiers including heavy-metal and pesticide residue thresholds. Extract suppliers without in-house analytical capabilities face exclusion from qualified vendor lists of major cosmetics manufacturers. German and French formulators are consolidating procurement toward vertically integrated raw material producers.
Consumer acquisition through dedicated skincare platforms is collapsing legacy wholesale and retail pharmacy distribution. Korean direct-to-consumer brands are controlling pricing and customer data across Asian and North American markets. This channel shift concentrates demand recognition with digital-native formulators. The behavior is most visible in serum and ampoule categories where ingredient transparency drives purchase decisions.
Centella Asiatica Market Segmentation
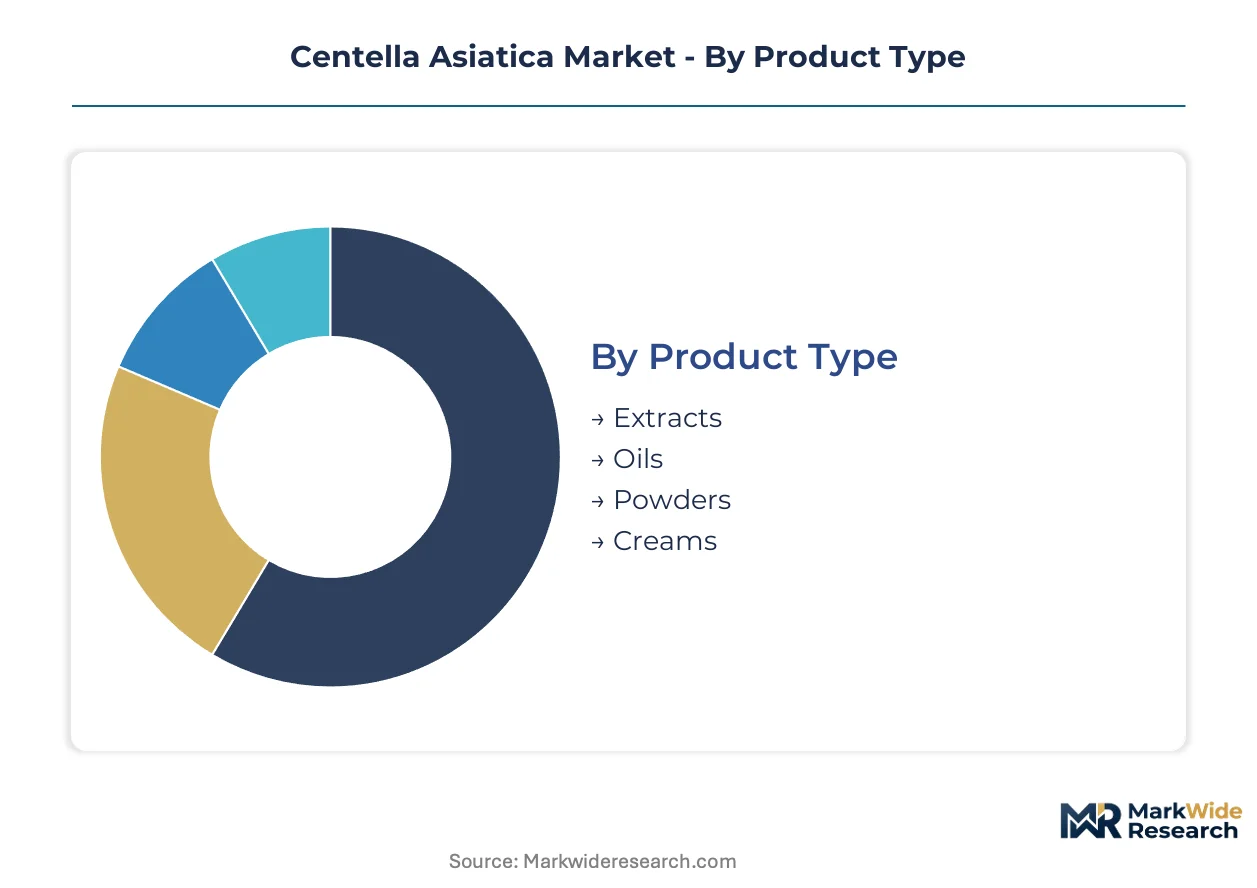
Centella Asiatica supply chains require distinct technical support intensity depending on product complexity. Extracts and serums demand chromatographic validation and regulatory dossier assistance, while commodity powders need minimal after-sales engagement. Understanding these service-tier differences shapes procurement strategy and margin capture across the value chain.
Product Type:
After-sales service intensity varies dramatically across product categories, with standardized extracts requiring regulatory documentation support and custom formulations demanding formulation partnership.
- Extracts:Hydroalcoholic or supercritical CO2-derived concentrates containing standardized triterpenoid saponins. South Korean cosmetics manufacturers dominate procurement, driven by ECHA REACH compliance mandates for documented safety profiles in premium skincare lines.
- Oils:Lipid-soluble fractions targeting K-beauty scalp care protocols. Niche positioning limits volume but commands formulation premiums in follicular treatment applications.
- Powders:Dried aerial plant material for nutraceutical encapsulation. Health food companies in North America source bulk volumes with minimal technical service requirements.
- Creams:Finished emulsion formulations for direct retail distribution. European pharmacies and Asian duty-free channels absorb output from integrated brand manufacturers.
By volume, extracts lead. By growth pace, oils are ahead.
Application:
Cost tier stratification separates premium cosmetic applications from commoditized nutraceutical uses, with pharmaceutical-grade commanding the steepest certification premiums.
- Skincare:Anti-inflammatory and collagen-stimulating formulations leveraging asiaticoside and madecassoside actives. French and South Korean premium brands concentrate demand for serum and ampoule delivery systems.
- Haircare:Scalp treatment oils penetrating follicular tissue via lipid-soluble compounds. K-beauty protocols are displacing chemical growth agents in Asian markets.
- Pharmaceuticals:Wound healing and venous insufficiency preparations requiring MFDS and FDA botanical drug pathway compliance. Regulatory dossier costs filter smaller suppliers from viability.
- Nutraceuticals:Oral supplements for cognitive and circulatory support. North American health food companies drive volume through direct-to-consumer capsule formats.
Skincare captures the largest revenue pool. Pharmaceuticals exhibit the steepest margin structure.
Form:
Customer type divergence separates professional-grade topical formats from consumer-accessible oral delivery, with B2B serum manufacturers demanding the deepest technical integration.
- Topical:Creams and lotions for dermatological and cosmetic application. European formulators prioritize REACH-compliant extract integration.
- Oral:Liquid preparations for traditional medicine and functional beverage markets. Southeast Asian consumption patterns sustain regional supply chains.
- Capsules:Encapsulated powders for standardized dosing in nutraceutical protocols. North American health food distribution channels absorb bulk output.
- Serums:High-efficacy concentrated delivery systems. Direct-to-consumer Korean brands control pricing through owned digital storefronts across Asian and North American markets.
Topical formats dominate current volume. Serums are expanding most quickly as consumers prioritize targeted efficacy.
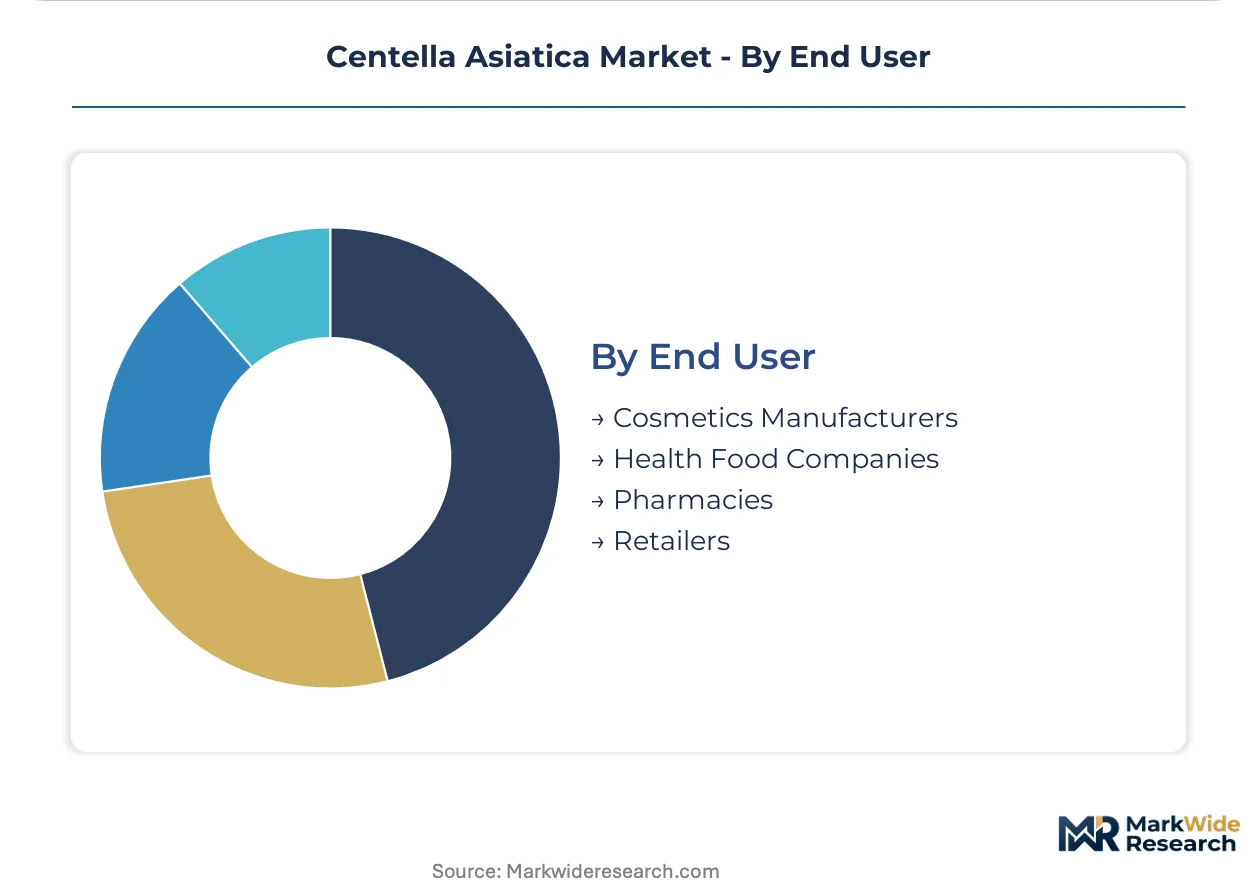
End User:
Supply concentration tilts toward vertically integrated cosmetics manufacturers, while fragmented retail channels face margin compression from wholesale disintermediation.
- Cosmetics Manufacturers:Premium skincare formulators in South Korea and France consolidating procurement toward certified extract suppliers with captive cultivation partnerships.
- Health Food Companies:North American nutraceutical brands sourcing standardized powders for capsule and functional food integration.
- Pharmacies:European and Asian retail pharmacy chains stocking wound healing and dermatological preparations with documented triterpenoid concentrations.
- Retailers:Duty-free operators and e-commerce platforms capturing direct-to-consumer serum demand through brand-owned storefronts.
Cosmetics manufacturers command the largest procurement volumes. Retailers are gaining share fastest through channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean cosmetics manufacturers command premium pricing for Centella-based serums while Indian bulk extract suppliers compete on standardized powder volumes. This asymmetry shapes procurement patterns across the value chain.
South Korea
Seoul-based formulators drive demand for REACH-compliant extracts amid ECHA substance evaluation deadlines. MFDS cosmetic ingredient regulations mandate chromatographic fingerprinting documentation. The Seoul Capital Area concentrates premium skincare manufacturing where COSRX and Innisfree control direct-to-consumer digital distribution.
China
Domestic cosmetics manufacturers absorb standardized gotu kola extracts through simplified NMPA botanical registration pathways. NMPA documentation requirements filter smaller traders from qualified vendor lists. The Yangtze River Delta anchors contract manufacturing clusters serving both domestic and export skincare brands.
United States
Health food companies procure bulk Centella powders for nutraceutical encapsulation with minimal regulatory friction. FDA cosmetic ingredient oversight applies primarily to topical finished goods rather than raw botanical imports. California-based direct-to-consumer wellness brands source through Asian extraction partners.
France
Parisian and Lyon-based formulators consolidate procurement toward vertically integrated extract producers with captive cultivation security. ECHA REACH compliance mandates heavy-metal and pesticide residue documentation. The Île-de-France region hosts premium skincare R&D facilities integrating supercritical CO2-derived actives.
Madagascar
Wild-harvested gotu kola collection sustains upstream supply for major active ingredient producers through captive farming partnerships. Collection permit restrictions and climate variability expose supply continuity risks. The Antananarivo-Toamasina corridor concentrates drying and initial processing infrastructure for export.
Centella Asiatica Market Competitive Environment
Vertically integrated chemical conglomerates and digital-native skincare specialists split the market into upstream supply security versus downstream margin capture. Three archetypes dominate: multinational ingredient suppliers with captive cultivation, Korean direct-to-consumer brands controlling pricing through owned channels, and Indian bulk extract traders competing on standardized commodity volumes. Competitive moves concentrate on backward integration into Madagascar farming partnerships and supercritical CO2 extraction capacity expansion.
Within the multinational ingredient tier, BASF anchors supply security through Indian Ocean cultivation networks. Among Korean digital-native specialists, COSRX exemplifies channel disintermediation through owned storefronts across Asian and North American markets. Indian bulk suppliers represented by Alchem International occupy commodity positioning in standardized powder segments serving North American nutraceutical demand.
| Leading Market Players |
|---|
| COSRX |
| Alchem International Pvt. Ltd. |
| BASF |
| The Face Shop |
| Earth Rhythm |
| L'Oreal |
| Innisfree |
| Youth Biotech CO., Ltd. |
| Himalaya Wellness |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in supercritical CO2 extraction infrastructure across Madagascar and Southeast Asia is compressing margins for commodity-grade suppliers while amplifying pricing power for certified producers with validated chromatographic capabilities. ECHA REACH documentation requirements and MFDS microbial testing mandates are forcing buyers toward qualified vendors, widening the spread between documented extract premiums and undifferentiated powder discounts.
Pricing Analysis
The customization-premium spread separates REACH-compliant extracts with full triterpenoid fingerprinting from standard hydroalcoholic concentrates lacking batch-specific documentation. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with South Korean cosmetics manufacturers absorbing steep premiums for MFDS-compliant serums. Cost compression in commodity powders is intensifying because Indian bulk suppliers are saturating North American nutraceutical channels. Health food companies exhibit the highest price sensitivity, while French and Korean premium formulators prioritize supply security over unit economics.
Supply Chain Analysis
Upstream wild-harvested gotu kola feedstock draws from Madagascar, Indonesia, and Sri Lankan collection zones where permit restrictions and monsoon variability constrain consistent availability. Raw material dependencies rest on dried aerial biomass, ethanol for hydroalcoholic processing, and supercritical CO2 equipment components anchored in German and Japanese manufacturing bases. Single-source vulnerability concentrates in Madagascar's Antananarivo-Toamasina corridor, where BASF and major ingredient producers have established captive farming partnerships. Distribution runs through integrated cosmetics manufacturers in Seoul and Paris, direct-to-consumer digital storefronts, and Asian duty-free retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers: ECHA REACH and MFDS certification requirements impose 18-24 month dossier timelines that filter opportunistic entrants and lock incumbent positions.
For Market Incumbents: Pre-empt synthetic peptide substitution threats by deepening supercritical CO2 capacity in Madagascar cultivation partnerships. Secure chromatographic fingerprinting talent pools before analytical chemist salary premiums erode mid-tier economics. Channel control through owned digital storefronts defends margin capture against wholesale disintermediation.
For New Entrants and Emerging Players: Scalp care oil formulations in K-beauty follicular treatment protocols represent the most penetrable entry point, bypassing saturated serum competition. China's NMPA simplified botanical registration pathway offers regulatory arbitrage against REACH-dominated European procurement. A formulation partnership with established Asian contract manufacturers accelerates commercialization without captive cultivation investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure as equipment lead times extend and analytical validation costs compound. Vertically integrated extract producers with Madagascar farming partnerships and in-house chromatographic capabilities present the strongest acquisition target archetype. The signal to watch is ECHA REACH substance evaluation deadline acceleration, which would force consolidation toward qualified vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Madagascar Cultivation | Captive farming partnerships secure wild-harvested gotu kola supply against climate and permit risks. |
| Supercritical CO2 Capacity Expansion | Solvent-free processing meets clean-label demands from K-beauty and Western natural cosmetics brands. |
| Direct-to-Consumer Digital Launch | Owned storefronts collapse wholesale layers and capture first-party customer data across Asian and North American markets. |
| Regulatory Dossier Acceleration | Parallel MFDS, NMPA, and FDA preparation compresses 18-24 month commercialization cycles for global entry. |
| Scalp Care Formulation Partnership | Lipid-soluble Centella actives penetrate K-beauty haircare protocols previously dominated by chemical growth agents. |
Study Parameters
The analysis maps extract-grade tiers, serum formulation categories, and powder commoditization segments, each validated through procurement directors at cosmetics manufacturers, regulatory affairs leads at extract suppliers, and chromatographic laboratory managers. Primary interviews with South Korean formulators, Madagascar cultivation partners, and Indian bulk traders combined with secondary validation from ECHA REACH substance evaluation databases, MFDS cosmetic ingredient filings, and NMPA botanical registration records. Bottom-up volume triangulation across cultivation acreage, extraction yields, and end-use consumption patterns converged with top-down value estimates from import-export customs data and premium skincare retail audits.
Assumptions held fixed include ECHA REACH enforcement timelines, Madagascar collection permit regimes, and supercritical CO2 equipment availability, while variables included NMPA pathway simplification pace and synthetic peptide substitution rates across mass-market skincare. The analytical framework modeled product type, application, form, and end-user segmentation dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit trends, with inputs from triterpenoid standardization cost curves and direct-to-consumer channel penetration rates.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on premium skincare, logistics costs from Indian Ocean shipping lanes, or ethanol feedstock pricing would shift the trajectory. Forecasts reflect these assumptions without contingency for abrupt regulatory harmonization or breakthrough synthetic alternatives. Cross-checking against customs trade data for gotu kola biomass and extract volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
Poultry Processing Product Market