
 Flower Pot Market | 2026-2036
Flower Pot Market Size, Share, and Industry Trends Forecast 2026-2036
Flower Pot Market Analysis
Subscription-based pot-and-plant pairing services is rebalancing how manufacturers capture recurring revenue beyond one-time container sales. Lechuza leverages its self-watering technology leadership to anchor premium positioning in European home gardening channels. HC Companies sustains broad distribution control across North American mass retail and independent nursery networks. Pöppelmann differentiates through deep manufacturing scale in injection-molded resin containers for professional landscaping clients.
A flower pot is a manufactured vessel, typically ranging from 100 milliliters to several hundred liters in internal volume, designed to contain soil and support plant root systems in non-ground environments. Production methods span slip-cast ceramic firing, blow-molded polypropylene forming, and pressed-fiber composite curing, with wall thickness and drainage porosity calibrated to plant species requirements. Plastic resin formulations currently lead volume shipments due to cost scalability and weather resistance, while terracotta segments retain margin concentration among specialty retailers serving heritage gardening enthusiasts. Ceramic categories occupy the premium tier in European and Japanese markets where frost-proof certification commands price separation. Small-to-medium sizes dominate home gardener transactions, though extra-large formats for commercial landscaping generate disproportionate profit per unit.
The EPA regulates phthalate content in polypropylene garden products under consumer safety mandates, while REACH compliance in Europe restricts heavy-metal pigments in glazed ceramic finishes. China's SAMR enforces GB standards for plastic recyclability labeling that reshape resin sourcing decisions for export-oriented manufacturers. India's BIS certification requirements for food-contact-grade polymers increasingly influence material selection even in non-edible horticulture applications. Stakeholders must monitor how extended producer responsibility frameworks in Germany and France redirect cost structures toward closed-loop recycling infrastructure.
Market Dynamics
Extended producer responsibility frameworks in Germany and France are forcing manufacturers to internalize end-of-life collection costs, compressing margins on conventional resin formulations while rewarding closed-loop recyclability investments.
Growth Catalysts
- REACH compliance mandates:Heavy-metal restrictions in glazed ceramic finishes are accelerating pigment substitution toward mineral-based alternatives, opening premium positioning for certified frost-proof suppliers.
- Self-watering reservoir integration:Capillary wick systems are displacing passive drainage in European balcony gardening segments, commanding 40-60% price premiums over standard injection-molded containers.
- Urban India residential adoption:Metropolitan balcony gardening is concentrating demand in Mumbai, Bangalore, and Delhi NCR corridors, pulling specialized small-format production toward sub-5-liter volume classes.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to naphtha cracking economics compress margin predictability for blow-molded volume producers serving mass retail channels.
- GB standards tightening:China's SAMR recyclability labeling requirements are fragmenting resin sourcing decisions, forcing export-oriented manufacturers to maintain dual formulation inventories.
- Terracotta substitution ceiling:Heritage gardening enthusiasts in Japan and Italy retain inelastic demand for traditional fired clay, capping polymer conversion in premium decorative segments.
Strategic Opportunities
- BIS certification alignment:India's food-contact-grade polymer standards are creating compliance arbitrage for manufacturers repurposing certified resin streams into horticulture applications.
- Subscription pairing services:Recurring-revenue pot-and-plant bundling is displacing one-time container transactions in North American direct-to-consumer channels, reducing customer acquisition cost amortization periods.
- Pressed-fiber composite convergence:Molded pulp technologies from food packaging are cross-applying into biodegradable horticulture containers, targeting municipal composting infrastructure in California and Oregon.
Industry Challenges
- Dual certification timelines:Simultaneous EPA phthalate review and REACH heavy-metal compliance are extending product launch cycles by 8-14 months for multi-territory suppliers.
- Capillary system integration complexity:Self-watering mechanism assembly requires precision molding tolerances and specialized wick material sourcing that strain legacy injection-molding footprints.
- Closed-loop infrastructure gaps:Collection and reprocessing networks for post-consumer polypropylene pots remain underdeveloped outside German and Dutch municipal systems, limiting circularity claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flower Pot Market |
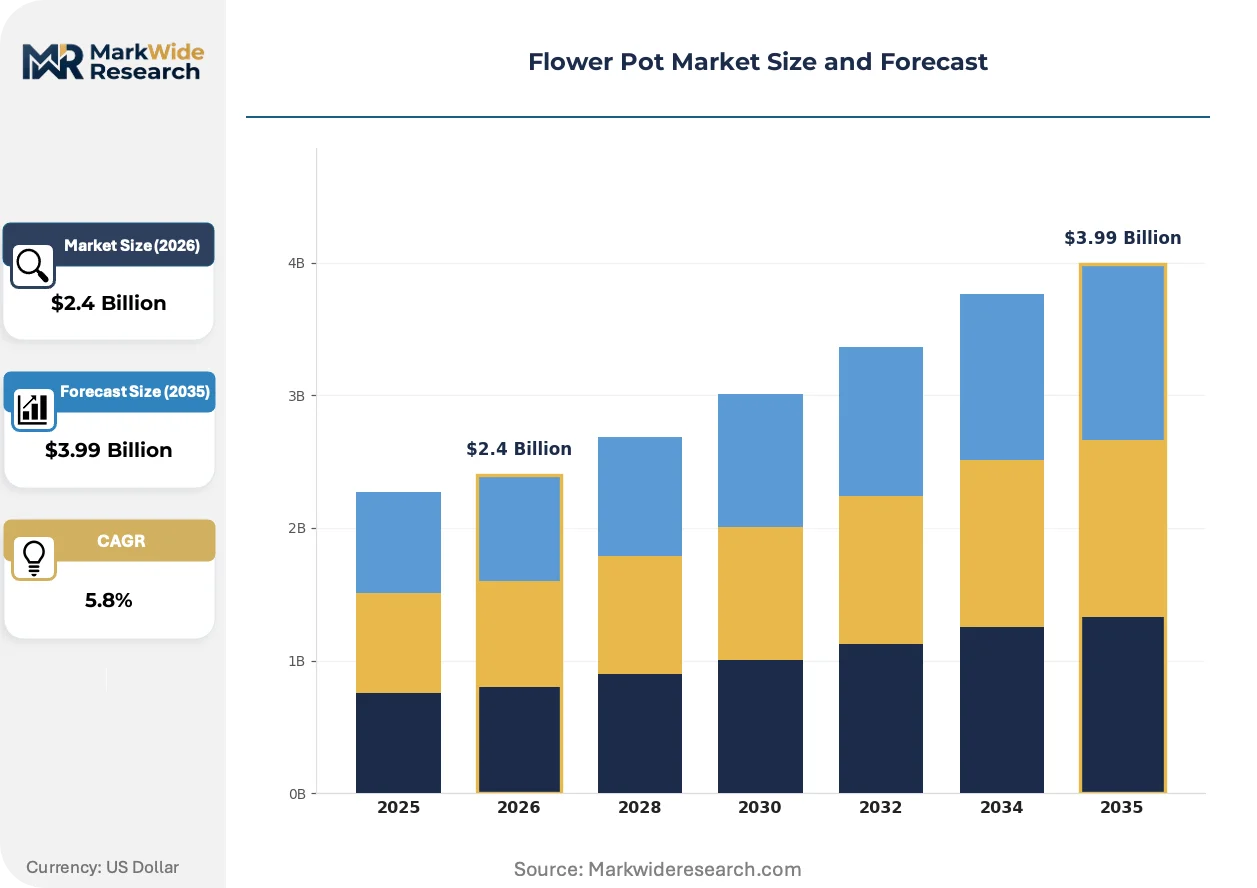
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terracotta, Plastic, Ceramic, Metal Material: Clay, Resin, Fiberglass, Stone Size: Small, Medium, Large, Extra Large End User: Home Gardeners, Landscaping Professionals, Retailers, Nurseries |
| Companies Covered | HC Companies, Pöppelmann, Lechuza, Fiskars Group, Scheurich Group, Keter Group, Bloem Living, China Xiamen Roommu Horticulture Co., Ltd., Elho, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flower Pot Market Emerging Trajectories
Material science convergence with digital commerce infrastructure is compressing traditional channel hierarchies while elevating performance-certified products to premium tier dominance.
Biodegradable molded pulp formulations are expanding into commercial landscaping procurement specifications. Municipal groundskeepers in California and Pacific Northwest corridors are piloting seasonal replacement programs that eliminate container retrieval logistics. The structural consequence is expanding into landfill diversion reporting requirements that polymer containers cannot satisfy.
China's GB standards for plastic recyclability are tightening material specifications for export-oriented manufacturers. SAMR enforcement of labeling mandates is reshaping resin compound selection toward single-polymer streams that municipal sorting facilities can process. Small-to-medium ceramic exporters face disproportionate compliance burden as testing documentation requirements multiply.
Direct-to-consumer subscription bundling is displacing garden-center bulk purchasing among urban apartment dwellers. Millennials in metropolitan Germany and US coastal cities are prioritizing curated plant-pot pairings over self-directed container selection. This behavioral pivot concentrates margin capture with vertically integrated brands that control both horticultural supply and vessel manufacturing.
Flower Pot Market Segmentation
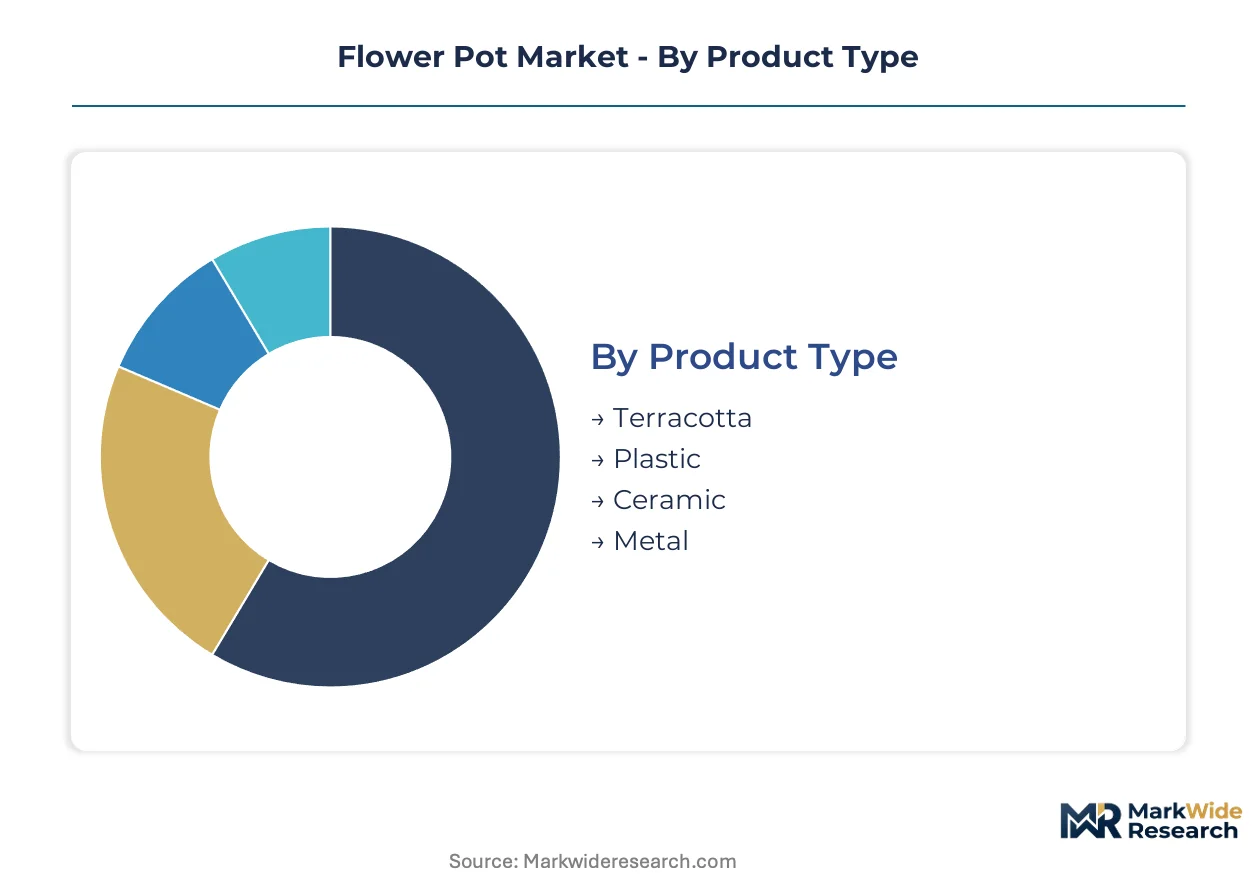
Segmentation in the flower pot market reveals how material science, scale economics, and end-use specialization create distinct competitive arenas. Manufacturers must calibrate formulation investments, molding tolerances, and distribution channels against the specific performance requirements and purchasing behaviors of each segment cluster.
Product Type:
Customization versus standardization tension runs deepest here — terracotta demands artisan firing cycles while plastic leverages mass-production repeatability.
- Terracotta:Fired clay construction with porous walls enables natural root aeration and moisture regulation. Heritage gardening communities in Italy and Japan sustain demand despite higher unit costs and frost-susceptibility, with collectors paying premiums for hand-thrown regional styles.
- Plastic:Injection-molded polypropylene and blow-molded polyethylene dominate volume shipments through weather resistance and cost scalability. India's metropolitan balcony gardening corridors are pulling specialized small-format production toward sub-5-liter classes with self-watering reservoir compatibility.
- Ceramic:Glazed stoneware and porcelain formulations offer frost-proof certification in European markets. REACH heavy-metal restrictions are accelerating mineral-based pigment substitution among premium suppliers.
- Metal:Galvanized steel and aluminum containers serve commercial landscaping with durability specifications. Zinc and copper alloys command decorative premiums in North American direct-to-consumer channels.
Most installed capacity flows through plastic. Expansion is steepest in ceramic frost-proof certified lines.
Material:
Cost tier stratification separates commodity resin streams from performance-engineered compounds and heritage extraction sources.
- Clay:Natural earthenware and stoneware deposits feed terracotta and ceramic production. Traditional sourcing from Mediterranean and Mexican extraction sites faces transport cost pressure against regional shale alternatives.
- Resin:Polypropylene and polyethylene formulations lead volume economics with weather resistance and color stability. China's GB standards for recyclability labeling are fragmenting sourcing decisions toward single-polymer streams.
- Fiberglass:Reinforced polymer composites enable large-format commercial planters with structural strength at reduced weight. Professional landscaping procurement in Germany and France specifies these for rooftop installations with load-bearing constraints.
- Stone:Carved granite, limestone, and concrete composites serve permanent installation contracts. Municipal groundskeepers in California pilot seasonal replacement programs that favor biodegradable alternatives over stone retrieval logistics.
Resin commands the broadest manufacturing footprint. Fiberglass is gaining share fastest in commercial specification channels.
Size:
Volume concentration versus margin per unit creates divergent profitability profiles across the dimensional spectrum.
- Small:Sub-5-liter vessels target apartment balcony gardening and desktop cultivation. Subscription pot-and-plant pairing services in North American direct-to-consumer channels concentrate transactions in this class.
- Medium:5-20 liter containers balance root volume with portability for residential patio use. European garden-center retail corridors in Germany show concentration here for self-watering reservoir integration.
- Large:20-50 liter formats serve established home gardeners with specimen plant requirements. Terracotta substitution ceilings persist among heritage enthusiasts despite polymer cost advantages.
- Extra Large:50+ liter containers generate disproportionate profit per unit in commercial landscaping. Pressed-fiber composite technologies from food packaging are cross-applying into biodegradable specifications for municipal procurement.
Small and medium sizes absorb the highest transaction velocity. Extra large formats deliver the steepest margin expansion trajectory.
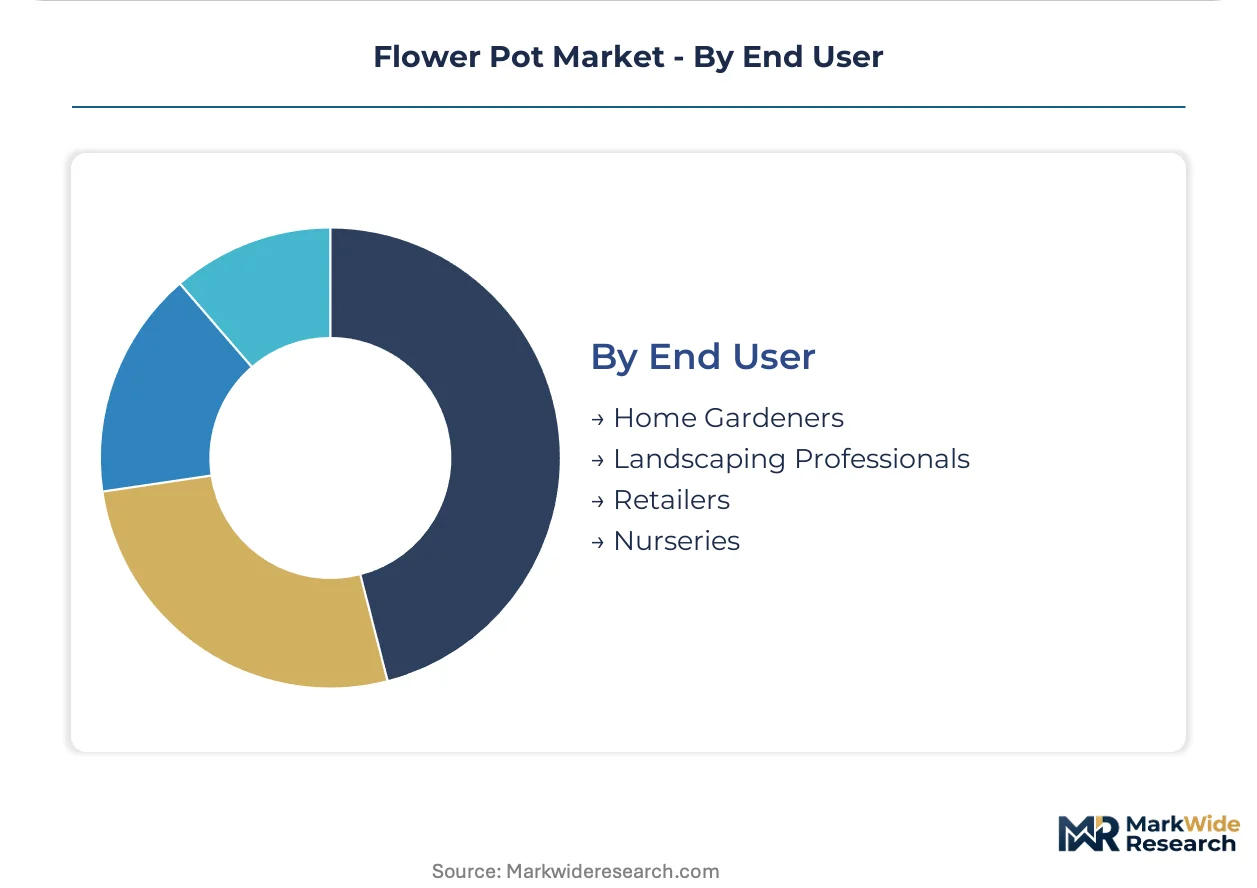
End User:
Customer type determines channel configuration — direct-to-consumer bundling versus wholesale nursery supply versus municipal procurement compliance.
- Home Gardeners:Individual consumers purchasing through retail, e-commerce, and subscription services. Millennial apartment dwellers in metropolitan Germany and US coastal cities prioritize curated plant-pot pairings over self-directed selection.
- Landscaping Professionals:Contract installers specifying durability, drainage engineering, and installation logistics. Extended producer responsibility frameworks in France are forcing internalization of end-of-life collection costs into specification decisions.
- Retailers:Mass merchants and specialty garden centers managing inventory turnover and seasonal assortment. Lechuza anchors premium positioning through self-watering technology leadership in European home gardening channels.
- Nurseries:Horticultural producers requiring propagation efficiency and transplant compatibility. HC Companies sustains broad distribution control across North American independent nursery networks through scale and logistics integration.
Home gardeners generate the highest transaction frequency. Landscaping professionals command the steepest expansion curve through specification lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's metropolitan balcony gardening corridors are pulling small-format production volumes that Germany's frost-proof ceramic certification premiums cannot match, while China's GB standards reshape export-oriented resin sourcing across multiple sourcing basins.
Germany
Self-watering reservoir integration commands 40-60% price premiums in metropolitan garden-center retail corridors. Extended producer responsibility frameworks under France's environmental regulations are forcing German manufacturers to internalize end-of-life collection costs. Bavaria and North Rhine-Westphalia concentrate injection-molded resin production for professional landscaping clients facing specification compliance pressures.
China
SAMR enforcement of GB recyclability labeling mandates is fragmenting resin compound selection toward single-polymer streams. Municipal sorting facility compatibility requirements are reshaping export-oriented manufacturer formulation decisions. Yangtze River Delta and Pearl River Delta production clusters maintain dual inventory streams to serve divergent domestic and export certification requirements.
United States
Subscription pot-and-plant pairing services are displacing garden-center bulk purchasing among urban apartment dwellers in coastal metropolitan areas. EPA phthalate content regulations under consumer safety mandates constrain polypropylene garden product formulations. California and Pacific Northwest municipal groundskeepers are piloting pressed-fiber composite seasonal replacement programs that eliminate container retrieval logistics.
India
Residential balcony gardening adoption is accelerating in Mumbai, Bangalore, and Delhi NCR corridors, pulling specialized small-format production toward sub-5-liter volume classes. BIS certification requirements for food-contact-grade polymers increasingly influence material selection even in non-edible horticulture applications. Maharashtra and Karnataka manufacturing clusters are repurposing certified resin streams into horticulture applications to capture compliance arbitrage.
Japan
Heritage gardening enthusiasts retain inelastic demand for traditional fired clay, capping polymer conversion in premium decorative segments. METI standards and JIS certification frameworks influence quality benchmarks for ceramic frost-proof performance. Kanto and Kansai metropolitan areas sustain collector premiums for hand-thrown regional terracotta styles despite higher unit costs.
Flower Pot Market Vendor Landscape
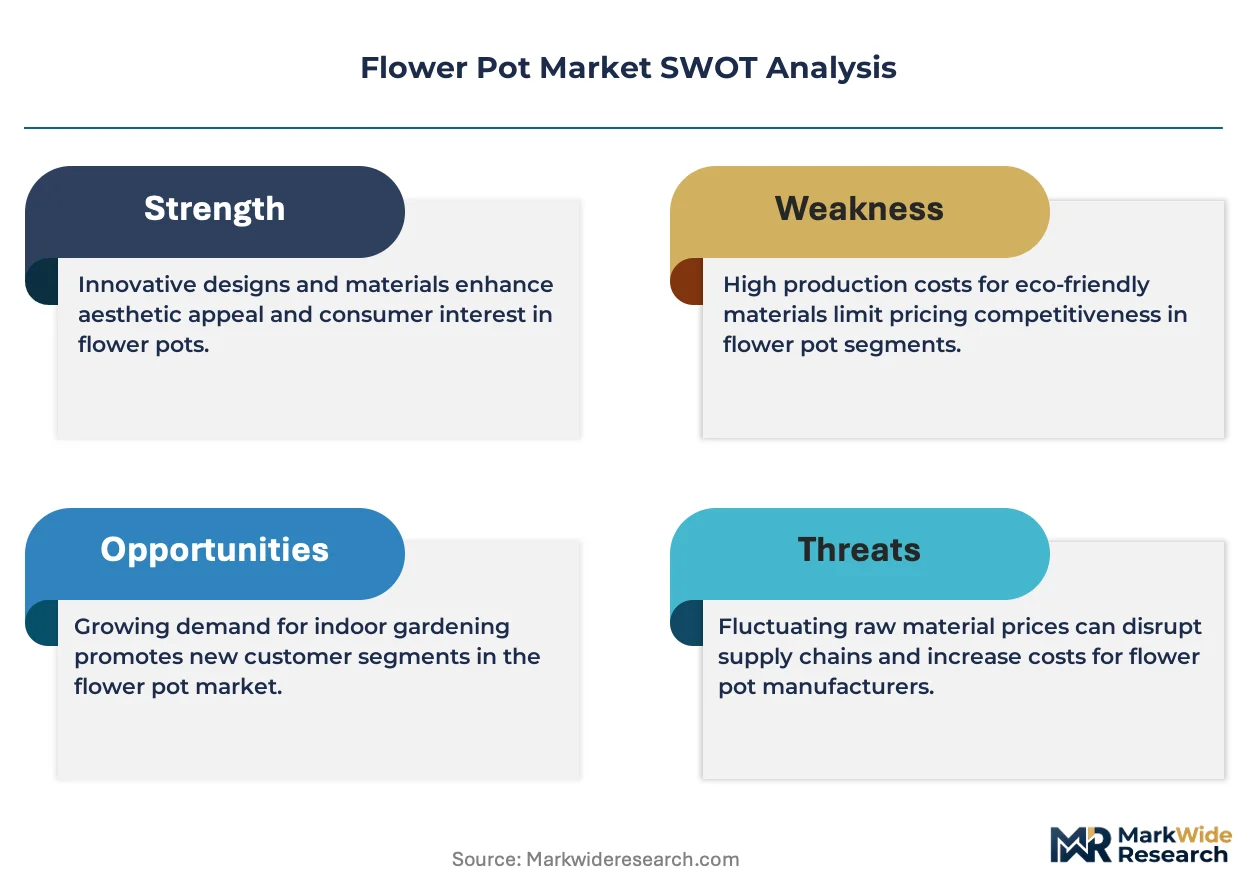
Top-tier vendors anchor premium technology positioning, while mid-scale fabricators compete on distribution breadth and manufacturing scale. The vendor base organizes around three strategic archetypes: self-watering technology specialists commanding price premiums, broad-distribution mass-market suppliers, and injection-molded resin scale players serving professional landscaping. Competitive moves concentrate on portfolio diversification toward subscription bundling capabilities and backward integration into resin formulation to manage compliance fragmentation.
Among European technology-focused specialists, Lechuza occupies a position exemplifying premium-tier self-watering reservoir integration, while Scheurich Group represents heritage ceramic manufacturing with frost-proof certification concentration. HC Companies and Pöppelmann anchor the scale-driven manufacturing tier, with the former exemplifying broad North American distribution control and the latter representing deep injection-molded resin capabilities for professional landscaping procurement. These four named entities collectively illustrate how competitive positioning stratifies across technology premium, heritage craftsmanship, and manufacturing scale vectors.
| Leading Market Players |
|---|
| HC Companies |
| Pöppelmann |
| Lechuza |
| Fiskars Group |
| Scheurich Group |
| Keter Group |
| Bloem Living |
| China Xiamen Roommu Horticulture Co., Ltd. |
| Elho |
| Others |
Supply Flow & Price Mechanics
Polypropylene resin feedstock costs cascade through three distinct pricing tiers as naphtha cracking economics in Asian production basins transmit volatility downstream to blow-molded volume manufacturers and premium self-watering specialists alike.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for injection-molded resin containers. Three-tier pricing structure across premium self-watering, standard weather-resistant, and economy disposable tiers separates Lechuza's capillary reservoir systems from mass-retail polypropylene lines. Cost compression in the standard tier intensifies because GB standards compliance requires dual formulation inventories. Home gardeners in urban India exhibit highest price sensitivity, while German frost-proof ceramic collectors show least.
Supply Chain Analysis
REACH heavy-metal certification and BIS food-contact-grade polymer qualification gate entry for European and Indian procurement channels respectively. Resin compounding concentrates in China, Germany, and the United States. Raw material draws from naphtha crackers, mineral-based pigment streams, and capillary wick textiles. Single-source vulnerability runs through Yangtze River Delta resin production clusters exposed to SAMR enforcement shifts. Distribution runs through garden-center retail corridors in metropolitan Germany and direct-to-consumer subscription channels in coastal US cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flower pot market compounds steadily as urban balcony gardening penetration in dense metropolitan corridors generates recurring replacement demand for container vessels.
For Market Incumbents: Acquire self-watering mechanism IP and specialized wick material sourcing capabilities to defend against biodegradable molded pulp substitution threatening polymer volume positions. Extend backward integration into single-polymer resin streams to neutralize GB standards fragmentation costs. For New Entrants and Emerging Players: Subscription fulfillment partners represent the fastest channel to scale in North American direct-to-consumer corridors. Target India's sub-5-liter balcony gardening segment where BIS certification arbitrage creates entry wedge against established resin suppliers. Lead with curated plant-pot pairing services to bypass garden-center distribution bottlenecks. For Investors and Strategic Acquirers: Consolidation pressure builds where extended producer responsibility frameworks force end-of-life cost internalization onto sub-scale resin manufacturers. The 5-10 year window favors acquisition of injection-molded scale players with municipal recycling infrastructure relationships. Watch California and Oregon municipal procurement shifts toward pressed-fiber seasonal replacement programs as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Self-Watering Technology Acquisition | Capillary reservoir IP anchors 40-60% price premiums in European balcony gardening channels. |
| Single-Polymer Resin Stream Conversion | GB standards compliance in China eliminates dual inventory carrying costs for export-oriented manufacturers. |
| Subscription Bundling Platform Launch | Recurring revenue models reduce customer acquisition cost amortization in North American direct-to-consumer markets. |
| Pressed-Fiber Composite Capacity Buildout | Biodegradable specifications capture California municipal groundskeeper procurement diverting from polymer retrieval logistics. |
| BIS Certification Arbitrage Exploitation | Food-contact-grade polymer repurposing into horticulture applications opens margin expansion in Maharashtra manufacturing clusters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary conversations with injection-molding plant managers, garden-center category buyers, municipal groundskeeper procurement officers, and self-watering technology R&D directors informed demand-side validation. Secondary sources included customs trade data for resin and ceramic imports, EPA phthalate regulatory filings, REACH compliance documentation, and SEC 10-K disclosures from listed container manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across material and end-use dimensions.
Segment-weighting approaches distributed value and volume across product type, material formulation, size class, and end-user archetype dimensions throughout the forecast period. CAGRs derived from regression analysis against urbanization rates, balcony gardening adoption curves, and regulatory implementation timelines. Industry-specific inputs included naphtha cracking spread forecasts and municipal composting infrastructure buildout schedules in target geographies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR enforcement intensity on GB recyclability labeling and EPR framework expansion beyond Germany and France. Deviation in resin feedstock price volatility or capillary wick material supply constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Canada Animal Protein Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market