
 Live Goods Market | 2026-2036
Live Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Live Goods Market Analytics
The EU Green Deal is hardening phytosanitary requirements for cross-border plant shipments, forcing nurseries to invest in certified pest-free propagation. Amway leverages its direct-sales infrastructure to move live herb kits through wellness channels in North America. Herbalife sustains a parallel botanical supply chain for aloe and botanical extracts that shares cold-chain logistics with live goods distributors. Forever Living anchors its vertically integrated aloe operations in Texas and the Dominican Republic, controlling propagation through retail shelf.
Live goods encompass physiologically active plants, seeds, flowers, and shrubs maintained in viable growing condition from harvest through point of sale, requiring controlled humidity between 85-95% and temperature bands of 4-12°C for temperate species to prevent root desiccation and floral abortion. These products serve commercial landscapers, retail garden centers, and direct-to-homeowner channels where plant establishment success determines repeat purchase rates. The plants and flowers segment leads value contribution due to higher per-unit margins and impulse purchase velocity at retail, while the online distribution channel registers the fastest structural expansion as last-mile cold-chain solutions mature for containerized live shipments. Nurseries and garden centers remain the dominant end-user category, though homeowner direct acquisition is displacing traditional wholesale intermediaries in suburban and exurban markets.
The USDA's Animal and Plant Health Inspection Service enforces quarantine protocols under the Plant Protection Act, restricting interstate movement of host material for regulated pests such as the spotted lanternfly and sudden oak death pathogen. The European Commission's Plant Health Regulation (EU) 2016/2031 mandates pre-export inspection and passport documentation for all live plant transfers within the single market, raising compliance costs for non-certified growers. Stakeholders must monitor evolving biosecurity perimeters and decide whether to absorb certification overhead or exit restricted species categories before regulatory deadlines lock in market access barriers.
Market Dynamics
EU Green Deal biodiversity mandates are compressing propagation timelines and forcing nursery certification upgrades across the single market, while Dutch auction concentration funnels root stock pricing power toward Rotterdam's distribution clusters.
Growth Catalysts
- Native perennial demand:North American suburban homeowners prioritize drought-tolerant indigenous species for water-restricted landscapes, expanding contract volumes for specialized growers.
- Edible landscaping:Residential developers integrate food-producing shrubs into multi-family common areas, creating specification pull-through for compact fruit stock.
- EU Plant Health Regulation (EU) 2016/2031:Mandatory passport documentation creates competitive moats for certified propagators, squeezing uncertified competitors from cross-border supply chains.
Market Restraints
- Input cost volatility:Peat substrate and propagation tray prices fluctuate with energy-intensive extraction and polymer feedstock costs, compressing margin at small-scale operations.
- Supply concentration risk:Dutch auction houses control 70 percent of EU root stock liquidity, creating single-point vulnerability for German and French garden center procurement.
- Phytosanitary friction:USDA APHIS quarantine protocols for spotted lanternfly host material restrict interstate shipment of select maple and stone fruit varieties, fragmenting domestic supply.
Strategic Opportunities
- Direct-to-homeowner channels:Last-mile cold-chain maturation enables subscription live goods delivery, bypassing wholesale garden center markups in suburban markets.
- Wellness crossover applications:Aloe and medicinal herb kits integrate with direct-sales wellness infrastructure, opening non-traditional retail pathways.
- EU Green Deal restoration mandates:Member state biodiversity targets create public procurement demand for certified native stock in riparian and pollinator corridor projects.
Industry Challenges
- Certification timeline compression:EU Plant Health Regulation compliance requires 18-24 month propagation facility upgrades, straining working capital for mid-tier nurseries.
- Cold-chain capex intensity:Containerized humidity control systems for 85-95 percent relative humidity maintenance demand refrigerated truck fleet investment that exceeds small distributor balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live Goods Market |
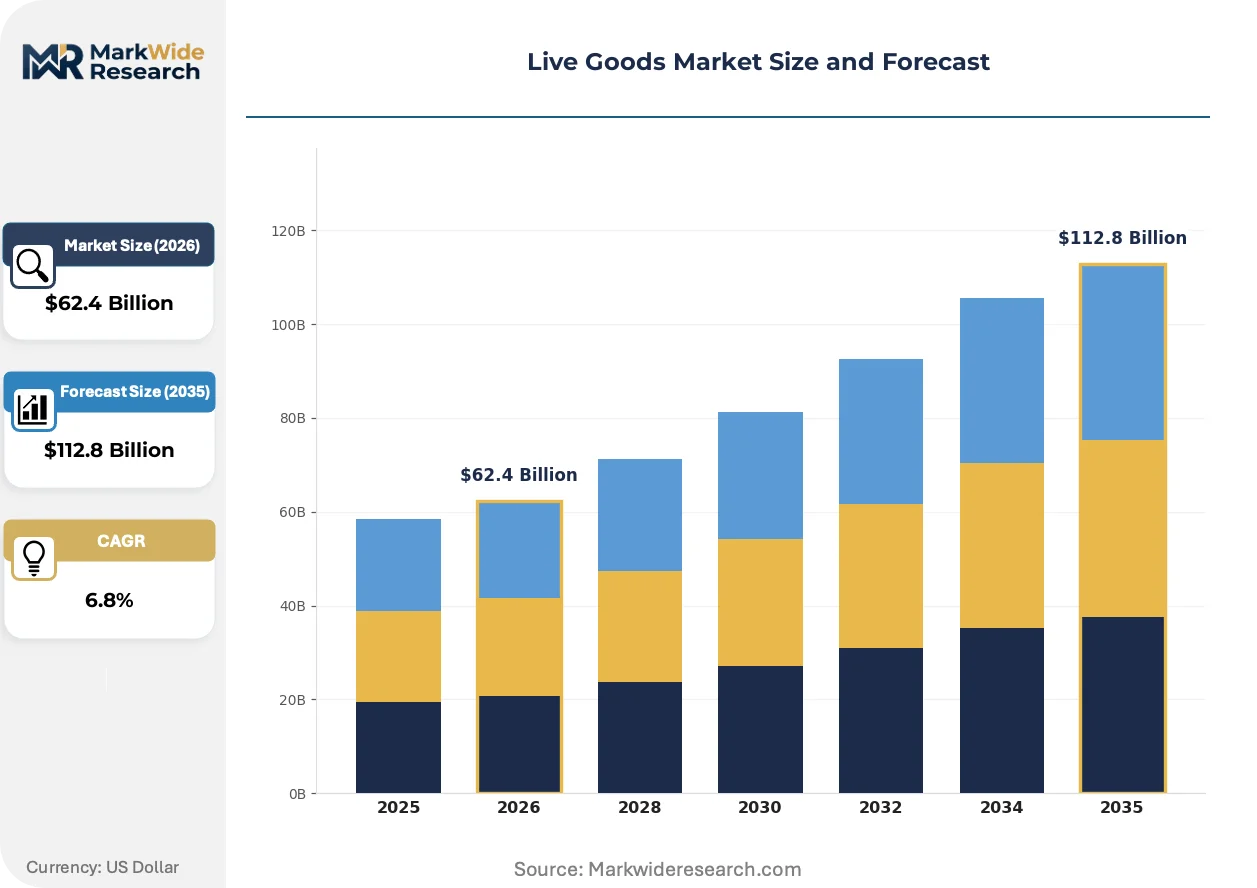
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plants, Seeds, Flowers, Shrubs Distribution Channel: Retail, Wholesale, Online, Direct Sales End User: Nurseries, Garden Centers, Landscapers, Homeowners Packaging Type: Bulk, Retail Packs, Pots, Trays |
| Companies Covered | Young Living, Nu Skin, LiveGood, Primerica, Melaleuca, Amway, Mary Kay, Forever Living, Herbalife, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live Goods Market Evolving Landscape
Propagation automation and digital phenotyping are compressing varietal development cycles, while regulatory documentation requirements digitize supply chain traceability from lab to retail shelf.
Sensor-driven climate control is overtaking manual greenhouse management in large-scale propagation facilities. Commercial nurseries in the Netherlands deploy IoT-enabled humidity and temperature modulation to maintain 4-12°C bands for temperate species. This precision is enabling year-round production that compresses seasonal pricing volatility and extends contract fulfillment windows.
EU Green Deal biodiversity targets are hardening nursery stock certification requirements across member states. The European Commission mandates pre-export inspection and digital passport documentation for all live plant transfers, raising compliance overhead. German and French propagation labs are responding by consolidating certification in-house rather than outsourcing to third-party inspectors.
Homeowner direct acquisition is displacing traditional wholesale intermediaries in suburban and exurban markets. Retail garden centers face margin compression as last-mile cold-chain solutions mature for containerized live shipments. This channel rotation is most visible in North American markets where subscription herb kit services bypass brick-and-mortar markup structures.
Live Goods Market Segmentation
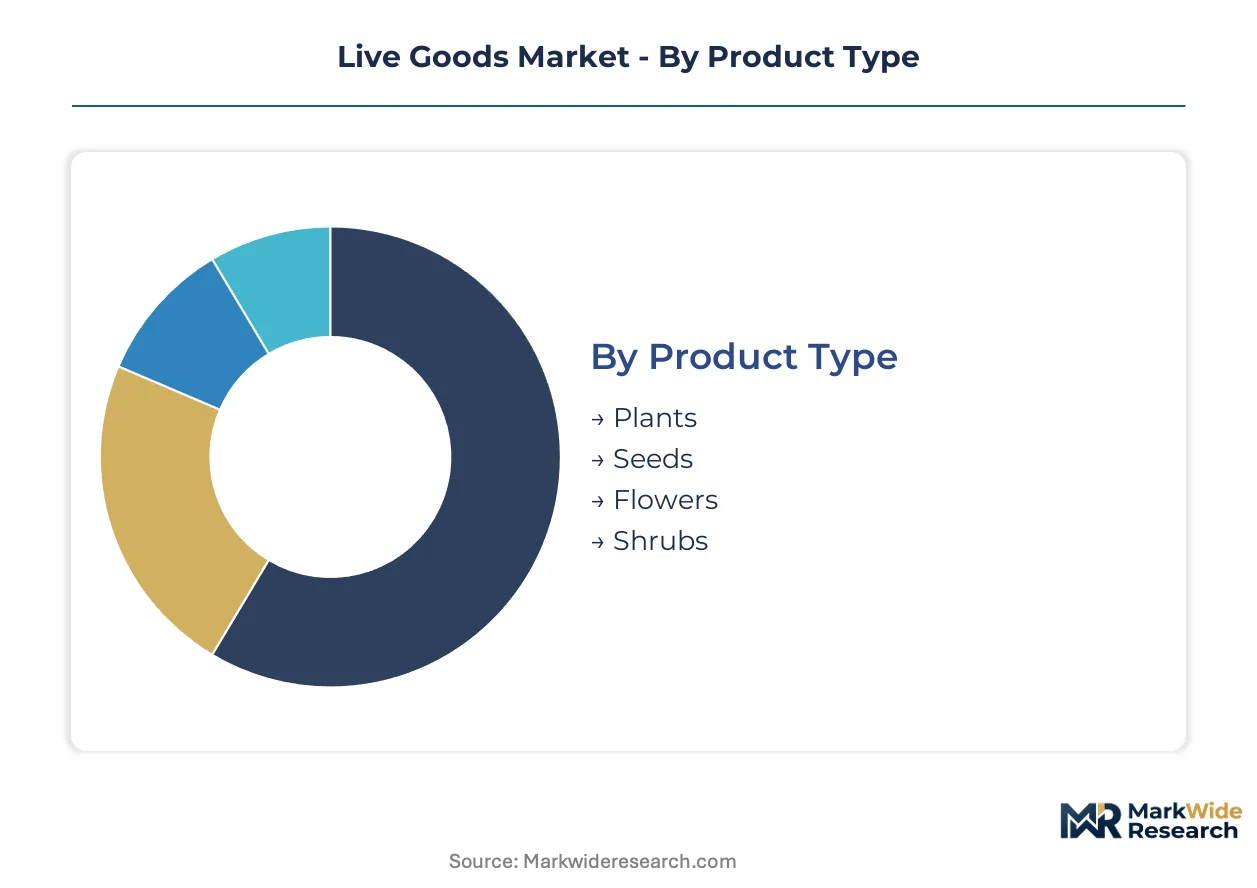
Segmentation in live goods determines capital allocation across propagation infrastructure, cold-chain logistics, and certification compliance. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Capital intensity peaks with physiologically active inventory requiring continuous climate control through the value chain.
- Plants:Temperate species demand 85-95% relative humidity and 4-12°C temperature bands to prevent root desiccation. North American suburban homeowners drive contract volumes for drought-tolerant native perennials as water restrictions harden.
- Flowers:High per-unit margins and impulse purchase velocity at retail garden centers define this segment. Dutch auction houses concentrate pricing power for cut flowers and bedding stock distributed across Germany, France, and the United Kingdom.
- Seeds:Lower cold-chain burden enables decentralized packaging and longer distribution radii.
- Shrubs:Extended nursery holding periods tie up working capital in field-grown inventory.
Plants absorb the bulk of installed propagation capacity; flowers are expanding most quickly through retail impulse channels.
Distribution Channel:
Channel selection dictates last-mile infrastructure requirements and margin capture points.
- Online:Subscription herb kit services leverage maturing containerized cold-chain solutions for direct-to-homeowner delivery. This channel bypasses traditional wholesale markups in suburban and exurban markets.
- Retail:Garden centers depend on refrigerated truck fleets and humidity-controlled display infrastructure. Brick-and-mortar locations face margin compression as digital channels erode foot traffic.
- Wholesale:Dutch auction houses control root stock liquidity for German and French procurement.
- Direct Sales:Wellness-oriented aloe and medicinal herb kits integrate with direct-sales infrastructure in North America.
Retail commands the deepest cold-chain investment; online climbs the fastest as logistics solutions mature.
End User:
Customer type determines specification complexity and repeat purchase economics.
- Homeowners:Direct acquisition is displacing wholesale intermediaries in suburban markets. Edible landscaping specifications for multi-family common areas create pull-through for compact fruit stock.
- Nurseries:EU Plant Health Regulation compliance requires 18-24 month facility upgrades for passport documentation capabilities.
- Garden Centers:Procurement concentrates through Rotterdam distribution clusters for EU root stock.
- Landscapers:Commercial specifications for native stock in riparian and pollinator corridor projects align with EU Green Deal restoration mandates.
Nurseries anchor certification-heavy supply; homeowners gain share fastest through channel disintermediation.
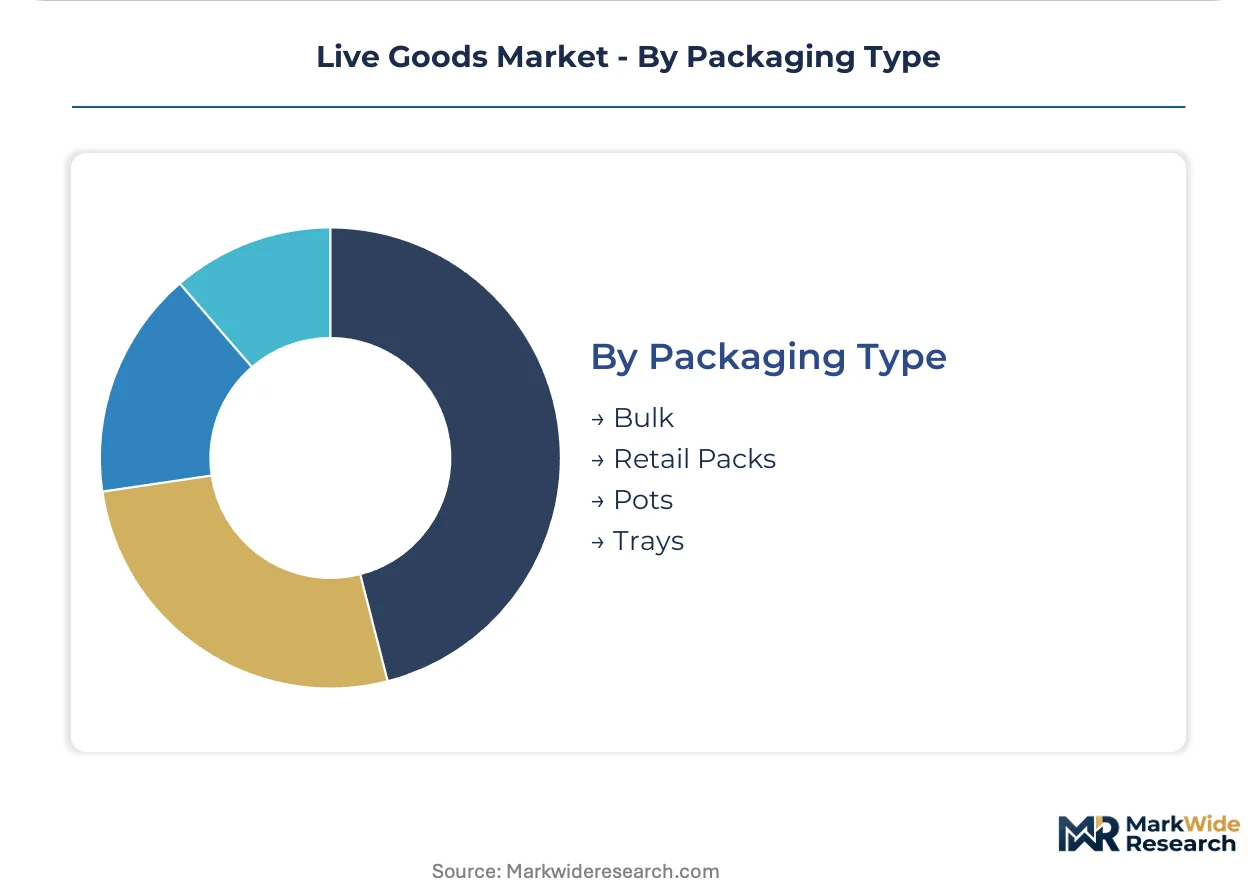
Packaging Type:
Packaging format shapes handling automation and per-unit logistics cost.
- Pots:Individual containerization enables precision humidity control for high-value temperate species. Retail garden centers favor this format for display aesthetics and reduced transplant shock.
- Trays:Modular propagation systems support IoT-enabled climate modulation in Dutch greenhouse facilities. Automation compatibility drives adoption in large-scale commercial nurseries.
- Bulk:Reduced per-unit packaging cost suits landscape-scale projects with immediate installation.
- Retail Packs:Consumer-facing formats require branded shelf-ready presentation and barcode traceability.
Pots carry the highest packaging cost burden; trays scale fastest through propagation automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's auction houses and propagation labs anchor root stock distribution across northwestern Europe, while North American demand concentrates in suburban corridors where direct-to-homeowner channels displace traditional wholesale intermediaries.
United States
Suburban homeowners in water-restricted southwestern states drive contract volumes for drought-tolerant native perennials. The USDA's Animal and Plant Health Inspection Service enforces quarantine protocols under the Plant Protection Act, restricting interstate movement of host material for the spotted lanternfly. Greater Phoenix and Dallas-Fort Worth corridors host specialized growers supplying retail garden centers with climate-adapted stock.
Netherlands
Dutch auction houses control the majority of EU root stock liquidity, funneling pricing power toward Rotterdam distribution clusters. The EU Green Deal's biodiversity targets harden nursery stock certification requirements across member states. Westland greenhouse complexes deploy IoT-enabled climate modulation to maintain precise humidity and temperature bands for year-round temperate species production.
Germany
German garden centers procure root stock through Rotterdam distribution clusters, creating procurement concentration risk for domestic retailers. The European Commission's Plant Health Regulation mandates pre-export inspection and passport documentation for all live plant transfers within the single market. Bavarian propagation labs respond by consolidating certification capabilities in-house rather than outsourcing to third-party inspectors.
United Kingdom
UK retailers source bedding stock and cut flowers through Dutch auction channels, though post-trade friction has altered traditional procurement patterns. EU Plant Health Regulation compliance requirements raise overhead for cross-border shipments from continental suppliers. Kent and Sussex nursery clusters specialize in ornamental propagation for domestic garden center distribution.
France
French landscapers specify native stock for riparian and pollinator corridor projects aligned with EU Green Deal restoration mandates. The country's national phytosanitary regulator enforces digital passport documentation for all live plant transfers, squeezing uncertified competitors from supply chains. Provence-Alpes-Côte d'Azur propagation facilities concentrate on Mediterranean-adapted species for regional retail distribution.
Live Goods Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and cold-chain infrastructure dimensions, with Dutch auction houses and vertically integrated wellness distributors occupying distinct tier positions. The vendor base fragments across direct-sales networks, retail garden center suppliers, and specialized propagation facilities. Three archetypes dominate: auction-mediated bulk distributors, wellness-channel direct marketers, and certified propagation specialists. Competitive moves concentrate on certification compliance investments and last-mile cold-chain capacity expansion.
Within the wellness-channel tier, Amway leverages its direct-sales infrastructure to move live herb kits through non-traditional retail pathways. Herbalife sustains a parallel botanical supply chain for aloe and botanical extracts. Forever Living anchors vertically integrated aloe operations in Texas and the Dominican Republic, representing captive supply chain control from propagation through retail shelf.
| Leading Market Players |
|---|
| Young Living |
| Nu Skin |
| LiveGood |
| Primerica |
| Melaleuca |
| Amway |
| Mary Kay |
| Forever Living |
| Herbalife |
| Others |
Value Network & Pricing Analysis
Skilled propagation technicians concentrated in the Netherlands' Westland greenhouse corridor command wage premiums that compress margin spreads between economy-grade bedding stock and certified passport-compliant inventory. Labor-cost differentials between Dutch-certified facilities and uncertified Eastern European competitors widen pricing-tier spreads as EU Plant Health Regulation compliance overhead accumulates.
Pricing Analysis
Plant-establishment success rates anchor value-based pricing for live goods, with subscription herb kit providers capturing recurring revenue streams against transactional garden center sales. Three-tier pricing structure across certified passport stock, standard nursery-grade inventory, and economy bedding plants reflects certification grade and cold-chain integrity. Cost compression in the economy tier intensifies because peat substrate and polymer propagation tray prices track energy-intensive extraction and feedstock costs. Retail garden centers exhibit highest price sensitivity due to margin compression from direct-to-homeowner channel erosion, while commercial landscapers prioritize establishment guarantees over per-unit cost.
Supply Chain Analysis
Peat substrate supply rests on extraction operations in Canada, Ireland, and the Baltic states, where environmental licensing constraints tighten feedstock availability. Root stock propagation draws from Dutch greenhouse complexes, Belgian container nurseries, and specialized field-grown operations in the United States Pacific Northwest. Single-source vulnerability concentrates in Rotterdam auction houses controlling EU root stock liquidity. Distribution runs through refrigerated truck fleets maintaining 85-95% humidity bands, with last-mile containerized solutions emerging for direct-to-homeowner subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The live goods market functions as a cost-of-compliance story where EU Plant Health Regulation certification creates durable barrier-to-entry moats for passport-compliant propagators. Capital deployment favors players with absorbed certification overhead versus competitors facing facility upgrade timelines.
For Market Incumbents: Anticipate channel disintermediation pressure from maturing direct-to-homeowner cold-chain solutions by consolidating certification capabilities in-house rather than outsourcing inspection overhead. Prioritize backward integration into propagation automation and IoT-enabled climate modulation to compress varietal development cycles against emerging digital phenotyping competitors. Lock in long-term contract volumes with commercial landscapers specifying native stock for EU Green Deal restoration mandates. For New Entrants and Emerging Players: The mid-market price-point gap between premium certified passport stock and economy-grade uncertified inventory offers white-space positioning for hybrid certification models targeting suburban homeowner direct acquisition. Target North American water-restricted corridors where drought-tolerant native perennial demand outstrips specialized grower capacity. Pursue wellness-channel partnerships for aloe and medicinal herb kit distribution through established direct-sales infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated propagation-to-retail operators given EU biodiversity target enforcement accelerating certification consolidation. Long-term viability across the analysis window favors players with captive cold-chain logistics and in-house passport documentation capabilities. Watch Dutch auction house pricing power erosion as German and French garden centers diversify procurement toward certified regional propagation labs.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Facility Upgrade | EU Plant Health Regulation compliance creates competitive moats for passport-capable propagators. |
| Direct-to-Consumer Channel Launch | Subscription herb kits bypass wholesale markups in suburban North American corridors. |
| Propagation Automation Investment | IoT-enabled climate modulation compresses seasonal pricing volatility for temperate species. |
| Wellness Infrastructure Partnership | Aloe and medicinal herb kits leverage established direct-sales distribution networks. |
| Native Stock Specification Capture | EU Green Deal restoration mandates create public procurement demand for certified inventory. |
Research Methodology
Independent corroboration across propagation facility operators, retail garden center procurement managers, and commercial landscaping specification directors underwrites the qualitative findings. Primary interviews with Dutch auction house trading specialists, German nursery certification officers, and North American direct-to-consumer logistics providers combined with secondary validation from USDA APHIS quarantine protocols, EU Commission Plant Health Regulation filings, and customs trade data for peat substrate and propagation equipment. Bottom-up volume modeling across product type, distribution channel, and end-user segments triangulates against top-down market sizing.
Historical reference periods anchored the forecast window to pre-regulatory and post-implementation phases of EU Plant Health Regulation enforcement. The analytical framework models segmentation across physiologically active inventory categories, cold-chain infrastructure tiers, and certification compliance levels throughout the projection horizon. CAGRs derive from propagated volume trajectories, pricing elasticity coefficients for certified versus uncertified stock, and channel-shift assumptions for direct-to-homeowner penetration. Forecast inputs incorporate EU Green Deal biodiversity target timelines and USDA spotted lanternfly quarantine expansion patterns.
Underlying measurement precision varies by segment; certified passport-compliant propagation carries tighter precision than uncertified economy-grade inventory where data fragmentation persists. Forecasts reflect assumptions regarding regulatory enforcement intensity, cold-chain logistics maturation, and homeowner channel adoption curves. A small set of named triggers warrants ongoing watch: EU member state biodiversity procurement allocation shifts, peat substrate extraction licensing restrictions, and spotted lanternfly host material quarantine geographic expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Genetically Modified Feed Market
Agriculture and Agri Products
Bamboos Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Organic Feed Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Colombia Floriculture Market