
 GCC Compound Feed Market | 2026-2036
GCC Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Compound Feed Market Insights
UAE feed safety standards are decoupling small traders from institutional procurement channels. Cargill Middle East DMCC leverages its Jebel Ali milling complex to anchor supply security for UAE poultry integrators. ARASCO dominates Saudi Arabia's ruminant feed segment through backward integration into alfalfa cultivation and captive grain handling. Al Dahra extends its Nile Valley sourcing network to secure year-round raw material flows into GCC crushing facilities.
Compound feed denotes nutritionally complete formulated rations combining cereal grains, protein meals, fats and oils, and functional additives into specified pellets or mashes for targeted animal production stages. Manufacturers grind, mix, condition, and extrude base ingredients to achieve precise protein, energy, and micronutrient profiles that optimize feed conversion ratios in commercial livestock operations. Poultry feed leads volume across the GCC due to vertically integrated broiler operations in Saudi Arabia and Qatar, while aquafeed represents the fastest-expanding category as RAS installations multiply along the Arabian Gulf coast. Additives capture disproportionate margin pools as enzyme and probiotic formulations displace antibiotic growth promoters under tightening veterinary drug regulations.
Saudi Arabia's SFDA and the UAE's Ministry of Climate Change and Environment enforce residue monitoring and import certification protocols that elevate barrier-to-entry for non-compliant feed suppliers. The EU Green Deal's due diligence spillover into Gulf trade relationships is pressing GCC mills to document sustainable soy and palm oil provenance. Stakeholders must monitor how Saudi water tariff reforms and UAE carbon accounting mandates recalibrate the cost structure of local versus imported grain processing.
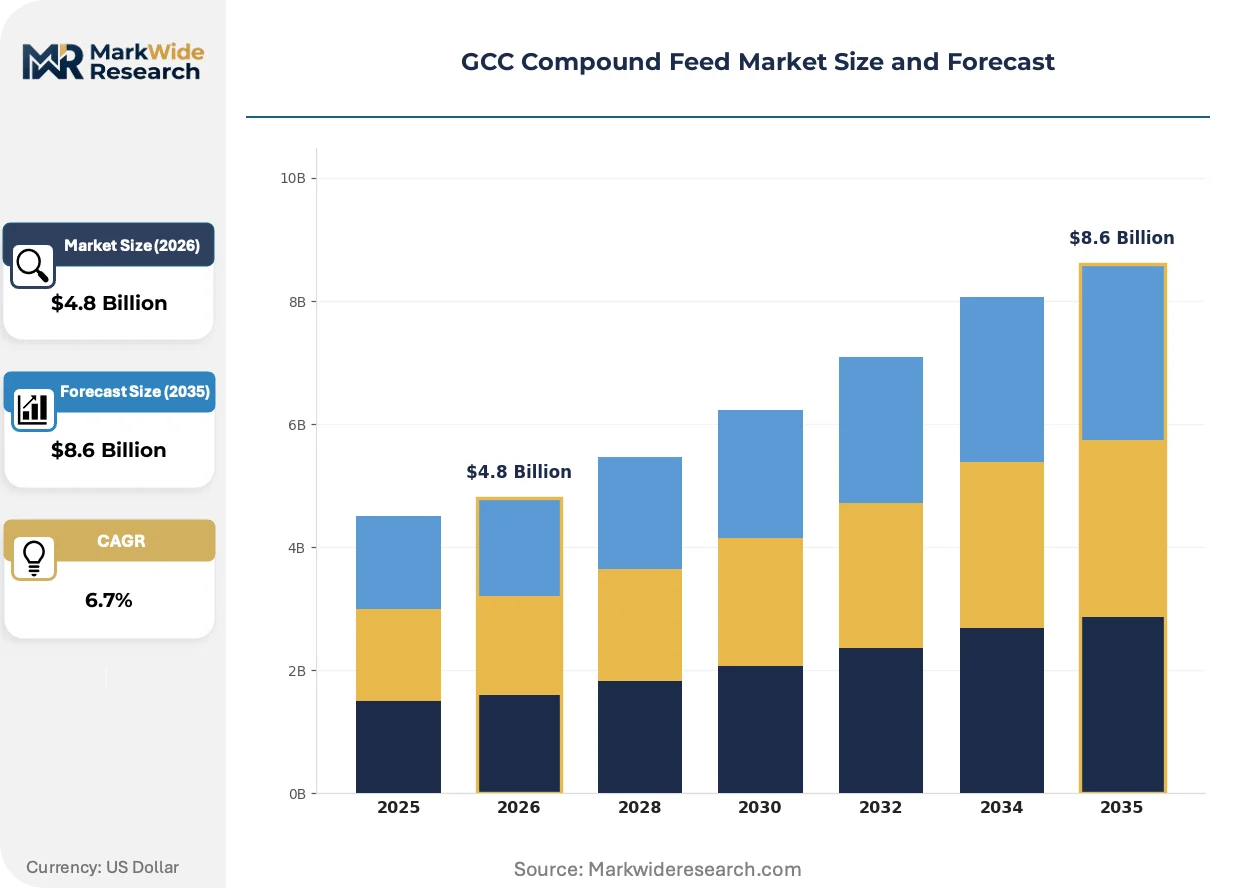
Market Dynamics
Saudi Arabia's water tariff reforms and the UAE's carbon accounting mandates are recalibrating the cost structure of local versus imported grain processing across GCC compound feed operations.
Growth Catalysts
- EU Green Deal due diligence spillover:Gulf trade relationships now demand documented sustainable soy and palm oil provenance, elevating procurement standards for GCC mills serving institutional buyers.
- Vertically integrated broiler operations:Poultry feed volume concentrates in Saudi Arabia and Qatar as domestic protein self-sufficiency targets accelerate compound feed consumption.
- RAS installations:Recirculating aquaculture systems multiplying along the Arabian Gulf coast are driving aquafeed as the fastest-expanding category in regional feed portfolios.
Market Restraints
- Raw material import dependency:GCC crushing facilities rely on Nile Valley and Black Sea grain corridors, exposing margins to Suez Canal transit disruptions and currency volatility.
- SFDA residue monitoring protocols:Saudi Arabia's import certification requirements create barrier-to-entry friction for non-compliant feed suppliers lacking laboratory accreditation.
- Antibiotic growth promoter displacement:Tightening veterinary drug regulations across the Gulf are forcing rapid reformulation cycles before enzyme and probiotic alternatives achieve cost parity.
Strategic Opportunities
- Backward integration into alfalfa cultivation:Saudi Arabia's central dairy belt offers land and water infrastructure for captive forage production reducing import exposure.
- Enzyme formulation premiums:Functional additives capture disproportionate margin pools as mills differentiate through feed conversion ratio guarantees to poultry integrators.
- Jebel Ali milling complex anchoring:UAE feed safety standards decoupling small traders from institutional channels create consolidation openings for integrated operators with cold chain and traceability systems.
Industry Challenges
- Formulation scientist scarcity:GCC universities produce insufficient animal nutrition PhDs to staff quality control and R&D functions at expanding mill capacity.
- Extrusion equipment capex cycles:Precision pelleting lines for aquafeed require capital commitments that strain mid-tier mill balance sheets before volume thresholds justify investment.
- Dual certification timelines:Simultaneous SFDA and UAE Ministry of Climate Change and Environment approval processes extend product launch windows by 8-14 months for novel additive introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Compound Feed Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pet Feed, Ruminant Feed, Poultry Feed, Aquafeed Ingredient Type: Cereal Grains, Protein Meals, Fats & Oils, Additives Distribution Channel: Online Sales, Retail Stores, Wholesalers, Direct Sales End User: Livestock Farmers, Poultry Producers, Aquaculture Farms, Pet Owners |
| Companies Covered | IFFCO Group, Cargill Middle East DMCC, Al Ghurair Foods LLC, Omani National Livestock Development Co, Adisseo Animal Nutrition DMCC, Arabian Agricultural Services Company (ARASCO), Trouw Nutrition Middle East, Al Dahra, Agthia Group PJSC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Compound Feed Market Trends and Innovations
Digital feed formulation platforms and precision livestock monitoring are compressing the feedback loop between animal performance data and ration adjustments across GCC commercial operations.
Precision dosing systems for liquid enzymes and probiotics are modularizing additive incorporation workflows at GCC mills. Poultry integrators in Saudi Arabia's central belt are retrofitting batch plants with automated micro-ingredient stations. This modularizing architecture reduces cross-contamination risk while enabling rapid formula switches between growth phases.
SFDA and the UAE's Ministry of Climate Change and Environment are tightening residue monitoring and import certification protocols that elevate documentation burdens for non-compliant suppliers. Mills must now maintain chain-of-custody records from raw material origin through finished feed dispatch. Aquafeed producers along the Arabian Gulf coast face the steepest compliance ramps as RAS operators demand batch-level traceability for export certification.
Buyer consolidation among UAE poultry integrators is compressing supplier qualification cycles and unbundling technical service from commodity feed supply. Large integrators now retain in-house nutrition teams that specify exact matrix values rather than accepting standard formulations. This procurement model shift is most visible in Dubai and Abu Dhabi integrated poultry corridors where three buyers represent over sixty percent of compound feed offtake.
GCC Compound Feed Market Segmentation
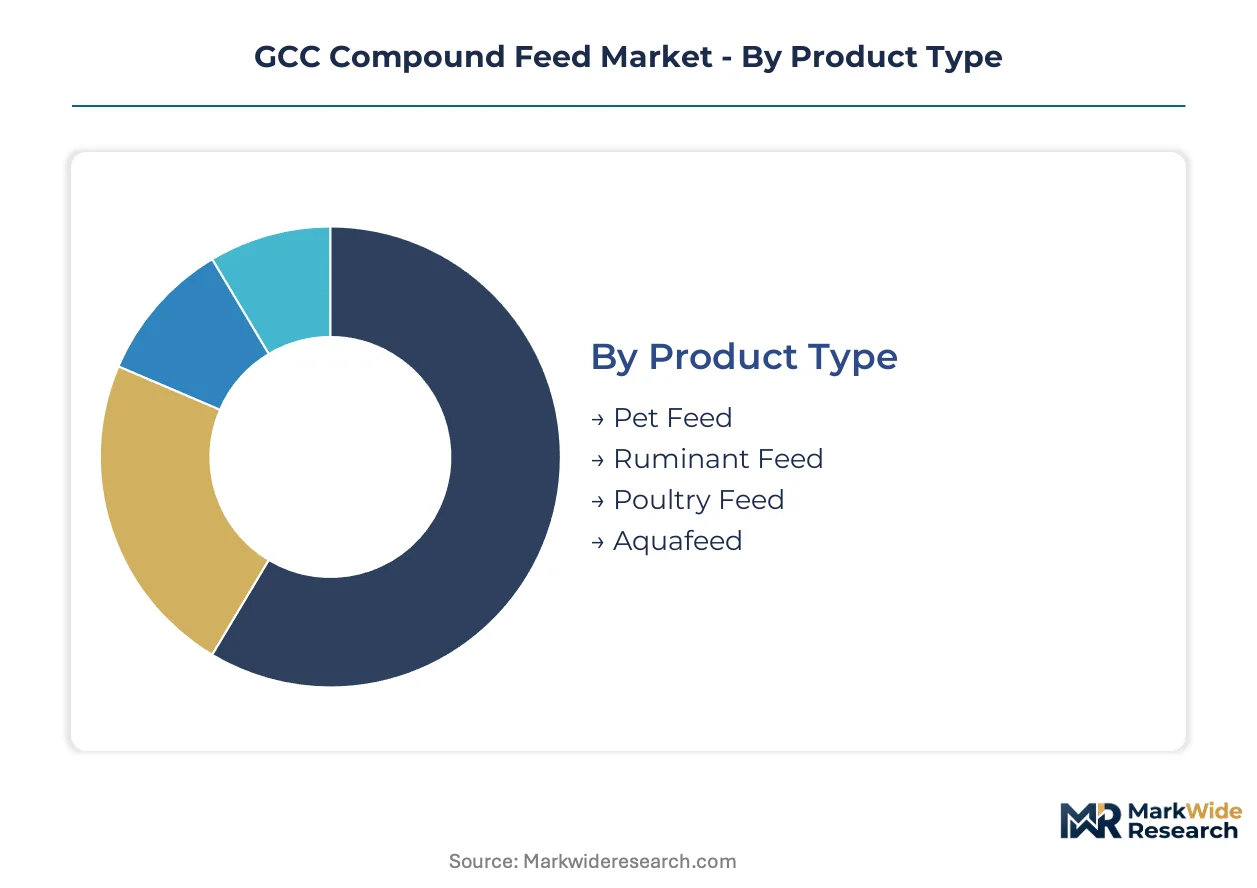
Compound feed segmentation across the GCC reflects divergent margin architectures between commodity volume plays and specialized premium formulations. Ingredient sourcing protocols and distribution channel control determine competitive position more than geographic coverage alone.
Product Type:
Poultry feed commands volume leadership while aquafeed captures the steepest expansion trajectory as RAS infrastructure scales.
- Poultry Feed:Formulated rations optimized for broiler growth phases dominate Saudi Arabia's vertically integrated operations. SFDA residue monitoring protocols are accelerating antibiotic-free formulation shifts across Riyadh and Qassim poultry corridors.
- Aquafeed:Precision-extruded pellets for recirculating aquaculture systems require higher protein density and water stability than terrestrial feeds. UAE Ministry of Climate Change and Environment batch-level traceability mandates are concentrating demand among accredited mills along the Arabian Gulf coast.
- Ruminant Feed:Alfalfa-based roughage and concentrate blends serve Saudi Arabia's central dairy belt where ARASCO maintains captive forage production.
- Pet Feed:Premium kibble and wet formulations for companion animals represent a nascent category with limited local manufacturing presence.
Mature deployment sits with poultry feed. Newer deployment is concentrated in aquafeed.
Ingredient Type:
Cost tier stratification separates commodity inputs from functional additives commanding formulation premiums.
- Additives:Enzyme and probiotic formulations displace antibiotic growth promoters under tightening veterinary drug regulations. Poultry integrators in Dubai and Abu Dhabi now specify exact matrix values rather than accepting standard formulations.
- Protein Meals:Soybean meal and alternative protein sources anchor nitrogen supply in commercial rations. EU Green Deal due diligence requirements are pressing GCC mills to document sustainable soy provenance for institutional buyers.
- Cereal Grains:Corn and sorghum provide energy density in base formulations with sourcing concentrated through Nile Valley and Black Sea corridors.
- Fats & Oils:Palm oil and tallow supply caloric density and pellet binding properties with sustainability documentation increasingly required for export-oriented aquaculture operations.
Commodity volume concentrates in cereal grains. Value capture is climbing fastest in additives.
Distribution Channel:
Channel selection determines compliance burden and customer stickiness in a market decoupling small traders from institutional procurement.
- Direct Sales:Mill-to-integrator relationships bypass intermediaries for large poultry and aquaculture operations. Cargill Middle East DMCC leverages its Jebel Ali milling complex to anchor supply security for UAE poultry integrators through dedicated logistics.
- Wholesalers:Regional distributors aggregate volume for mid-tier livestock farmers across Saudi Arabia's central dairy belt and peripheral emirates.
- Retail Stores:Bagged feed for smallholder operations and hobby farmers moves through agricultural supply cooperatives and general trade.
- Online Sales:Digital ordering platforms for specialty additives and pet feed remain underdeveloped relative to other agricultural inputs.
Established volume flows through wholesalers. Channel control is consolidating fastest in direct sales.
End User:
Customer scale determines procurement sophistication and technical service requirements across the value chain.
- Poultry Producers:Vertically integrated broiler operations in Saudi Arabia and Qatar specify exact nutrient matrices and demand feed conversion ratio guarantees. Three buyers in Dubai and Abu Dhabi integrated corridors represent over sixty percent of compound feed offtake.
- Aquaculture Farms:RAS operators along the Arabian Gulf coast require batch-level traceability for export certification, creating qualification barriers for non-compliant suppliers.
- Livestock Farmers:Dairy and beef operations in Saudi Arabia's central belt source roughage and concentrate blends with backward integration into alfalfa cultivation reducing import exposure.
- Pet Owners:Premium companion animal nutrition represents a fragmented demand base with limited local formulation expertise.
Institutional procurement concentrates with poultry producers. Technical service intensity is expanding fastest among aquaculture farms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia's central dairy belt and the UAE's integrated poultry corridors as protein self-sufficiency mandates reshape procurement patterns across the Gulf.
Saudi Arabia
Vertically integrated broiler operations in Riyadh and Qassim drive poultry feed volume as the Kingdom pursues domestic protein targets. SFDA residue monitoring protocols enforce antibiotic-free formulation shifts that elevate compliance costs for non-accredited suppliers. ARASCO anchors supply security through captive alfalfa cultivation and grain handling infrastructure across the central dairy belt.
United Arab Emirates
Recirculating aquaculture systems along the Arabian Gulf coast are accelerating aquafeed demand faster than any other category. The Ministry of Climate Change and Environment mandates batch-level traceability for export certification, disqualifying mills lacking chain-of-custody documentation. Cargill Middle East DMCC leverages its Jebel Ali milling complex to serve institutional poultry integrators through dedicated cold chain logistics.
Qatar
State-led food security investments support scaled broiler operations that concentrate compound feed procurement among a narrow buyer base. The Qatar General Organization for Standardization enforces import certification protocols aligned with Gulf harmonization frameworks. Industrial poultry clusters near Doha source formulated rations through direct mill relationships that bypass traditional distribution channels.
Oman
Livestock development programs in the Batinah coastal plain and Dhofar region are expanding ruminant feed requirements for dairy and beef operations. The Ministry of Agriculture and Fisheries administers subsidy frameworks that favor local milling capacity over imported finished feed. Omani National Livestock Development Co coordinates procurement across government-supported farming collectives in the Salalah agricultural zone.
Kuwait
Poultry integrators in the Al-Jahra and Al-Wafra farming zones are upgrading feed conversion specifications as domestic broiler production scales. The Public Authority for Food and Nutrition monitors veterinary drug residues through import inspection regimes that mirror Saudi and Emirati standards. Limited local milling capacity forces reliance on GCC cross-border supply chains subject to transit cost volatility.
GCC Compound Feed Market Competitive Landscape
Saudi producers anchor one tier; UAE-based specialists hold procurement relationships with institutional integrators. The vendor structure concentrates around integrated operators with captive supply chains and regional distributors serving mid-tier livestock farmers. Three archetypes dominate: multinational agribusinesses with Gulf milling assets, domestic conglomerates with backward integration into forage production, and European nutrition specialists licensing additive formulations. Competitive dynamics center on capacity expansion near demand clusters and strategic partnerships securing year-round raw material flows.
Within the integrated agribusiness tier, Cargill Middle East DMCC and Arabian Agricultural Services Company exemplify scale-driven positioning through milling infrastructure and captive supply control. Al Dahra occupies a position bridging raw material sourcing and regional distribution. These anchors reflect the market's bifurcation between multinational operators with global procurement networks and domestic players leveraging land and water access for forage self-sufficiency.
| Leading Market Players |
|---|
| IFFCO Group |
| Cargill Middle East DMCC |
| Al Ghurair Foods LLC |
| Omani National Livestock Development Co |
| Adisseo Animal Nutrition DMCC |
| Arabian Agricultural Services Company (ARASCO) |
| Trouw Nutrition Middle East |
| Al Dahra |
| Agthia Group PJSC |
| Others |
Pricing and Supply Chain Analysis
UAE poultry integrator consolidation into three dominant buyers representing over sixty percent of compound feed offtake is forcing mills to absorb certification and traceability costs that previously flowed through to pricing. This procurement concentration is compressing margin pools for mid-tier suppliers while rewarding integrated operators with captive supply chains.
Pricing Analysis
Volume concentrates in commodity poultry feed while margin capture accelerates in functional additives and aquafeed premiums. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-accredited antibiotic-free formulations from conventional rations and generic blends. Pricing pressure stems from buyer consolidation as large integrators specify exact nutrient matrices rather than accepting standard formulations. Smallholder operations through retail cooperatives exhibit highest price sensitivity; RAS operators along the Arabian Gulf coast demonstrate lowest sensitivity due to export certification requirements.
Supply Chain Analysis
Saudi Arabia's water tariff reforms and UAE carbon accounting mandates are reshaping sourcing protocols toward domestic alfalfa cultivation and regional grain processing. Raw material flows draw from Nile Valley and Black Sea corridors for cereal grains, Southeast Asian palm oil estates, and South American soybean operations. Single-source vulnerability concentrates in Suez Canal transit routes where disruptions cascade through crushing facility margins. Distribution runs through direct mill-to-integrator relationships for institutional poultry and aquaculture operations, with wholesalers serving mid-tier livestock farmers across peripheral emirates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA and UAE Ministry of Climate Change and Environment dual certification timelines extending product launch windows by 8-14 months are accelerating consolidation as smaller mills lack capital reserves to navigate extended approval cycles.
For Market Incumbents: Acquire extrusion equipment capacity and precision pelleting lines to serve aquafeed demand from multiplying RAS installations. Defensive positioning requires securing year-round raw material flows through backward integration into alfalfa cultivation or long-term supply agreements with Nile Valley grain corridors. Threat substitution from enzyme and probiotic formulations displacing antibiotic growth promoters demands R&D investment in functional additive portfolios. For New Entrants and Emerging Players: Enter via specialty additive licensing partnerships with European nutrition specialists to bypass capital-intensive milling infrastructure. White-space targets concentrate in enzyme formulation premiums and batch-level traceability services for RAS operators along the Arabian Gulf coast. Go-to-market execution should anchor on technical service intensity rather than commodity volume plays. For Investors and Strategic Acquirers: The window for entry favors integrated operators with captive supply chains and cold chain logistics capabilities over standalone milling assets. Long-term viability centers on land and water access for forage self-sufficiency in Saudi Arabia's central dairy belt. Watch SFDA enforcement patterns on residue monitoring protocols as the inflection signal for regulatory compliance moat widening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alfalfa Cultivation | ARASCO's captive forage production reduces import exposure and secures ruminant feed margins. |
| Precision Extrusion Capacity Buildout | Aquafeed pellet water stability requirements strain mid-tier mill balance sheets before volume thresholds justify investment. |
| Dual Certification Compliance Investment | SFDA and UAE Ministry approval processes extend launch windows, favoring capital-reserved integrated operators. |
| Enzyme Formulation Licensing Partnerships | European specialists provide formulation technology without domestic R&D infrastructure requirements. |
| Direct Sales Channel Consolidation | Cargill's Jebel Ali complex anchors supply security through dedicated logistics bypassing wholesale intermediaries. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this GCC compound feed market assessment. Primary interviews with mill operations directors, poultry integrator procurement leads, aquaculture farm managers, and feed formulation scientists validated demand-side assumptions. Secondary sources included SFDA residue monitoring protocols, UAE Ministry of Climate Change and Environment certification requirements, and Gulf harmonization framework documentation. Bottom-up volume modeling across product types and top-down macroeconomic triangulation ensured cross-verification.
Granularity-level modeling operated at ingredient-type and distribution-channel intersections with end-user scale tiers across Saudi Arabia, UAE, Qatar, Oman, and Kuwait. Segmentation dimensions included poultry feed, aquafeed, ruminant feed, and pet feed product categories; additives, protein meals, cereal grains, and fats and oils ingredient types; and direct sales, wholesale, retail, and online channels. CAGRs were derived from trend extrapolation and adoption curve analysis. Industry-specific inputs incorporated RAS installation pipelines, water tariff reform schedules, and antibiotic-free formulation transition rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Suez Canal transit disruptions and currency volatility in grain sourcing corridors. Forecasts reflect assumptions on regulatory enforcement intensity and buyer consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Canada Animal Protein Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
UAE Agriculture Market