
 South Africa Compound Feed Market | 2026-2036
South Africa Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Compound Feed Market Analytics
Poultry farm demand is hardening as the dominant end-use vertical, pulling formulation complexity upward across the value chain. Meadow Feeds leverages its geographic dominance in KwaZulu-Natal to control distribution into coastal poultry belts. RCL Foods Ltd. anchors its position through backward integration into grain milling and oilseed processing. AFGRI Animal Feeds differentiates via specialized ruminant feed lines serving the commercial beef sector in the Free State.
Compound feed denotes nutritionally complete, commercially manufactured feed mixtures formulated from grains, proteins, vitamins, and minerals to meet species-specific dietary requirements, typically produced via pelleting or extrusion processes to ensure digestibility and storage stability. Poultry feed occupies the largest volume share given the vertical integration of South Africa's broiler industry, while aquafeed represents the fastest-growing category as marine and freshwater farm projects expand along the Western Cape coast. Ruminant feed maintains mature, stable offtake patterns tied to seasonal grazing cycles and drought-recovery herd rebuilding.
The Department of Agriculture, Land Reform and Rural Development administers the Fertilizers, Farm Feeds, Seeds and Remedies Act, mandating registration and labeling standards that shape product market access timelines. BIS-aligned import protocols and the country's national agricultural quality regulator enforce mycotoxin thresholds and genetically modified organism disclosure requirements for imported feed ingredients. Stakeholders must monitor evolving drought-response policies and water-use licensing frameworks that directly constrain feed crop production planning across the maize belt.
Market Dynamics
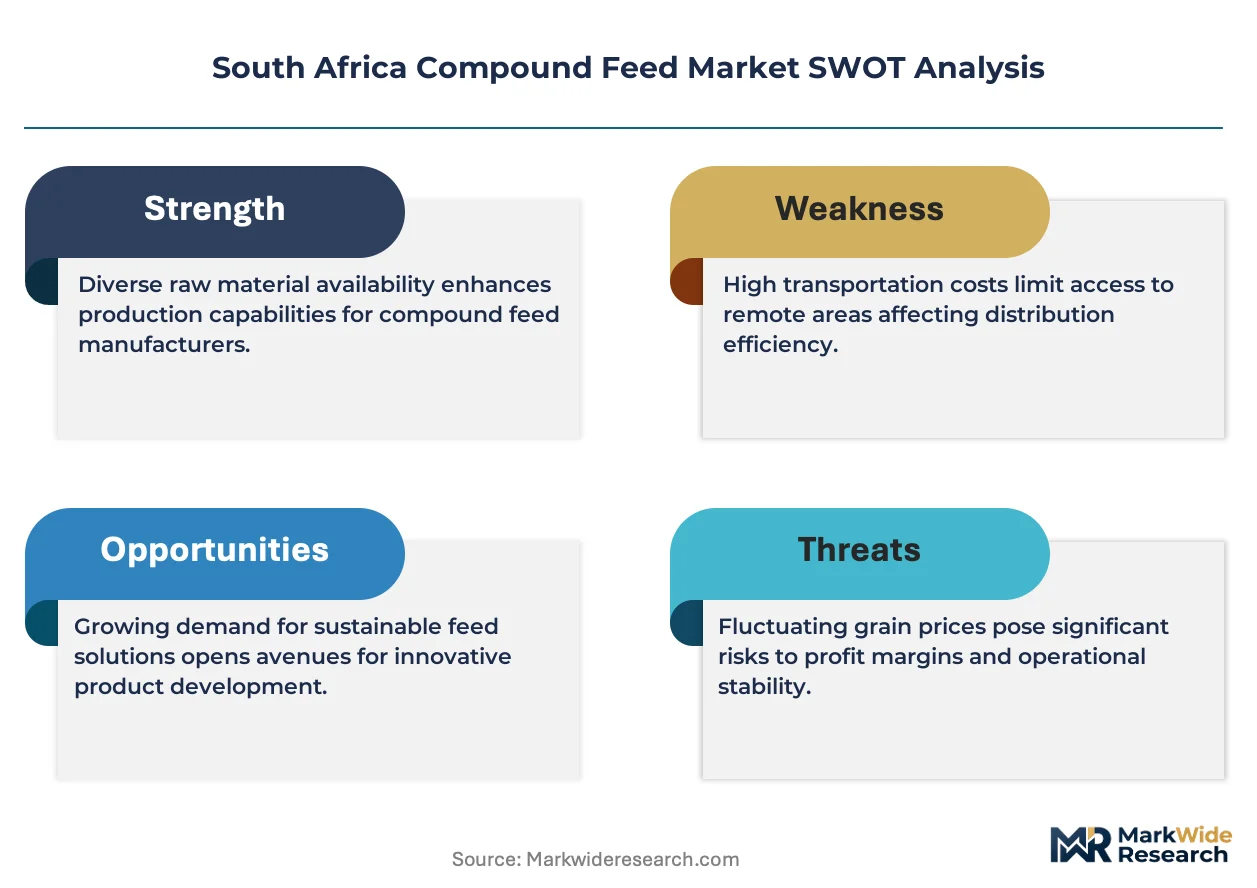
Poultry farm consolidation across Gauteng and KwaZulu-Natal is concentrating formulation demand toward high-performance starter and grower feeds, compressing margin tolerance for smaller blending operations.
Growth Catalysts
- Poultry sector verticalization:Integrated broiler operations are standardizing feed specifications across their breeder, broiler, and layer divisions, creating volume anchors for compound feed mills.
- Fertilizers, Farm Feeds, Seeds and Remedies Act enforcement:Mandatory registration and mycotoxin testing protocols are professionalizing the supplier base and disqualifying informal blenders.
- Western Cape aquaculture licensing:Marine and freshwater farm permits are expanding addressable demand for species-specific extruded feeds.
Market Restraints
- Maize price volatility:Drought-recovery cycles in the Free State and North West provinces destabilize input cost structures for carbohydrate-dependent formulations.
- Import concentration risk:Soybean meal and fishmeal sourcing depends on Durban port throughput and BIS-aligned GMO disclosure protocols, creating single-point vulnerabilities.
- Ruminant feed seasonality:Beef and dairy operations in the Eastern Cape retain grazing-dependent feeding patterns that resist year-round compound feed conversion.
Strategic Opportunities
- Limpopo smallholder penetration:Emerging poultry cooperatives in the Vhembe and Mopani districts represent unserved volume for 25kg bagged starter feeds.
- Precision nutrition services:Near-infrared spectroscopy and farm-level diet optimization are converging to create subscription-based formulation advisory models.
- Drought-response policy alignment:Government herd-rebuilding subsidies in drought-declared municipalities can be captured through certified drought-recovery feed product lines.
Industry Challenges
- Feed safety auditor scarcity:The Department of Agriculture, Land Reform and Rural Development maintains limited inspection capacity, extending product registration timelines.
- Extrusion capex barriers:Aquafeed-grade extrusion equipment requires capital outlays that mid-tier mills struggle to finance against ruminant feed margin profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Compound Feed Market |
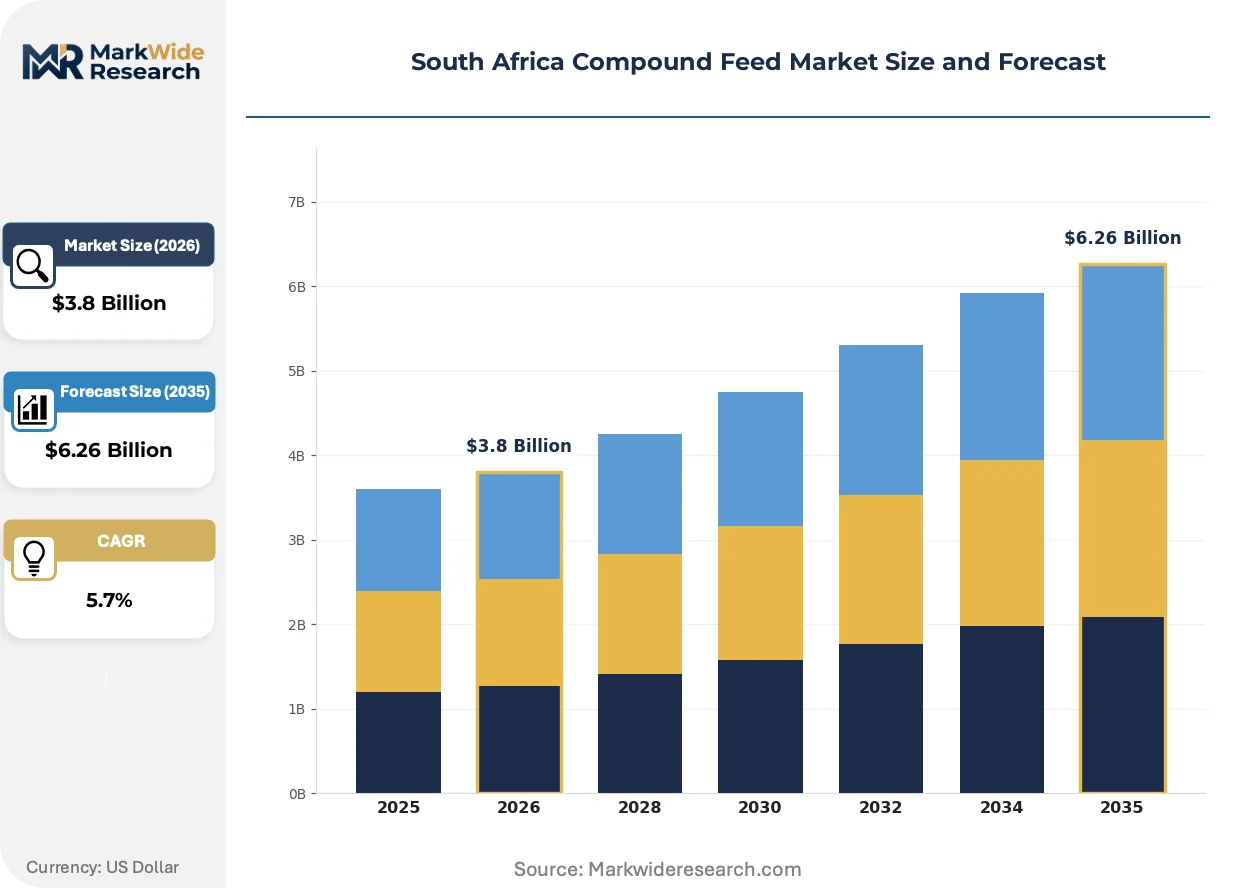
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Ruminant Feed, Swine Feed, Aquafeed End User: Livestock Farmers, Poultry Farms, Aquaculture Operations, Feed Manufacturers Ingredient Type: Grains, Proteins, Vitamins, Minerals Distribution Channel: Direct Sales, Retail Stores, Online Sales, Distributors |
| Companies Covered | Epol, Meadow Feeds, RCL Foods Ltd., Archer Daniels Midland, Cargill Inc., Astral Foods, AFGRI Animal Feeds, Novus International, Country Bird Holdings Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Compound Feed Market Evolving Landscape
Digital feed formulation platforms and alternative protein sourcing are compressing traditional supply relationships while regulatory mycotoxin surveillance tightens ingredient provenance requirements.
Enzyme-supplemented poultry diets are consolidating around phytase and xylanase cocktails that reduce phosphorus and energy input costs. Large integrated broiler operations in Mpumalanga are adopting these premixes at scale. The technology is consolidating feed conversion ratio advantages toward operations with in-house nutrition teams.
The Department of Agriculture, Land Reform and Rural Development is expanding mycotoxin surveillance sampling across imported grain shipments under amended Fertilizers, Farm Feeds, Seeds and Remedies Act regulations. This enforcement is extending laboratory certification timelines for new ingredient suppliers. Poultry feed blenders dependent on imported yellow maize are responding by diversifying toward local white maize sourcing.
Buyers are consolidating procurement contracts toward single-source supply agreements with volume-tiered pricing. Independent layer farms in the Western Cape are displacing spot-market purchasing with annual framework contracts. This concentration is most visible among medium-scale operations seeking price stability against volatile raw material markets.
South Africa Compound Feed Market Segmentation
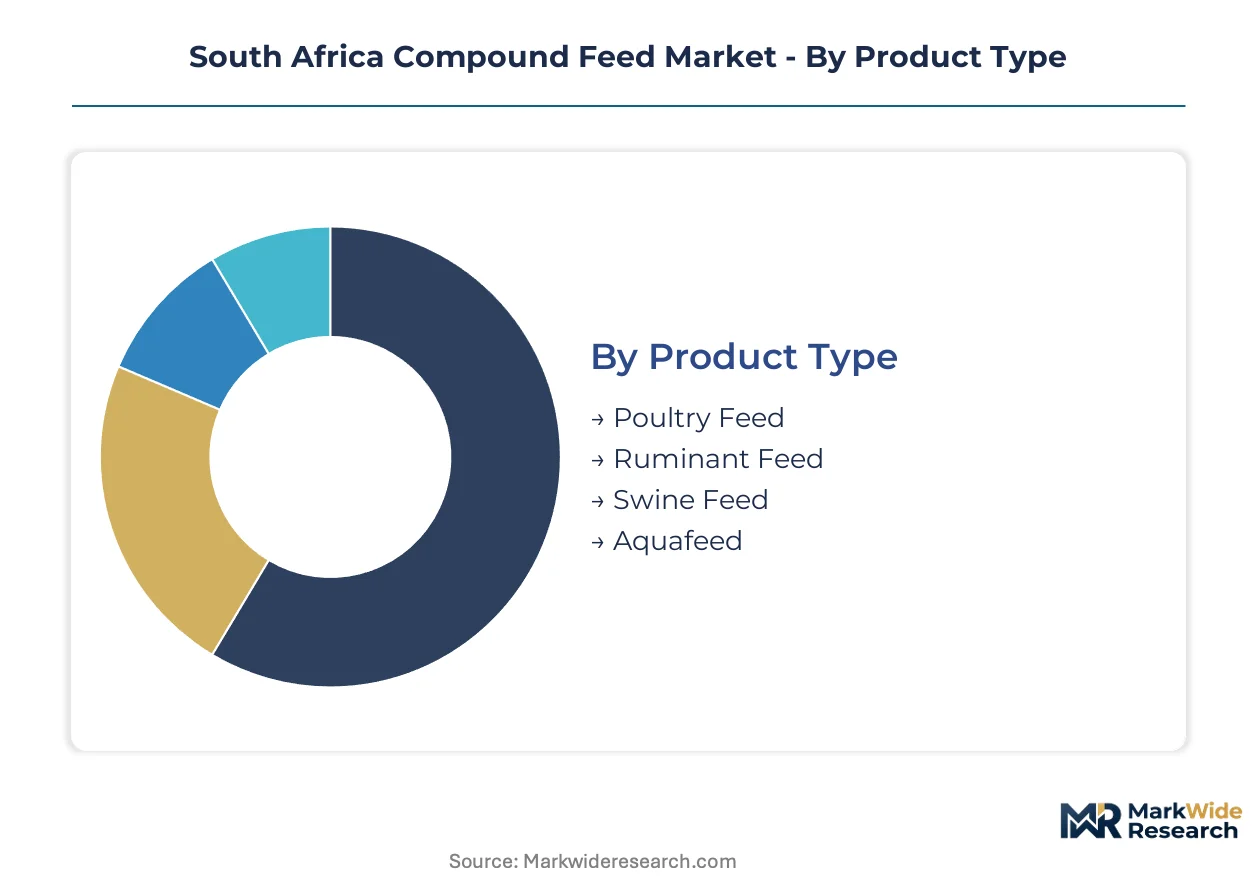
Compound feed formulation in South Africa diverges sharply across species requirements and procurement channels. Buyers prioritize nutritional precision, cost stability, and regulatory compliance when selecting feed categories. The Department of Agriculture, Land Reform and Rural Development's registration mandates create tiered market access that shapes competitive positioning across each segment.
Product Type:
Formulation complexity and margin profiles drive buyer selection, with vertical integration depth determining specification control.
- Poultry Feed:Starter, grower, and layer formulations dominate volume throughput, with phytase-supplemented diets reducing phosphorus input costs. Integrated broiler operations in Gauteng and Mpumalanga standardize specifications across breeder, broiler, and layer divisions, compressing margin tolerance for independent blenders.
- Aquafeed:Extruded marine and freshwater species-specific feeds require specialized processing equipment. Western Cape aquaculture licensing expansion near Saldanha Bay and Hermanus is pulling demand for high-protein floating and sinking pellet formulations.
- Ruminant Feed:Beef and dairy concentrates in the Free State follow seasonal grazing cycles with drought-recovery herd rebuilding patterns.
- Swine Feed:Sow, piglet, and finisher formulations serve commercial pork operations in the North West province.
Poultry feed leads on scale; aquafeed leads on momentum.
End User:
Procurement scale and technical capability separate volume-tiered buyers from spot-market purchasers.
- Poultry Farms:Vertically integrated operations with in-house nutrition teams negotiate annual framework contracts with volume-tiered pricing. These buyers specify enzyme-supplemented premixes and near-infrared verified ingredient profiles.
- Livestock Farmers:Commercial beef and dairy operations in the Eastern Cape retain grazing-dependent feeding patterns that resist year-round compound feed conversion, concentrating demand during winter supplementation periods.
- Aquaculture Operations:Marine and freshwater farms along the Western Cape coast require species-specific extruded feeds with precise protein-to-energy ratios.
- Feed Manufacturers:Regional blending operations in KwaZulu-Natal and Limpopo source base mixes and premixes from integrated suppliers.
Poultry farms command procurement leverage; aquaculture operations are climbing the fastest on specification intensity.
Ingredient Type:
Input cost volatility and mycotoxin surveillance protocols determine sourcing geography and supplier qualification timelines.
- Grains:Yellow and white maize from the Free State maize belt provides carbohydrate foundations, with drought-recovery cycles destabilizing price structures. Buyers are diversifying toward local white maize as BIS-aligned import protocols extend laboratory certification timelines for imported shipments.
- Proteins:Soybean meal, fishmeal, and oilseed derivatives supply amino acid density. Durban port throughput concentration creates single-point vulnerabilities for imported soybean meal.
- Vitamins:Premix formulations incorporate species-specific micronutrient profiles regulated under the Fertilizers, Farm Feeds, Seeds and Remedies Act labeling standards.
- Minerals:Calcium, phosphorus, and trace element supplementation varies by production phase and local soil deficiency mapping.
Grains anchor formulation economics; proteins represent the steepest expansion trajectory on import substitution pressures.
Distribution Channel:
Geographic concentration of livestock operations and infrastructure access shape channel selection.
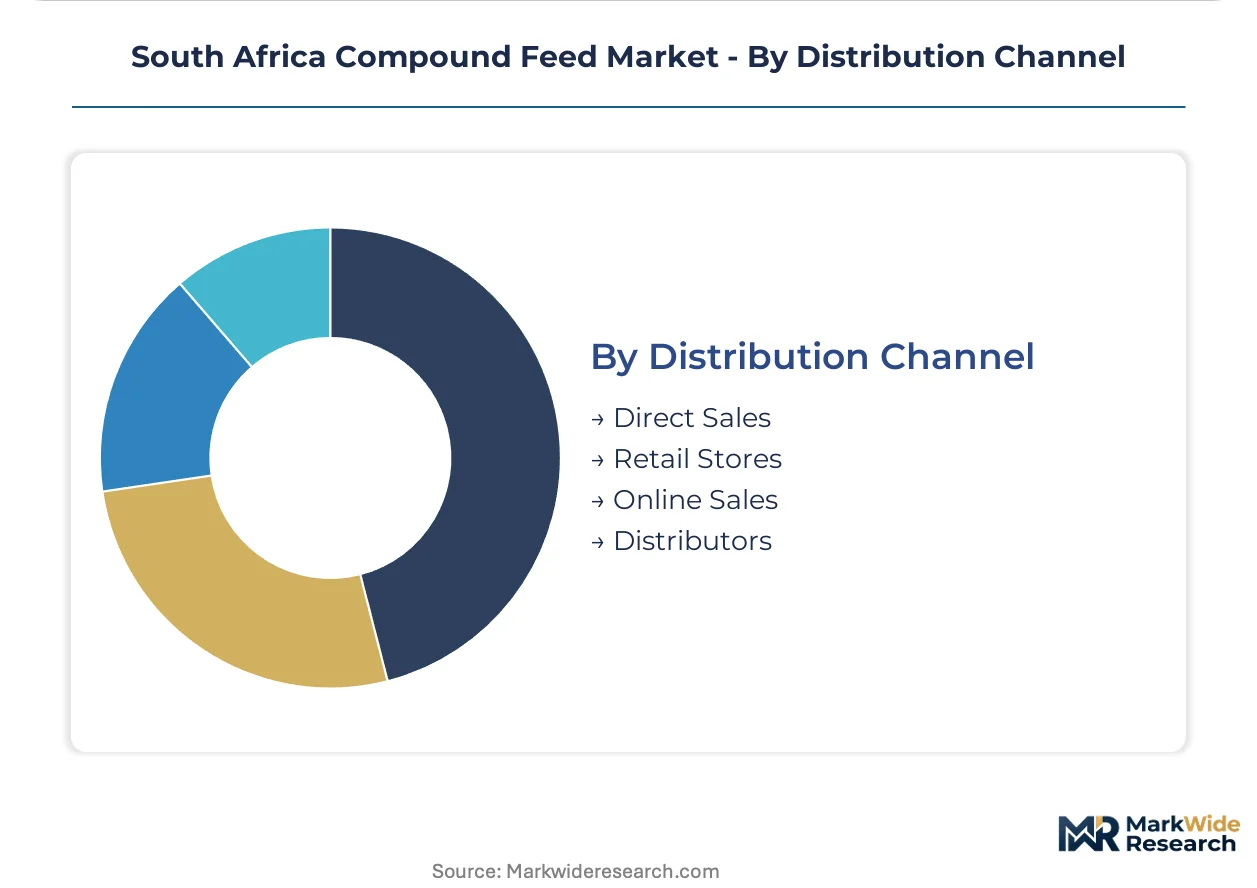
- Direct Sales:Large integrated poultry and aquaculture operations procure via mill-direct agreements with scheduled delivery windows. Meadow Feeds leverages geographic dominance in KwaZulu-Natal to control coastal distribution through captive logistics.
- Distributors:Regional wholesalers serve mid-tier livestock farmers in Limpopo and the Eastern Cape with 25kg to 1000kg bagged product lines.
- Retail Stores:Agricultural cooperatives and farm supply outlets cater to smallholder poultry cooperatives in Vhembe and Mopani districts.
- Online Sales:Digital procurement platforms are emerging for premix and supplement ordering, though bulk feed logistics limit adoption.
Direct sales capture volume concentration; distributor networks are gaining share fastest in smallholder penetration zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing compound feed production toward provinces where Fertilizers, Farm Feeds, Seeds and Remedies Act compliance costs diverge from operational density advantages. Mills migrate to balance registration burden against proximity to poultry belt demand.
Gauteng
Intensive broiler operations in Johannesburg and Pretoria corridors consume high-performance starter and grower formulations at scale. The Department of Agriculture, Land Reform and Rural Development maintains regional inspection offices here, compressing product registration timelines for local mills. Vereeniging and Bronkhorstsprai feed clusters anchor supply to vertically integrated poultry processors.
KwaZulu-Natal
Coastal poultry belts around Durban and Pietermaritzburg pull specialized layer and breeder feeds through captive distribution networks. Provincial environmental licensing frameworks govern effluent discharge from feed milling operations. Meadow Feeds leverages geographic dominance here to control port-adjacent logistics corridors serving export-oriented aquaculture.
Western Cape
Marine and freshwater farm projects near Saldanha Bay and Hermanus are accelerating extruded aquafeed demand. Municipal water-use licensing under the National Water Act constrains feed crop irrigation planning in the Swartland wheat belt. Stellenbosch agricultural research clusters support species-specific formulation development for emerging finfish operations.
Free State
Commercial beef and dairy concentrates follow seasonal grazing cycles tied to maize belt harvest patterns. Drought-recovery herd rebuilding programs channel government subsidies toward certified drought-recovery feed lines. Bloemfontein milling operations serve dispersed cattle operations across the eastern Free State rangelands.
Limpopo
Emerging poultry cooperatives in Vhembe and Mopani districts represent unserved volume for 25kg bagged starter feeds. Land reform beneficiary support programs under provincial agricultural development schemes lower barrier-to-entry for smallholder feed procurement. Polokwane distributor networks extend reach into remote communal farming areas.
South Africa Compound Feed Market Competitive Landscape
Backward integration into grain milling and oilseed processing dominates the current landscape, compressing margin tolerance for standalone blenders. The supplier base concentrates around three operational tiers: integrated agribusiness conglomerates with captive supply chains, regional specialists commanding geographic niches, and multinational traders leveraging import scale. Strategic archetypes separate upstream-controlled formulators from distribution-heavy localists and premix-focused nutrition houses. Competitive intensity manifests through capacity expansion in aquafeed extrusion and strategic partnerships locking poultry offtake agreements.
Among South Africa-based integrated players, RCL Foods Ltd. and AFGRI Animal Feeds occupy positions exemplifying upstream-controlled and regional-specialist archetypes respectively. Meadow Feeds represents the distribution-heavy localist model through KwaZulu-Natal geographic concentration. Multinational presence includes Archer Daniels Midland and Cargill Inc., which sit within the import-scale trader tier.
| Leading Market Players |
|---|
| Epol |
| Meadow Feeds |
| RCL Foods Ltd. |
| Archer Daniels Midland |
| Cargill Inc. |
| Astral Foods |
| AFGRI Animal Feeds |
| Novus International |
| Country Bird Holdings Ltd. |
| Others |
Value Network & Pricing Analysis
Vertically integrated poultry operations in Gauteng and Mpumalanga negotiate annual framework contracts with volume-tiered pricing, anchoring the market around contract-based long-term offtake structures that compress spot-market premiums.
Pricing Analysis
Distributor margins in KwaZulu-Natal coastal corridors capture 8-12% markups on 25kg bagged starter feeds delivered to emerging poultry cooperatives. Pricing stratifies across premium enzyme-supplemented formulations, standard certified lines, and economy unregistered blends. Cost compression in economy tiers intensifies because drought-recovery maize cycles destabilize input structures. Independent layer farms in the Western Cape exhibit highest price sensitivity, while integrated broiler operations with captive nutrition teams prioritize specification stability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Durban port throughput for imported soybean meal and fishmeal, creating chokepoint exposure for coastal mills. Raw material sourcing draws from Argentina and Brazil for soybean derivatives, Peru and Chile for fishmeal, and the Free State maize belt for carbohydrate foundations. Tariff exposure runs through BIS-aligned GMO disclosure protocols that extend laboratory certification timelines. Distribution runs through mill-direct agreements for large integrated operations and regional wholesalers serving mid-tier livestock farmers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by poultry farm consolidation pulling formulation demand toward high-performance enzyme-supplemented diets with verified ingredient profiles.
For Market Incumbents: To counter margin compression from drought-driven maize volatility, secure backward integration into grain milling in the Free State and invest in near-infrared spectroscopy certification to differentiate precision nutrition services. Channel control through captive logistics in KwaZulu-Natal reinforces geographic moats against regional challengers. For New Entrants and Emerging Players: Begin with 25kg bagged starter feed distribution to emerging poultry cooperatives in Vhembe and Mopani districts, where land reform beneficiary programs lower procurement barriers. A go-to-market angle anchored in drought-response subsidy alignment with certified feed lines captures government-supported volume. For Investors and Strategic Acquirers: Integrated agribusiness conglomerates with captive oilseed processing are the most active acquirer in this space, targeting regional specialists with geographic concentration in underpenetrated provinces. Long-term viability favors upstream-controlled formulators with extrusion capability for aquafeed expansion. The signal to watch is Western Cape aquaculture licensing velocity as inflection indicator for species-specific feed demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Milling | RCL Foods Ltd. controls input cost volatility through captive maize processing in the Free State. |
| Aquafeed Extrusion Capacity Expansion | Western Cape licensing near Saldanha Bay pulls demand for marine species-specific floating pellet formulations. |
| Precision Nutrition Subscription Services | Farm-level diet optimization via near-infrared spectroscopy creates recurring revenue from integrated broiler operations. |
| Drought-Recovery Feed Certification | Alignment with Department of Agriculture herd-rebuilding subsidies captures government-procurement volume in declared municipalities. |
| Smallholder Distribution Network Extension | Polokwane distributor networks reach remote communal farming areas in Limpopo with 25kg bagged product lines. |
Research Methodology
Coverage spans Gauteng, KwaZulu-Natal, Western Cape, Free State, and Limpopo provinces, with primary inputs from each. The analysis combines structured interviews with feed mill operations managers, poultry farm procurement directors, Department of Agriculture inspection officers, and aquaculture project developers, validated against secondary sources including Fertilizers, Farm Feeds, Seeds and Remedies Act registration databases, South African Grain Information Service harvest reports, and port authority import manifests. Bottom-up volume modeling and top-down value reconciliation triangulate market sizing across species-specific formulation segments.
Granularity-level modeling operates at provincial production cluster, species category, and procurement channel tiers. The analytical framework projects volume and value across poultry, aquaculture, ruminant, and swine feed segments, with ingredient cost indices and drought-recovery cycle assumptions feeding into CAGR derivation. Feed conversion ratio improvements from enzyme-supplemented diets and aquaculture licensing velocity serve as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including extreme drought declarations beyond historical recurrence patterns, port labor disruptions affecting soybean meal throughput, and regulatory amendments to GMO disclosure protocols. Forecasts reflect documented assumptions about maize yield recovery and poultry farm consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Animal Feed and Pet Food Market