
 Livestock Farm Equipment Market | 2026-2036
Livestock Farm Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Livestock Farm Equipment Market Intelligence
Procurement strategy from single-source to multi-source supplier relationships is shifting how livestock operations acquire precision feeding and milking infrastructure. DeLaval leverages its integrated dairy system portfolio to sustain long-term service contracts across Nordic cooperatives. GEA Group anchors its position through advanced manure management engineering that dominates Central European pork operations. AGCO Corporation competes by extending its precision agriculture telemetry into cattle monitoring applications.
Livestock farm equipment encompasses mechanized and automated systems engineered for animal husbandry operations, typically constructed from corrosion-resistant stainless steel alloys and food-grade polymers to withstand sustained exposure to organic waste and moisture cycles. These systems perform core functions including automated feed distribution, precision milking extraction, environmental climate control, and waste collection management to optimize animal welfare metrics and operational throughput. Milking equipment retains the largest installed base across dairy applications while autonomous systems represent the fastest-expanding technology segment as labor scarcity intensifies retrofit demand. Precision agriculture tools command premium margin pools where IoT-enabled herd analytics justify subscription-based revenue models for equipment vendors.
The EU F-Gas Regulation and CE marking directives constrain refrigerant choices in climate-controlled housing systems, compelling manufacturers to redesign ventilation and cooling architectures for compliance. FDA guidelines on dairy equipment sanitation and USDA biosecurity protocols for interstate livestock movement further shape product specifications and market access requirements. Stakeholders must monitor evolving carbon accounting standards for agricultural machinery as sustainability disclosure obligations extend into supply chain emissions reporting.
Market Dynamics
Labor scarcity across dairy and pork operations is accelerating autonomous equipment retrofit cycles, forcing manufacturers to reconfigure service architectures around predictive maintenance rather than reactive repair models.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates in climate-controlled housing systems are compelling Dutch and German producers to electrify ventilation infrastructure, expanding the addressable market for heat pump-based livestock housing.
- Precision feeding algorithms:IoT-enabled ration optimization is penetrating Bavarian dairy cooperatives where margin compression demands feed conversion efficiency gains of three to five percentage points.
- Manure management engineering:Nitrogen emission caps under the EU Green Deal are concentrating demand for automated slurry separation systems across Denmark's centralized pork processing belt.
Market Restraints
- Stainless steel input volatility:Grade 316L alloy price swings constrain margin stability for milking parlor manufacturers dependent on corrosion-resistant fabrication.
- CE marking complexity:Machinery Directive conformity assessment timelines extend eighteen to twenty-four months for novel autonomous systems, delaying commercialization of robotic feeding platforms.
- Technical integration barriers:Legacy barn infrastructure in Poland and Romania lacks ethernet backbone capacity, limiting telemetry deployment for herd analytics without parallel electrical upgrades.
Strategic Opportunities
- Underpenetrated Iberian Peninsula:Spanish and Portuguese dairy operations maintain sub-fifteen percent automation rates versus Nordic benchmarks, creating whitespace for milking robot deployment.
- Subscription telemetry models:Sensor-as-a-service pricing for lameness detection and estrus monitoring is displacing capital-intensive equipment purchases among mid-scale French producers.
- Carbon accounting integration:CSRD-aligned emissions reporting requirements are opening consultative revenue streams for vendors bundling equipment with methane monitoring dashboards.
Industry Challenges
- Electromechanical technician scarcity:Dairy belt regions face acute shortages of technicians qualified to service robotic milking arm hydraulics and laser optic calibration.
- Multi-vendor integration friction:Proprietary data protocols from competing feeding and milking platforms prevent unified herd management dashboards, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Livestock Farm Equipment Market |
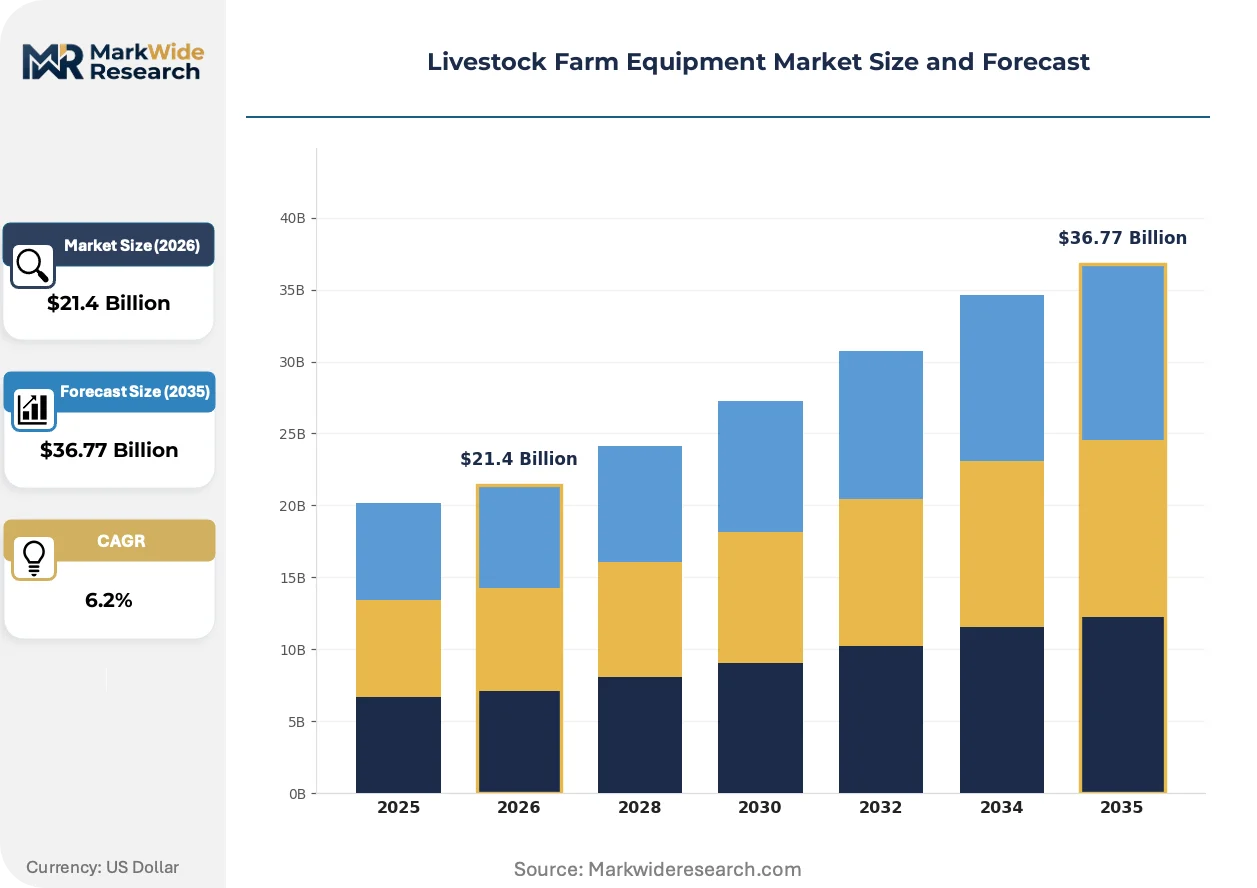
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $36.77 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feeders, Waterers, Milking Equipment, Manure Spreaders Technology: Autonomous Systems, Robotics, Precision Agriculture, IoT Solutions Application: Dairy Farming, Poultry Farming, Beef Production, Aquaculture End User: Farmers, Agricultural Cooperatives, Livestock Producers, Researchers |
| Companies Covered | DeLaval, GEA Group, Deere & Company, AGCO Corporation, Lely, Afimilk Ltd., BouMatic, FarmTek, Nedap NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Livestock Farm Equipment Market Strategic Shifts & Innovations
Autonomous systems are compressing operational labor requirements while regulatory pressure on emissions intensifies equipment electrification roadmaps across European livestock belts.
Robotic milking systems equipped with three-dimensional vision and automated teat cleaning are overtaking conventional parlor configurations in new-build dairy facilities. Bavarian and Dutch cooperatives are specifying these platforms as standard for greenfield expansions. The technology is overtaking fixed-stall infrastructure by eliminating the labor bottleneck that previously constrained herd size scaling.
REACH chemical restrictions and the EU F-Gas Regulation are banning hydrofluorocarbon refrigerants in climate-controlled housing, compelling ventilation engineers to specify propane-based heat pumps and liquid cooling loops. Equipment manufacturers in Germany and Denmark are redesigning thermal management architectures to maintain performance under stricter refrigerant global warming potential ceilings. Pork operations in the Netherlands are responding by accelerating barn renovation cycles to accommodate compliant climate systems.
Cooperative procurement consortia are consolidating equipment purchasing power across multi-farm memberships, displacing individual farm capital expenditure models. Dutch dairy cooperatives and French pork associations are negotiating fleet-scale service contracts that bundle maintenance, telemetry, and upgrade pathways. This concentration is most visible in the Netherlands where Rabobank-financed cooperative structures dominate capital allocation for precision livestock infrastructure.
Livestock Farm Equipment Market Segmentation
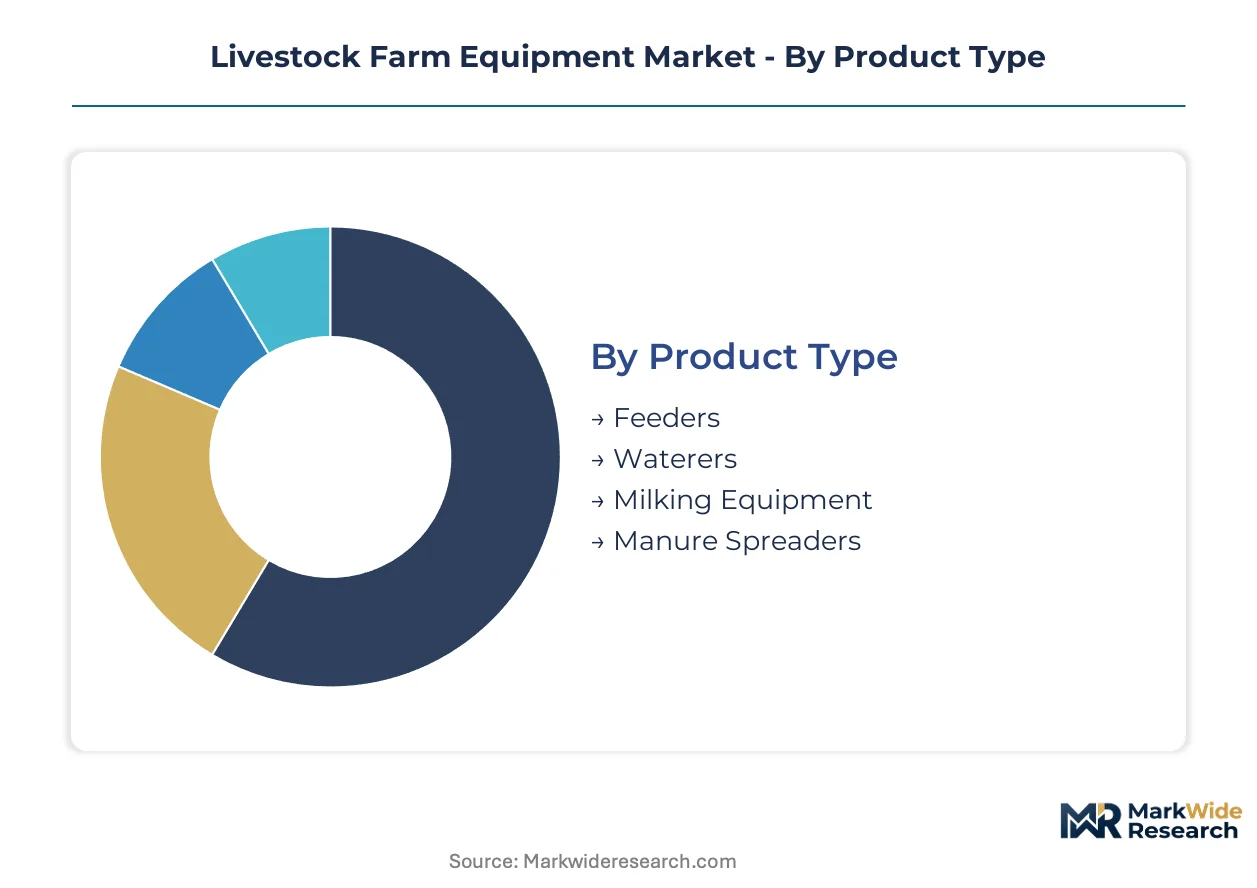
Equipment segmentation in livestock agriculture reveals divergent margin structures across automation tiers. Procurement decisions increasingly weight total cost of ownership against labor substitution potential rather than upfront capital outlay alone.
Product Type:
Farmers prioritize corrosion resistance and washdown compatibility when selecting equipment categories for high-moisture barn environments.
- Milking Equipment:Stainless steel parlor infrastructure and robotic milking arms extract fluid under vacuum pressure with automated teat cleaning cycles. Dutch dairy cooperatives dominate procurement volumes as Rabobank-financed expansions specify integrated milking systems for greenfield facilities.
- Feeders:Auger-driven and conveyor-based distribution systems meter rations by weight or time interval across multiple pen configurations. Bavarian dairy operations concentrate demand where precision feeding algorithms target three-to-five percentage point feed conversion gains under margin compression.
- Waterers:Heated trough and nipple drinker systems prevent freeze-thaw damage in cold-climate housing. Frost-resistant polymer construction addresses seasonal operational continuity requirements.
- Manure Spreaders:Tanker and trailer-mounted applicators distribute slurry across field boundaries with variable-rate injection capability. Danish pork producers accelerate replacement cycles under EU Green Deal nitrogen emission caps.
Volume sits with milking equipment; growth tilts toward autonomous feeding systems.
Technology:
Technology selection hinges on legacy barn infrastructure compatibility and available electrical backbone capacity.
- Autonomous Systems:Self-propelled feeding robots and unmanned manure collection platforms navigate barn corridors using LiDAR and machine vision. Polish and Romanian operations face deployment barriers where ethernet infrastructure requires parallel electrical upgrades.
- Robotics:Articulated milking arms and automated teat preparation systems eliminate fixed-stall labor bottlenecks. Nordic cooperatives specify these as standard for new-build dairy facilities.
- IoT Solutions:Wireless sensor networks transmit estrus, lameness, and rumination data to centralized dashboards. French mid-scale producers favor subscription telemetry pricing over capital-intensive equipment purchases.
- Precision Agriculture:GPS-guided field machinery and variable-rate nutrient application optimize forage production for on-farm feed sourcing.
Installed base concentrates in precision agriculture tools; steepest expansion trajectory belongs to autonomous systems retrofit demand.
Application:
Application focus determines equipment scale specifications and regulatory compliance pathways.
- Dairy Farming:Climate-controlled housing, milking infrastructure, and calf rearing systems dominate capital allocation. German Bavarian belt and Dutch cooperative networks anchor regional demand concentration.
- Poultry Farming:Automated feeding lines, egg collection conveyors, and ventilation systems engineered for high-density housing configurations.
- Beef Production:Handling chutes, weighing systems, and backgrounding facility equipment optimized for growth-phase management.
- Aquaculture:Oxygenation, feeding, and water quality monitoring systems for land-based recirculating systems.
Revenue pools concentrate in dairy applications; poultry automation is climbing the fastest on labor substitution economics.
End User:
End-user category shapes procurement scale and service contract structuring.
- Agricultural Cooperatives:Multi-farm membership structures negotiate fleet-scale service contracts bundling maintenance, telemetry, and upgrade pathways. Dutch dairy cooperatives exemplify consolidated purchasing power.
- Livestock Producers:Corporate and family-owned operations with direct control over capital expenditure decisions.
- Farmers:Individual owner-operators selecting equipment through dealer networks with financing arrangements.
- Researchers:University and government experimental stations procuring specialized monitoring equipment for herd behavior and nutrition studies.
Transaction volume flows through farmers; cooperative procurement is gaining share fastest on economies of scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock availability in Jamshedpur anchors Indian fabrication capacity for corrosion-resistant dairy infrastructure. German engineering clusters around Stuttgart and Dortmund concentrate precision milking system manufacturing. Dutch cooperative banking networks in Friesland and Overijssel direct capital flows toward automated barn installations.
Germany
Bavarian dairy cooperatives drive demand for robotic milking arms and precision feeding systems. The EU F-Gas Regulation compels heat pump retrofits in climate-controlled housing across Lower Saxony pork operations. Stuttgart engineering fabricators supply stainless steel parlor infrastructure to Central European export markets.
Netherlands
Rabobank-financed cooperative structures consolidate procurement for automated milking and manure separation systems. REACH chemical restrictions and nitrogen emission caps under the EU Green Deal accelerate barn renovation cycles in Friesland. Eindhoven-region sensor manufacturers supply telemetry hardware for estrus monitoring deployments.
Denmark
Centralized pork processing belts concentrate demand for automated slurry separation and environmental control systems. Nitrogen emission regulations enforce replacement cycles for manure spreaders and ventilation infrastructure. Aarhus engineering firms specialize in heat pump-based livestock housing thermal management.
France
Mid-scale producers in Brittany and Normandy favor subscription telemetry pricing over capital-intensive equipment purchases. CE marking directives extend conformity timelines for autonomous feeding platforms entering the market. Lyon-based agricultural cooperatives negotiate fleet-scale service contracts bundling maintenance and upgrade pathways.
Spain
Sub-fifteen percent automation rates in Castile-León and Galicia dairy operations create whitespace for milking robot deployment. Iberian pork producers face margin compression that delays precision feeding algorithm adoption. Barcelona equipment distributors serve as entry channels for Nordic and German manufacturers targeting underpenetrated southern European markets.
Livestock Farm Equipment Market Key Industry Players
Global majors compete with regional champions across integrated system portfolios versus specialized component supply. The vendor base stratifies into three tiers: full-stack dairy solution providers, precision agriculture telemetry specialists, and stainless steel fabrication houses serving barn infrastructure. Consolidation pressure concentrates in the mid-tier as cooperative procurement consortia demand single-source accountability for multi-farm service contracts. Dominant competitive moves include backward integration into sensor manufacturing and geographic expansion through distributor acquisition in underpenetrated Iberian and Eastern European markets.
Within the full-stack dairy solutions tier, DeLaval and GEA Group exemplify integrated platform vendors bundling milking infrastructure with long-term service architectures. AGCO Corporation occupies a position bridging precision agriculture telemetry into cattle monitoring applications. Among sensor and automation specialists, Nedap NV and Afimilk Ltd. represent the component-level supply tier where proprietary data protocols create integration friction with competing platforms. Regional fabrication champions in stainless steel parlor construction anchor the third archetype, typically serving national markets through dealer networks with localized maintenance capabilities.
| Leading Market Players |
|---|
| DeLaval |
| GEA Group |
| Deere & Company |
| AGCO Corporation |
| Lely |
| Afimilk Ltd. |
| BouMatic |
| FarmTek |
| Nedap NV |
| Others |
Cost & Logistics Intelligence
Rabobank-financed cooperative structures across Dutch dairy belts concentrate procurement power into consolidated fleet-scale contracts, compressing supplier margins while extending payment terms that strain working capital for stainless steel fabrication houses.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium-tier vendors from unbundled equipment-only suppliers in robotic milking system negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and IoT telemetry inclusion. Cost compression in mid-tier feeders is intensifying because Bavarian cooperatives demand feed conversion efficiency guarantees written into service contracts. Individual farmers in Iberian markets exhibit highest price sensitivity, while Dutch cooperative consortia prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Dual-sourcing mandates from German pork processors and Dutch dairy cooperatives force stainless steel parlor manufacturers to qualify secondary forging houses in Poland and Turkey alongside primary German suppliers. Grade 316L alloy feedstock draws from German, Swedish, and Indian metallurgical producers. Supply chain risk centers on nickel price volatility transmitted through stainless steel alloy contracts. Distribution runs through manufacturer-direct sales teams for large cooperative accounts, with regional dealer networks serving individual farm operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical technician scarcity across dairy belt regions props pricing for vendors bundling predictive maintenance, as labor substitution premiums command contract priority.
For Market Incumbents: Anchor market position through backward integration into sensor manufacturing for estrus monitoring hardware, countering proprietary data protocol fragmentation that threatens unified herd management dashboard adoption. Expand captive service technician training academies in Germany and the Netherlands to address acute maintenance capacity shortages constraining robotic milking arm deployment. For New Entrants and Emerging Players: Direct-to-veterinarian digital channels bypass entrenched dealer networks for lameness detection subscription services, offering lower customer acquisition costs than field sales teams. Target Spanish Castile-León dairy operations where sub-fifteen percent automation rates create whitespace for milking robot deployment without displacing incumbent service relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision agriculture telemetry specialists with established French mid-scale producer subscriptions, as margin compression accelerates capital-light sensor-as-a-service adoption over equipment purchases. Watch nitrogen emission cap enforcement velocity under the EU Green Deal as inflection indicator for manure management engineering demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Proprietary estrus monitoring hardware secures telemetry revenue streams against component supplier margin capture. |
| Cooperative Procurement Consortium Participation | Fleet-scale service contracts with Rabobank-financed Dutch dairy networks concentrate volume and lock out competitors. |
| CE Marking Fast-Track Investment | Reduced conformity assessment timelines accelerate robotic feeding platform commercialization ahead of rivals. |
| Heat Pump Thermal Architecture Redesign | EU F-Gas Regulation compliance opens Dutch and German climate-controlled housing replacement cycles. |
| Iberian Distributor Acquisition | Barcelona-based channels provide established service infrastructure for underpenetrated Spanish and Portuguese automation markets. |
Research Approach
Multi-period observation of robotic milking system installation rates and cooperative procurement contract structures anchored the trend analysis, supplemented by interviews with dairy cooperative procurement directors, precision agriculture telemetry vendors, stainless steel fabrication plant managers, and aftermarket service heads. Secondary validation drew from EU F-Gas Regulation implementation filings, Rabobank agricultural lending disclosures, CE marking directive conformity databases, and customs records for Grade 316L alloy trade flows. Bottom-up equipment shipment tallies triangulated against top-down cooperative capital expenditure surveys.
Input-output matrices mapped stainless steel feedstock costs through fabrication, assembly, and distribution stages to installed equipment value across the projection horizon. Segmentation dimensions modeled include product type, automation technology tier, application focus, and end-user procurement scale. CAGRs were derived from trend extrapolation of retrofit adoption curves and greenfield installation pipelines. Forecast inputs incorporated EU Green Deal nitrogen emission cap trajectories and labor scarcity indices across dairy belt regions.
The model holds under stable stainless steel alloy pricing and continued Rabobank cooperative financing availability; deviation in nickel commodity volatility or Dutch banking regulatory shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Starter Feed Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Hydraulic Squeeze Chute Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Europe Livestock Monitoring Market