
 Frozen Egg Market | 2026-2036
Frozen Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Egg Market Foresight
Flash-freezing and cryogenic processing is reshaping how frozen egg products retain functional properties through extended storage. Cargill Inc. leverages its integrated grain-to-protein supply chain to secure feed cost advantages for contracted layer farms. Michael Foods Inc. sustains one of the largest shell-to-liquid processing footprints in North America. Rembrandt Enterprises anchors its position through in-house breaker operations serving institutional bakeries and QSR chains.
Frozen eggs are shell eggs or liquid egg products blast-frozen at temperatures below minus eighteen degrees Celsius to preserve emulsification, foaming, and coagulation properties for industrial food production. The freezing process typically employs individual quick freezing or plate freezing to minimize ice crystal formation that degrades albumen functionality. Liquid eggs dominate volume flows into baking and confectionery applications where consistent whip stability and pasteurization safety matter most. Powdered eggs compete on transport economics for remote hospitality and military catering channels where refrigeration infrastructure remains limited. Albumin concentrate occupies a premium tier targeting nutritional supplements and high-protein functional foods with specialized fractionation requirements.
The USDA Food Safety and Inspection Service mandates continuous pasteurization for liquid egg products crossing state lines, while the FDA enforces Hazard Analysis Critical Control Point protocols across frozen egg processing facilities. EU hygiene regulations under Regulation EC No 853/2004 specify temperature controls and traceability for egg products entering member state food manufacturing chains. Stakeholders must monitor evolving cage-free and welfare-grade mandates in California and the European Union that are restructuring layer flock sourcing and freezing plant procurement strategies.
Market Dynamics
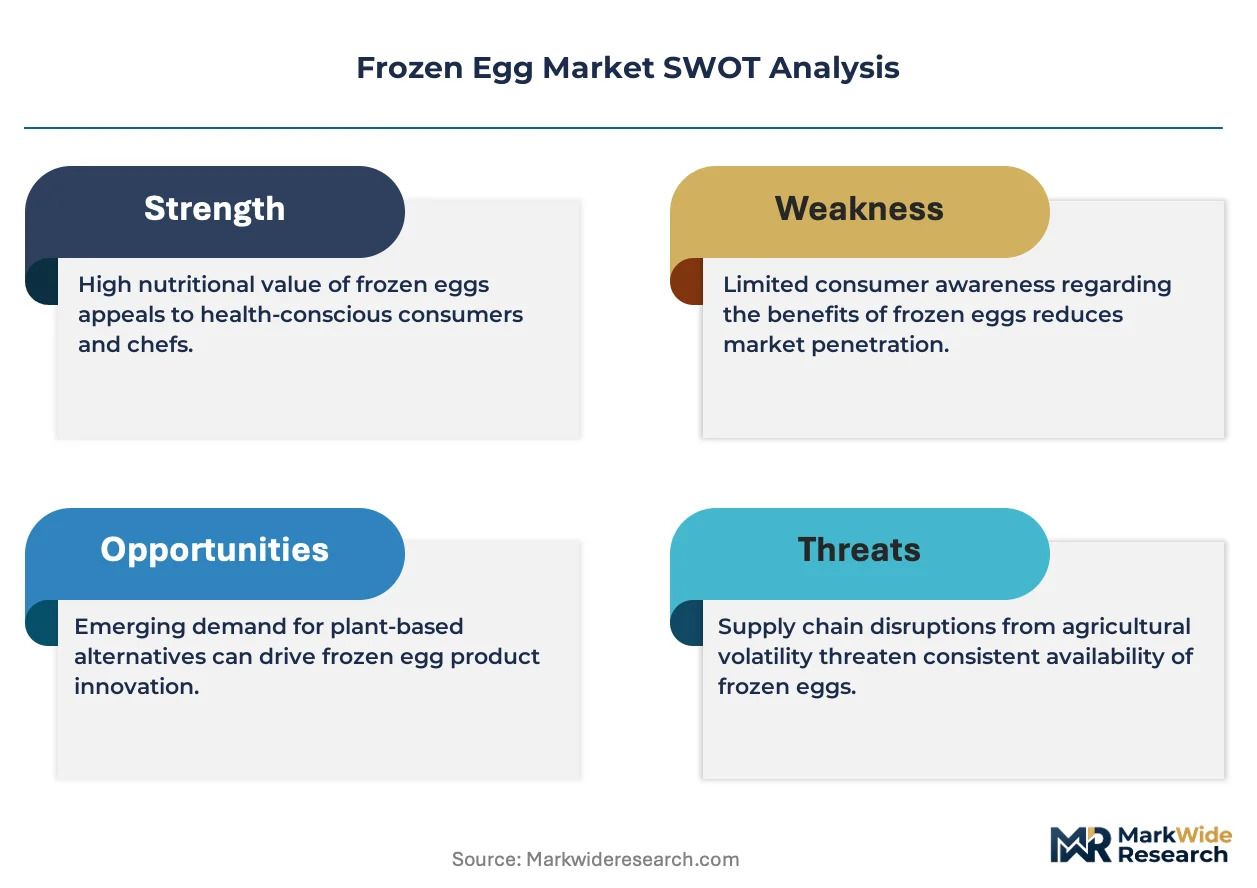
Cold chain logistics modernization and cage-free layer flock mandates are restructuring procurement economics across frozen egg processing, forcing manufacturers to reconfigure sourcing footprints and freezing plant locations.
Growth Catalysts
- EU Hygiene Regulation EC No 853/2004:Mandatory temperature controls and traceability requirements are elevating processing standards that favor capitalized frozen egg producers over shell egg traders in cross-border food manufacturing.
- Flash-freezing technology adoption:Individual quick freezing and cryogenic plate freezing systems preserve albumen functionality for extended storage, expanding addressable shelf-life windows for industrial bakery procurement.
- QSR chain central kitchen expansion:Quick-service restaurant operators in the United States are consolidating egg ingredient procurement through frozen liquid contracts to standardize product consistency across franchise networks.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings directly transmit to layer farm operating costs, compressing margins for integrated frozen egg processors without captive grain handling.
- Layer flock concentration risk:Iowa and Ohio host disproportionate shares of US commercial egg production, creating geographic supply vulnerability to avian influenza outbreaks and climate events.
- Powdered egg substitution threat:Dehydrated egg products compete on transport economics for remote hospitality and military catering channels where cold chain infrastructure remains underdeveloped.
Strategic Opportunities
- China processed food sector expansion:Commercial baking and confectionery growth in Shanghai and Guangzhou is creating demand for imported frozen egg products with certified pasteurization protocols.
- Albumin concentrate nutritional applications:High-protein functional foods and sports nutrition formulations are opening premium pricing tiers for specialized egg fractionation beyond standard liquid or frozen forms.
- California Proposition 12 compliance services:Cage-free and welfare-grade mandates are restructuring layer flock sourcing, creating advisory and certification revenue streams for processors with verified supply chain audit capabilities.
Industry Challenges
- Pasteurization equipment capex intensity:Continuous flow thermal processing systems required for USDA Food Safety and Inspection Service compliance demand seven-figure capital commitments that barrier mid-scale entrants.
- Cross-state regulatory fragmentation:Divergent state-level cage-free implementation timelines and inspection protocols complicate national distribution planning for multi-facility processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Egg Market |
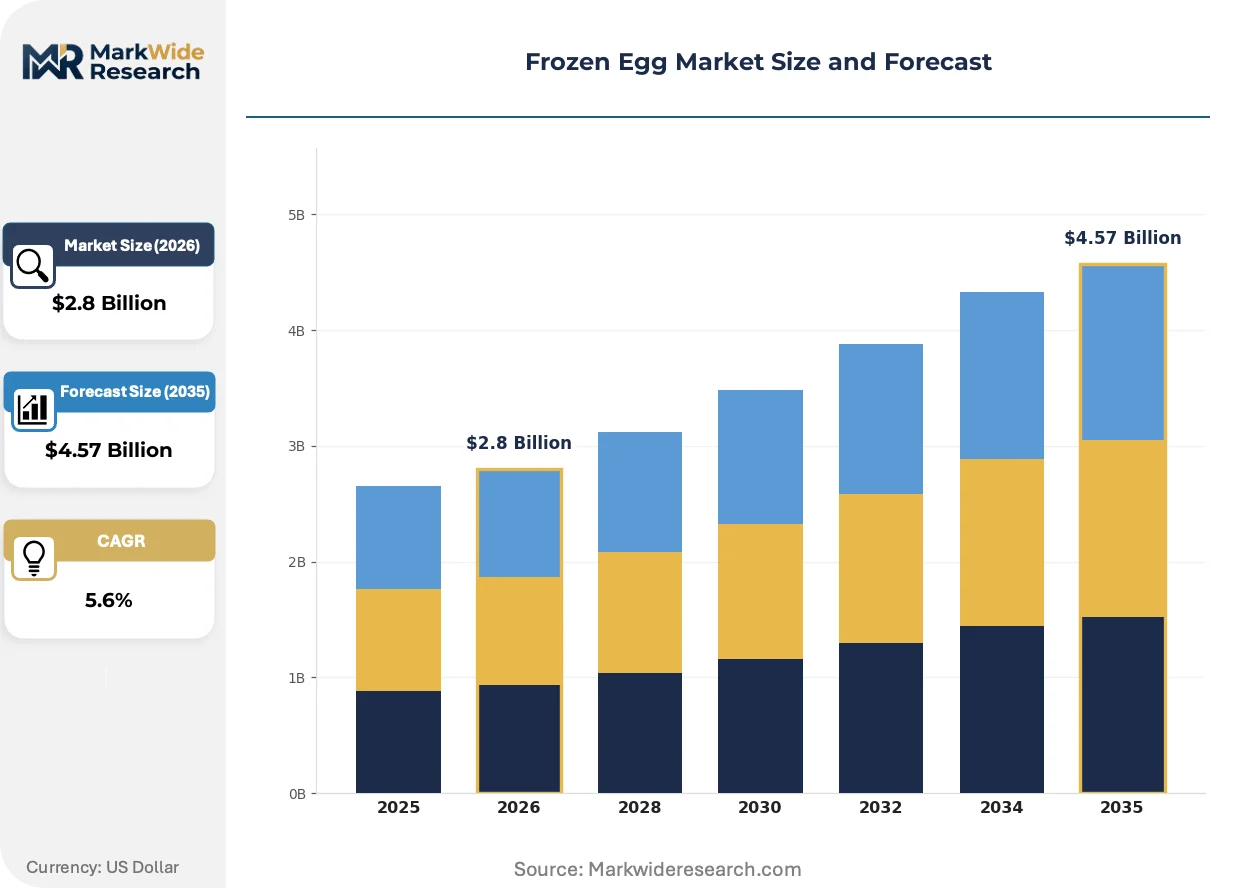
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell Eggs, Liquid Eggs, Powdered Eggs, Albumin Concentrate Application: Baking, Confectionery, Sauces, Meat Processing, Nutritional Supplements End User: Food & Beverage Manufacturers, Bakeries, Hospitality, Healthcare Nutrition Providers Packaging Type: Cartons, Pouches, Drums, Tubs, Bottles |
| Companies Covered | Ballas Egg, Crystal Lake LLC, Cargill Inc., Michael Foods Inc., Rembrandt Enterprises, Ovobest, Bouwhuis Enthoven, Igreca, Pace Farm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Egg Market Shifts & Advancements
Digital supply chain orchestration and precision freezing technologies are compressing quality degradation windows while regulatory compliance automation is reducing audit friction across multi-jurisdictional operations.
Cryogenic nitrogen injection systems for plate freezing are virtualizing traditional blast-freezing throughput constraints. North American institutional bakeries are retrofitting receiving facilities for cryogenic-compatible storage at accelerating pace. This technology is virtualizing the historical trade-off between freezing speed and capital efficiency that favored large-scale central plants over distributed processing nodes.
EU Green Deal farm-to-fork sustainability reporting requirements are mandating Scope 3 emissions disclosure for egg product imports into member states. Frozen egg processors must now document layer feed origin, manure management practices, and transport refrigeration carbon intensity. German and Dutch food manufacturers are prioritizing suppliers with verified lifecycle assessments, shifting procurement preference toward integrated grain-to-egg operations with captive carbon accounting.
Direct contracting between frozen egg processors and quick-service restaurant procurement teams is displacing traditional foodservice distributor intermediation. Large QSR chains are unbundling ingredient sourcing from broadline distribution, negotiating multi-year liquid egg supply agreements with volume commitments and price collars. This pattern concentrates most visibly in the United States, where Yum Brands and McDonald's procurement organizations have established dedicated protein category management functions.
Frozen Egg Market Segmentation
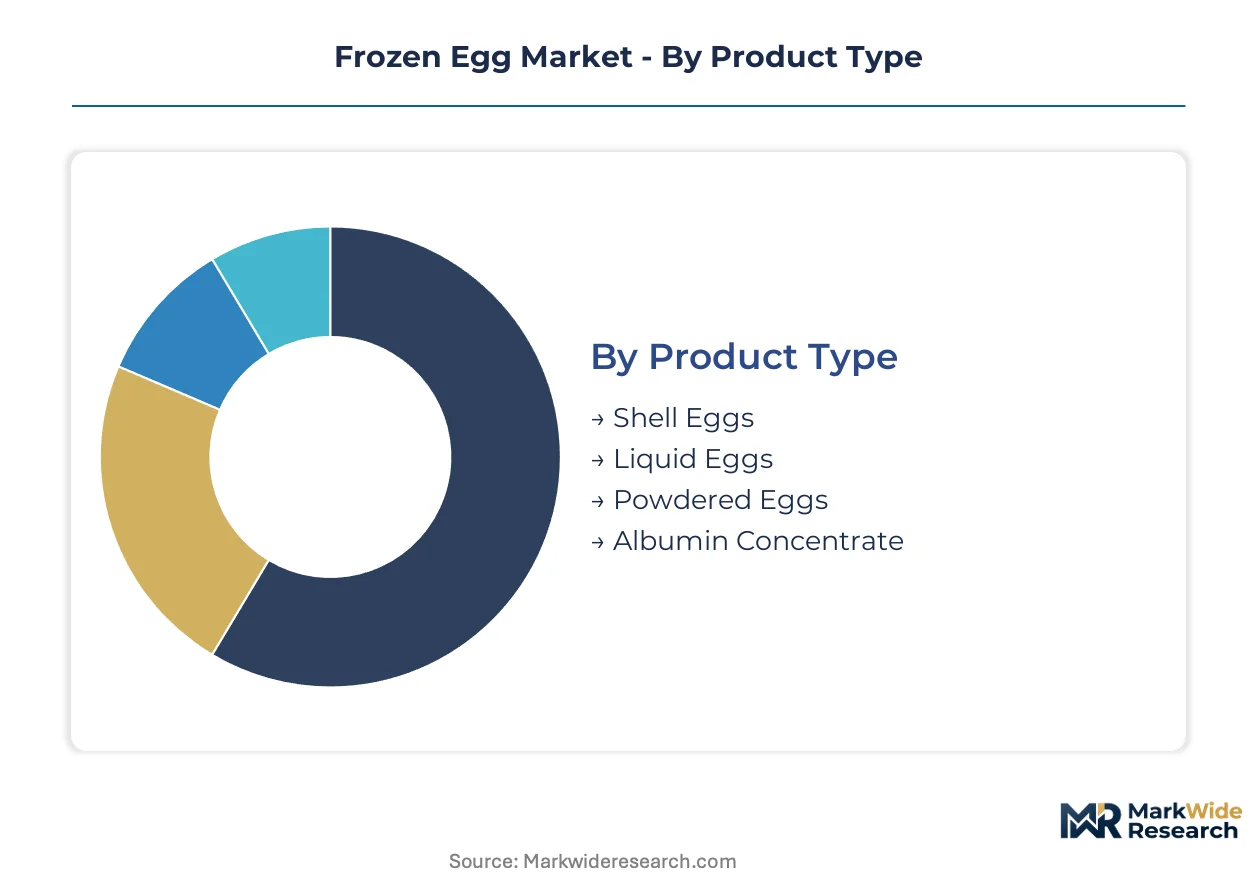
Frozen egg segmentation reveals how functional properties and supply chain economics fragment procurement patterns across industrial food manufacturing. Product form, application specificity, and end-user scale each create distinct margin and logistics requirements that reshape processor specialization.
Product Type:
Cost tier differentiation separates commodity liquid forms from premium fractionated concentrates, with freezing technology intensity determining capital recovery timelines.
- Shell Eggs:Whole eggs blast-frozen in protective coatings retain yolk integrity for extended storage. Demand concentrates in institutional bakeries across Germany and China where shell-to-liquid breaking capacity remains limited. Avian influenza biosecurity protocols constrain sourcing flexibility.
- Liquid Eggs:Pasteurized whole egg, yolk, or white preparations dominate volume flows into industrial baking and QSR central kitchens. The United States hosts the largest installed base of continuous-flow thermal processing systems. USDA Food Safety and Inspection Service compliance mandates create seven-figure capital barriers.
- Powdered Eggs:Spray-dried whole egg and albumen powders serve remote hospitality and military catering channels where cold chain infrastructure is underdeveloped.
- Albumin Concentrate:Specialized fractionation yields high-protein isolates for sports nutrition and functional food formulations with premium pricing tiers.
Liquid eggs hold installed capacity. Albumin concentrate is rotating up the share rankings.
Application:
End-use functionality requirements dictate freezing protocols, with emulsification stability and foaming capacity driving divergent specification standards.
- Baking:Frozen whole eggs and yolks provide consistent leavening and crumb structure for commercial bread and pastry production. Industrial bakeries in the United States and Germany specify cryogenic plate freezing to preserve albumen whip stability through extended distribution cycles.
- Confectionery:Meringue and soufflé applications demand precisely controlled frozen egg white functionality with minimal ice crystal degradation. Belgian and Swiss chocolate manufacturers source specialized liquid white preparations with certified Salmonella-negative protocols.
- Sauces:Mayonnaise and hollandaise bases utilize frozen yolk emulsions with specified phospholipid content for heat-stability.
- Meat Processing:Binder and extender applications in sausage and prepared meats employ frozen whole egg for protein functionality.
- Nutritional Supplements:High-purity albumin concentrates target protein fortification with specialized fractionation and reduced lipid content.
Baking commands volume concentration. Nutritional supplements are climbing the fastest.
End User:
Customer type determines contract structure, with procurement scale separating spot-market hospitality buyers from multi-year volume commitments.
- Food & Beverage Manufacturers:Processed food conglomerates negotiate annual liquid egg supply agreements with price collars and volume guarantees. Cargill Inc. and Michael Foods Inc. maintain dedicated account management for national bakery and sauce producers.
- Bakeries:Regional and artisanal operations source frozen eggs through foodservice distributors with shorter lead times and smaller lot sizes.
- Hospitality:Hotel and restaurant chains with limited cold storage favor powdered egg alternatives for operational simplicity.
- Healthcare Nutrition Providers:Hospital and long-term care facilities specify pasteurized frozen eggs for immunocompromised patient safety protocols.
Food & Beverage Manufacturers hold installed capacity. Healthcare Nutrition Providers are rotating up the share rankings.
Packaging Type:
Volume and handling requirements segment packaging selection, with automation compatibility and shelf-life extension driving material specification.
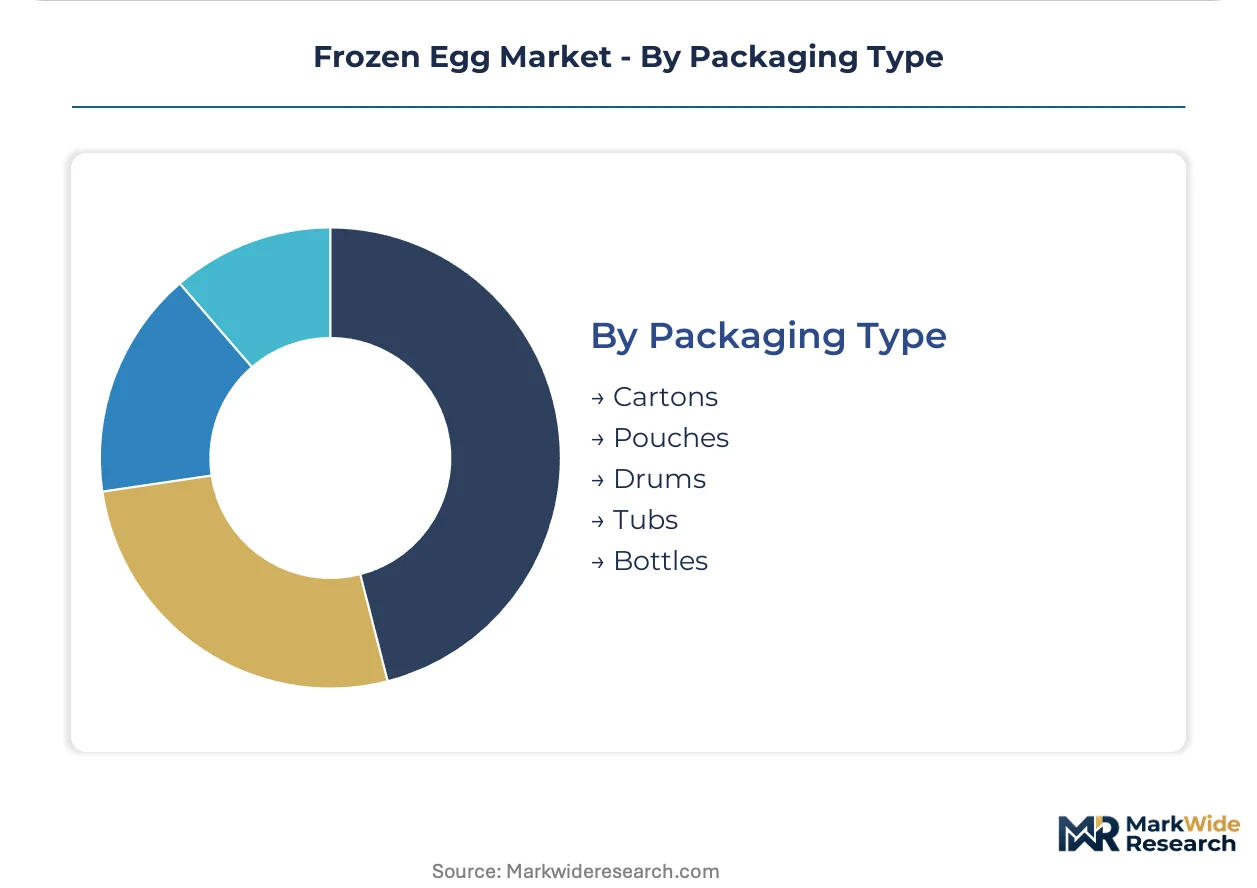
- Cartons:Standard corrugated containment for frozen shell eggs with moisture-resistant coatings.
- Pouches:Flexible film bags for liquid egg portions optimize cube utilization in limited cold storage.
- Drums:Industrial-scale steel or plastic containers for bulk liquid egg transport to manufacturing facilities.
- Tubs:Rigid polyethylene containers for foodservice liquid egg with resealable lids.
- Bottles:PET or HDPE formats for retail-adjacent liquid egg with pour-spout convenience.
Drums hold installed capacity. Pouches are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States frozen egg processors export pasteurized liquid preparations to Canadian and Mexican bakery chains under USMCA tariff preferences. German manufacturers supply frozen albumen concentrates to confectionery producers across Central Europe. Chinese importers source certified frozen whole eggs from Australian and Brazilian suppliers for Shanghai's expanding processed food sector.
United States
QSR central kitchen consolidation drives frozen liquid egg procurement through multi-year supply agreements with volume commitments. USDA Food Safety and Inspection Service mandates continuous pasteurization for interstate commerce, elevating capital barriers for mid-scale processors. Iowa and Ohio host concentrated layer flock operations where avian influenza biosecurity protocols constrain sourcing flexibility.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia specify cryogenic plate freezing to preserve albumen whip stability through extended distribution cycles. EU Green Deal farm-to-fork sustainability reporting requires Scope 3 emissions disclosure for imported egg products, favoring suppliers with verified lifecycle assessments. Hamburg serves as the primary cold chain logistics hub for frozen egg distribution into Scandinavian markets.
China
Commercial baking growth in Shanghai and Guangzhou creates demand for imported frozen egg products with certified pasteurization protocols. SAMR enforces dual carbon goals that pressure processors to document feed origin and transport refrigeration carbon intensity. Yangtze River Delta food manufacturers prioritize suppliers with integrated grain-to-egg operations and captive carbon accounting capabilities.
Brazil
Layer flock expansion in São Paulo and Minas Gerais positions Brazilian processors as cost-competitive exporters to Middle Eastern and African markets. ANVISA hygiene regulations align with Codex Alimentarius standards for frozen egg product safety certification. Paraná's integrated poultry operations leverage soybean meal feed cost advantages to undercut North American export pricing.
Netherlands
Randstad-based food manufacturers source frozen egg white preparations for confectionery and sauce applications requiring precise emulsification stability. ECHA REACH compliance obligations extend to egg product imports, mandating chemical safety documentation for processing aids. Eindhoven Region hosts specialized fractionation facilities serving sports nutrition and functional food formulations.
Frozen Egg Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. Consolidation concentrates among integrated grain-to-protein operations with captive feed handling and multi-facility freezing footprints. Three archetypes dominate: vertically integrated agricultural conglomerates, dedicated egg processing specialists, and regional co-operative breakers. Competitive moves center on backward integration into layer flock ownership and cryogenic freezing capacity expansion to capture premium bakery contracts.
Within the integrated agricultural tier, Cargill Inc. exemplifies channel control through feed-to-egg supply chain coordination. Michael Foods Inc. and Rembrandt Enterprises occupy positions as dedicated processing specialists with North American institutional bakery relationships. These three anchors represent distinct strategic postures: agricultural conglomerate diversification versus focused egg fractionation expertise versus co-operative scale aggregation.
| Leading Market Players |
|---|
| Ballas Egg |
| Crystal Lake LLC |
| Cargill Inc. |
| Michael Foods Inc. |
| Rembrandt Enterprises |
| Ovobest |
| Bouwhuis Enthoven |
| Igreca |
| Pace Farm |
| Others |
Supply & Pricing Matrix
Iowa and Ohio layer flock concentration feeds directly into margin capture by integrated processors with captive feed handling and multi-state pasteurization capacity. Powdered egg alternatives discipline pricing at the transport-limited frontier, while liquid frozen commands premiums where cold chain integrity is verifiable.
Pricing Analysis
Flash-freezing versus cryogenic plate versus traditional blast configurations stratify equipment investment tiers that processors recover through contract structures. Three-tier pricing separates premium albumin concentrate from standard liquid whole egg from economy powdered alternatives, with EU Green Deal carbon accounting and California Proposition 12 compliance emerging as price differentiation drivers. Cost compression in standard liquid tiers is intensifying because feed cost volatility transmits directly from corn and soybean markets. Food and beverage manufacturers with annual volume commitments exhibit lowest price sensitivity; hospitality operators without cold storage infrastructure face highest substitution elasticity to powdered formats.
Supply Chain Analysis
Corn and soybean meal feedstock sourcing centers on the US Midwest, Brazil's Paraná state, and Ukraine's Black Sea corridor before layer flock placement decisions lock in regional processing footprints. Frozen egg production draws from specialized plate freezing equipment, continuous-flow pasteurization systems, and cryogenic nitrogen infrastructure that create capital barriers. Single-source vulnerability concentrates in Iowa and Ohio layer operations where avian influenza biosecurity protocols constrain rapid sourcing pivots. Distribution runs through dedicated cold chain logistics providers with temperature-verified custody transfer to institutional bakery and QSR central kitchen facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct contracting platforms between frozen egg processors and QSR procurement teams represent a platform-economics inflection, unbundling ingredient sourcing from broadline distribution intermediaries and rewiring margin capture toward volume-commitment structures.
For Market Incumbents: Insulate pasteurization capacity advantages by securing multi-year feed supply agreements with price collars that neutralize corn and soybean volatility. Cryogenic freezing retrofit programs at regional breaker facilities defend against emerging Brazilian export competition by preserving albumen functionality premiums for European bakery contracts. For New Entrants and Emerging Players: Establish a beachhead in albumin concentrate fractionation for sports nutrition applications where specialized processing creates margin shelter from commodity liquid competition. China's Yangtze River Delta commercial baking expansion offers the most penetrable geography for certified-pasteurization imports, with carbon-accounting documentation as the critical go-to-market credential. For Investors and Strategic Acquirers: Capital is best deployed toward integrated grain-to-egg operations with captive carbon accounting capabilities and verified lifecycle assessment documentation. Long-term viability across the analysis window favors processors with backward integration into layer flock ownership rather than toll-breaking models. The signal to watch is QSR procurement team unbundling velocity as indicator of direct-contracting platform maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Freezing Capacity Expansion | Preserves albumen whip stability for extended distribution cycles demanded by German industrial bakeries. |
| Backward Integration into Layer Flock Ownership | Neutralizes feed cost volatility and satisfies EU Green Deal Scope 3 emissions disclosure requirements. |
| California Proposition 12 Compliance Certification | Unlocks cage-free and welfare-grade procurement channels restructuring national sourcing footprints. |
| Direct QSR Procurement Platform Development | Displaces foodservice distributor intermediation through multi-year liquid egg volume-commitment structures. |
| Albumin Concentrate Fractionation Investment | Captures premium pricing tiers in sports nutrition and functional food formulations beyond commodity forms. |
Research Methodology
Cross-validation between continuous pasteurization equipment manufacturer technical specifications and USDA Food Safety and Inspection Service compliance databases anchors the qualitative findings on capital barrier intensity. Primary interviews with layer farm operations managers, frozen egg plant engineers, QSR procurement category directors, and cold chain logistics coordinators were combined with secondary validation through FDA inspection records, EU Rapid Alert System for Food and Feed notifications, and customs trade flow documentation. Bottom-up installed capacity estimates and top-down demand segmentation from commercial baking and confectionery production indices complete the triangulation.
Calibration against historical feed cost volatility episodes and avian influenza supply disruption events tests projection sensitivity across product form, application, and end-user dimensions. Segmentation modeling incorporates freezing technology tier, pasteurization protocol, packaging format, and regional regulatory cluster variations. CAGRs were derived from volume-weighted growth rate aggregation across these segments, with layer flock placement cycles and QSR central kitchen expansion timelines as industry-specific forecast inputs.
Stress conditions across corn-soybean price spreads, avian influenza outbreak frequency, and EU carbon border adjustment implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cage-free mandate adoption velocity and cryogenic freezing technology diffusion rates. Cross-checking against USDA National Agricultural Statistics Service layer flock inventory reports and EU egg product import certification data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Organic Feed Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Taro Market