
 Latin America Agricultural Machinery Market | 2026-2036
Latin America Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Agricultural Machinery Market Foresight
Medium-scale cooperatives are rotating toward precision-equipped tractor fleets as Brazil's Mato Grosso soy belt consolidates operational scale. Deere & Company anchors its regional position through extensive dealer networks and localized manufacturing capacity. CNH Industrial competes aggressively in the harvester segment with models calibrated for Latin American crop profiles. AGCO Corporation differentiates via its Fendt and Valtra brands, targeting premium-tier cooperative buyers with telemetry-integrated platforms.
Latin America agricultural machinery encompasses mechanized equipment engineered for soil preparation, planting, cultivation, and harvesting across diverse topographies and climate zones, with power ratings typically spanning 50 to 400 horsepower and implements designed for row-crop, broadacre, and specialty applications. Tractors constitute the foundational revenue pool given their universal deployment across all farm scales, while harvesters command premium margins tied to seasonal utilization intensity and technology integration. Precision Agriculture represents the fastest-expanding technology dimension as GPS guidance, variable-rate application, and yield mapping systems migrate from large estates to mid-tier operations. Smart Farming and IoT Solutions are reshaping aftermarket service models through predictive maintenance and fleet telematics.
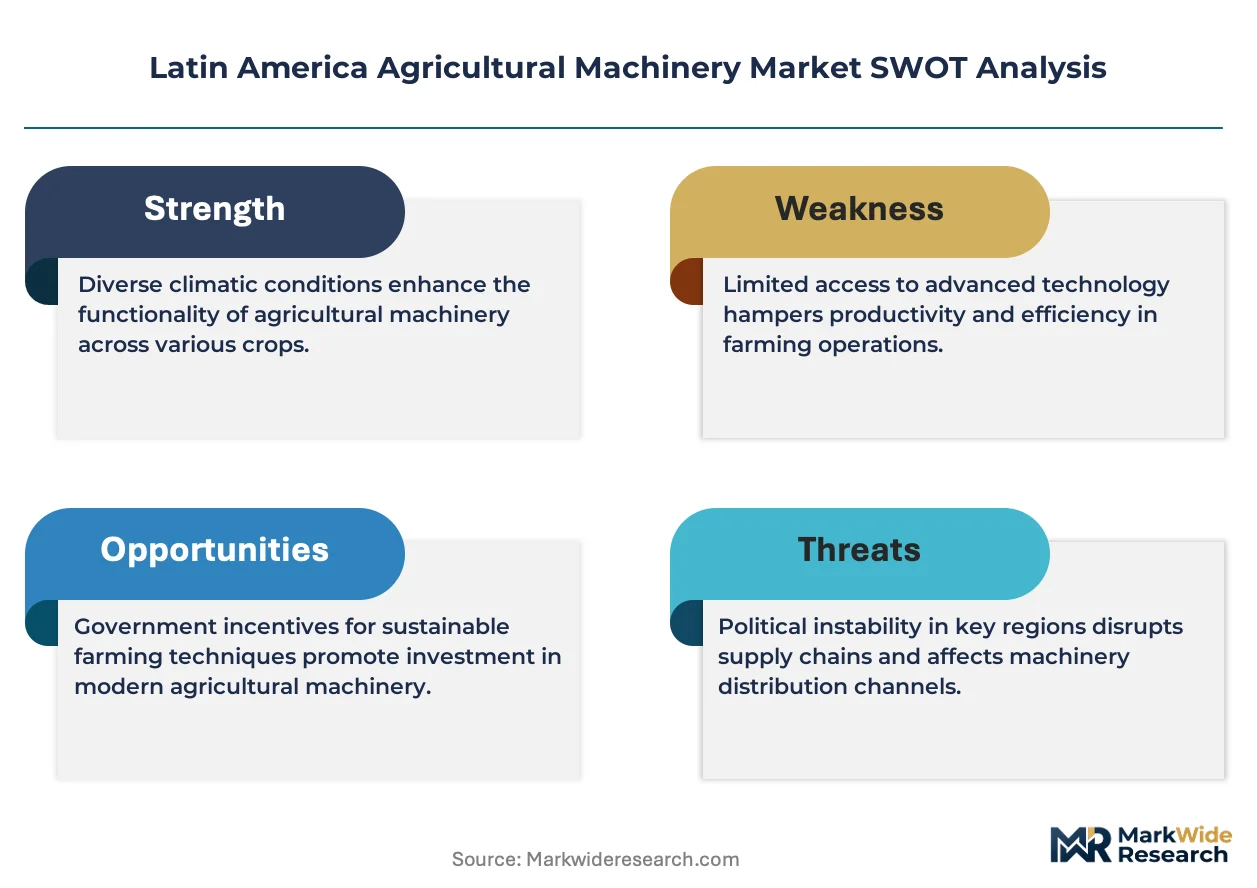
Brazil's MAPA and Argentina's SENASA enforce equipment safety and emissions compliance that manufacturers must satisfy for market access, while Mexico's NOM standards govern imported machinery certification. PROTRATOR and similar national subsidy frameworks directly shape purchasing cycles and equipment specification tiers across the region. Stakeholders must monitor how evolving emissions thresholds and digital connectivity requirements will reconfigure product development priorities and aftermarket revenue architectures.
Market Dynamics
Precision agriculture adoption is decomposing traditional equipment procurement patterns across Latin America's soybean and grain belts, as medium-scale cooperatives demand telemetry-integrated tractor fleets that shift revenue from hardware margins to subscription-based service architectures.
Growth Catalysts
- Brazil's PROTRATOR subsidy program:Direct credit lines for mechanization purchases are accelerating fleet turnover in Mato Grosso and Goiás soy operations, with preference clauses favoring domestically assembled equipment.
- IoT-enabled variable-rate application:GPS-guided seeders and sprayers are reducing input waste by enabling site-specific management across Argentina's Pampas grain region, justifying premium equipment premiums for cooperatives.
- Consolidation of medium-scale farms:Operational scale expansion in Rio Grande do Sul and Paraná is creating demand for 150-250 horsepower tractor classes previously dominated by imported used machinery.
Market Restraints
- Import dependency for precision electronics:GPS modules, yield sensors, and telematics hardware concentrate sourcing from East Asian suppliers, exposing Brazilian assemblers to currency volatility and extended lead times.
- Stringent emissions compliance:Brazil's CONAMA resolutions and Argentina's SENASA technical standards are phasing out Tier 2 diesel engines, forcing premature obsolescence of refurbished equipment pools that served smallholder segments.
- Credit access fragmentation:Rural financing gaps in Paraguay, Bolivia, and Ecuador limit machinery penetration outside the Southern Cone core, constraining addressable market expansion.
Strategic Opportunities
- Underpenetrated Colombian llanos:Large-scale oil palm and rice expansion in Meta and Casanare departments lacks mechanization density, creating first-mover advantage for precision-equipped fleet providers.
- Telematics-integrated aftermarket services:Predictive maintenance platforms leveraging harvester operational data are opening recurring revenue streams independent of new equipment sales cycles.
- Agrivoltaic machinery compatibility:Dual-use solar installations over cropping areas in Chile's Coquimbo region are stimulating demand for low-clearance, electric-compatible implement configurations.
Industry Challenges
- Precision agriculture technician scarcity:Shortage of certified specialists for GPS calibration, yield map interpretation, and telemetry troubleshooting is delaying technology adoption timelines for mid-tier cooperatives.
- Legacy fleet integration complexity:Retrofitting 5-15 year old tractors with ISOBUS-compatible implements requires proprietary adapter hardware that fragments maintenance protocols across mixed-brand operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Agricultural Machinery Market |
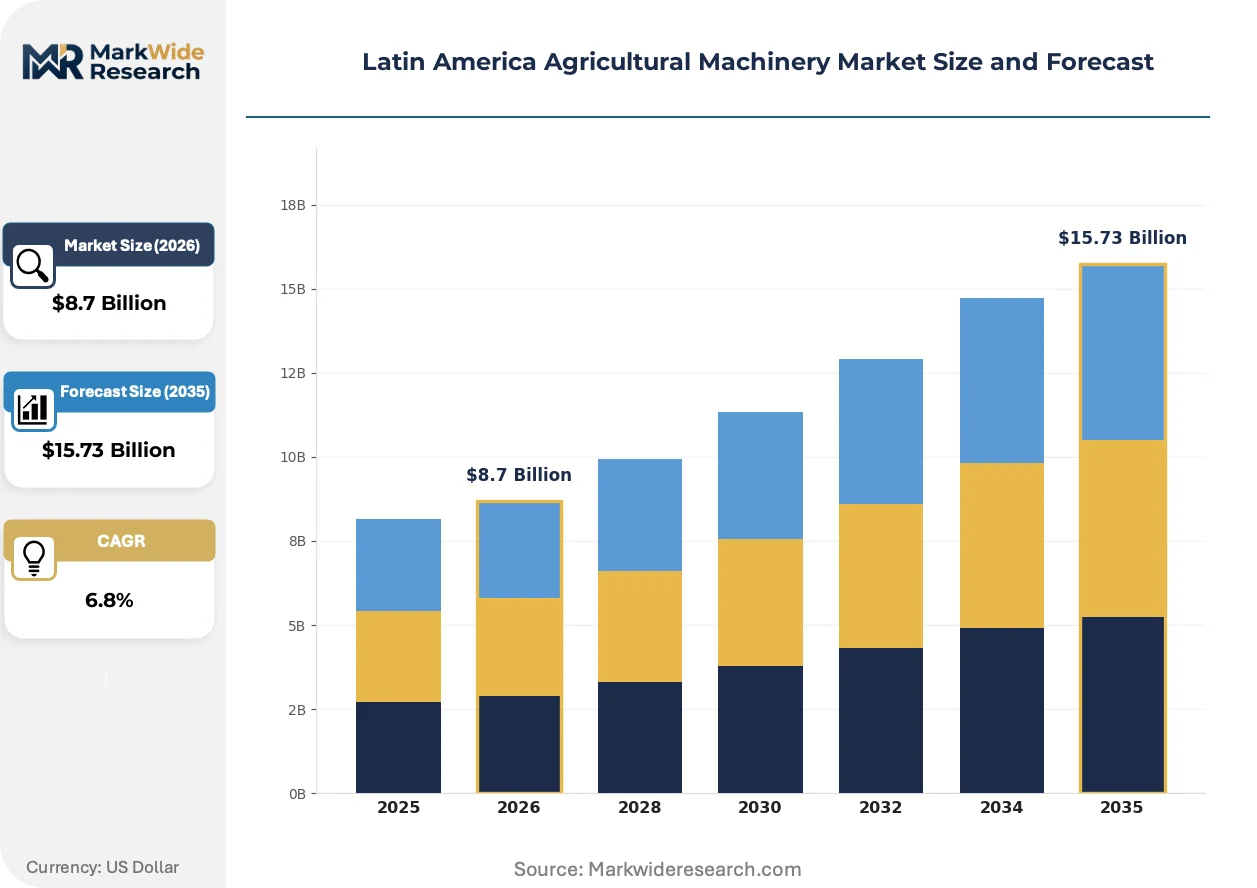
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Harvesters, Seeders Application: Crop Production, Livestock, Forestry, Aquaculture Technology: Precision Agriculture, Autonomous Machinery, Smart Farming, IoT Solutions End User: Farmers, Cooperatives, Agricultural Contractors, Agro-entrepreneurs |
| Companies Covered | Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra and Mahindra Ltd, CLAAS KGaA mbH, Kuhn Group, Yanmar Co. Ltd, Agrale SA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Agricultural Machinery Market Shifts & Advancements
Equipment intelligence layers are migrating from cab-mounted displays to cloud-native platforms, compressing the traditional dealer-service relationship and enabling manufacturer-direct data monetization across Latin American grain belts.
Autonomous guidance systems are decomposing the operator-centric cost structure of large-scale planting and harvesting operations. Brazilian cooperatives in Mato Grosso are deploying driver-optional tractors for night-shift sowing windows, compressing seasonal labor constraints and enabling 24-hour utilization cycles that justify premium capital commitments.
Brazil's MAPA is tightening conformity assessment procedures for agricultural machinery under INMETRO Ordinance 389, requiring third-party certification for electromagnetic compatibility and functional safety of electronic control units. Argentine manufacturers serving cross-border markets are consolidating testing protocols to avoid dual compliance costs, with harvester electronics facing the steepest recertification burdens.
Cooperative buyers are consolidating procurement authority through centralized purchasing federations, displacing individual farm-level dealer relationships. Federations in Rio Grande do Sul and Santa Fe are negotiating fleet-scale telemetry packages directly with manufacturers, compressing regional dealer margins while securing standardized service-level agreements across multi-site operations.
Latin America Agricultural Machinery Market Segmentation
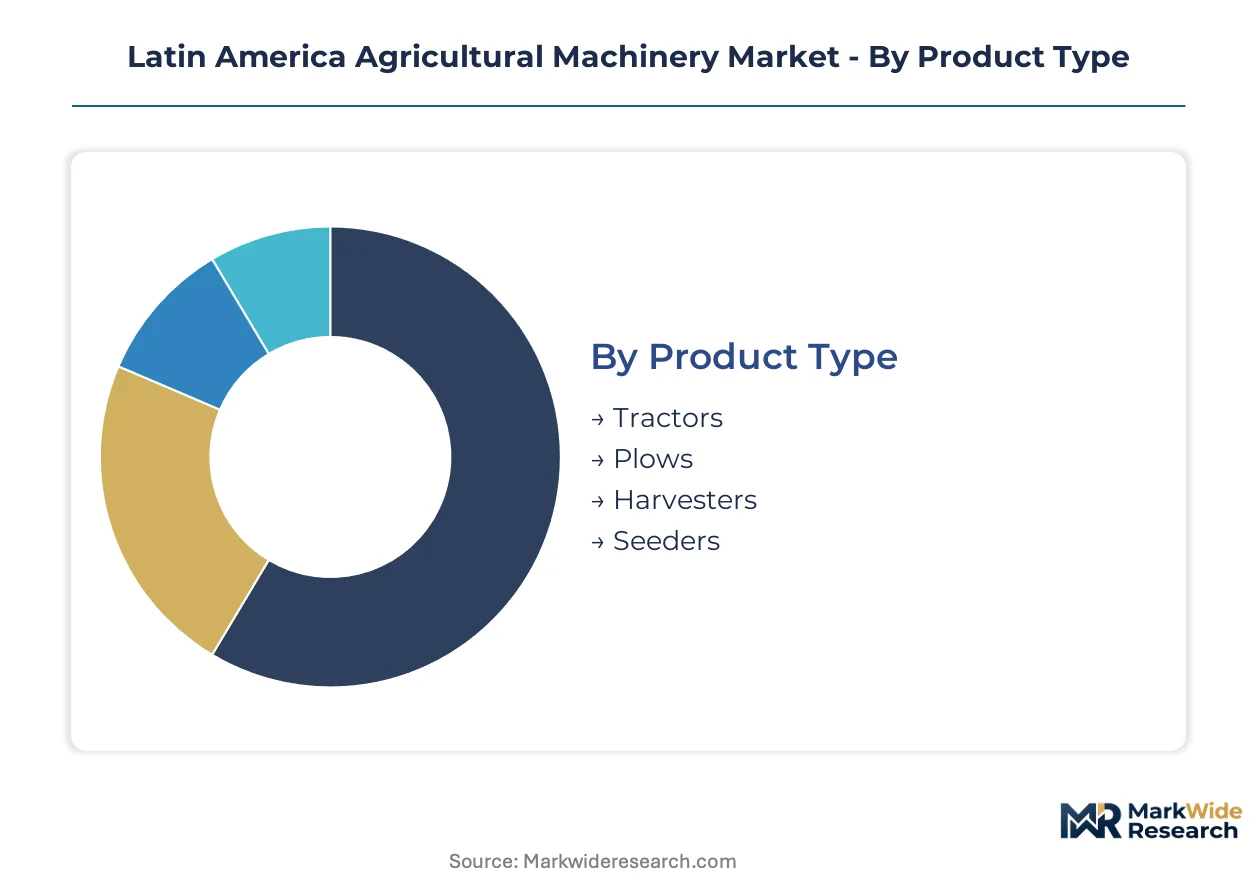
Segmentation clarity matters for Latin America's agricultural machinery sector because subsidy eligibility, financing terms, and precision technology adoption rates diverge sharply across equipment categories and user types. Understanding these fault lines enables manufacturers to align product development with PROTRATOR program specifications and cooperative procurement patterns.
Product Type:
Tractors face substitution pressure from refurbished imported units in Paraguay and Bolivia, while harvesters defend their position through technology integration that used equipment cannot replicate.
- Tractors:Power ratings from 50 to 400 horsepower span utility, row-crop, and broadacre configurations. Demand concentrates in Brazil's Mato Grosso soy belt where medium-scale cooperatives are rotating toward precision-equipped fleets to maximize PROTRATOR subsidy capture.
- Harvesters:Self-propelled grain and sugarcane harvesters command premium margins tied to seasonal utilization intensity and yield-sensor integration. Argentine Pampas grain operations drive specification requirements for multi-crop threshing systems that reduce downtime between wheat and soybean cycles.
- Plows:Disc and moldboard implements attach to three-point hitch systems across soil preparation windows in Rio Grande do Sul's wheat regions.
- Seeders:No-till and conventional drilling equipment serves Argentina's double-crop soybean-wheat rotations with GPS-guided row spacing.
Tractors retain volume leadership; harvesters hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive crop production equipment from livestock machinery that commands lower per-unit prices but higher service attachment rates.
- Crop Production:Soil preparation, planting, cultivation, and harvesting equipment dominates revenue pools across Brazil's soy belt and Argentina's grain regions. Telemetry-integrated fleets are displacing standalone mechanical systems as cooperatives consolidate procurement authority.
- Livestock:Feed handling, manure management, and pasture maintenance machinery serves cattle operations in Mato Grosso do Sul and Uruguay's beef belt where financing access lags crop-sector equivalents.
- Forestry:Harvesters and forwarders support pulp and timber operations in southern Brazil's Araucaria zones and Chile's radiata pine plantations.
- Aquaculture:Specialized feeding and aeration equipment addresses shrimp farming in Ecuador's El Oro province and tilapia operations in Colombia's Magdalena basin.
Crop production commands the highest capital deployment per hectare; aquaculture presents the narrowest installed base but strongest technology upgrade appetite.
Technology:
Application maturity varies dramatically, with precision agriculture migrating from large estates to mid-tier operations while autonomous systems remain confined to demonstration deployments.
- Precision Agriculture:GPS guidance, variable-rate application, and yield mapping systems reduce input waste across site-specific management zones. Brazilian cooperatives in Goiás justify premium equipment spend through fertilizer savings that recover capital within two growing seasons.
- Smart Farming:Cloud-native platforms compress dealer-service relationships by enabling manufacturer-direct data monetization and predictive maintenance scheduling.
- IoT Solutions:Fleet telematics and sensor networks connect implements to centralized monitoring dashboards for real-time operational visibility.
- Autonomous Machinery:Driver-optional tractors for night-shift sowing are operational in Mato Grosso demonstration fleets but face regulatory uncertainty under Brazil's MAPA conformity assessment protocols.
Precision agriculture retains volume leadership; smart farming platforms hold the steepest expansion curve.
End User:
Customer type determines procurement channel access, with cooperatives leveraging centralized purchasing federations that individual farmers cannot replicate.
- Cooperatives:Medium-scale federations in Rio Grande do Sul and Santa Fe negotiate fleet-scale telemetry packages directly with manufacturers, compressing regional dealer margins while securing standardized service-level agreements.
- Farmers:Individual proprietors in Paraguay and Bolivia depend on informal credit and refurbished equipment pools that limit precision technology penetration.
- Agricultural Contractors:Custom service providers in Brazil's Cerrado frontier supply planting and harvesting capacity to landholders who lack capital for owned fleets.
- Agro-entrepreneurs:Investor-backed farming ventures in Colombia's Meta department and Chile's Coquimbo region prioritize electric-compatible implement configurations for agrivoltaic compatibility.
Cooperatives retain volume leadership; agro-entrepreneurs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos grain terminal expansion underwrites Brazil's machinery import capacity, while the Paraná-Paraguay waterway system enables Argentine equipment distribution into landlocked interior markets.
Brazil
Mato Grosso's soy belt drives demand for 150-250 horsepower tractor classes as medium-scale cooperatives consolidate operational scale. MAPA's PROTRATOR subsidy program accelerates fleet turnover through preferential credit lines favoring domestically assembled equipment. São Paulo state's manufacturing corridor anchors localized production capacity for precision-electronics integration.
Argentina
The Pampas grain region generates specification requirements for multi-crop threshing systems that reduce downtime between wheat and soybean cycles. SENASA enforces technical standards phasing out Tier 2 diesel engines and mandating electromagnetic compatibility certification. Rosario's agro-industrial cluster concentrates harvester assembly operations serving cross-border Southern Cone markets.
Mexico
Bajío region fruit and vegetable operations create demand for specialized cultivation equipment with precision planting capabilities. NOM standards govern imported machinery certification for electromagnetic compatibility and functional safety of electronic control units. Querétaro's manufacturing hub supports component sourcing for North American agricultural equipment supply chains.
Chile
Coquimbo region agrivoltaic installations stimulate demand for low-clearance, electric-compatible implement configurations. The country's national agricultural regulator enforces conformity assessment procedures for machinery safety and emissions compliance. Maule Valley's fruit production belt concentrates precision sprayer deployment for vineyard site-specific management.
Colombia
Meta and Casanare departments in the Colombian llanos lack mechanization density despite large-scale oil palm and rice expansion. The national agricultural financing authority structures rural credit programs targeting first-mover fleet providers. Bogotá's procurement federations negotiate centralized equipment purchases for cooperative buyers across the Orinoco basin.
Latin America Agricultural Machinery Market Competitive Landscape
Listed leaders compete with private specialists across telemetry-integrated platform development, creating a tiered structure where scale-driven manufacturers anchor volume positions while regional assemblers defend margin through subsidy-aligned domestic production. Strategic archetypes include precision-technology integrators, subsidy-optimized local assemblers, and used-equipment refurbishers serving price-sensitive segments. Dominant competitive moves encompass backward integration into electronics sourcing and geographic expansion through dealer network consolidation.
Within the precision-technology tier, Deere & Company and CNH Industrial exemplify listed leaders with extensive regional dealer networks, while AGCO Corporation occupies a position targeting premium-tier cooperative buyers through brand differentiation. Kubota Corporation represents the mid-scale specialist archetype, and Mahindra and Mahindra Ltd anchors the emerging-market volume segment with cost-optimized configurations.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra and Mahindra Ltd |
| CLAAS KGaA mbH |
| Kuhn Group |
| Yanmar Co. Ltd |
| Agrale SA |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for GPS modules and yield sensors from East Asian suppliers compress Brazilian assemblers' pricing flexibility, binding equipment cost structures to currency volatility while cooperative buyers exploit fleet-scale procurement to extract volume concessions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Latin American equipment markets. Price differentiation rests on telemetry integration density and PROTRATOR subsidy eligibility tier. Cost compression in the economy tier is intensifying because refurbished imported units from Paraguay and Bolivia undercut domestic assembly margins. Individual farmers in landlocked markets exhibit highest price sensitivity, while Rio Grande do Sul cooperatives demonstrate lowest sensitivity due to centralized federation bargaining power.
Supply Chain Analysis
Strategic stockpiling of precision electronics dominates inventory strategy as Brazilian manufacturers buffer against extended lead times from Taiwan, South Korea, and China. Raw material feeds from German engine component suppliers and Japanese hydraulic systems anchor final assembly quality. Single-source vulnerability concentrates in GPS module sourcing, exposing assemblers to logistics chokepoints at the Port of Santos. Distribution runs through manufacturer-direct fleet contracts with cooperative federations, displacing traditional dealer-centric models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against refurbished imported equipment pools that undercut new machinery margins across Paraguay, Bolivia, and Ecuador. Incumbents must fortify positions against this price-arbitrage threat while capturing precision-technology upgrade cycles.
For Market Incumbents: Shield domestic assembly margins through backward integration into precision electronics sourcing, reducing exposure to East Asian currency volatility. Accelerate certification investment under Brazil's INMETRO Ordinance 389 to create regulatory barriers against non-compliant refurbished imports. Channel control through exclusive telemetry service agreements locks cooperative buyers into recurring revenue architectures.
For New Entrants and Emerging Players: Differentiate on agrivoltaic-compatible implement configurations targeting Chile's Coquimbo region and Colombia's Meta department oil palm expansion. The Colombian llanos present the most penetrable geography given mechanization density gaps alongside large-scale commercial farming growth. A manufacturer-direct fleet leasing model bypasses established dealer networks that incumbent players dominate.
For Investors and Strategic Acquirers: Long-term, this sits as a precision-technology consolidation play because telemetry-integrated platforms are compressing hardware margins into subscription-based service architectures. Acquisition targets should display captive maintenance networks or proprietary yield-data analytics capabilities. Watch PROTRATOR subsidy allocation shifts as the inflection indicator for fleet turnover velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Electronics | Reduces currency exposure to Taiwan and South Korean GPS module suppliers for Brazilian assemblers. |
| Telemetry Platform Standardization | Enables manufacturer-direct data monetization across Mato Grosso cooperative federations. |
| Agrivoltaic Implement Development | Captures emerging demand from Chile's Coquimbo dual-use solar installations. |
| Certification Pre-Positioning | Accelerates INMETRO conformity assessment compliance ahead of MAPA enforcement tightening. |
| Aftermarket Service Network Expansion | Locks recurring revenue through predictive maintenance contracts independent of equipment sales cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of equipment registration databases, customs import records, and subsidy program disbursement filings. Primary interviews engaged agricultural cooperative procurement directors, OEM regional sales managers, precision agriculture technicians, and MAPA regulatory compliance officers. Secondary validation drew from INMETRO certification registries, PROTRATOR credit allocation reports, and SENASA technical standard updates. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction across the analysis window.
Segmentation dimensions modeled span power rating tier, crop application type, precision technology integration level, and end-user procurement channel. CAGRs derive from logistic adoption curves fitted to cooperative fleet turnover patterns and subsidy program phase-in schedules. Industry-specific forecast inputs incorporate PROTRATOR eligibility rule changes and CONAMA emissions compliance timelines.
Material uncertainties — subsidy program renewal decisions, currency volatility in precision electronics sourcing, and autonomous machinery regulatory clarity — sit outside the modeled envelope. Forecasts reflect assumptions regarding cooperative consolidation continuity and Tier 3 engine adoption rates. Revision becomes warranted when PROTRATOR credit volume crosses thresholds that alter fleet replacement elasticity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
South America Agricultural Sprayers Market