
 North America Feed Antibiotics Market | 2026-2036
North America Feed Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Antibiotics Market Analytics
Broiler poultry operations is consolidating procurement volumes as integrators expand contract grower networks across the southeastern United States. Zoetis Inc. leverages its veterinary distribution infrastructure to maintain formulary access across major poultry complexes. Elanco Animal Health Inc. anchors its position through R&D intensity in alternative growth-promotion technologies. Phibro Animal Health Corporation specializes in ionophore manufacturing scale that sustains cost advantages in ruminant applications.
Feed antibiotics comprise antimicrobial compounds administered through animal feed at subtherapeutic or therapeutic doses to enhance feed efficiency, control disease, and improve weight gain in livestock production systems; tetracyclines function as broad-spectrum agents effective against gram-positive and gram-negative bacteria in swine respiratory and enteric disease protocols. Tetracyclines and ionophores occupy the largest volume positions due to established efficacy in poultry coccidiosis prevention and cattle feedlot performance, while macrolides represent a faster-growing structural pocket as producers seek alternatives to growth-promotion bans through metaphylactic respiratory disease control. Premix formulations dominate commercial channels because they integrate directly into feed mill operations, though liquid delivery systems are gaining traction in automated swine nursery systems.
FDA Guidance for Industry 209 and 213 reshaped product registration by eliminating growth-promotion claims and mandating veterinary oversight for medically important antibiotics in feed. The USDA and EPA coordinate residue monitoring and environmental discharge standards that constrain manufacturing plant locations and effluent treatment investments. Stakeholders must monitor state-level veterinary practice act variations and emerging FDA enforcement patterns around compounded medicated feeds to anticipate compliance cost trajectories and distribution channel restructuring.
Market Dynamics
FDA Guidance for Industry 209 and 213 enforcement is compressing the therapeutic-use-only transition across US livestock operations, concentrating procurement authority within vertically integrated poultry and swine complexes while eliminating over-the-counter growth-promotion formulations from feed mill inventories.
Growth Catalysts
- Metaphylactic respiratory protocols:Cattle feedlots in Texas and Kansas are expanding macrolide use for disease prevention amid growth-promotion claim eliminations, sustaining ionophore adjacency demand.
- Veterinary Feed Directive compliance infrastructure:Large integrators in the US Southeast are capturing formulary access advantages through captive veterinary staff, locking out smaller independent operators.
- Canada's veterinary oversight expansion:Health Canada and PMRA alignment with US medically important antibiotic restrictions is harmonizing cross-border product registrations and extending manufacturer addressable markets.
Market Restraints
- Active pharmaceutical ingredient concentration:Tetracycline and ionophore API manufacturing clusters in China create single-source vulnerability for North American formulators despite finished dose domestic production.
- Environmental discharge compliance:EPA effluent limitations guidelines for pharmaceutical manufacturing constrain greenfield plant siting in the US Midwest, elevating capital recovery timelines for fermentation-based production.
- Direct-fed microbial substitution:Yeast cell wall and Bacillus-based alternatives are capturing coccidiosis prevention share in US broiler operations, compressing ionophore volume growth in contract grower networks.
Strategic Opportunities
- Mexico's regulatory harmonization lag:COFEPRIS enforcement gaps around growth-promotion claims sustain parallel product formulations for export-oriented US manufacturers with dual-registered facilities.
- Liquid delivery system automation:Swine nursery operations in Iowa and Minnesota are retrofitting medicated water systems that bypass feed mill VFD bottlenecks, creating aftermarket equipment-service bundling potential.
- USDA residue monitoring data monetization:Integration of Food Safety and Inspection Service testing databases with producer quality assurance programs offers subscription analytics services to integrated complexes.
Industry Challenges
- Veterinary prescription fulfillment latency:State-level veterinary practice act variations create 48-72 hour VFD authorization delays that disrupt just-in-time feed mill scheduling across multi-state operations.
- Compounded medicated feed enforcement ambiguity:FDA Center for Veterinary Medicine inspection priority shifts between 503A pharmacies and 503B outsourcing facilities generate compliance cost uncertainty for regional feed manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Antibiotics Market |
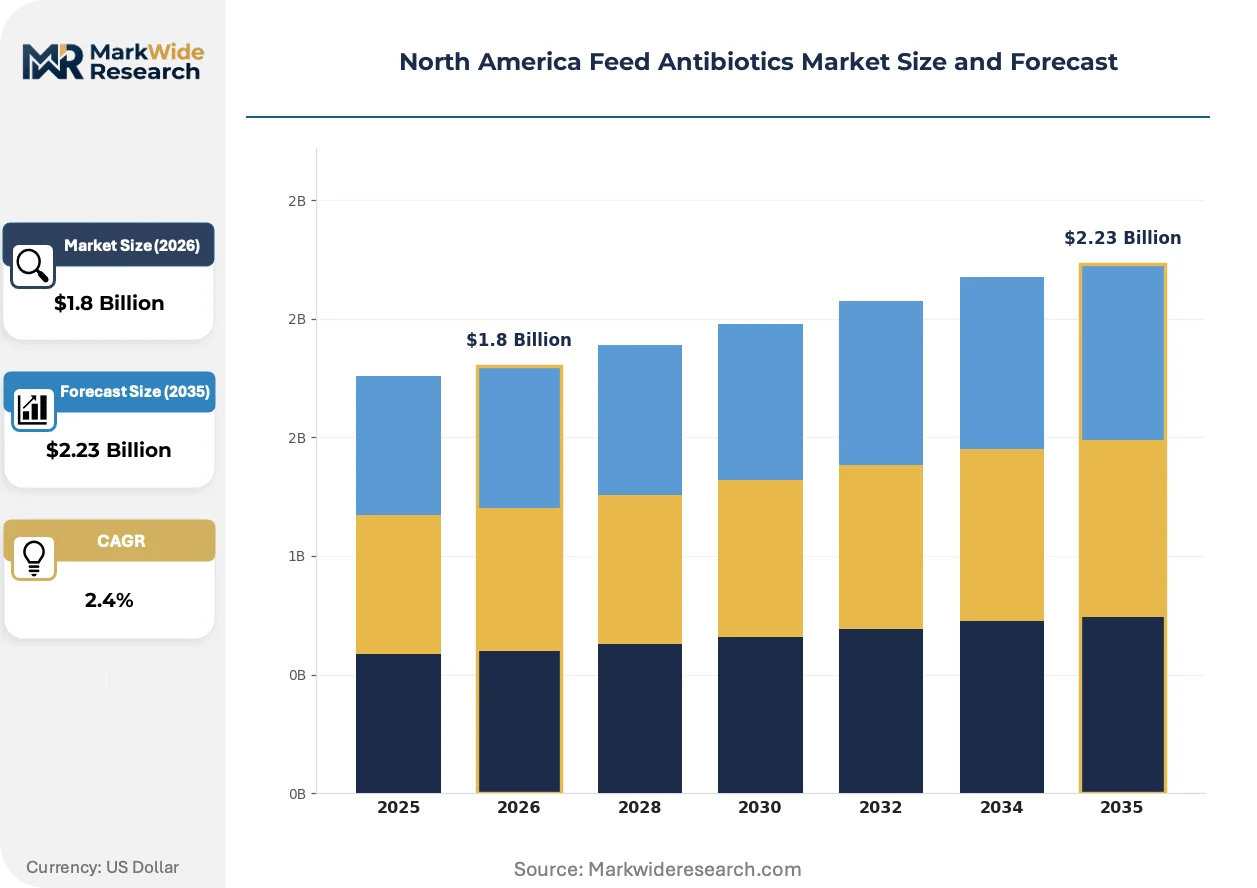
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tetracyclines, Penicillins, Macrolides, Ionophores End User: Poultry, Swine, Ruminants, Aquaculture Formulation: Powder, Liquid, Granules, Premix Distribution Channel: Online, Veterinary Clinics, Distributors, Feed Manufacturers |
| Companies Covered | Bayer HealthCare AG, Elanco Animal Health Inc., Phibro Animal Health Corporation, Huvepharma, Zomedica Inc., Zoetis Inc., Merck & Co Inc, Cargill Incorporated, Boehringer Ingelheim GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Antibiotics Market Evolving Landscape
Precision livestock monitoring systems are converging with antimicrobial stewardship protocols, reshaping how North American producers time metaphylactic interventions and document veterinary oversight for regulatory audit trails.
Biosensor-enabled feed intake monitoring is electrifying disease detection timing in US cattle feedlots. Accelerometer and rumen bolus systems flag subclinical morbidity 24-48 hours before visual symptoms, allowing targeted macrolide administration rather than pen-wide metaphylaxis. This compression of therapeutic windows is reducing total antimicrobial mass per head while preserving performance outcomes.
Health Canada and PMRA are accelerating VFD-equivalent veterinary oversight requirements for medically important antibiotics in feed, mirroring FDA 209/213 implementation timelines. Canadian provincial veterinary medical associations are developing prescription infrastructure that lags US state boards by approximately 18-24 months, creating transitional arbitrage for cross-border integrated operations with unified quality systems.
Buyer concentration within US poultry integrators is collapsing supplier rosters to three-to-four approved vendors per therapeutic category. Contract grower networks in Georgia, Alabama, and Mississippi now procure exclusively through integrator-negotiated formularies, displacing independent feed mill relationships and compressing price negotiation leverage for remaining approved suppliers.
North America Feed Antibiotics Market Segmentation
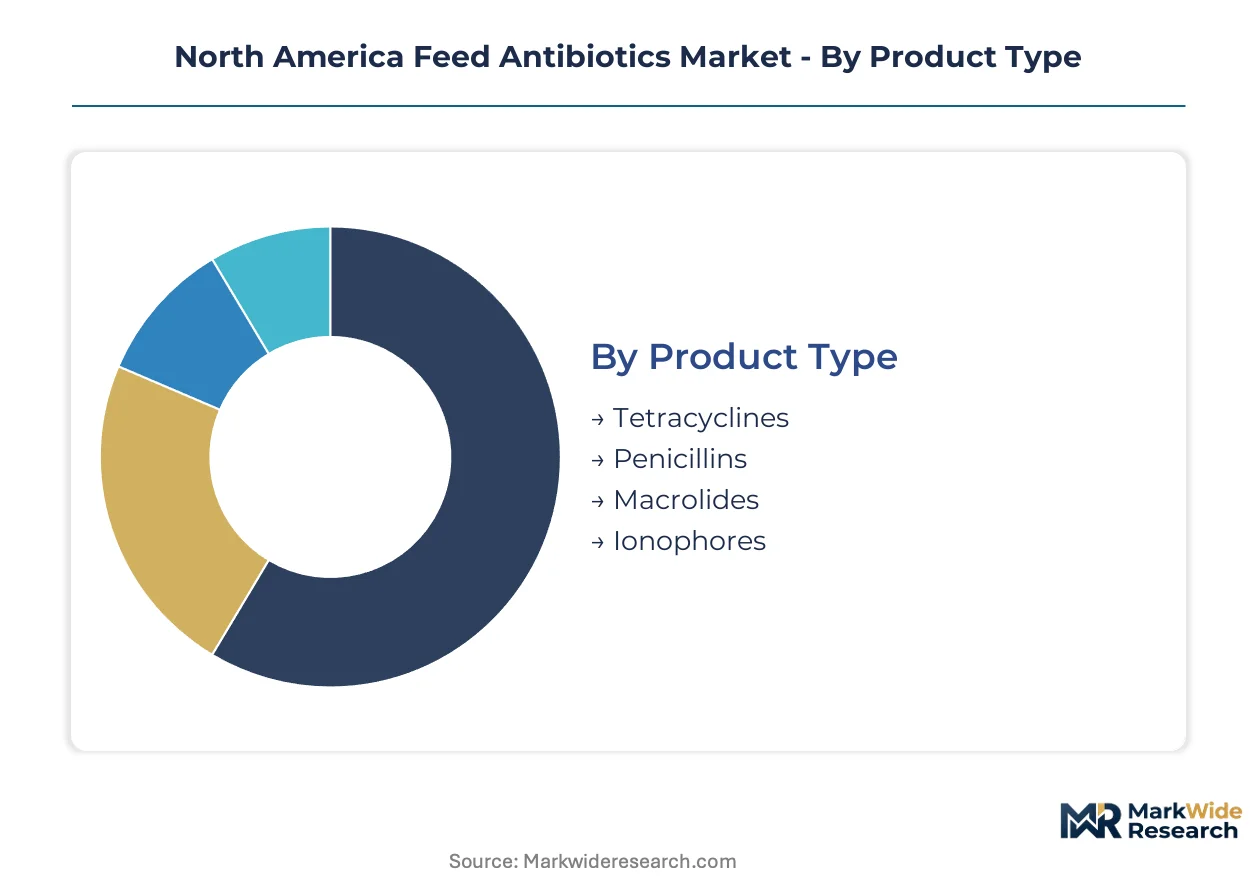
Procurement authority concentrates differently across each dimension of the North America feed antibiotics market. Veterinary feed directive compliance costs and integrator consolidation patterns reshape which segments capture volume and margin.
Product Type:
Cost tier separates commodity broad-spectrum agents from specialized ionophore manufacturing.
- Tetracyclines:Broad-spectrum agents effective against gram-positive and gram-negative bacteria in swine respiratory and enteric protocols. Demand concentrates in US Midwest swine nurseries where metaphylactic protocols persist amid FDA 209/213 enforcement.
- Ionophores:Fermentation-derived compounds selectively targeting coccidiosis prevention in poultry and rumen modulation in cattle. Volume anchors in Texas and Kansas feedlots where macrolide adjacency sustains combination therapy demand.
- Penicillins:Beta-lactam compounds with narrower spectrum targeting specific gram-positive pathogens in dairy calf protocols.
- Macrolides:Respiratory-focused agents gaining substitution share where growth-promotion claims have been eliminated.
Volume sits with tetracyclines; growth tilts toward macrolides.
End User:
Application intensity varies by species-specific disease pressure and integrator consolidation stage.
- Poultry:Broiler operations across Georgia, Alabama, and Mississippi drive coccidiosis prevention demand through integrator-controlled formularies.
- Swine:Respiratory and enteric protocols dominate in Iowa and Minnesota nursery systems where liquid delivery automation is retrofitting traditional feed-based administration.
- Ruminants:Cattle feedlots in the US Plains sustain ionophore volume for rumen efficiency and liver abscess control.
- Aquaculture:Therapeutic use in catfish and salmonid operations operates under distinct EPA discharge constraints.
Volume concentrates in poultry; expansion tilts toward swine automation systems.
Formulation:
Supply chain position determines whether products integrate at feed mill or farm level.
- Premix:Standardized blends incorporated during feed manufacturing dominate commercial channels due to mill integration efficiency.
- Liquid:Water-soluble concentrates bypass veterinary feed directive bottlenecks in automated swine nursery systems across Iowa and Minnesota.
- Powder:Dry concentrates requiring on-farm mixing serve smaller independent operations outside integrator networks.
- Granules:Flowable formulations for specific species applications where dust control matters.
Volume rests with premix; adoption momentum favors liquid systems.
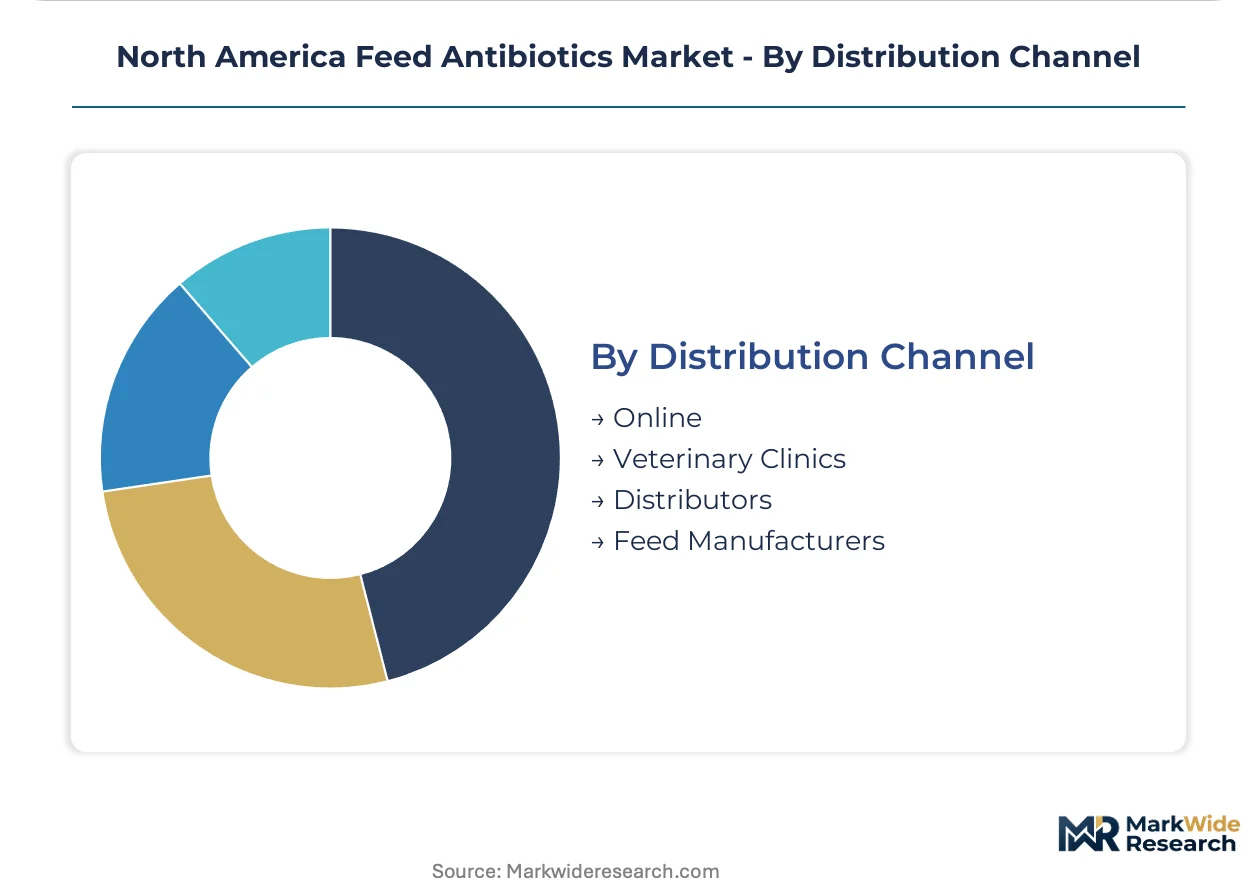
Distribution Channel:
Customer type and scale dictate access pathways amid regulatory compliance layering.
- Feed Manufacturers:Vertically integrated mills in the US Southeast and Midwest control procurement for contract grower networks.
- Distributors:Regional veterinary supply networks maintain inventory positions for independent producers outside integrator systems.
- Veterinary Clinics:Captive staff within large poultry and swine complexes handle prescription fulfillment for VFD compliance.
- Online:Emerging platform sales face state-level veterinary practice act variations creating fulfillment latency.
Volume anchors with feed manufacturers; channel development points toward veterinary clinic consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Midwest feed mill zones and Canadian Prairie livestock corridors concentrate procurement authority through integrator tax incentives and provincial veterinary infrastructure grants.
United States
Texas and Kansas cattle feedlots drive macrolide demand for metaphylactic respiratory protocols amid growth-promotion claim eliminations. FDA Guidance 209/213 enforcement mandates veterinary feed directive compliance across all medically important antibiotics. Iowa and Minnesota swine nursery automation clusters retrofit liquid delivery systems that bypass traditional feed mill bottlenecks.
Canada
Alberta and Saskatchewan beef operations sustain ionophore volume for rumen efficiency in cold-climate feedlot finishing. Health Canada and PMRA alignment with US antibiotic restrictions harmonizes cross-border product registrations. Ontario poultry integrators consolidate formulary access through provincial veterinary medical association prescription infrastructure.
Mexico
Nuevo León and Jalisco poultry complexes maintain dual-registered facilities serving export-oriented US supply chains. COFEPRIS enforcement gaps around growth-promotion claims sustain parallel product formulations for domestic versus export production. Northern border states concentrate API formulation capacity for regional distribution.
North America Feed Antibiotics Market Competitive Landscape
Top-tier vendors anchor integrated pharmaceutical portfolios, while mid-tier specialists concentrate on single-class manufacturing scale. The market exhibits tiered concentration around fermentation-derived ionophores and synthetic broad-spectrum agents. Strategic archetypes include captive veterinary distribution networks, API-to-finished-dose vertical control, and alternative growth-promotion technology developers. Competitive moves center on regulatory compliance infrastructure capture and automated delivery system partnerships.
Among US-based animal health multinationals, Elanco Animal Health Inc., Zoetis Inc., and Phibro Animal Health Corporation exemplify distinct competitive positioning archetypes. Elanco occupies a position emphasizing research intensity in alternative technologies. Zoetis anchors veterinary distribution infrastructure penetration across major poultry complexes. Phibro represents specialized ionophore manufacturing scale advantages in ruminant applications. European-headquartered Bayer HealthCare AG and Boehringer Ingelheim GmbH sit within the pharmaceutical conglomerate tier leveraging human health manufacturing synergies.
| Leading Market Players |
|---|
| Bayer HealthCare AG |
| Elanco Animal Health Inc. |
| Phibro Animal Health Corporation |
| Huvepharma |
| Zomedica Inc. |
| Zoetis Inc. |
| Merck & Co Inc |
| Cargill Incorporated |
| Boehringer Ingelheim GmbH |
| Others |
Value Network & Pricing Analysis
Fermentation-based ionophore manufacturing scale transitions are simultaneously elevating capital recovery timelines for domestic producers and compressing margin structures for API-dependent formulators across North American feed mill networks. Veterinary feed directive compliance layering concentrates procurement authority within vertically integrated complexes, amplifying price negotiation leverage for buyers with captive veterinary infrastructure.
Pricing Analysis
Lead-time-driven pricing stratification rewards integrators with contracted veterinary staff who secure 48-72 hour VFD turnaround, while independent operators absorbing spot-market inventory penalties face cost disadvantages. Three-tier pricing structure across formulary-preferred, conditional-use, and non-preferred agent categories reflects FDA 209/213 compliance certification status and ionophore manufacturing origin. Cost compression in non-preferred tetracycline tiers intensifies because Chinese API concentration exposes formulators to single-source volatility and tariff exposure. Contract grower networks within Georgia and Alabama poultry integrators demonstrate lowest price sensitivity due to pass-through procurement arrangements, whereas independent Midwest swine nurseries exhibit highest sensitivity to liquid delivery system retrofit costs.
Supply Chain Analysis
Direct-to-integrator channels handle volume concentration across US Southeast poultry complexes, while distributor networks serve fragmented independent producers outside captive formulary systems. Active pharmaceutical ingredient manufacturing clusters in China, India, and select European jurisdictions supply tetracycline and ionophore precursors that North American formulators convert to finished doses under EPA effluent constraints. Corn fermentation feedstocks, specialized bioreactor equipment, and cold-chain logistics capacity constitute critical input dependencies. Single-source vulnerability for Chinese-origin APIs creates structural supply chain risk that domestic manufacturers mitigate through dual-registration strategies and inventory buffering. Distribution runs through vertically integrated feed manufacturers with mill-level premix incorporation, veterinary clinic prescription fulfillment, and emerging automated liquid delivery partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
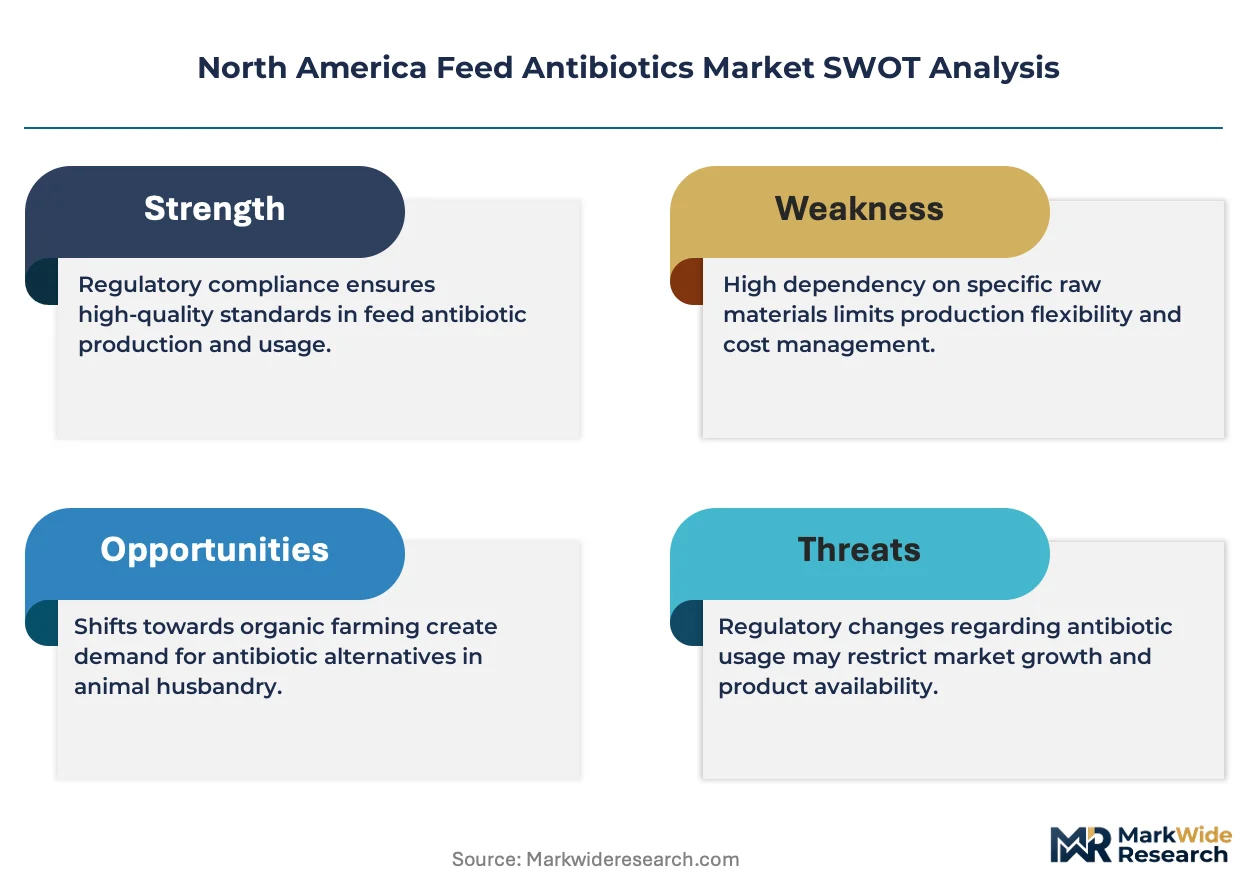
FDA Guidance for Industry 209 and 213 enforcement has erected a cost-of-compliance barrier that consolidates market access around players with veterinary infrastructure investments, eliminating over-the-counter competitors and protecting compliant incumbents from price-driven disruption.
For Market Incumbents: Lock in formulary exclusivity across Georgia, Alabama, and Mississippi broiler integrators by embedding captive veterinary staff within contract grower networks before provincial Canadian infrastructure matures. Deepen backward integration into ionophore fermentation capacity to reduce Chinese API exposure and capture margin from supply-constrained competitors. Direct-fed microbial substitution technologies represent the priority threat requiring defensive R&D allocation. For New Entrants and Emerging Players: Enter via liquid delivery system automation partnerships with Iowa and Minnesota swine nursery operators seeking VFD bypass solutions, where regulatory arbitrage creates penetrable white space absent from integrator-controlled poultry channels. Target independent cattle feedlots in Texas and Kansas with macrolide-ionophore combination protocols as growth-promotion claim eliminations sustain metaphylactic demand. Go-to-market positioning should emphasize equipment-service bundling rather than commodity premix competition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pharmaceutical conglomerates seeking veterinary distribution infrastructure and FDA-compliant product registrations for portfolio diversification. Long-term viability favors manufacturers with captive API supply or alternative technology pipelines capable of substituting for restricted growth-promotion agents. The signal to watch is Health Canada-PMRA enforcement acceleration, which will eliminate transitional arbitrage opportunities for dual-registered facilities and compress valuation premiums for Mexico-exposed assets.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Infrastructure Capture | Embedding prescription fulfillment within integrator networks locks out competitors under FDA 209/213. |
| Alternative Technology R&D | Direct-fed microbial and precision livestock monitoring investments defend against ionophore volume compression. |
| Liquid Delivery System Partnerships | Automated swine nursery retrofits in Iowa and Minnesota bypass feed mill VFD bottlenecks. |
| Cross-Border Registration Harmonization | Health Canada-PMRA alignment extends addressable markets for US-compliant manufacturers. |
| API Supply Diversification | Reducing Chinese fermentation concentrate exposure mitigates single-source vulnerability for North American formulators. |
Research Methodology
Document review covered FDA Center for Veterinary Medicine guidance filings, EPA effluent limitation guidelines, Health Canada veterinary drug submissions, and USDA Food Safety and Inspection Service residue monitoring databases, complemented by interviews with feed mill procurement directors, poultry integrator veterinary staff, swine nursery operations managers, and animal health distributor inventory planners. Secondary validation drew from SEC 10-K disclosures of listed animal health multinationals, customs import records for API shipments, and provincial veterinary medical association prescription infrastructure reports. Bottom-up volume estimates from species-specific consumption patterns were triangulated against top-down manufacturer revenue allocations.
Historical consumption trends were cross-referenced against panel input from industry participants to construct segment-level projections across product type, end user species, formulation, and distribution channel dimensions. CAGRs were derived from regression analysis of regulatory enforcement timelines and technology substitution curves rather than extrapolation of historical growth rates. Ionophore manufacturing capacity utilization, VFD authorization latency by state veterinary board, and integrator formulary consolidation velocity served as industry-specific forecast inputs throughout the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated FDA compounded medicated feed enforcement or disruptive direct-fed microbial efficacy breakthroughs. Periodic stress-testing of base assumptions is recommended, particularly regarding Chinese API supply continuity and state-level veterinary practice act harmonization trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
North America Feed Pigments Market