
 Lauryl Myristyl Alcohol Market | 2026-2036
Lauryl Myristyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Lauryl Myristyl Alcohol Market Outlook
Personal care and cosmetics is shifting toward bio-based surfactant feedstocks, pulling demand away from conventional petrochemical routes. Croda International Plc anchors its position through oleochemical specialization and supply chain proximity to palm kernel oil sources. BASF competes by extending its surfactant intermediate portfolio into certified sustainable grades. VVF LLC leverages integrated fatty alcohol production to control raw material flows from Indian oleochemical complexes.
Lauryl myristyl alcohol denotes a blend of C12 (lauryl) and C14 (myristyl) fatty alcohols derived from natural oils or petrochemical ethylene, typically exhibiting a hydroxyl value between 280-295 mg KOH/g and serving as foundational intermediates for nonionic and anionic surfactants. The cosmetics and personal care product type commands premium positioning due to certification requirements for dermal safety and renewable content. Among applications, surfactants occupy the dominant volume share while emulsifiers capture disproportionate margin pools from specialty skin-care and hair-care formulations. Industrial cleaners represent a mature, price-sensitive segment where bulk packaging and drum logistics determine supplier selection.
REACH registration through ECHA governs import and formulation standards across European cosmetics and detergent value chains, while EPA Safer Choice labeling in the United States steers procurement toward biodegradable surfactant precursors. India's BIS certification for oleochemical derivatives adds compliance layers for exporters targeting personal care contract manufacturers in Mumbai and Gujarat chemical clusters. Stakeholders must track evolving palm oil sustainability certifications and regional oleochemical capacity additions to secure feedstock positions before supply bottlenecks emerge.
Market Dynamics
Plant-derived C12-C14 alcohol blends are displacing petrochemical routes as formulators face tightening purity mandates from ECHA REACH and EPA Safer Choice programs, while Southeast Asian oleochemical capacity expansion redraws feedstock sourcing maps.
Growth Catalysts
- REACH Registration Mandates:ECHA compliance requirements across European cosmetics and detergent value chains force formulators toward certified-purity natural alcohols, eliminating lower-grade petrochemical alternatives from supply portfolios.
- Surfactant Intermediate Demand:Personal care manufacturers in Germany and France expand purchases of bio-based feedstocks for sulfate-free shampoo and skin-care emulsions, pulling volume through dedicated oleochemical supply contracts.
- Palm Kernel Oil Proximity:Malaysian and Indonesian oleochemical complexes achieve cost-advantaged production through integrated refining-to-alcohol processing, capturing share in Asian and Middle Eastern export markets.
Market Restraints
- Feedstock Price Volatility:Crude palm oil price swings on Bursa Malaysia Derivatives Exchange transmit directly to C12-C14 alcohol cost structures, compressing margins for non-integrated producers.
- Technical Purity Barriers:Cosmetic-grade specifications demanding hydroxyl values between 280-295 mg KOH/g with sub-0.5% carbon chain deviation require distillation investments that smaller Malaysian and Thai producers cannot fund.
- Synthetic Alcohol Substitution:Ethylene-based fatty alcohols from Gulf Coast petrochemical complexes offer price stability during palm oil spikes, retaining share in industrial cleaner applications.
Strategic Opportunities
- Indian Contract Manufacturing:Mumbai and Gujarat chemical clusters lack sufficient local C12-C14 alcohol supply, creating import substitution potential for Indonesian producers with BIS-certified grades.
- EPA Safer Choice Tailwinds:Biodegradable surfactant precursor labeling in United States institutional cleaning contracts steers procurement toward renewable alcohols, opening premium positioning for certified suppliers.
- Specialty Emulsifier Convergence:Silicone-free hair-care formulations combine C12-C14 alcohols with cationic conditioning polymers, creating specification-locked demand in Korean and Japanese beauty markets.
Industry Challenges
- Certification Timeline Compression:RSPO Mass Balance and ISCC PLUS documentation requirements extend qualification cycles for new suppliers by 8-12 months, freezing spot market participation.
- Fractionation Capacity Bottlenecks:Limited molecular sieve and crystallization infrastructure at Indian and Southeast Asian oleochemical sites constrains production of narrow-cut C12-C14 blends demanded by cosmetic formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lauryl Myristyl Alcohol Market |
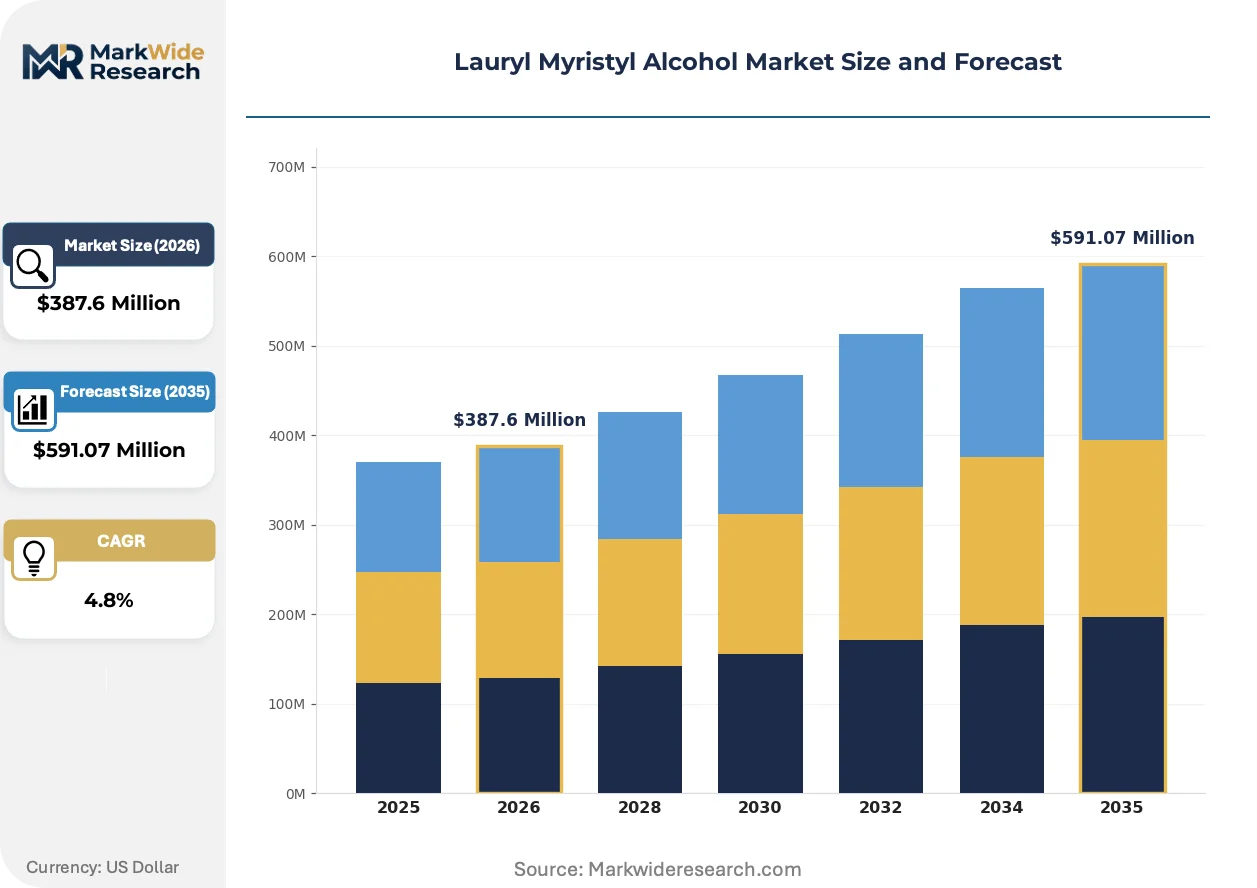
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Personal Care, Industrial Cleaners, Detergents Application: Surfactants, Emulsifiers, Solvents, Thickening Agents End User: Manufacturers, Distributors, Retailers, Research Institutions Packaging Type: Drums, Bottles, Jars, Bulk Packaging |
| Companies Covered | VVF LLC, Lubrizol Corporation, Croda International Plc, Dow Chemical Company, Eco Green Oleochemicals, MSD OLEO FZC, Wilmar International Ltd, Procter & Gamble, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lauryl Myristyl Alcohol Market Strategic Shifts
Enzymatic esterification and continuous hydrolysis technologies are reconfiguring process economics, while regulatory labeling schemes and procurement centralization reshape competitive positioning across value chains.
Enzymatic transesterification using immobilized lipase biocatalysts is expanding into lauryl myristyl alcohol production, enabling lower-temperature processing that preserves color specifications for cosmetic applications. German and Dutch specialty chemical producers deploy these systems to serve premium skin-care formulators requiring Gardner color below 2.0. The technology is expanding into mid-tier surfactant intermediates previously dominated by high-pressure hydrogenation routes, compressing capital barriers for new market entrants.
EU Green Deal chemical sustainability requirements and CSRD supply chain disclosure mandates force downstream formulators to document renewable carbon content across C12-C14 alcohol purchases. Cosmetic brands in France and Italy now require batch-level mass balance certificates from oleochemical suppliers, shifting procurement criteria beyond price and purity to traceability infrastructure. Small and mid-sized Malaysian producers lacking blockchain-tracked supply chains face exclusion from European personal care contract manufacturing networks.
Consolidated procurement by multinational personal care brands compresses supplier qualification cycles and raises minimum volume thresholds for direct supply relationships. Indian and Southeast Asian formulators increasingly source through regional distributors holding inventory and certification documentation, displacing direct mill relationships that dominated trade through 2020. This channel restructuring concentrates margin capture with integrated oleochemical-distributor hybrids in Singapore and Mumbai, fragmenting spot market liquidity.
Lauryl Myristyl Alcohol Market Segmentation
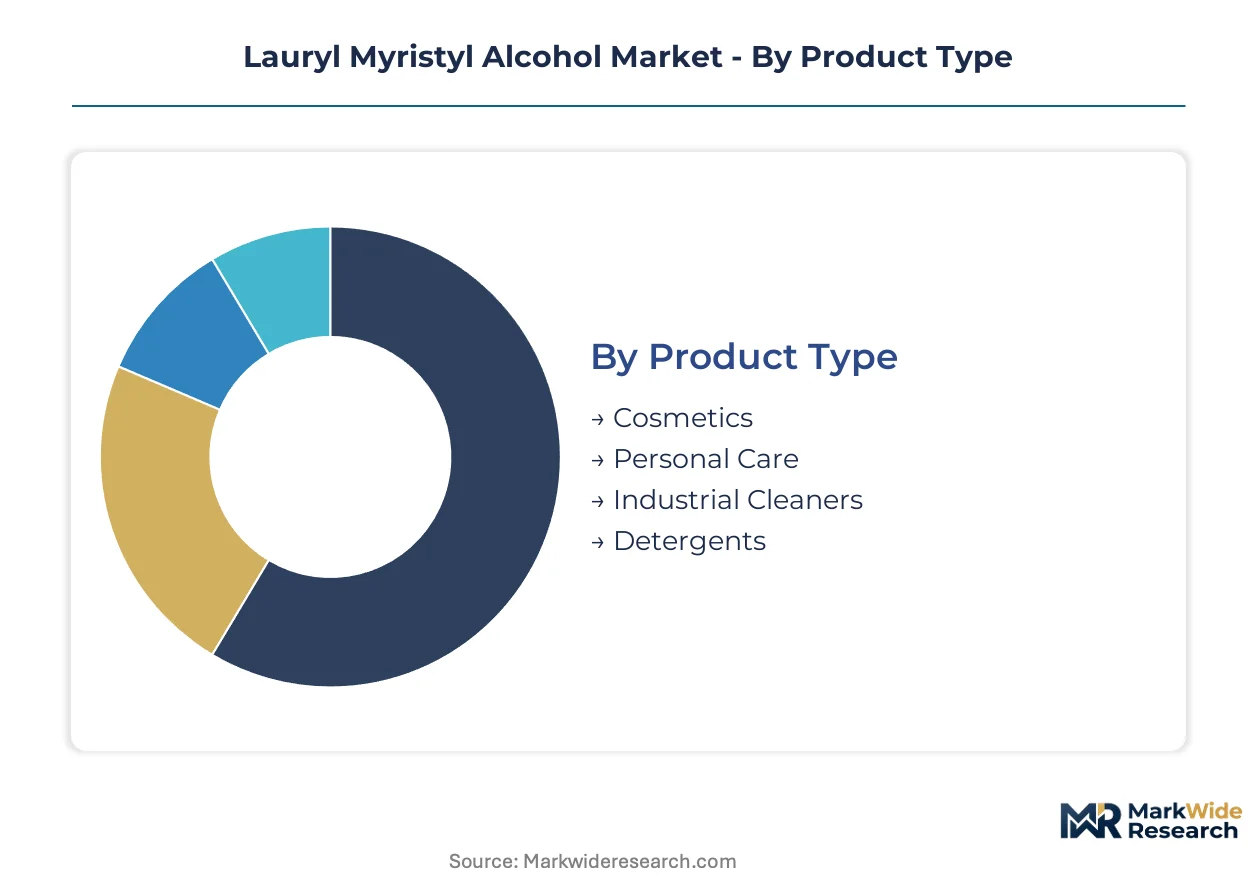
C12-C14 alcohol specifications diverge sharply across end-use tiers, with cosmetic-grade purity commanding five-fold premiums over industrial bulk grades. Understanding these segment boundaries protects margin positioning as procurement centralization reshapes supplier relationships.
Product Type:
Cosmetics and personal care segments absorb disproportionate margin pools despite smaller volumes, while industrial applications anchor baseline throughput for integrated producers.
- Cosmetics:Dermal-grade C12-C14 alcohols require hydroxyl values of 280-295 mg KOH/g with Gardner color below 2.0, specifications that exclude most Southeast Asian producers lacking molecular sieve fractionation. French and Italian formulators now mandate RSPO Mass Balance certification at batch level, compressing qualified supplier pools.
- Personal Care:Sulfate-free shampoo and silicone-free hair-care formulations in Korea and Japan specification-lock C12-C14 alcohols with cationic conditioning polymers, creating captive demand for narrow-cut blends. Malaysian integrated producers with dedicated personal care lines capture premium positioning through supply chain proximity.
- Industrial Cleaners:Bulk drum logistics and price-sensitive procurement dominate this mature segment.
- Detergents:Institutional cleaning contracts in the United States steer toward EPA Safer Choice-labeled biodegradable precursors.
Today's leader: Cosmetics. Tomorrow's challenger: Personal Care.
Application:
Surfactant intermediates generate volume throughput while emulsifier specializations capture technology-locked premiums in skin-care formulations.
- Surfactants:Anionic and nonionic surfactant production consumes the dominant volume share of C12-C14 alcohol output, with German and French manufacturers expanding bio-based feedstock purchases through dedicated oleochemical contracts. REACH registration mandates eliminate lower-grade petrochemical alternatives from European supply portfolios.
- Emulsifiers:Specialty skin-care and hair-care formulations demand emulsifier-grade alcohols with sub-0.5% carbon chain deviation, specifications requiring distillation investments that smaller Thai producers cannot fund. Korean beauty markets specification-lock these grades through silicone-free formulation trends.
- Solvents:Industrial solvent applications prioritize cost stability over renewable content.
- Thickening Agents:Rheology modifiers for personal care absorb narrow-cut fractions with tight viscosity control requirements.
Surfactants anchor current volume. Emulsifiers are climbing the fastest as premium skin-care formulations proliferate.
End User:
Procurement centralization by multinational brands concentrates direct relationships with integrated producers, fragmenting spot market access for smaller manufacturers.
- Manufacturers:Contract manufacturers in Mumbai and Gujarat chemical clusters lack sufficient local C12-C14 alcohol supply, creating import substitution potential for Indonesian producers with BIS-certified grades. Direct mill relationships that dominated trade through 2020 now displace toward regional distributors.
- Distributors:Singapore and Mumbai-based oleochemical-distributor hybrids consolidate margin capture through inventory holding and certification documentation services.
- Retailers:Private-label personal care brands source through consolidated procurement desks with elevated minimum volume thresholds.
- Research Institutions:Specialty sample volumes for enzymatic esterification trials flow through academic-industrial partnerships.
Manufacturers retain volume leadership. Distributors are gaining share fastest through channel restructuring.
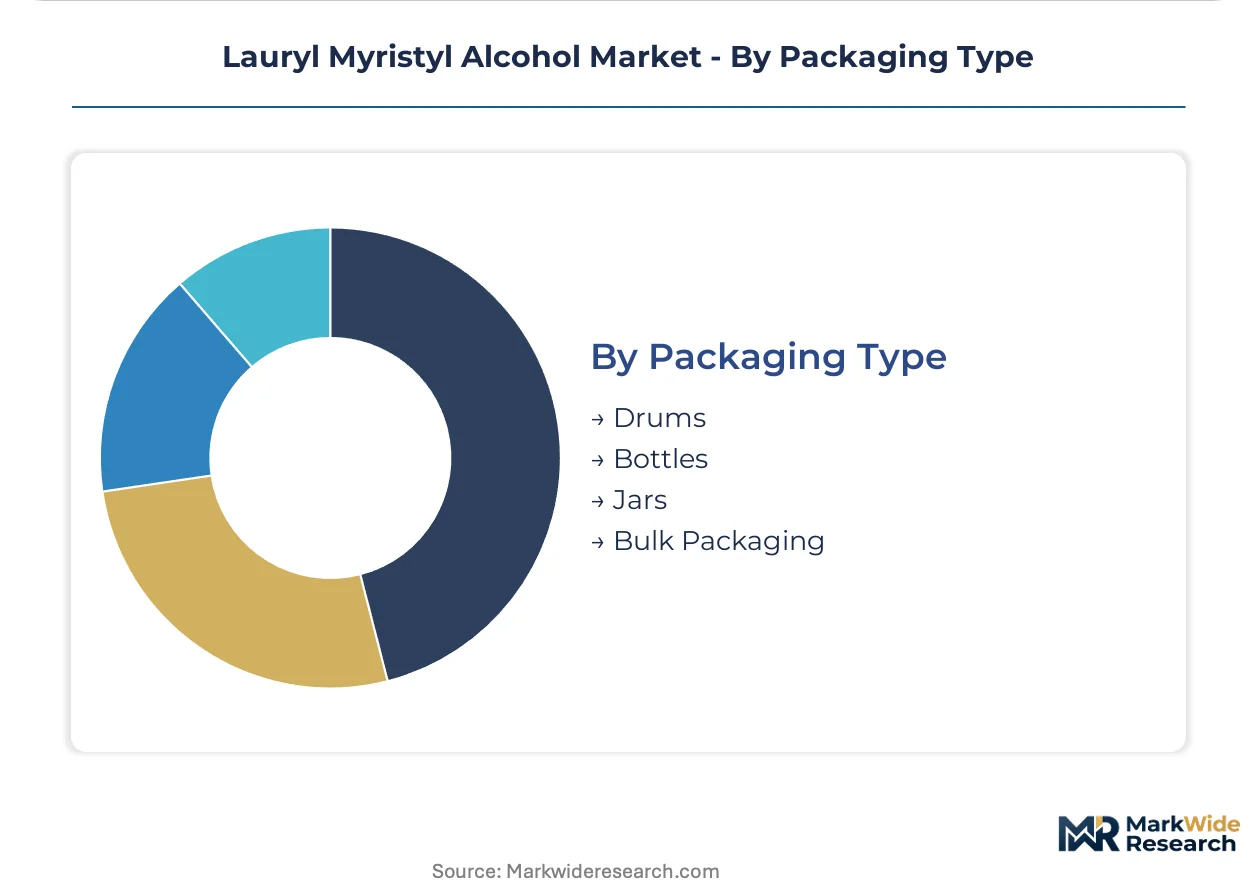
Packaging Type:
Logistics configuration separates industrial bulk from cosmetic precision, with drum specifications varying by end-use purity tier.
- Drums:Standard 200-liter steel drums dominate industrial cleaner shipments where bulk packaging logistics determine supplier selection.
- Bottles:Smaller-format packaging serves research institution and specialty sample requirements.
- Jars:Cosmetic-grade materials in jar format target artisanal and small-batch formulators.
- Bulk Packaging:Tanker and ISO-tank configurations serve integrated surfactant manufacturers with captive alcohol consumption.
Drums command present volume. Bulk packaging represents the steepest expansion trajectory as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian oleochemical complexes anchor regional production capacity, drawing feedstock integration advantages from proximity to palm kernel oil refining. Southeast Asian capacity expansion is redrawing sourcing maps for European and Indian formulators seeking certified-purity C12-C14 alcohols.
Malaysia
Integrated refining-to-alcohol processing at Port Klang and Pasir Gudang clusters captures cost advantages for surfactant intermediate exports. The country's national standards body enforces certification alignment with EU REACH documentation requirements. Johor-based oleochemical sites are expanding molecular sieve fractionation capacity to meet cosmetic-grade hydroxyl specifications.
Indonesia
Medan and Surabaya chemical corridors are attracting investment for C12-C14 alcohol output targeting Indian import substitution. BIS-equivalent export documentation protocols are compressing qualification timelines for Mumbai and Gujarat contract manufacturers. North Sumatra palm kernel supply chains are integrating backward into dedicated fatty alcohol production lines.
Germany
Ruhr industrial region formulators are expanding bio-based surfactant feedstock purchases through dedicated oleochemical contracts. ECHA REACH registration mandates are eliminating lower-grade petrochemical alternatives from detergent value chains. Leverkusen and Ludwigshafen chemical parks are deploying enzymatic esterification systems for premium skin-care applications.
India
Mumbai and Gujarat chemical clusters lack sufficient local C12-C14 alcohol supply, creating import dependency for personal care contract manufacturers. BIS certification requirements for oleochemical derivatives add compliance layers for Indonesian and Malaysian exporters. Dahej and Mundra port zones are evaluating greenfield oleochemical investments to capture domestic demand.
United States
Gulf Coast petrochemical complexes maintain synthetic fatty alcohol output for industrial cleaner price stability during palm oil volatility. EPA Safer Choice labeling steers institutional procurement toward biodegradable surfactant precursors. Texas and Louisiana surfactant manufacturers are dual-sourcing between renewable and ethylene-based routes to hedge feedstock exposure.
Lauryl Myristyl Alcohol Market Competitive Environment
Capacity expansion dominates the current landscape as Southeast Asian producers build molecular sieve fractionation infrastructure to capture cosmetic-grade premiums. The vendor base concentrates around integrated oleochemical groups with captive palm kernel oil supply and specialty chemical divisions with enzymatic processing capabilities. Three archetypes define competitive positioning: integrated Southeast Asian producers with feedstock proximity, European specialty chemical groups with certification infrastructure, and diversified multinational chemical conglomerates with surfactant downstream integration. Geographic expansion into Indian contract manufacturing zones and technology licensing for enzymatic esterification represent the dominant competitive moves.
Within the integrated producer tier, Wilmar International Ltd exemplifies Southeast Asian feedstock-advantaged positioning through its Singapore-based oleochemical network. Croda International Plc represents the European specialty archetype with certification-heavy supply chains serving French and Italian cosmetic formulators. BASF occupies a position bridging scale-driven commodity supply and premium-grade surfactant intermediate specialization. These three anchors illustrate how competitive positioning diverges between feedstock-integrated volume players and specification-locked premium suppliers.
| Leading Market Players |
|---|
| VVF LLC |
| Lubrizol Corporation |
| Croda International Plc |
| Dow Chemical Company |
| Eco Green Oleochemicals |
| MSD OLEO FZC |
| Wilmar International Ltd |
| Procter & Gamble |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Palm kernel oil feedstock costs transmit directly from Bursa Malaysia Derivatives Exchange through to cosmetic-grade C12-C14 alcohol premiums, with integrated Malaysian producers capturing margin insulation that non-integrated Indian and Thai competitors cannot replicate. This upstream cost architecture splits downstream pricing into certification-locked premium tiers for European personal care formulators versus bulk industrial grades for institutional cleaning contracts.
Pricing Analysis
Distributor margin layers concentrate with Singapore and Mumbai-based oleochemical-distributor hybrids holding inventory and certification documentation. Three-tier pricing structure across premium, standard, and economy levels separates RSPO Mass Balance-certified cosmetic grades from industrial bulk drums and spot-market synthetics. Cost compression in mid-tier surfactant intermediates is intensifying because Indonesian capacity additions are pressuring Malaysian incumbent positions. Industrial cleaner buyers exhibit highest price sensitivity, while French and Italian cosmetic formulators absorb five-fold premiums for batch-level traceability.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian palm kernel oil refining clusters feeding C12-C14 alcohol fractionation. Geographic supply concentration centers on Malaysia, Indonesia, and India, with German and U.S. Gulf Coast petrochemical complexes providing synthetic alternatives. Raw material dependencies rest on crude palm oil, palm kernel oil, and ethylene feedstocks. Supply chain risk hinges on Bursa Malaysia price volatility transmitting through oleochemical value chains. Distribution runs through regional distributor networks consolidating procurement for multinational personal care brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lauryl myristyl alcohol procurement functions as a geographic-arbitrage play between Southeast Asian feedstock-integrated production and Indian import-dependent chemical clusters, with ECHA REACH compliance costs in Europe widening the cost differential against BIS-certified Indonesian exports.
For Market Incumbents: Deploy molecular sieve fractionation capacity additions in Johor and Port Klang to defend cosmetic-grade positioning against emerging Indonesian competitors. Backward integration into dedicated palm kernel supply lines insulates margin structures from Bursa Malaysia volatility. Certification infrastructure investments in RSPO Mass Balance and ISCC PLUS documentation compress qualification cycles for European formulators. For New Entrants and Emerging Players: Enzymatic esterification technology using immobilized lipase biocatalysts offers lower-temperature processing entry into premium skin-care grades previously dominated by high-pressure hydrogenation incumbents. White-space targets include BIS-certified supply to Mumbai and Gujarat contract manufacturers lacking local C12-C14 alcohol production. Go-to-market positioning through regional distributor partnerships bypasses direct mill relationship barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where fractionation capacity bottlenecks constrain narrow-cut cosmetic-grade supply against specification-locked demand from Korean silicone-free hair-care formulators. Long-term viability favors integrated oleochemical groups with captive palm kernel oil supply and blockchain-tracked traceability infrastructure. Acquisition target archetype: mid-tier Malaysian producers with underutilized distillation assets and latent certification capabilities. The signal to watch is EPA Safer Choice procurement volume acceleration in U.S. institutional cleaning contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Johor-based molecular sieve installations capture cosmetic-grade premiums from European REACH-mandated formulators. |
| Backward Integration | North Sumatra palm kernel supply chains into dedicated fatty alcohol lines reduce Bursa Malaysia price exposure. |
| Green Manufacturing Transition | Enzymatic esterification systems preserve Gardner color specifications for French premium skin-care brands. |
| Long-term Supply Agreement | Dedicated oleochemical contracts with German and French manufacturers lock volume through REACH registration cycles. |
| Joint Venture | Indonesian-Mumbai partnerships bridge BIS certification gaps for Gujarat contract manufacturing clusters. |
Study Parameters
Multiple input streams — primary interviews with oleochemical plant managers, procurement leads at personal care OEMs, and distribution channel partners, combined with customs/trade data, ACC/Cefic reports, and SEC 10-K filings — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from ECHA REACH registration databases, BIS certification records, and RSPO supply chain documentation. Stakeholder perspectives spanned Malaysian integrated producers, Indonesian export-focused operators, and European specialty chemical formulators.
Data-stream reconciliation across the analysis window applied segmentation dimensions of grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived through trend extrapolation anchored in oleochemical capacity addition timelines and regulatory mandate implementation schedules. Industry-specific forecast inputs included palm kernel oil price trajectory assumptions and enzymatic processing technology adoption curves in German and Dutch specialty chemical parks.
The model holds under stable Bursa Malaysia feedstock pricing and sustained ECHA REACH enforcement; deviation in crude palm oil volatility spikes or Indonesian capacity acceleration would shift volume and value distributions. Forecasts reflect documented assumptions about certification timeline compression and procurement centralization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Trimethylamine Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Calcium Carbide Market
Chemicals
Guaiazulene Market
Chemicals
Periodic Acid Market
Chemicals
Power Plant Chemicals Market
Chemicals
Aluminum Chemicals Market
Chemicals
Aromatic Polyamine Market
Chemicals
Potassium Zirconium Fluoride Market
Chemicals
Flooring Chemicals Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Chemical Distribution Market
Chemicals
Fluorochemicals Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
South America Construction Chemicals Market
Chemicals
Hydrazine Market