
 Monoisopropanolamine (MIPA) Market | 2026-2036
Monoisopropanolamine (MIPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Monoisopropanolamine (MIPA) Market Foresight
Pharmaceutical-grade purity tiers are rotating toward the center of supplier strategy as downstream buyers tighten certificate-of-analysis requirements. BASF leverages integrated amine-to-alkanolamine production chains in Europe to sustain margin control. Huntsman Corporation anchors North American supply through dedicated alkoxylation capacity. Dow Chemical Company differentiates via technical service bundled with bulk solvent distribution.
Monoisopropanolamine is a secondary alkanolamine with the molecular formula C3H9NO, typically manufactured through the direct amination of propylene oxide with ammonia under controlled temperature and pressure conditions; it functions primarily as an intermediate for surfactant synthesis, pH buffering, and corrosion inhibition across industrial and consumer formulations. Industrial grade MIPA occupies the largest volume share due to broad solvent and neutralizing-agent demand in metalworking and gas-treatment applications, while pharmaceutical grade commands the highest margin pool as CDSCO and FDA filing requirements tighten impurity-profile specifications. Reagent grade consumption concentrates in analytical laboratories and specialty chemical synthesis where lot-to-lot consistency determines supplier selection.
EPA standards under the Toxic Substances Control Act shape permissible emission profiles during MIPA manufacture and downstream formulation in the United States, while REACH registration obligations in Europe mandate full toxicological dossiers for import and production volumes above one tonne annually. China's NMPA and GB standards govern pharmaceutical-grade impurity thresholds for domestically produced and imported material. Stakeholders must monitor regulatory divergence between jurisdictions to align certification investments with access priorities.
Market Dynamics
Pharmaceutical-grade purity specifications are compressing supplier margins while creating tiered entry barriers, as CDSCO and FDA filing requirements force capital-intensive impurity-profile documentation across the value chain.
Growth Catalysts
- REACH registration dossiers:Full toxicological documentation mandated by ECHA for volumes above one tonne annually is consolidating compliant suppliers and locking in premium pricing for certified producers.
- Gas-treatment solvent demand:Metalworking and natural gas processing facilities in the United States are expanding MIPA procurement for corrosion inhibition and pH buffering applications.
- Propylene oxide supply integration:Backward integration into amination feedstock is reducing cost volatility for integrated alkanolamine producers in Germany and China.
Market Restraints
- Ammonia price volatility:Feedstock cost swings in ammonia markets directly compress MIPA production margins, particularly for non-integrated manufacturers.
- Supplier concentration in China:Domestic amine producers control pharmaceutical-grade capacity expansion, creating geographic supply risk for European and North American formulators.
- Diethanolamine substitution:Alternative alkanolamines in surfactant formulations threaten volume share in industrial cleaning applications where purity thresholds permit flexibility.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO filing requirements for excipient-grade MIPA create certified-supplier gaps that compliant importers can exploit.
- Green chemistry mandates:EU Green Deal criteria for bio-based process routes are incentivizing ammonia-from-biomass pilot investments in the Netherlands and Belgium.
- Direct-to-formulator distribution:Bulk solvent distributors are bypassing traditional chemical merchant networks to capture technical service premiums in specialty surfactant segments.
Industry Challenges
- Analytical chemistry talent scarcity:Lot-to-lot consistency documentation for reagent-grade MIPA requires specialized chromatography expertise that competes with pharmaceutical QA budgets.
- Legacy equipment retrofit costs:EPA emission profile compliance under TSCA requires capital-intensive scrubber and containment upgrades at aging amination facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoisopropanolamine (MIPA) Market |
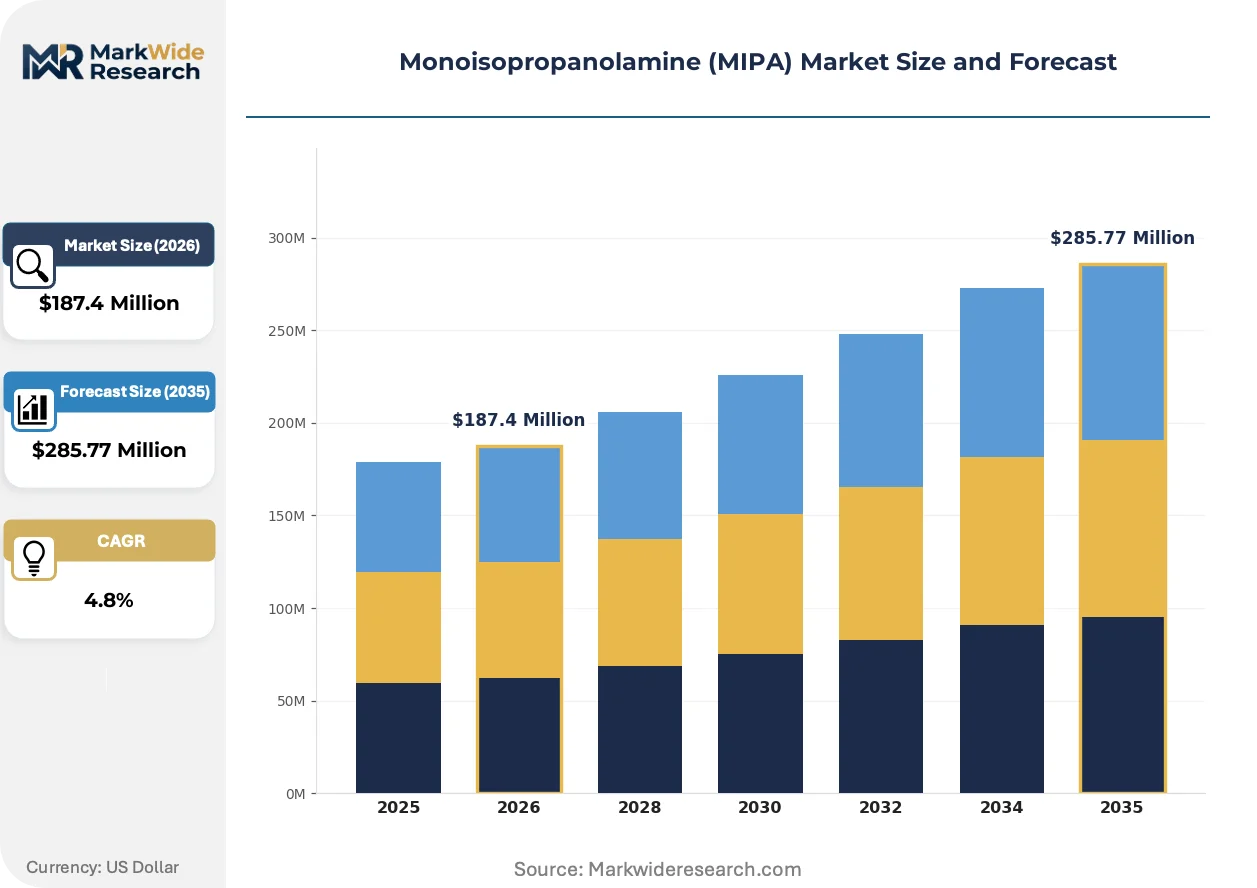
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Pharmaceutical Grade, Cosmetic Grade End Use Industry: Pharmaceuticals, Agriculture, Personal Care, Cleaning Agents Application: Solvent, Surfactant, Neutralizing Agent, Intermediary Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Huntsman Corporation, Horizon Chemical, BASF, Air Products and Chemicals, Inc., Clariant AG, Dow Chemical Company, Nanjing Hongbaoli, Amines & Plasticizers Ltd., Sasol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoisopropanolamine (MIPA) Market Shifts & Advancements
Continuous flow amination reactor technology is displacing batch processes, while regulatory data requirements are digitizing certificate-of-analysis workflows and procurement patterns are consolidating around certified-supplier lists.
Membrane separation systems for propylene oxide purification are miniaturizing impurity removal steps previously requiring multi-stage distillation. Specialty chemical manufacturers in Japan and South Korea are adopting these units to meet PMDA and MFDS pharmaceutical-grade specifications. The technology is miniaturizing capital footprints for mid-scale producers seeking to enter certified supply chains without greenfield construction.
REACH Annex XVII restrictions on residual ethylene oxide in ethoxylated derivatives are tightening upstream accountability for MIPA suppliers providing intermediates to surfactant formulators. European formulators must now document full supply chain toxicological profiles, forcing certification investments that smaller merchants cannot absorb. Personal care and household cleaning segments are responding by consolidating procurement around vertically integrated producers with in-house analytical capabilities.
Certificate-of-analysis digitization is replacing paper-based lot documentation as downstream buyers automate supplier qualification workflows. Specialty chemical distributors are embedding blockchain-traceable purity data into customer portals, displacing manual COA verification. This pattern is most visible in United States pharmaceutical and cosmetic formulating clusters where FDA inspection readiness demands real-time documentation access.
Monoisopropanolamine (MIPA) Market Segmentation
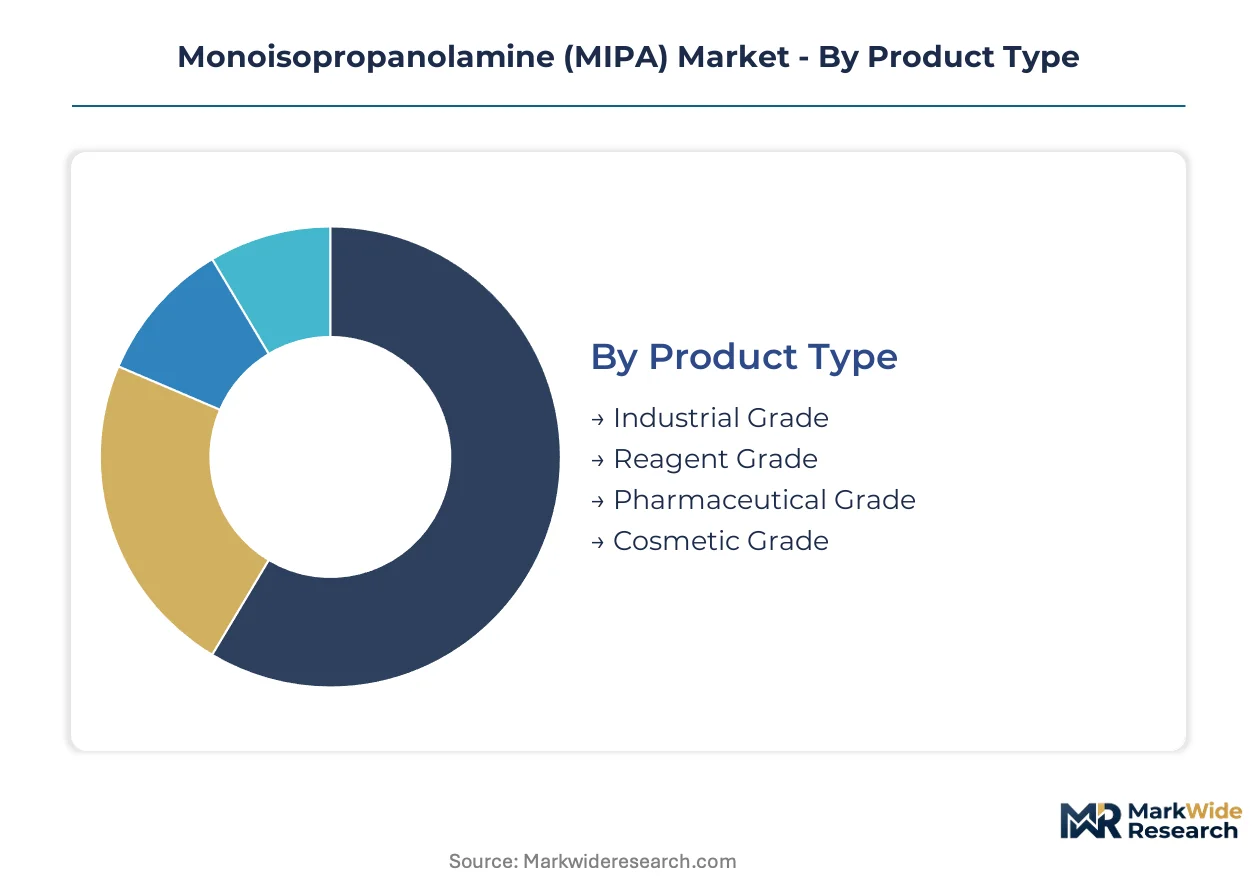
Margin capture in MIPA markets diverges sharply across purity tiers and end-use specifications, with certification requirements fragmenting supplier economics. Pharmaceutical-grade and industrial-grade segments operate on fundamentally different cost structures and customer loyalty mechanisms.
Product Type:
Pharmaceutical-grade commands the highest margin pool per tonne, while industrial-grade generates volume-driven revenue through commodity solvent applications.
- Industrial Grade:Standard purity specifications serve metalworking fluid formulations and gas-treatment corrosion inhibition across manufacturing clusters in Germany and Texas. BASF and Dow Chemical anchor supply through integrated propylene oxide amination chains.
- Pharmaceutical Grade:Impurity-profile documentation under FDA and CDSCO filing requirements forces dedicated production lines and chromatography validation. Demand concentrates in excipient manufacturing for oral dosage forms where lot-to-lot consistency determines supplier selection.
- Reagent Grade:Analytical laboratory consumption in quality control and research synthesis drives procurement from specialty chemical distributors.
- Cosmetic Grade:Personal care formulators in France and South Korea specify residual solvent limits below industrial thresholds for emulsifier applications.
Industrial grade holds installed capacity. Pharmaceutical grade is rotating up the share rankings.
End Use Industry:
Cleaning agents manufacturers are expanding procurement fastest, while pharmaceutical formulators impose the steepest certification barriers.
- Cleaning Agents:Industrial and household surfactant producers in the United States and China specify MIPA for pH buffering and emulsification. REACH Annex XVII compliance on ethoxylated derivatives is consolidating procurement around vertically integrated suppliers with in-house toxicological documentation.
- Pharmaceuticals:Excipient-grade consumption for tablet coating and solubilization requires FDA-type II drug master file support. CDSCO filing requirements in India create certified-supplier gaps that compliant importers exploit.
- Personal Care:Cosmetic formulators in Japan and South Korea demand PMDA and MFDS-aligned impurity profiles for rinse-off and leave-on applications.
- Agriculture:Pesticide intermediate synthesis consumes technical-grade material through captive production at agrochemical manufacturers in China.
Cleaning agents is expanding most quickly. Pharmaceuticals retains the tightest supplier qualification standards.
Application:
Surfactant synthesis generates the densest customer concentration, while neutralizing-agent applications spread across fragmented industrial maintenance budgets.
- Surfactant:Alkanolamine ethoxylation for household and industrial detergents concentrates demand in Germany, the United States, and China. Huntsman Corporation and BASF compete through dedicated alkoxylation capacity and technical service bundling.
- Solvent:Metalworking fluid formulations and natural gas processing facilities specify MIPA for corrosion inhibition and pH control. Demand clusters in Texas, Alberta, and the North Sea offshore infrastructure.
- Neutralizing Agent:pH adjustment in water treatment and chemical synthesis operates on price-sensitive procurement through merchant chemical distributors.
- Intermediary:Specialty chemical synthesis for pharmaceutical and agrochemical active ingredients requires reagent-grade consistency and documented supply chain traceability.
Solvent holds installed capacity. Surfactant is rotating up the share rankings.
Distribution Channel:
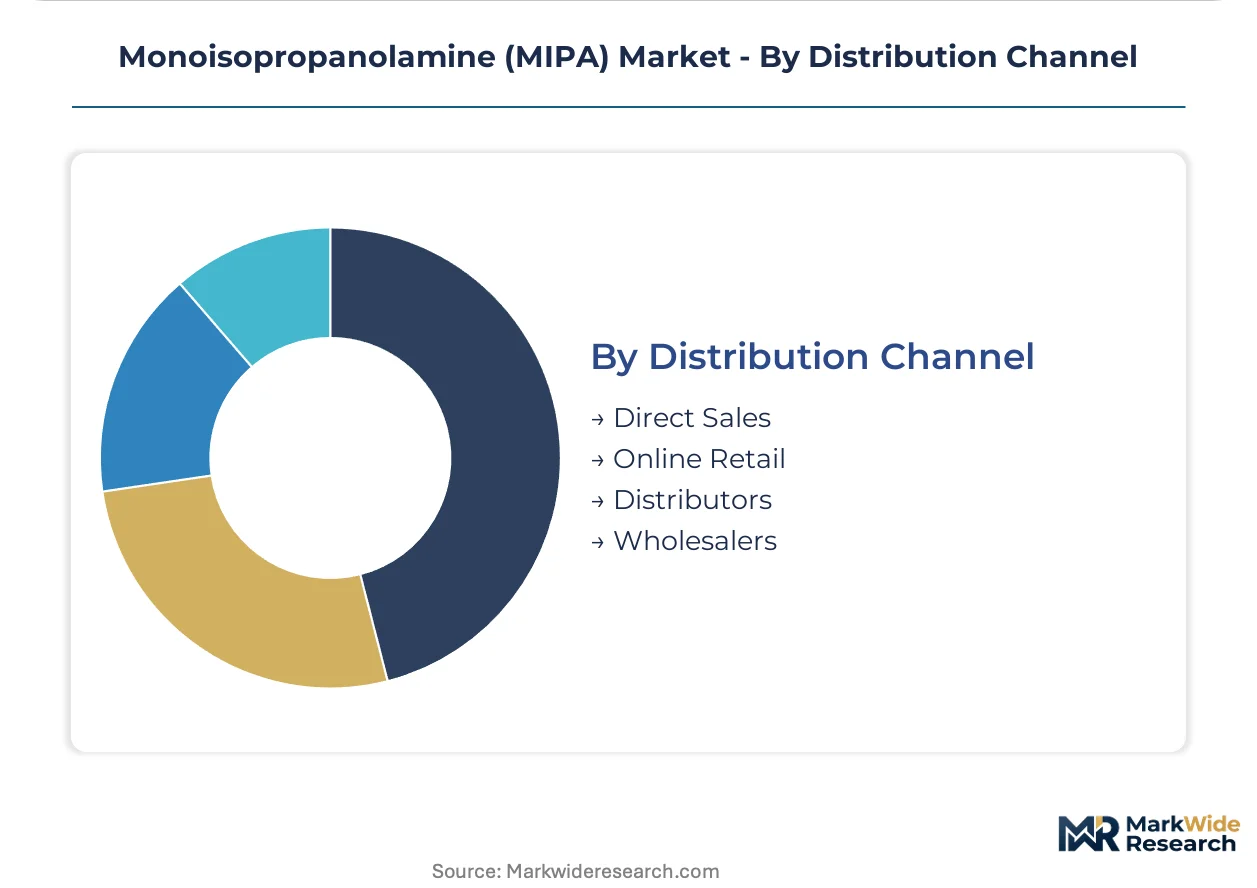
Direct sales capture premium pricing through technical service attachment, while distributor networks fragment margin pools across multiple intermediaries.
- Direct Sales:Bulk solvent distributors bypass traditional merchant networks to embed certificate-of-analysis digitization and real-time lot traceability for pharmaceutical and cosmetic formulators. Blockchain-enabled purity data displaces manual verification workflows.
- Distributors:Regional chemical merchants serve mid-scale industrial formulators with standardized industrial-grade material and paper-based documentation.
- Online Retail:Laboratory chemical suppliers list reagent-grade MIPA through e-procurement portals for analytical and research customers.
- Wholesalers:Commodity chemical traders aggregate small-lot demand from fragmented metalworking and maintenance operations.
Direct sales is climbing the fastest. Distributors retains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping procurement patterns as pharmaceutical-grade supply concentrates in manufacturing hubs while industrial-grade demand spreads across processing clusters. Net importers face certificate-of-analysis bottlenecks. Net exporters leverage integrated feedstock positions.
China
Domestic amine producers are scaling pharmaceutical-grade output for excipient and surfactant applications. NMPA and GB standards govern impurity thresholds for domestically produced and imported material. The Yangtze River Delta hosts concentrated alkoxylation capacity serving cleaning agents manufacturers.
United States
Metalworking and natural gas processing facilities in Texas and the Gulf Coast are expanding MIPA procurement for corrosion inhibition. EPA standards under the Toxic Substances Control Act shape permissible emission profiles during manufacture. Houston anchors North American supply through dedicated alkoxylation infrastructure.
Germany
REACH registration obligations mandate full toxicological dossiers for import and production volumes above one tonne annually. ECHA compliance is consolidating compliant suppliers and locking in premium pricing. The Rhine-Ruhr region maintains integrated amine-to-alkanolamine production chains.
India
CDSCO filing requirements for excipient-grade MIPA create certified-supplier gaps that compliant importers can exploit. Pharmaceutical manufacturing clusters in Maharashtra and Gujarat drive demand for documented impurity profiles. Mumbai-Pune corridor concentrates tablet coating and solubilization applications.
Japan
Specialty chemical manufacturers are adopting membrane separation systems to meet PMDA pharmaceutical-grade specifications. METI oversees industrial chemical standards while PMDA governs excipient purity. The Kansai region around Osaka hosts mid-scale producers seeking certified supply chain entry.
Monoisopropanolamine (MIPA) Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The vendor base fragments across integrated chemical conglomerates, regional amine specialists, and captive agrochemical producers. Three archetypes dominate: backward-integrated propylene oxide players, dedicated alkanolamine merchants, and pharmaceutical-grade purity specialists. Competitive moves concentrate on capacity expansion in Asia-Pacific and M&A targeting analytical chemistry capabilities.
Within the integrated chemical tier, BASF and Dow Chemical Company exemplify archetypes combining feedstock control with technical service bundling. Huntsman Corporation occupies a position among North American alkoxylation specialists. These three anchors demonstrate how geographic production integration and certification infrastructure determine competitive positioning across purity grades.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Horizon Chemical |
| BASF |
| Air Products and Chemicals, Inc. |
| Clariant AG |
| Dow Chemical Company |
| Nanjing Hongbaoli |
| Amines & Plasticizers Ltd. |
| Sasol |
| Others |
Supply & Pricing Matrix
Capacity utilization at integrated propylene oxide amination facilities in Germany and China shapes both supply concentration and price floors for non-integrated competitors. REACH registration costs and EPA emission compliance create fixed-cost barriers that reinforce tiered pricing stratification across pharmaceutical and industrial grades.
Pricing Analysis
Industrial OEM buyers anchor commodity pricing for metalworking fluid and gas-treatment applications, while pharmaceutical formulators accept premium-mid-economy pricing differentiation driven by FDA and CDSCO certification tiers. Price differentiation stems from impurity-profile documentation costs and volume scale commitments. Cost compression in industrial grades is intensifying because ammonia feedstock volatility squeezes merchant producer margins. Cleaning agents manufacturers exhibit highest price sensitivity, whereas excipient-grade pharmaceutical buyers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Inventory buffers for pharmaceutical-grade MIPA extend lead times by 30-45 days versus industrial-grade spot availability due to chromatography validation requirements. Manufacturing concentrates in China, Germany, and the United States, with propylene oxide, ammonia, and specialized catalysts as critical inputs. Single-source vulnerability runs through Yangtze River Delta alkoxylation clusters exposed to NMPA regulatory shifts. Distribution runs through bulk solvent distributors embedding certificate-of-analysis digitization for pharmaceutical and cosmetic formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward cleaning agents manufacturers consolidating procurement around vertically integrated suppliers with in-house toxicological documentation capabilities.
For Market Incumbents: Compound analytical chemistry capabilities through dedicated chromatography validation investments to defend pharmaceutical-grade margin pools against emerging purity specialists. Deepen backward integration into propylene oxide feedstock to buffer ammonia price volatility and sustain cost position in industrial grades. For New Entrants and Emerging Players: Lead with CDSCO-compliant excipient-grade supply to capture certified-supplier gaps in Maharashtra and Gujarat pharmaceutical manufacturing clusters. Target direct-to-formulator distribution partnerships that bypass traditional merchant networks and embed real-time lot traceability. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane separation system adopters meeting PMDA and MFDS specifications without greenfield construction. Long-term viability hinges on regulatory data infrastructure rather than capacity scale alone. Watch for digitization of certificate-of-analysis workflows as inflection signal for procurement pattern consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene oxide supply insulates BASF and Dow from feedstock volatility. |
| Green Manufacturing Transition | Ammonia-from-biomass pilots in the Netherlands align with EU Green Deal criteria. |
| Long-term Supply Agreement | Cleaning agents manufacturers lock in REACH-compliant ethoxylated derivative supply. |
| Capacity Expansion | Yangtze River Delta alkoxylation additions serve domestic surfactant demand growth. |
| Joint Venture | Membrane technology partnerships enable Japanese mid-scale producers to enter certified chains. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with plant managers, procurement leads at downstream surfactant OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, ACC/Cefic industry reports, SEC 10-K filings, and ECHA registration dossiers. Bottom-up capacity and consumption modeling triangulated against top-down trade flow analysis.
Across the projection horizon, the analytical framework segmented by grade tier, end-use industry, and regional production hub. CAGRs derived from regression against historical propylene oxide price elasticity and regulatory filing velocity. Forecast inputs included REACH Annex XVII compliance cost trajectories and CDSCO excipient approval timelines.
The analysis sits within stated boundaries; outcomes outside sustained ammonia supply stability or accelerated green chemistry mandate adoption would require recalibration. Forecasts reflect documented assumptions regarding propylene oxide amination technology diffusion and regulatory data requirement harmonization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Japan Methanol Market
Chemicals
Inorganic Chemicals Market
Chemicals
Triethylenediamine Market
Chemicals
Piroctone Olamine Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Vinyl Acetate Market
Chemicals
Ruthenium Tetroxide Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Trichlorosilane Market
Chemicals
Thioacetic Acid Market
Chemicals
Cummene Derivatives Market
Chemicals
United States Construction Chemicals Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Phosgene Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Rocket Propellant Chemicals Market