
 Guaiazulene Market | 2026-2036
Guaiazulene Market Size, Share, and Industry Trends Forecast 2026-2036
Guaiazulene Market Analysis
Synthetic guaiazulene is realigning cost structures as manufacturers shift from chamomile-derived natural extracts to lab-sourced alternatives. Chemwill Asia Co., Ltd. leverages its Chinese chemical synthesis base to supply bulk pharmaceutical-grade material. Haihang Industry Co., Ltd. sustains competitive positioning through specialized azulene derivative portfolios. MEDIANS Co., Ltd. anchors its operations in South Korean cosmetic ingredient channels, where formulation houses demand consistent batch purity.
Guaiazulene is a bicyclic sesquiterpene azulene hydrocarbon (C15H18) with a deep-blue chromophore, typically isolated from chamomile essential oil or synthesized via dehydrogenation of guaiol; it functions primarily as an anti-inflammatory, skin-soothing, and colorant agent across topical and aromatic applications. Natural guaiazulene commands premium positioning in clean-label skincare, though synthetic variants capture volume in pharmaceutical manufacturing where cost predictability matters more than botanical provenance. Skincare applications lead absolute consumption, while medicinal uses show the steepest growth trajectory as topical anti-inflammatory formulations expand in dermatology pipelines.
REACH in Europe mandates purity thresholds and full supply-chain disclosure for cosmetic and pharmaceutical raw materials, pushing non-compliant suppliers toward reformulation or exit. China's NMPA and SAMR enforce Good Manufacturing Practice standards for active pharmaceutical ingredients that include guaiazulene, creating compliance barriers for uncertified exporters. South Korea's MFDS cosmetic ingredient notification system adds another layer of pre-market scrutiny. Stakeholders must monitor regulatory divergence between these jurisdictions to avoid supply interruptions and align certification investments with their highest-revenue destination markets.
Market Dynamics
Synthetic guaiazulene is displacing chamomile-derived extracts as REACH purity mandates tighten and East Asian cosmetic formulators demand batch-to-batch color consistency. This feedstock shift is compressing natural extract premiums while expanding pharmaceutical-grade synthesis capacity.
Growth Catalysts
- REACH Purity Thresholds:ECHA's tightened impurity limits for cosmetic raw materials are disqualifying natural extract variability, forcing formulators toward synthetic alternatives with certified chromophore stability.
- Sensitive-Skin Product Lines:South Korean skincare houses are embedding azulene derivatives into ceramide-based barrier repair formulations, creating dedicated ingredient demand that bypasses commodity spot markets.
- Guaiol Dehydrogenation:Continuous-flow catalytic synthesis is reducing per-kilogram production costs versus batch natural extraction, enabling volume supply to pharmaceutical anti-inflammatory pipelines.
Market Restraints
- Feedstock Concentration:Guaiol supply for synthetic routes concentrates in Chinese terpene processors, exposing buyers to single-origin disruption risk during environmental compliance inspections.
- Natural Extract Substitution:Chamomile-derived guaiazulene retains clean-label premium positioning in EU organic cosmetic channels, limiting synthetic penetration where botanical provenance commands shelf price premiums.
- Chromophore Degradation:Synthetic batches exhibit photolytic instability under UV exposure, requiring stabilized formulation vehicles that add compounding complexity and cost.
Strategic Opportunities
- Brazilian ANVISA Pathway:Pre-registration of synthetic guaiazulene as an active pharmaceutical ingredient under Brazil's simplified API notification creates first-mover access to Latin American dermatology markets.
- Bioreactor-Derived Biosynthesis:Yeast-engineered sesquiterpene production converges synthetic consistency with renewable feedstocks, potentially satisfying EU Green Deal circularity requirements without agricultural land use.
- Direct-to-Formulator Platforms:Specialty chemical distributors are launching digital sample-to-bulk procurement portals, disintermediating traditional agent networks for mid-scale cosmetic compounders.
Industry Challenges
- Pharmaceutical GMP Certification:China's NMPA and SAMR require documented continuous process validation for API-grade material, extending facility qualification timelines by 18-24 months for uncertified entrants.
- Analytical Method Harmonization:Divergent purity testing protocols between MFDS in South Korea and ECHA in Europe force duplicate batch characterization, inflating quality control overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guaiazulene Market |
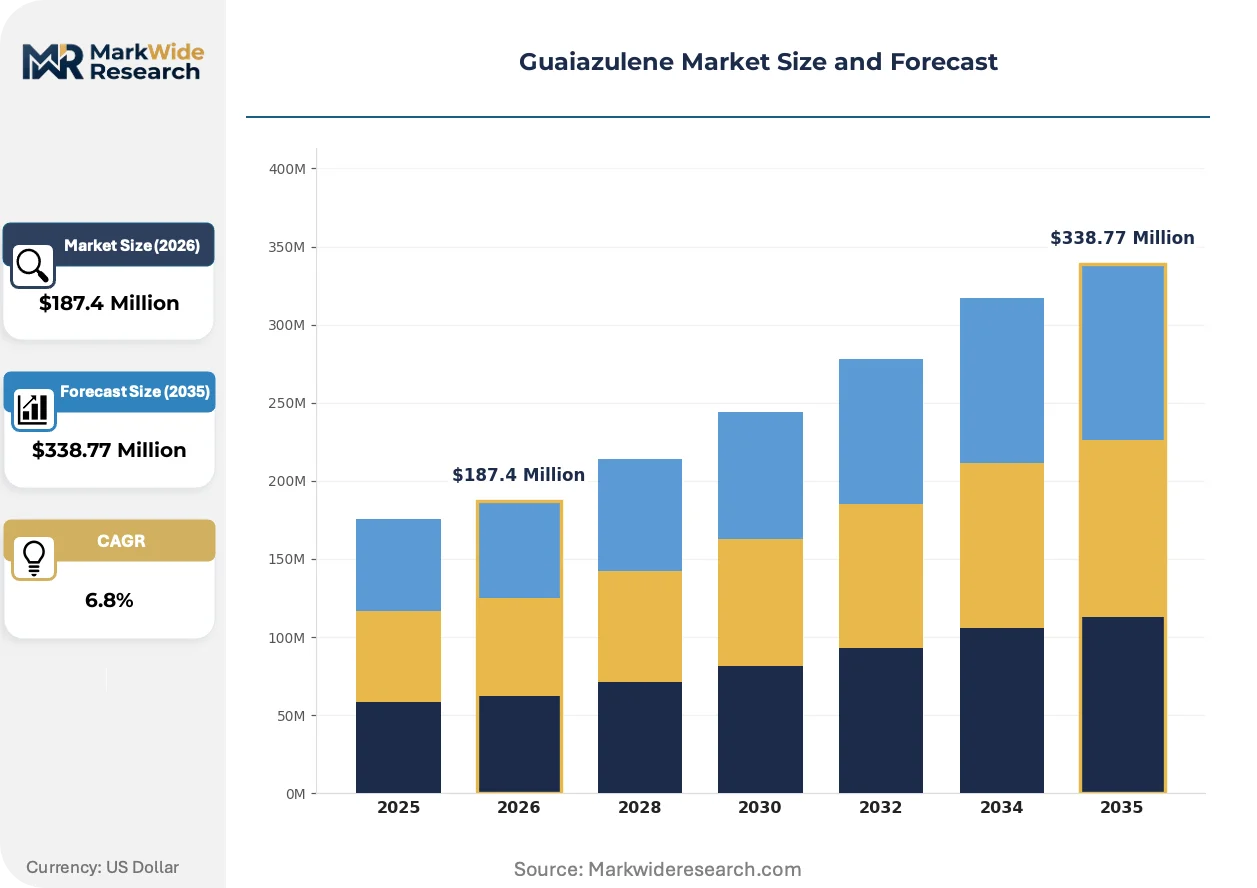
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Guaiazulene, Synthetic Guaiazulene, Pharmaceutical Guaiazulene, Cosmetic Guaiazulene Application: Skincare Products, Haircare Products, Medicinal Uses, Aromatherapy Products End User: Pharmaceutical Companies, Cosmetic Manufacturers, Research Laboratories, Nutraceutical Firms Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Chemwill Asia Co., Ltd., Haihang Industry Co., Ltd., MEDIANS Co., Ltd., Venus Concept, Guangzhou Fourto Sanitary Products Co., Ltd., HONG KONG YASHA Bio-technology Company Ltd., Mainchem Co., Ltd., Hubei Xin Bonus Chemical Co., Ltd., Calibre Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guaiazulene Market Emerging Trajectories
Process intensification and regulatory alignment are reshaping how guaiazulene is manufactured, certified, and procured. Three developments are compressing legacy supply arrangements while opening new specification tiers.
Continuous-flow catalytic dehydrogenation is electrifying synthetic production economics by replacing batch reactors with microchannel systems that halve solvent waste and enable real-time purity monitoring. Pharmaceutical manufacturers in Germany are qualifying this technology for anti-inflammatory API supply, while Chinese synthesis houses scale output for cosmetic-grade volumes. The shift is compressing batch-to-batch color variation below 2% Delta E, unlocking premium skincare formulation contracts that previously rejected synthetic material.
REACH's 2023 update to Annex XVII restricted substance thresholds is forcing reformulation of legacy azulene-containing topical products across EU member states. Manufacturers must now submit full supply-chain substance flow documentation, including guaiazulene precursor origins. Cosmetic compounders are responding by dual-sourcing synthetic material from REACH-registered Chinese suppliers while maintaining natural extract lines for organic-certified channels.
South Korean skincare brands are compressing ingredient qualification cycles from 18 months to 6 months through pre-validated supplier partnerships, bypassing traditional RFP processes. This acceleration favors synthesis houses with established MFDS cosmetic ingredient notifications, locking out unregistered competitors regardless of price position. The shift is most visible in Seoul's Gangnam formulation cluster, where contract manufacturers bundle azulene derivatives into turnkey sensitive-skin bases for emerging domestic brands.
Guaiazulene Market Segmentation
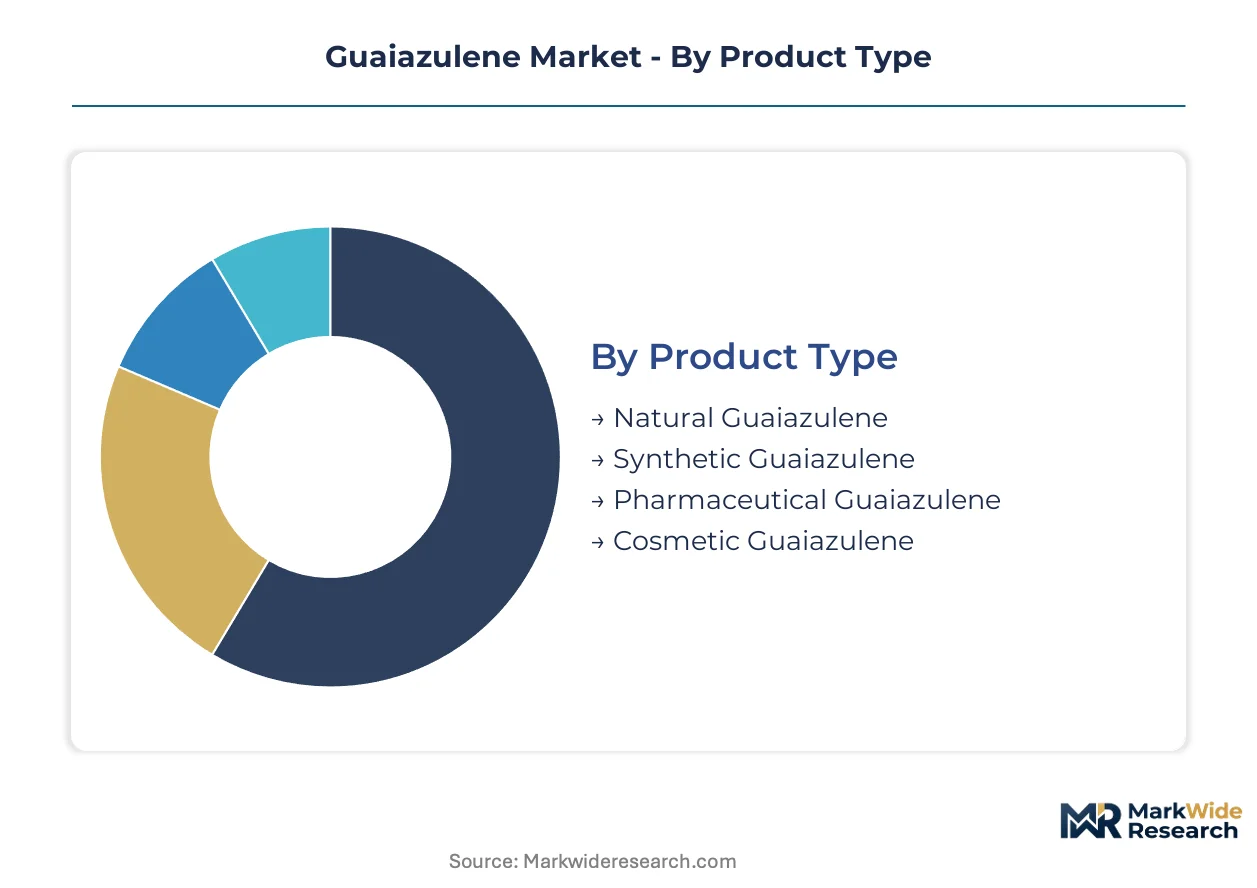
Guaiazulene's value chain fragments across purity grades and certification tiers that determine access to pharmaceutical versus cosmetic channels. Specification alignment with REACH, NMPA, and MFDS standards creates rigid segment boundaries that suppliers cannot cross without facility reinvestment.
Product Type:
Synthetic consistency now defines competitive positioning as batch-to-batch chromophore stability becomes a procurement requirement.
- Natural Guaiazulene:Isolated from chamomile essential oil through fractional distillation, retaining trace sesquiterpene complexity that clean-label formulators market as botanical authenticity. EU organic cosmetic channels in France and Germany sustain premium offtake despite price volatility from agricultural yield fluctuation.
- Synthetic Guaiazulene:Manufactured via guaiol dehydrogenation with controlled catalytic conditions yielding C15H18 purity above 99.5%. German pharmaceutical manufacturers now specify synthetic material exclusively as ECHA tightens impurity disclosure thresholds for topical anti-inflammatory APIs.
- Pharmaceutical Guaiazulene:GMP-certified production with documented continuous process validation for API-grade supply.
- Cosmetic Guaiazulene:MFDS-registered batches with color stability specifications for sensitive-skin formulation bases.
Mature deployment sits with natural extraction for premium organic channels. Newer deployment is concentrated in synthetic pharmaceutical-grade material.
Application:
End-use concentration tracks regulatory pathway complexity, with medicinal routes demanding steeper compliance investment than cosmetic compounding.
- Skincare Products:Ceramide-based barrier repair formulations in South Korea absorb azulene derivatives at specification tiers that require sub-2% Delta E color variation. Seoul's Gangnam formulation cluster sources pre-validated material through direct supplier partnerships that compress qualification cycles.
- Medicinal Uses:Topical anti-inflammatory dermatology pipelines in Germany specify synthetic guaiazulene for API incorporation, with EMA marketing authorization pathways mandating full supply-chain substance flow documentation.
- Haircare Products:Scalp-soothing treatments in Japanese professional salon channels.
- Aromatherapy Products:Chromophore-dependent colorant applications with lower purity thresholds.
Mature deployment sits with aromatherapy colorant applications. Newer deployment is concentrated in medicinal dermatology formulations.
End User:
Customer scale determines procurement modality, with large compounders bypassing distributor networks entirely.
- Pharmaceutical Companies:Bayer and Merck KGaA procurement specifications for anti-inflammatory APIs require REACH-registered suppliers with ECHA substance volume tracking.
- Cosmetic Manufacturers:Amorepacific and LG Household & Health Care operate pre-validated supplier partnerships that lock out unregistered competitors regardless of price position.
- Research Laboratories:Academic and contract research organizations sourcing analytical-grade reference standards.
- Nutraceutical Firms:Ingestible-grade azulene derivative demand for antioxidant supplement formulations.
Mature deployment sits with research laboratory reference standard supply. Newer deployment is concentrated in cosmetic manufacturer direct partnerships.
Distribution Channel:
Channel selection reflects order scale and specification complexity, with pharmaceutical-grade material rarely transacting through open retail.
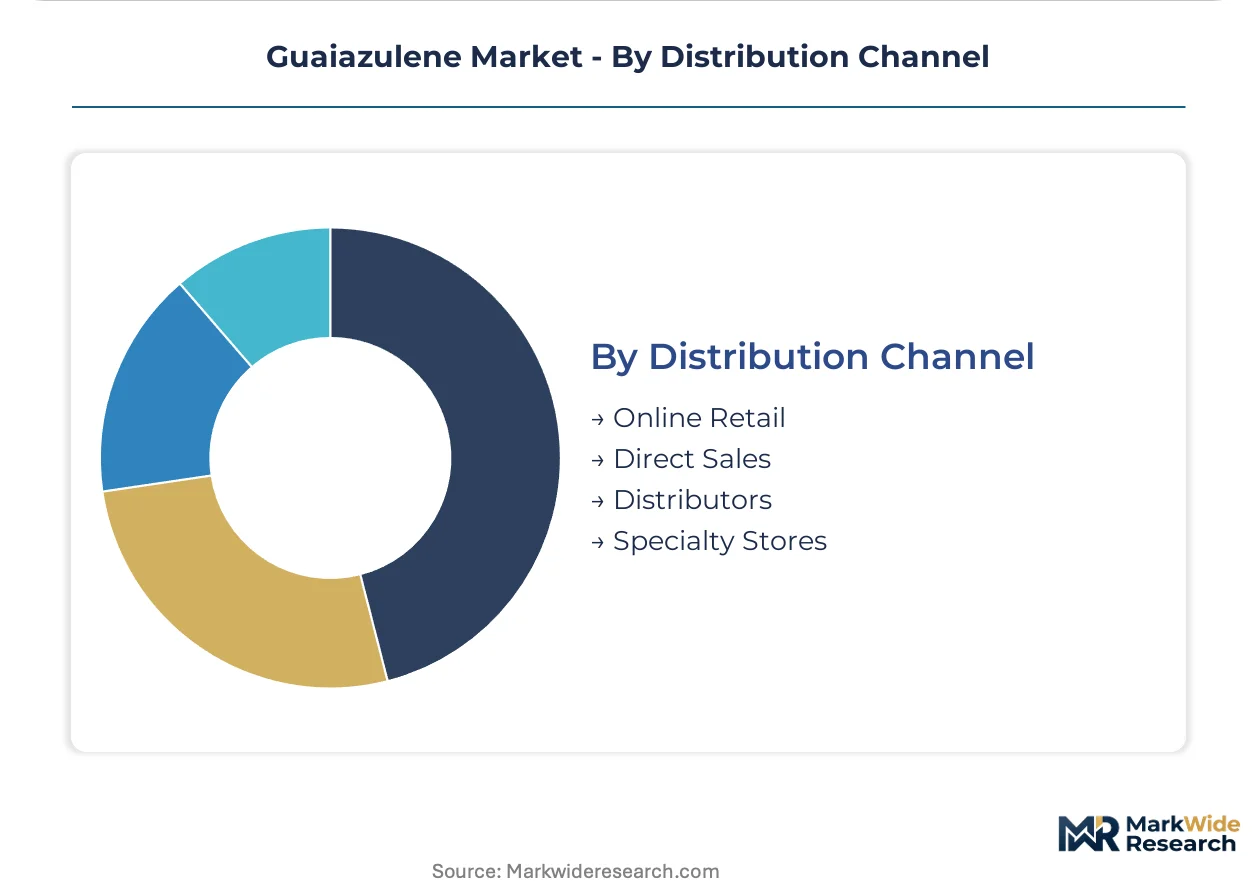
- Direct Sales:Multi-year supply agreements with pharmaceutical manufacturers specify continuous-flow synthesis output with quarterly purity audits.
- Distributors:Specialty chemical distributors in Shanghai and Rotterdam maintain cosmetic-grade inventory for mid-scale compounders.
- Online Retail:Small-volume azulene derivative sales to independent formulators and research institutions.
- Specialty Stores:Regional cosmetic ingredient retailers serving artisan skincare producers.
Mature deployment sits with distributor networks for mid-scale cosmetic compounders. Newer deployment is concentrated in direct sales agreements with pharmaceutical manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian cosmetic manufacturing clusters absorb the majority of pharmaceutical-grade guaiazulene volume, while German pharmaceutical pipelines drive synthetic specification standards through REACH-mandated purity thresholds.
South Korea
Seoul's Gangnam formulation cluster processes azulene derivatives for sensitive-skin ceramide bases at specification tiers requiring sub-2% Delta E color variation. MFDS cosmetic ingredient notification requirements compress supplier qualification cycles to six months, locking out unregistered competitors. Pre-validated partnerships with domestic synthesis houses now dominate procurement for emerging skincare brands headquartered in the capital region.
Germany
Bayer and Merck KGaA procurement specifications for topical anti-inflammatory APIs require REACH-registered suppliers with full ECHA substance volume tracking. EMA marketing authorization pathways mandate documented supply-chain substance flow for guaiazulene precursor origins. Pharmaceutical manufacturers in the Rhine-Ruhr industrial belt now specify synthetic material exclusively as ECHA tightens impurity disclosure thresholds.
China
Yangtze River Delta chemical synthesis bases supply bulk pharmaceutical-grade material through continuous-flow catalytic dehydrogenation systems. NMPA and SAMR enforce GMP standards for active pharmaceutical ingredients that include guaiazulene, creating compliance barriers for uncertified exporters. Shanghai specialty distributors maintain cosmetic-grade inventory for mid-scale compounders serving domestic and export channels.
Japan
PMDA marketing authorization pathways for topical dermatology products specify chromophore stability requirements that favor synthetic consistency over natural extract variability. METI industrial standards for cosmetic raw materials align with REACH purity thresholds, facilitating cross-qualification for suppliers. Osaka-based scalp-soothing treatment manufacturers source stabilized azulene derivatives for professional salon channels.
Brazil
ANVISA's simplified API notification pathway for synthetic guaiazulene creates first-mover access to Latin American dermatology markets for pre-registered suppliers. São Paulo-based pharmaceutical distributors are qualifying new active ingredient sources as domestic topical anti-inflammatory demand expands. The regulatory window favors synthesis houses with documented continuous process validation and Portuguese-language dossier capabilities.
Guaiazulene Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade supply consolidating around GMP-certified synthesis houses while cosmetic channels fragment across specialty distributors. Three archetypes dominate: Chinese terpene processors controlling guaiol feedstock, South Korean cosmetic ingredient specialists with MFDS-registered portfolios, and European pharmaceutical-grade suppliers with REACH-registered production. Competitive moves center on backward integration into guaiol supply and pre-validation partnerships with major compounders that compress rival qualification timelines.
Within the Asian synthesis tier, Chemwill Asia Co., Ltd. and Haihang Industry Co., Ltd. represent Chinese chemical manufacturing archetypes positioned for bulk pharmaceutical-grade supply, while MEDIANS Co., Ltd. exemplifies South Korean cosmetic ingredient channel specialization. These three entities anchor distinct competitive vectors: feedstock-adjacent scale production, derivative portfolio breadth, and pre-validated regional channel access respectively.
| Leading Market Players |
|---|
| Chemwill Asia Co., Ltd. |
| Haihang Industry Co., Ltd. |
| MEDIANS Co., Ltd. |
| Venus Concept |
| Guangzhou Fourto Sanitary Products Co., Ltd. |
| HONG KONG YASHA Bio-technology Company Ltd. |
| Mainchem Co., Ltd. |
| Hubei Xin Bonus Chemical Co., Ltd. |
| Calibre Chemicals |
| Others |
Supply Flow & Price Mechanics
German pharmaceutical procurement offices and Seoul's Gangnam formulation cluster concentrate buying power in synthetic guaiazulene, anchoring a contract-based long-term offtake model where REACH-registered suppliers command 15-20% premia over uncertified alternatives. This buyer concentration compresses spot market liquidity and forces tiered pricing stratification across pharmaceutical-grade, cosmetic-grade, and aromatherapy material.
Pricing Analysis
High-volume pharmaceutical contracts absorb margin compression through multi-year supply agreements, while small-batch cosmetic compounders face pricing pressure from MFDS registration costs that add fixed overhead per kilogram. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and technical-grade levels differentiates synthetic material by certification tier and chromophore stability specification. Cost compression in cosmetic-grade tiers intensifies because South Korean formulators demand sub-2% Delta E color consistency that requires stabilized formulation vehicles. Research laboratories purchasing analytical-grade reference standards exhibit highest price sensitivity, while Bayer and Merck KGaA procurement specifications prioritize supply security over unit cost.
Supply Chain Analysis
Specialized catalytic process engineers in China's Yangtze River Delta, South Korean MFDS-registered synthesis houses, and German REACH-compliant API manufacturers anchor production capacity for pharmaceutical and cosmetic grades. Guaiol feedstock draws from Chinese terpene processors, hydrogen supply from regional chemical clusters, and stabilized formulation vehicles from Japanese specialty chemical producers. Single-source vulnerability concentrates in Yangtze River Delta guaiol supply during environmental compliance inspections. Distribution runs through Shanghai and Rotterdam specialty chemical distributors for mid-scale compounders, with direct sales agreements dominating pharmaceutical manufacturer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Guaiazulene supply is consolidating around GMP-certified synthesis houses as ECHA impurity disclosure thresholds and MFDS notification requirements force uncertified competitors toward exit or acquisition.
For Market Incumbents: Acquire continuous-flow catalytic dehydrogenation assets in China's Yangtze River Delta to lock in guaiol feedstock access and compress batch-to-batch color variation below rival capability. Backward integration into guaiol supply insulates against single-origin disruption risk during environmental compliance inspections. Pre-validated partnerships with Seoul's Gangnam formulation cluster defend market position against emerging South Korean domestic synthesis houses. For New Entrants and Emerging Players: Direct-to-formulator digital procurement portals offer the lowest barrier entry path for mid-scale cosmetic compounders seeking to bypass traditional agent networks. Brazil's ANVISA simplified API notification pathway presents the most penetrable regulatory geography for pharmaceutical-grade material, with São Paulo-based distributors actively qualifying new active ingredient sources. Target yeast-engineered sesquiterpene biosynthesis as a go-to-market angle that satisfies EU Green Deal circularity requirements without agricultural land use. For Investors and Strategic Acquirers: The window for entry favors GMP-certified Chinese synthesis houses with documented continuous process validation and Portuguese-language dossier capabilities for Latin American expansion. Long-term viability centers on regulatory moat width rather than production scale, as REACH and MFDS compliance costs rise faster than volume growth. Watch for ANVISA pre-registration approvals as the inflection indicator signaling first-mover access consolidation in Latin American dermatology markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guaiol Feedstock | Yangtze River Delta terpene processor acquisitions insulate against environmental compliance disruption. |
| MFDS Cosmetic Ingredient Notification | South Korean pre-validation compresses qualification cycles to six months for Seoul formulation clusters. |
| Continuous-Flow Catalytic Dehydrogenation Scale-Up | Microchannel systems halve solvent waste and enable real-time purity monitoring for pharmaceutical contracts. |
| ANVISA API Pre-Registration | Simplified notification creates first-mover access to São Paulo pharmaceutical distribution channels. |
| Yeast-Engineered Biosynthesis Development | Bioreactor-derived production converges synthetic consistency with EU Green Deal circularity requirements. |
Methodological Framework
Independent corroboration across synthesis house technical directors, pharmaceutical procurement managers at Bayer and Merck KGaA, and Seoul formulation cluster compounders underwrites the qualitative findings on specification tier fragmentation. Secondary validation draws from ECHA REACH registration databases, MFDS cosmetic ingredient notifications, NMPA GMP certification records, and customs trade data for guaiol and azulene derivative flows. Bottom-up capacity estimates from Yangtze River Delta chemical parks and top-down demand modeling from German dermatology prescription data triangulate market sizing.
Comparable-period anchoring to historical pharmaceutical API pricing and cosmetic ingredient procurement cycles establishes the forecast baseline across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application, certification pathway, and regional regulatory cluster. CAGRs derive from regression analysis of synthetic guaiazulene volume growth against REACH compliance cost trajectories and South Korean sensitive-skin product line expansion rates. Forecast inputs incorporate continuous-flow catalytic dehydrogenation capacity buildout schedules and MFDS notification approval timelines.
The model holds under stable REACH and MFDS regulatory enforcement intensity; deviation in ECHA impurity threshold tightening or NMPA environmental inspection frequency would shift supply concentration and pricing power distribution. Forecasts reflect documented assumptions on guaiol feedstock availability, certification cost inflation, and chromophore stability technology diffusion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Calcium Carbide Market
Chemicals
Superplasticizer Market
Chemicals
Global Cysteine Market
Chemicals
Zinc Chemicals Market
Chemicals
Coagulant Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Phenothiazine Market
Chemicals
Muriatic Acid Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Global Chiral Chemicals Market
Chemicals
China Methanol Market
Chemicals
Formalin Vials Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Industrial Odor Management Market