
 Middle East and Africa Construction Chemicals Market | 2026-2036
Middle East and Africa Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Construction Chemicals Market Insights
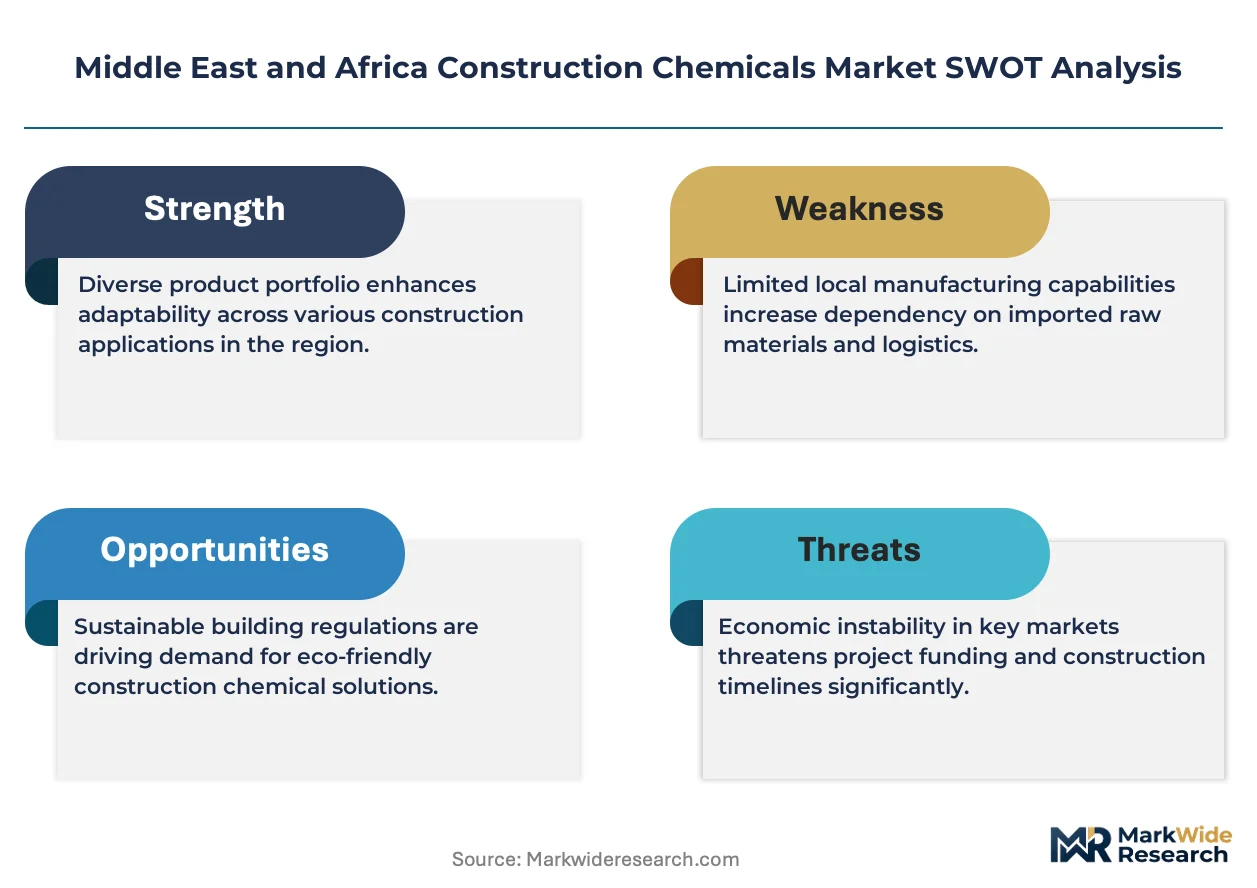
ISO 9001 quality management certification is reorganizing supplier eligibility across Middle East and Africa public tenders, sidelining uncertified local blenders. Sika AG leverages its Swiss technical heritage to sustain premium positioning in Gulf waterproofing segments. Fosroc Inc anchors its regional footprint through dedicated manufacturing in Jebel Ali and technical service centers across East Africa. Ahlia Chemicals Company competes on logistics proximity, controlling distribution networks within Saudi Arabia's interior construction corridors.
Construction chemicals encompass formulated additives and protective systems—ranging from polycarboxylate ether superplasticizers to epoxy-based membranes—that modify cementitious properties or shield structural elements from environmental degradation. These formulations typically achieve 15-40% water reduction in concrete mixes while extending service life through chloride ion resistance and carbonation protection. Admixtures dominate volume throughput across the region, reflecting the scale of ready-mix concrete consumption in Gulf mega-projects. Polymer-based coatings capture disproportionate margin pools, particularly in marine and hydrocarbon facility applications where epoxy and polyurethane chemistries command specification premiums. Cement-based materials retain cost-sensitive infrastructure share, though polymer modification is displacing traditional repair mortars in high-specification vertical construction.
SFDA material safety requirements, UAE's Emirates Authority for Standardization and Metrology (ESMA) conformity schemes, and Saudi Building Code provisions collectively dictate product registration, testing protocols, and environmental release thresholds for construction chemical formulations. These frameworks elevate compliance costs for imported formulations while creating localized formulation and testing capabilities as prerequisites for market participation. Stakeholders must monitor evolving Gulf standardization harmonization and potential carbon-content disclosure requirements that could reshape sourcing strategies and supplier qualification criteria.
Market Dynamics
SFDA material safety requirements and Emirates Authority for Standardization and Metrology conformity schemes are compressing supplier eligibility timelines, forcing formulation localization and testing infrastructure investment before market entry.
Growth Catalysts
- Polycarboxylate ether superplasticizers:Gulf mega-infrastructure programs are specifying these admixtures for high-strength concrete in high-rise and transport projects, driving volume procurement across ready-mix concrete channels.
- Saudi Building Code provisions:Structural durability mandates are tightening material compliance requirements, elevating demand for chloride-resistant and carbonation-protective formulations in vertical construction.
- UAE transport corridors:Dubai and Abu Dhabi project activity is anchoring protective coating consumption, particularly epoxy and polyurethane systems for marine and hydrocarbon facility applications.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and polyurethane precursor costs fluctuate with crude oil pricing, compressing margin stability for polymer-based membrane producers serving marine applications.
- Import formulation barriers:SFDA registration and ESMA testing protocols elevate compliance costs for foreign suppliers without localized blending capabilities or Gulf-based technical service centers.
- Cement-based repair mortar displacement:Polymer-modified systems are capturing high-specification vertical construction share, eroding traditional material volumes in cost-sensitive infrastructure segments.
Strategic Opportunities
- East Africa technical service expansion:Kenya and Ethiopia infrastructure pipelines lack established construction chemical distribution networks, creating first-mover advantages for suppliers establishing local application support.
- Carbon-content disclosure preparation:Anticipated Gulf standardization harmonization around embodied carbon tracking is opening formulation re-engineering contracts for low-carbon admixture development ahead of mandate implementation.
- ISO 9001 certification arbitrage:Public tender eligibility restrictions are sidelining uncertified local blenders, creating acquisition targets for regionally credentialed suppliers seeking interior Saudi distribution control.
Industry Challenges
- Formulation chemist scarcity:Gulf-based technical centers struggle to recruit professionals with simultaneous expertise in cement chemistry and polymer science for localized product adaptation.
- Multi-jurisdiction registration timelines:Parallel SFDA, ESMA, and municipal building code approvals extend product launch cycles by 18-24 months for new market entrants without established regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Construction Chemicals Market |
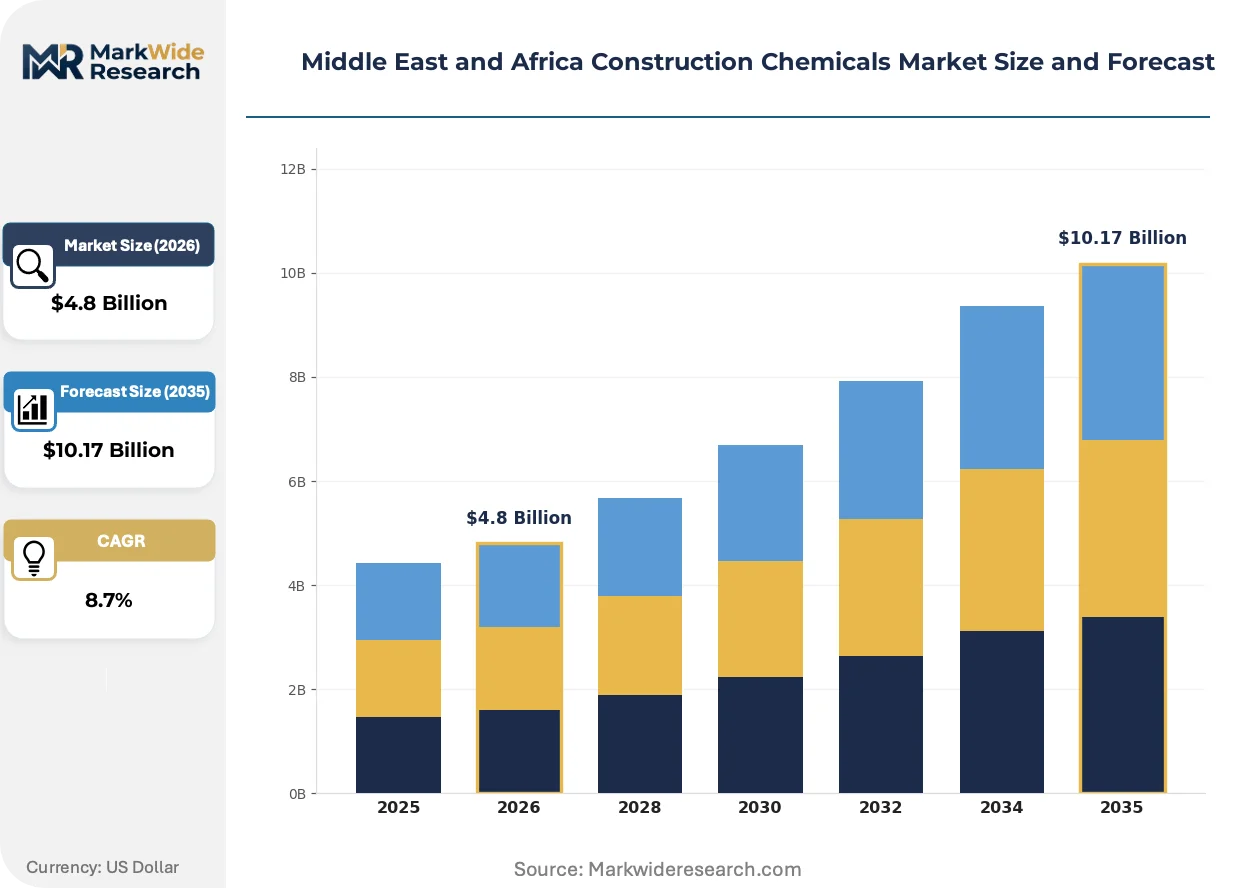
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Coatings Application: Residential Construction, Commercial Construction, Infrastructure Projects, Industrial Applications End User: Contractors, Builders, Architects, Engineers Material: Cement-based, Polymer-based, Bitumen, Others |
| Companies Covered | Fosroc Inc, Conmix, Sika AG, Ahlia Chemicals Company, Arkema, Saint-Gobain, MBCC Group, CIKO Middle East, MAPEI S.p.A., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Construction Chemicals Market Trends and Innovations
Formulation chemistry and compliance architecture are converging to reshape competitive positioning across the Middle East and Africa construction chemicals sector, with technology adoption patterns diverging by project specification intensity.
Hybrid polymer-cementitious repair systems are fragmenting traditional material categories by combining flexible polymer modification with cost-efficient cement bases. Hydrocarbon facility operators in the UAE are specifying these formulations for secondary containment and tank base applications where pure epoxy costs prove prohibitive. The technology is fragmenting specification standards, creating tiered performance categories that compress pure polymer system margins in mid-specification segments.
ESMA conformity schemes and Saudi Building Code harmonization initiatives are mandating unified testing protocols across Gulf Cooperation Council jurisdictions. This regulatory consolidation is eliminating redundant national certification requirements while elevating documentation burdens for suppliers serving multiple markets. Multi-country operators are consolidating regional testing facilities in Dubai and Riyadh to streamline compliance workflows.
Specification-driven procurement is compressing traditional distributor influence as engineering consultants and asset owners direct material selection through performance-based tender clauses. Main contractors are losing autonomy over construction chemical sourcing in high-specification UAE and Saudi projects. This pattern concentrates buying power with EPC firms and government project authorities in transport and energy verticals.
Middle East and Africa Construction Chemicals Market Segmentation
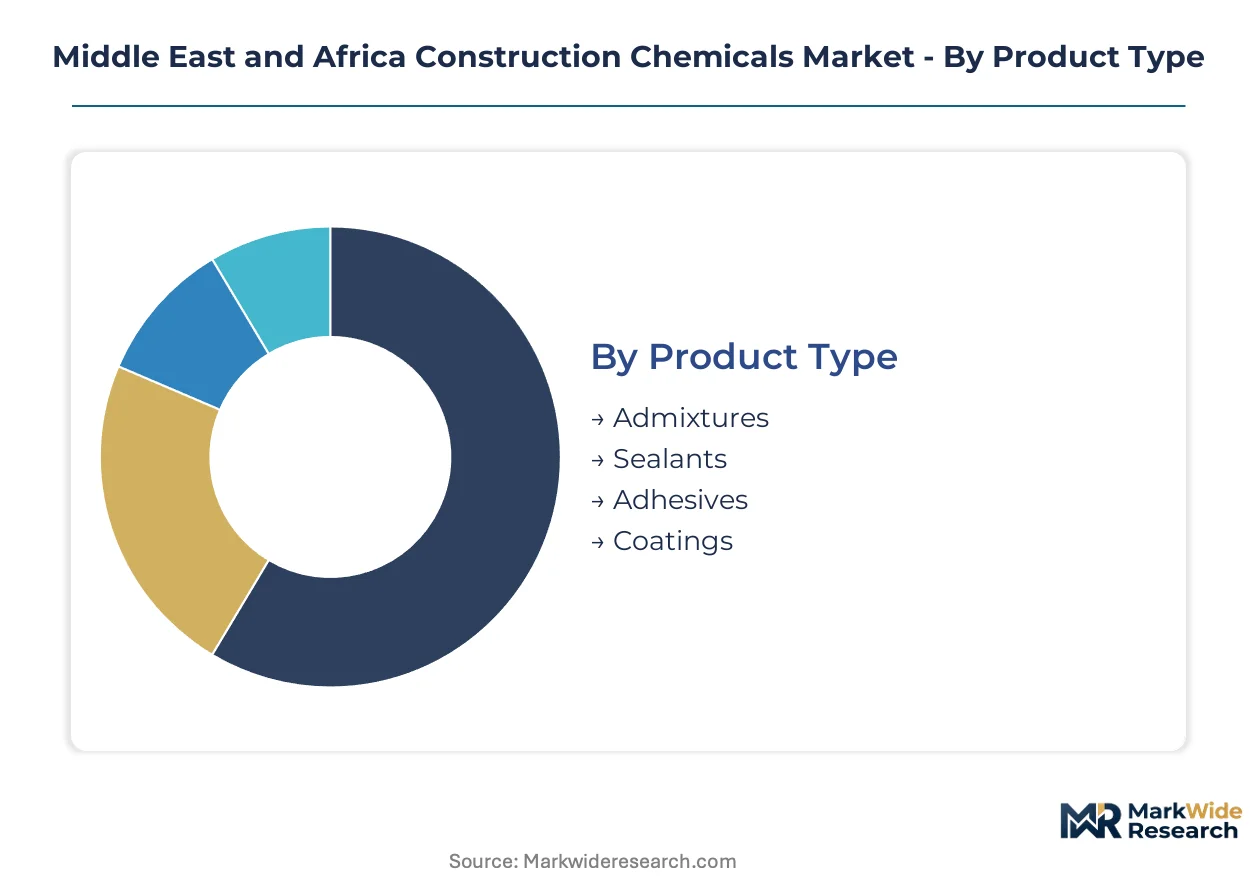
Construction chemicals in the Middle East and Africa fragment across formulation chemistry, project type, and procurement channel, with margin concentration diverging sharply between commodity admixtures and specification-driven protective systems. Understanding these segment boundaries clarifies where technical differentiation commands pricing power versus where logistics scale determines competitive survival.
Product Type:
Margin pools concentrate in polymer-modified formulations where specification premiums offset petrochemical feedstock volatility, while admixtures dominate volume throughput with thinner unit economics.
- Admixtures:Polycarboxylate ether superplasticizers and retarding agents modify cement hydration kinetics to achieve 15-40% water reduction in high-strength concrete. Gulf mega-infrastructure programs across Dubai and Abu Dhabi are specifying these formulations for transport corridor and high-rise foundations, compressing procurement cycles through ready-mix concrete channel consolidation.
- Coatings:Epoxy and polyurethane chemistries form protective barriers against chloride ion ingress and carbonation in marine and hydrocarbon facility applications. UAE specification intensity in secondary containment and tank base projects sustains margin premiums that pure cementitious systems cannot match.
- Sealants:Polyurethane and silicone formulations accommodate joint movement in high-rise curtain wall assemblies and infrastructure expansion joints.
- Adhesives:Cementitious and polymer-modified tile adhesives serve interior finishing across Saudi Arabia's residential construction corridors.
Admixtures hold installed capacity. Coatings are rotating up the share rankings on specification intensity in UAE energy infrastructure.
Application:
Project scale and specification tier create divergent procurement patterns, with infrastructure megaprojects demanding technical service depth that residential developers bypass.
- Infrastructure Projects:Transport corridors, water treatment facilities, and energy infrastructure require chloride-resistant and carbonation-protective formulations with documented performance under Gulf environmental exposure. Saudi Building Code durability mandates are elevating material compliance requirements for bridge decks and tunnel linings.
- Commercial Construction:High-rise vertical construction in Dubai and Abu Dhabi drives demand for superplasticized high-strength concrete and waterproofing membranes. Engineering consultants are directing material selection through performance-based tender clauses, compressing main contractor sourcing autonomy.
- Residential Construction:Cost-sensitive villa and apartment developments across Saudi Arabia's interior corridors favor cement-based repair mortars and standard tile adhesives.
- Industrial Applications:Hydrocarbon facility operators specify hybrid polymer-cementitious systems for secondary containment where pure epoxy costs prove prohibitive.
Commercial construction anchors current procurement volume. Infrastructure projects are climbing the fastest on Gulf mega-program expansion.
End User:
Technical decision authority is fragmenting across the project delivery chain, with specification influence migrating toward design-phase stakeholders.
- Engineers:Structural and materials engineers prescribe admixture dosages and coating specifications through performance-based contract clauses. Their authority concentrates in UAE and Saudi high-specification verticals where SFDA and ESMA compliance documentation is mandatory.
- Architects:Building envelope designers specify waterproofing and sealant systems for aesthetic and functional durability in high-rise developments.
- Contractors:Main contractors retain procurement control in mid-specification segments but are losing autonomy in transport and energy EPC contracts.
- Builders:Small-scale residential developers prioritize material cost and logistics proximity over technical service support.
Engineers hold specification authority. Contractors are rotating down the influence rankings as EPC firms consolidate procurement.
Material:
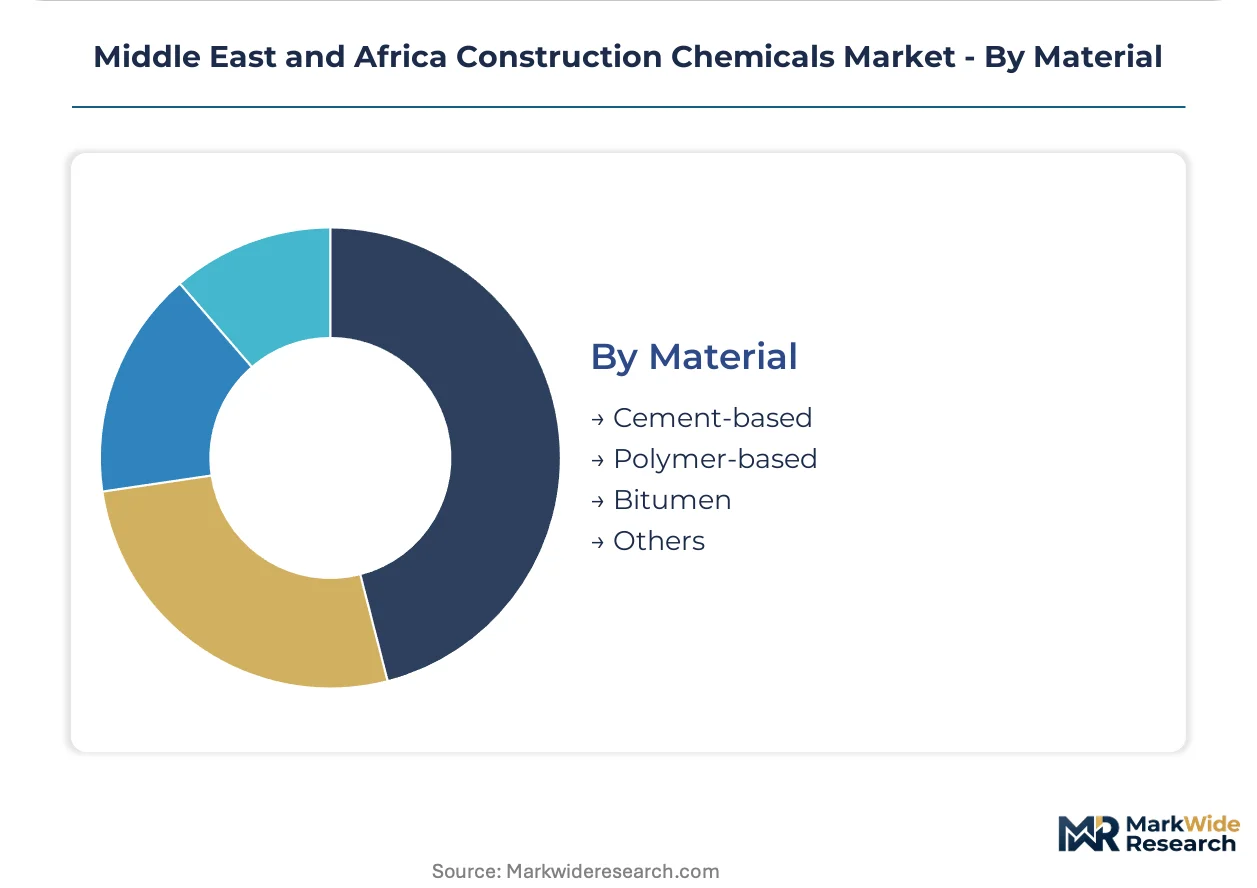
Cost-performance tradeoffs are fragmenting traditional material categories, with polymer modification penetrating segments once dominated by pure cementitious formulations.
- Polymer-based:Epoxy resins, polyurethane precursors, and acrylic dispersions deliver flexible, crack-bridging performance in waterproofing and repair applications. Petrochemical feedstock volatility compresses margin stability for regional blenders without backward integration into precursor supply.
- Cement-based:Portland cement mortars and grouts retain cost-sensitive infrastructure share but are losing ground to polymer-modified systems in high-specification vertical construction.
- Bitumen:Roofing and waterproofing membranes serve low-slope commercial applications across Gulf climates.
- Others:Silicate-based penetrants and crystalline waterproofing agents occupy niche below-grade applications.
Cement-based materials hold installed capacity. Polymer-based formulations are gaining share fastest on specification premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA material safety requirements and ESMA conformity schemes are reorganizing supplier eligibility across Gulf Cooperation Council procurement channels. Mega-infrastructure programs in transport and energy verticals are concentrating demand in specific metropolitan construction corridors.
United Arab Emirates
Dubai and Abu Dhabi anchor high-rise and transport project activity requiring chloride-resistant formulations. ESMA conformity schemes mandate unified testing protocols for construction chemical registration. The Jebel Ali industrial zone hosts blending facilities serving marine and hydrocarbon facility applications across the emirates.
Saudi Arabia
NEOM and Red Sea Project developments are specifying polycarboxylate ether superplasticizers for high-strength concrete foundations. Saudi Building Code provisions tighten material compliance requirements for structural durability. Riyadh's interior construction corridors concentrate distribution networks for cement-based repair mortars and standard tile adhesives.
Qatar
Lusail City and transport infrastructure expansions drive protective coating consumption for marine exposure conditions. Municipal building codes align with Gulf standardization harmonization initiatives for product registration. Doha's industrial area clusters technical service centers supporting hydrocarbon facility specifications.
South Africa
Water treatment and transport infrastructure programs require carbonation-protective formulations for concrete durability. National building regulations incorporate durability mandates for structural elements in coastal exposure zones. Johannesburg and Cape Town metropolitan construction corridors concentrate ready-mix concrete channel procurement.
Egypt
New Administrative Capital and Suez Canal Economic Zone developments are expanding specification-driven procurement for vertical construction. National standards organizations are adopting testing protocols harmonized with Gulf Cooperation Council frameworks. Cairo-Giza metropolitan construction anchors admixture volume consumption for high-rise foundations.
Middle East and Africa Construction Chemicals Market Competitive Landscape
Listed leaders compete with private specialists across certification and technical service dimensions in the Middle East and Africa construction chemicals sector. The vendor base organizes around three strategic archetypes: Swiss-heritage premium positioning specialists, Gulf-based manufacturing operators with interior distribution control, and European chemical conglomerates with polymer science capabilities. Consolidation pressures favor acquisition of ISO 9001-certified local blenders sidelined from public tender eligibility. Geographic expansion into East Africa technical service deserts represents the dominant competitive move alongside formulation localization investments.
Within the premium-tier positioning archetype, Sika AG leverages Swiss technical heritage to sustain specification premiums in Gulf waterproofing segments. Fosroc Inc anchors regional manufacturing presence through Jebel Ali facilities and exemplifies the Gulf-based operator model with East Africa technical service expansion. Ahlia Chemicals Company occupies the logistics proximity tier, controlling distribution networks within Saudi Arabia's interior construction corridors. These three players represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Fosroc Inc |
| Conmix |
| Sika AG |
| Ahlia Chemicals Company |
| Arkema |
| Saint-Gobain |
| MBCC Group |
| CIKO Middle East |
| MAPEI S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day formulation registration timelines at SFDA and ESMA compress inventory turns and concentrate pricing power with Gulf-based blenders holding localized testing infrastructure. This lead-time band rewards suppliers who pre-position blending capacity in Jebel Ali and Riyadh while penalizing import-dependent competitors with working capital strain and tender disqualification risk.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-certified suppliers and uncertified local blenders sidelined from Saudi public tenders. Three-tier pricing structure across premium certified, standard compliant, and economy unregistered levels tracks specification intensity in UAE hydrocarbon projects. Cost compression in polymer-modified coatings is intensifying because petrochemical feedstock volatility erodes margin buffers for non-integrated blenders. Residential construction buyers in Saudi Arabia's interior corridors exhibit highest price sensitivity, while EPC contractors in Dubai transport projects prioritize performance documentation over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites epoxy resin and polyurethane precursor flows from European and Asian petrochemical hubs to Gulf blending facilities. Manufacturing concentrates in the United Arab Emirates, Saudi Arabia, and Qatar, with Jebel Ali and Riyadh anchoring formulation capacity. Raw material dependencies center on naphtha-derived epichlorohydrin, aromatic isocyanates, and polycarboxylate ether monomers from specialized chemical producers. Single-source vulnerability in specialty amine hardeners for marine coatings creates supply continuity exposure during regional logistics disruptions. Distribution runs through ready-mix concrete channel consolidation in metropolitan construction corridors and technical service-direct models for hydrocarbon facility specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa construction chemicals sector rewards suppliers who control formulation chemist talent pools and localized testing infrastructure, with Gulf registration complexity creating durable capability moats around established operators.
For Market Incumbents: Consolidate distribution networks in Saudi Arabia's interior corridors through acquisition of ISO 9001-certified local blenders facing tender exclusion, while deepening backward integration into polycarboxylate ether monomer supply to offset petrochemical feedstock volatility. Prioritize East Africa technical service center expansion in Kenya and Ethiopia to capture first-mover advantage in infrastructure pipeline markets lacking established construction chemical distribution. For New Entrants and Emerging Players: Anchor in East Africa's technical service deserts, specifically Kenya's transport infrastructure and Ethiopia's water treatment programs, where incumbent presence remains thin and specification intensity is climbing fastest. Penetrate through performance-based tender compliance partnerships with engineering consultants rather than main contractor channel contests, leveraging carbon-content disclosure preparation as a differentiated entry wedge ahead of anticipated Gulf harmonization mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from European chemical conglomerates seeking to divest non-core construction chemical divisions lacking Gulf-specific registration infrastructure and localized formulation capabilities. Long-term viability hinges on regulatory compliance asset intensity rather than commodity scale, with acquisition premiums justified by SFDA and ESMA approval timelines that deter de novo market entry. Monitor Gulf standardization harmonization announcements as the critical signal for low-carbon admixture re-engineering contract inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive epichlorohydrin and isocyanate sourcing insulates margin stability from crude oil volatility. |
| East Africa Technical Service Expansion | Kenya and Ethiopia infrastructure pipelines lack established distribution, creating first-mover positioning. |
| ISO 9001 Certification Arbitrage | Acquisition of sidelined local blenders secures interior Saudi distribution control for public tender eligibility. |
| Carbon-Content Disclosure Preparation | Low-carbon admixture development contracts capture specification premium ahead of Gulf mandate implementation. |
| Regional Testing Facility Consolidation | Dubai and Riyadh hub consolidation streamlines multi-jurisdiction SFDA, ESMA, and municipal compliance workflows. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the Middle East and Africa construction chemicals value chain, including ready-mix concrete procurement managers, EPC contractor materials engineers, SFDA regulatory affairs specialists, and hydrocarbon facility maintenance directors. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical conglomerates, Gulf Cooperation Council standardization harmonization documents, and ESMA conformity scheme technical bulletins. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry and project type segments.
Across the analysis window, projections integrated polycarboxylate ether superplasticizer consumption patterns in Gulf mega-infrastructure programs, polymer coating specification intensity in UAE marine applications, and cement-based material displacement trajectories in Saudi vertical construction. Segmentation dimensions spanned formulation chemistry tier, project specification intensity, procurement channel structure, and regional regulatory cluster. CAGRs were derived from installed capacity expansion announcements, tender pipeline tracking, and historical consumption elasticity to construction output indices.
Material uncertainties — petrochemical feedstock volatility, Gulf standardization harmonization timing, and East Africa infrastructure financing commitment — sit outside the modeled envelope and could revise trajectory assumptions. Practitioners should keep alternative scenarios live as carbon-content disclosure mandates and formulation chemist labor market conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Electroplating Chemicals Market
Chemicals
Europe Methanol Market
Chemicals
Hydrogen Chloride Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Glycerol Carbonate Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Europe Biguanide Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Butylated Triphenyl Phosphate Market