
 Iscotrizinol Market | 2026-2036
Iscotrizinol Market Size, Share, and Industry Trends Forecast 2026-2036
Iscotrizinol Market Analytics
Market Context with Strategic Players
Capital-intensity divergence between integrated multinationals and specialty chemical suppliers is rotating competitive dynamics across the iscotrizinol supply base. BASF SE leverages its global aromatics and performance chemicals infrastructure to sustain backward-integrated production of advanced UV filter intermediates. Evonik Industries AG anchors its position through high-purity specialty chemical manufacturing protocols that dominate pharmaceutical-grade iscotrizinol supply. Rianlon Corporation competes on cost-optimized antioxidant and light stabilizer platforms that extend into Asian sunscreen manufacturing clusters.
Technical Definition and Structural Segments
Iscotrizinol is a lipophilic organic UV filter compound, structurally classified as a triazine derivative with absorption maxima in the UVA-II and UVB ranges, synthesized through condensation reactions of cyanuric chloride with aromatic amines and phenolic intermediates. The compound functions primarily as a photostabilizer and broad-spectrum absorber in topical formulations, protecting against solar-induced skin damage and premature photaging. Lotions and creams command the largest product type share due to established consumer familiarity and ease of formulation integration, while sprays represent the fastest-growing format as aerosol and pump-dispense technologies improve uniform skin coverage. Sunscreens anchor application demand through regulatory mandates for broad-spectrum protection labeling, whereas dermatology channels capture concentrated margin pools through prescription-strength and post-procedure formulations.
Regulatory Framework and Outlook
REACH in Europe and China's SAMR cosmetics supervision framework impose stringent safety dossier and environmental fate testing requirements on organic UV filters including iscotrizinol, elevating barriers for non-integrated suppliers. The FDA in the United States maintains a narrower approved UV filter monograph list, creating divergent formulation strategies between regulatory jurisdictions that fragment product development pipelines. Stakeholders must monitor pending regulatory reviews of additional organic UV absorbers and align R&D investments with jurisdiction-specific approval pathways rather than assuming harmonized global acceptance.
Market Dynamics
REACH dossier requirements and China's SAMR cosmetics supervision regulations are compressing the supplier base for organic UV filters, forcing formulators to consolidate procurement around qualified chemical manufacturers with validated safety data packages.
Growth Catalysts
- Broad-spectrum labeling mandates:Sunscreen regulations in Australia, the United States, and South Korea now require documented UVA-II and UVB protection, elevating demand for photostable triazine derivatives that deliver dual-range absorption without photodegradation.
- Dermatology channel expansion:Post-procedure skincare protocols in Germany and Japan are incorporating prescription-strength UV filters into recovery regimens, creating qualified demand pools with concentrated margin structures.
- Aerosol formulation advances:Pump-dispense and bag-on-valve technologies are improving uniform iscotrizinol distribution across skin surfaces, accelerating spray format adoption in beach and sport sunscreen segments.
Market Restraints
- Cyanuric chloride feedstock volatility:Triazine synthesis depends on chlorinated intermediate supply concentrated in Chinese and German chemical clusters, exposing producers to input cost swings and force majeure disruptions.
- FDA monograph fragmentation:The narrower approved UV filter list in the United States forces manufacturers to maintain parallel formulation pipelines, elevating R&D overhead and delaying product launches.
- Inorganic mineral substitution:Zinc oxide and titanium dioxide nanoparticles are capturing clean-label preference in premium organic skincare, constraining volume growth for synthetic organic absorbers in prestige channels.
Strategic Opportunities
- India personal care penetration:Domestic cosmetics manufacturers in Maharashtra and Gujarat are qualifying regional chemical suppliers for UV filter feedstock as BIS standards align with international safety protocols.
- Blue light protection positioning:Visible light filtering claims are emerging in digital-age skincare marketing, creating application white space for iscotrizinol formulations targeting screen-exposed urban consumers.
- Biodegradability certification:Reef-safe and aquatic toxicity standards in Hawaii, Palau, and the EU are creating differentiated positioning for UV filters with validated environmental fate profiles.
Industry Challenges
- Analytical method standardization:Inconsistent photostability testing protocols across ECHA, FDA, and NMPA guidelines force manufacturers to run multiple validation studies, compressing development timelines.
- Formulation compatibility complexity:Lipophilic triazine derivatives require precise emulsifier matching with modern clean-beauty bases, demanding reformulation cycles that strain technical service resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iscotrizinol Market |
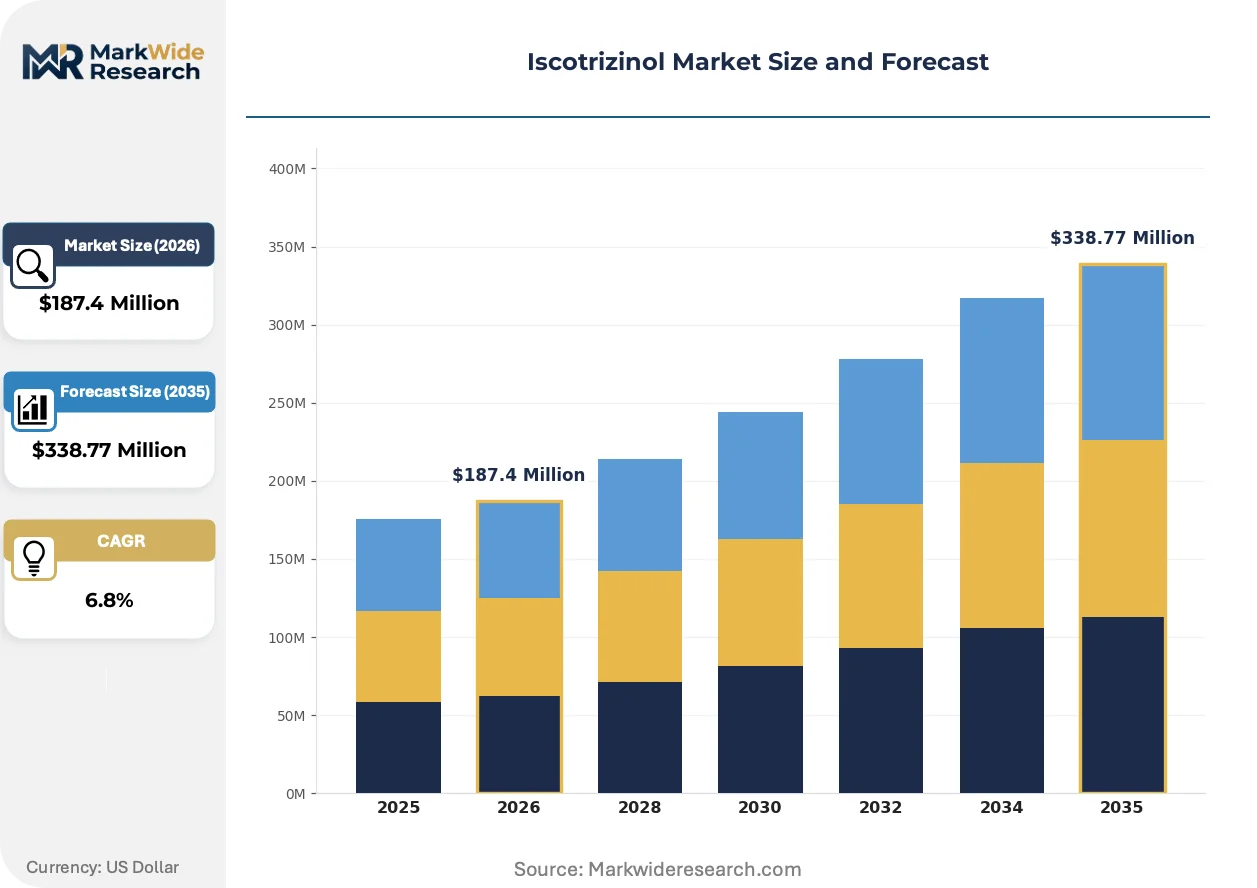
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Creams, Gels, Sprays Application: Cosmetics, Dermatology, Pharmaceutical, Sunscreens End User: Retail Consumers, Dermatologists, Cosmetics Manufacturers, Hospitals Distribution Channel: Online Stores, Pharmacies, Supermarkets, Beauty Salons |
| Companies Covered | Georges Walther, Chemspec Chemicals, Aurocos Speciality Chemicals, Coskin Specialities, BASF SE, Everlight Chemical Industrial Corporation, Evonik Industries AG, Rianlon Corporation, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iscotrizinol Market Evolving Landscape
Encapsulation technologies and regulatory data requirements are restructuring how UV filter suppliers demonstrate performance and safety, shifting competitive advantage toward integrated manufacturers with in-house toxicology and photostability capabilities.
Microencapsulation of iscotrizinol using silica and lipid-shell matrices is miniaturizing particle distribution while maintaining photoprotection efficacy. Korean and German formulators are adopting these systems for transparent-finish daily wear sunscreens. The technology is miniaturizing the trade-off between high SPF performance and cosmetic elegance that previously constrained organic UV filter penetration in facial skincare.
REACH authorization processes and candidate list updates are extending safety dossier timelines for triazine-class UV absorbers. ECHA's evolving endocrine disruptor assessment criteria are forcing suppliers to generate additional mammalian toxicity data. European formulators are responding by pre-qualifying alternative photostabilizers and accelerating inventory turnover to minimize regulatory stranded-asset risk.
Direct-to-dermatologist sampling programs are displacing traditional retail channel marketing for clinical-grade sunscreen lines. Specialty skincare brands are unbundling professional education from consumer advertising, concentrating technical training resources on prescribing physicians in Seoul, Munich, and São Paulo. This channel pivot is most visible in post-procedure care segments where formulation credentials outweigh mass-market brand recognition.
Iscotrizinol Market Segmentation
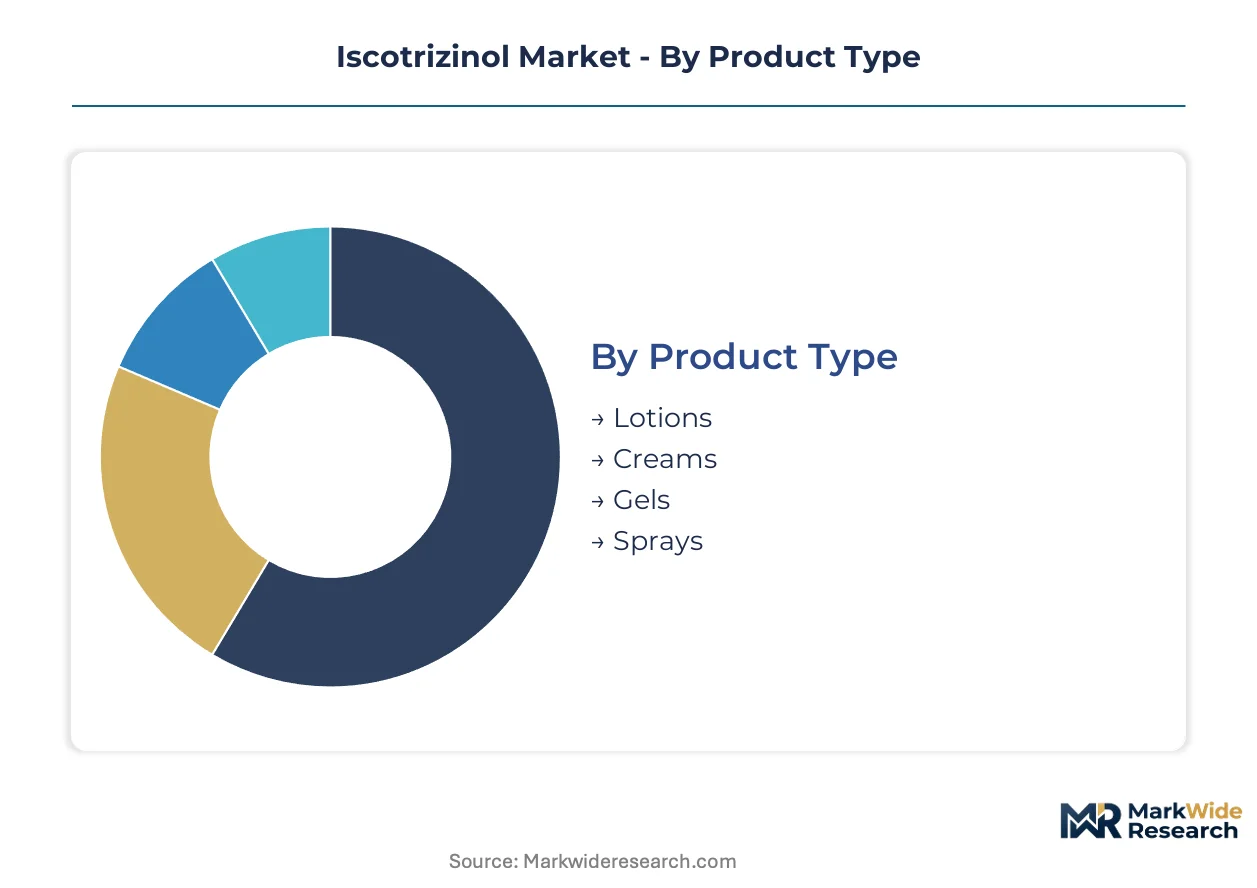
Iscotrizinol procurement patterns diverge sharply across formulation formats and channel structures, with substitution risk from mineral UV filters reshaping investment priorities in specific segments. Formulators must align R&D budgets with segment-specific performance requirements and regulatory exposure profiles.
Product Type:
Sprays and gels face the most acute substitution pressure from zinc oxide nanoparticle formulations, whereas lotions and creams defend share through established consumer habits and regulatory familiarity.
- Lotions:Emulsion-based vehicles with 15-30% oil phase content enable stable iscotrizinol dispersion without photodegradation. Demand concentrates in German and Australian mass-market sunscreens where SPF 50+ labeling mandates require proven photostability dossiers. Lotions retain volume leadership; sprays hold the steepest expansion curve.
- Creams:Thicker rheology profiles with higher emollient loads suit facial skincare and post-procedure dermatology protocols. Japanese and South Korean cosmetics manufacturers specify cream bases for premium anti-aging lines where cosmetic elegance commands price premiums.
- Gels:Water-based matrices with carbomer or xanthan structuring agents appeal to male grooming and sport sunscreen segments in Brazil and Spain. Alcohol-containing gel variants accelerate dry-down but complicate iscotrizinol solubility.
- Sprays:Aerosol and bag-on-valve delivery systems from Korean and German packaging suppliers improve uniform skin coverage for beach and outdoor activity use cases. Pump-dispense formats bypass propellant regulatory restrictions in EU and US markets.
Lotions command the largest production volumes; sprays are climbing the fastest as aerosol technology matures.
Application:
Margin structures vary threefold across applications, with dermatology and pharmaceutical channels capturing concentrated value pools through prescription requirements and clinical validation protocols.
- Sunscreens:Broad-spectrum UVA-II and UVB protection labeling mandates in Australia, South Korea, and the United States anchor baseline demand for photostable triazine derivatives. Regulatory compliance costs favor suppliers with pre-validated safety dossiers.
- Cosmetics:Daily wear facial products with SPF 15-30 positioning integrate iscotrizinol for incidental sun exposure protection. French and Italian prestige brands specify low-whitening transparent finishes that microencapsulated iscotrizinol delivers.
- Dermatology:Post-procedure recovery protocols in German and Japanese clinics incorporate prescription-strength UV filters with documented efficacy against photodamage. Clinical credentialing requirements create qualified demand pools with concentrated margins.
- Pharmaceutical:Drug-sunscreen combination products for photosensitivity disorders require pharmaceutical-grade iscotrizinol with validated impurity profiles. Evonik Industries and specialized GMP manufacturers dominate this specification tier.
Sunscreens retain volume leadership; dermatology holds the steepest expansion curve.
End User:
Procurement authority is fragmenting across the value chain, with cosmetics manufacturers consolidating supplier relationships while retail channels fragment into specialty and mass-market tiers.
- Cosmetics Manufacturers:Integrated formulators in China, Germany, and South Korea qualify regional chemical suppliers for iscotrizinol feedstock through audited safety data packages. Direct procurement contracts now span 3-5 year horizons to lock in REACH-compliant supply.
- Retail Consumers:Mass-market purchasing decisions in US and Australian drugstores remain price-sensitive, with SPF claims and brand recognition outweighing active ingredient specifications for most buyers.
- Dermatologists:Prescribing physicians in Seoul, Munich, and São Paulo drive clinical-grade sunscreen adoption through professional sampling programs that bypass traditional retail marketing.
- Hospitals:Institutional procurement in Japanese and French healthcare systems specifies bulk sunscreen for outpatient phototherapy units and burn ward protocols.
Cosmetics manufacturers retain volume leadership; dermatologists hold the steepest expansion curve.
Distribution Channel:
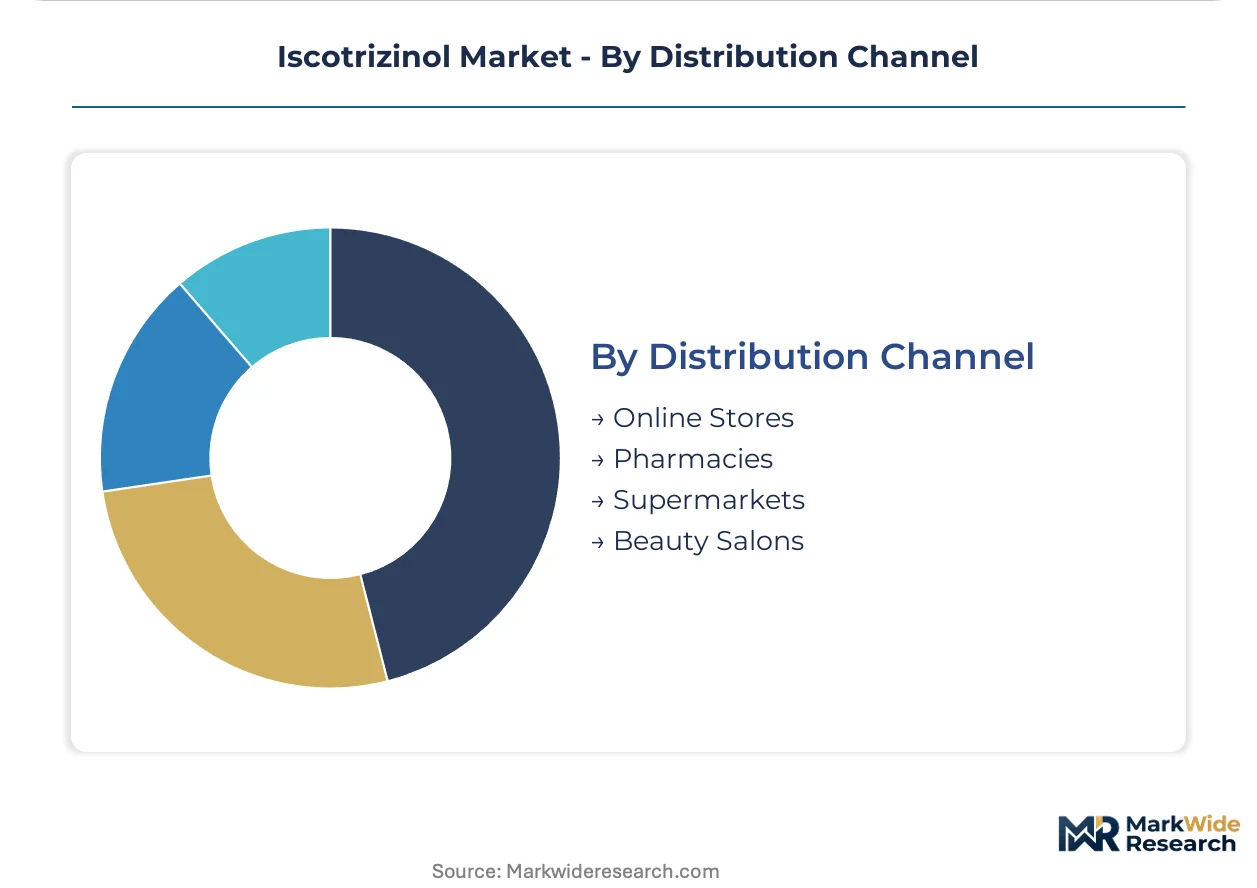
Channel mix is displacing toward digital platforms in urban markets while pharmacies defend professional credibility in clinical and premium segments.
- Pharmacies:Licensed dispensaries in Germany, France, and Spain anchor prescription and pharmacy-only sunscreen sales, with trained staff influencing ingredient-conscious purchasing decisions.
- Online Stores:Direct-to-consumer platforms and marketplace aggregators in China and the United States capture growing share of replenishment purchases and subscription sunscreen models.
- Supermarkets:Mass-market retail in Australia, Brazil, and the UK drives seasonal volume spikes through promotional pricing and multi-pack formats for family beach use cases.
- Beauty Salons:Professional service providers in Italy and South Korea upsell post-treatment skincare regimens with clinically positioned UV protection as part of facial service packages.
Pharmacies retain volume leadership; online stores hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, China, and South Korea consume iscotrizinol through distinct formulation paradigms—clinical dermatology, mass-market manufacturing scale, and K-beauty cosmetic elegance respectively—while the United States and Japan operate under narrower regulatory umbrellas that compress approved UV filter lists.
Germany
Post-procedure skincare protocols in Munich and Berlin clinics drive prescription-strength UV filter demand with concentrated margin structures. REACH authorization processes through ECHA impose extended safety dossier timelines on triazine-class absorbers. The North Rhine-Westphalia chemical cluster hosts backward-integrated manufacturers supplying validated photostability data packages to domestic formulators.
China
Domestic cosmetics manufacturers in Shanghai and Guangzhou are qualifying regional chemical suppliers for iscotrizinol feedstock as SAMR cosmetics supervision regulations tighten. NMPA-aligned safety protocols now require environmental fate testing that elevates barriers for non-integrated suppliers. The Yangtze River Delta concentration of sunscreen OEMs is absorbing microencapsulated UV filter imports from Korean packaging technology partners.
South Korea
Seoul-based K-beauty brands specify transparent-finish daily wear sunscreens that integrate microencapsulated iscotrizinol for cosmetic elegance without whitening. MFDS broad-spectrum labeling mandates align with Australian and US requirements, simplifying export formulation pipelines. The Gyeonggi-do cosmetics manufacturing corridor is expanding aerosol and pump-dispense capacity for sport sunscreen segments.
United States
FDA's narrower approved UV filter monograph list forces manufacturers to maintain parallel formulation pipelines distinct from European and Asian product architectures. California's reef-safe legislation and Hawaii's aquatic toxicity standards are creating differentiated positioning demands for environmental fate documentation. The New Jersey-Pennsylvania chemical corridor supplies pharmaceutical-grade specifications for photosensitivity disorder applications.
Japan
Tokyo and Osaka dermatology clinics incorporate prescription-strength UV filters into post-procedure recovery regimens with documented efficacy requirements. METI-aligned standards for organic UV absorbers emphasize photostability validation that favors suppliers with in-house toxicology capabilities. The Kansai region's prestige skincare manufacturers specify low-whitening finishes that microencapsulated triazine derivatives deliver.
Iscotrizinol Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the iscotrizinol supply base, with capital-intensity divergence rotating competitive dynamics across procurement channels. The upper tier commands REACH-compliant safety dossiers and captive cyanuric chloride feedstock access, while specialists compete on cost-optimized platforms and regional qualification speed. Three archetypes dominate: backward-integrated multinationals with aromatics infrastructure, high-purity specialty chemical manufacturers with pharmaceutical-grade protocols, and Asian cost-optimized suppliers with antioxidant and light stabilizer extensions. Capacity expansion and strategic partnerships represent the dominant competitive moves, as non-integrated players seek feedstock security and integrated players pursue formulation technology alliances.
Among European integrated chemical conglomerates, BASF SE and Evonik Industries AG occupy positions that exemplify the backward-integrated and high-purity archetypes respectively, with the former leveraging global aromatics infrastructure and the latter anchoring pharmaceutical-grade supply through specialty manufacturing protocols. Rianlon Corporation represents the Asian cost-optimized tier, competing on antioxidant and light stabilizer platforms that extend into regional sunscreen manufacturing clusters.
| Leading Market Players |
|---|
| Georges Walther |
| Chemspec Chemicals |
| Aurocos Speciality Chemicals |
| Coskin Specialities |
| BASF SE |
| Everlight Chemical Industrial Corporation |
| Evonik Industries AG |
| Rianlon Corporation |
| Clariant AG |
| Others |
Value Network & Pricing Analysis
Mineral UV filter substitution in prestige skincare channels is simultaneously redrawing supplier geography and compressing synthetic organic absorber margins, as zinc oxide nanoparticle adoption in French and Italian prestige brands forces triazine derivative producers to defend price positions through certification-tier differentiation rather than volume scale.
Pricing Analysis
Long-term offtake contracts spanning 3-5 years dominate procurement between REACH-compliant manufacturers and German cosmetics formulators, creating pricing stratification across pharmaceutical-grade, technical-grade, and feedstock-tier specifications. Price differentiation hinges on validated safety dossier completeness and captive cyanuric chloride access, with spot-market spot purchases from non-integrated Chinese suppliers facing steepest compression due to NMPA environmental fate testing mandates. Cost compression in economy-grade feedstock tiers is intensifying as South Korean OEMs consolidate supplier relationships. Cosmetics manufacturers with direct procurement authority exhibit lowest price sensitivity; mass-market retail channels in Australia and Brazil remain most vulnerable to promotional pricing cycles.
Supply Chain Analysis
China and Germany anchor cyanuric chloride production for triazine synthesis, with the Yangtze River Delta and North Rhine-Westphalia chemical clusters feeding downstream UV filter manufacturers across Asia-Pacific and Europe. Feedstock supply draws from chlorinated intermediate production concentrated in these jurisdictions, tethering iscotrizinol cost structures to Chinese petrochemical pricing and German energy input volatility. Single-source vulnerability in cyanuric chloride supply exposes formulators to force majeure disruptions from regional environmental compliance shutdowns. Distribution runs through qualified chemical supplier networks with audited REACH and SAMR safety packages, bypassing commodity spot markets for regulated end-uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iscotrizinol procurement operates as a regulatory-moat market where REACH-compliant safety dossiers create switching costs that entrench qualified suppliers against price-based competition from unvalidated entrants.
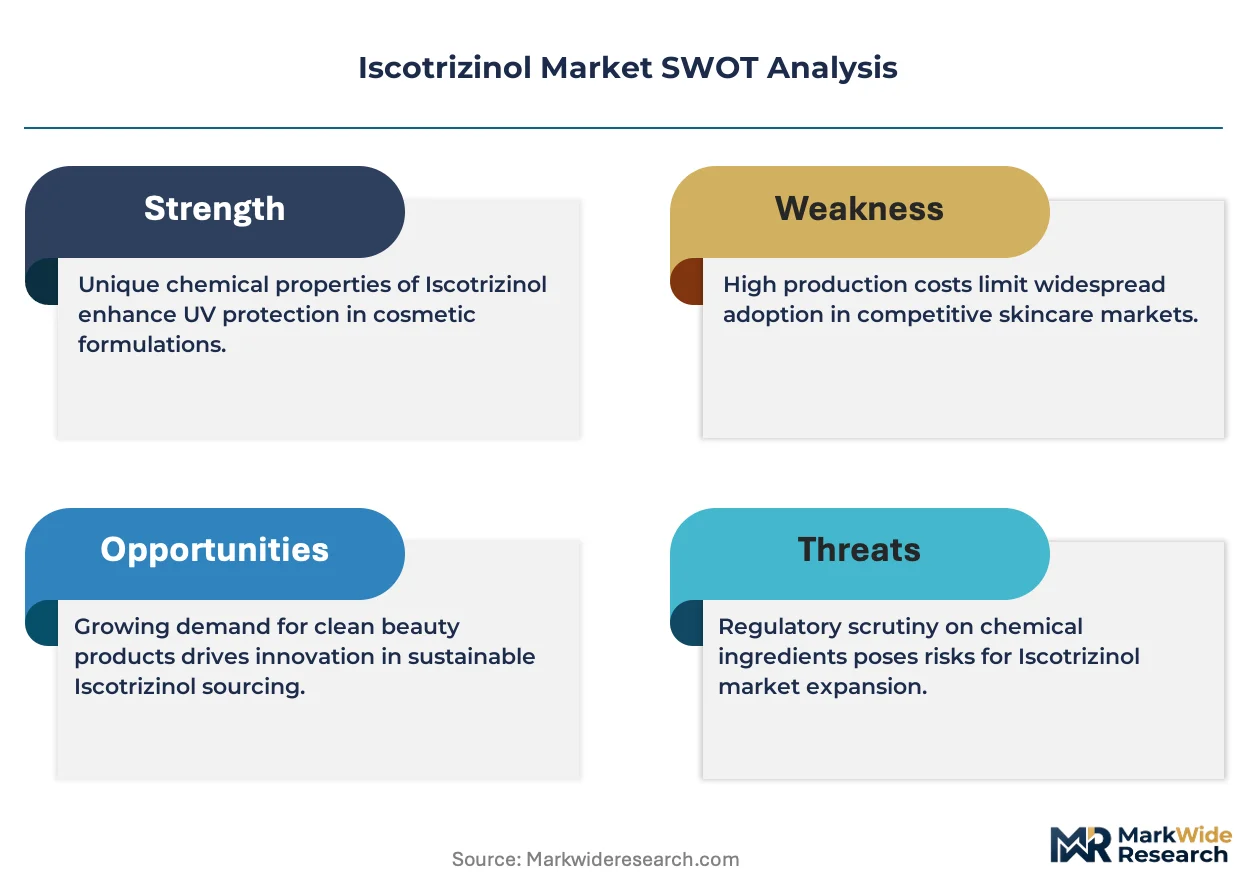
For Market Incumbents: Consolidate cyanuric chloride feedstock security through backward integration or long-term supply agreements with German and Chinese chemical clusters, while accelerating microencapsulation R&D partnerships with Korean packaging technology providers to defend margin positions against mineral UV filter substitution in prestige channels. Pre-qualify alternative photostabilizers to minimize regulatory stranded-asset risk from ECHA endocrine disruptor assessments. For New Entrants and Emerging Players: BIS certification fast-track for Indian domestic cosmetics manufacturers in Maharashtra and Gujarat offers the most penetrable entry vector, as regional formulators seek qualified local suppliers aligned with international safety protocols. Target spray-format sport sunscreen segments where aerosol technology partnerships with Korean packaging suppliers enable differentiation without competing directly on photostability dossier depth. Pursue direct-to-dermatologist sampling programs in São Paulo and Seoul to bypass established retail channel barriers. For Investors and Strategic Acquirers: The market sits at a regulatory-consolidation phase that favors integrated manufacturers with captive feedstock and in-house toxicology capabilities over non-integrated specialists. Long-term viability over the next decade rests on ECHA authorization timelines and SAMR enforcement intensity. Acquisition targets should demonstrate validated environmental fate profiles and existing relationships with German or South Korean formulators. The signal to watch is NMPA approval pathway acceleration for additional organic UV absorbers, which would signal expanded addressable market for compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyanuric Chloride | Captive feedstock supply secures margin defense against Chinese petrochemical price volatility. |
| Microencapsulation Technology Partnership | Korean silica-shell matrices enable transparent-finish positioning in K-beauty daily wear segments. |
| REACH-Compliant Safety Dossier Expansion | Pre-validated toxicology packages accelerate qualification with German dermatology formulators. |
| Direct-to-Dermatologist Sampling Program | Professional channel pivot in Munich and Seoul bypasses mass-market retail margin compression. |
| Biodegradability Certification Investment | Reef-safe validation aligns with Hawaii and EU aquatic toxicity standards for premium positioning. |
Research Methodology
A spread of perspectives from plant managers at triazine derivative manufacturers, procurement leads at South Korean cosmetics OEMs, distribution channel partners in German chemical supply, and technical R&D directors at encapsulation technology providers converged on the working assumptions that structure this analysis. Primary interview data combined with customs and trade flow records, ECHA registration dossiers, SEC 10-K filings from listed chemical conglomerates, and NMPA cosmetics supervision bulletins enabled bottom-up and top-down triangulation of volume and value estimates.
Segmentation dimensions modeled span product type (lotions, creams, gels, sprays), application tier (sunscreens, cosmetics, dermatology, pharmaceutical), and regional regulatory cluster (REACH-aligned Europe, SAMR-governed China, FDA-monograph United States, MFDS-mandated South Korea) across the projection horizon. CAGRs derived from time-series analysis of qualified supplier capacity additions, formulator procurement contract tenors, and regulatory approval pathway velocities. Industry-specific forecast inputs include photostability testing protocol standardization timelines and microencapsulation technology adoption curves in Korean and German formulator pipelines.
Underlying assumptions cover REACH authorization continuity, cyanuric chloride feedstock availability, and mineral UV filter substitution rates in prestige channels, with deviation risk concentrated in ECHA endocrine disruptor reclassification and SAMR enforcement intensity shifts. Recalibration cycles align with material shifts in regulatory list updates, force majeure events in chlorinated intermediate supply, and breakthrough mineral filter transparency technologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Ethyl Chloride Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Power Plant Chemicals Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Triethylaluminum Market
Chemicals
Roofing Chemical Market
Chemicals
Immunochemicals Market
Chemicals
Potassium Permanganate Market
Chemicals
Chemical Distribution Market
Chemicals
Hexamine Market
Chemicals
Potassium Fluoride Market