
 Fluorochemicals Market | 2026-2036
Fluorochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorochemicals Market Analysis
Chinese fluorochemical producers is expanding anhydrous hydrogen fluoride capacity to serve downstream refrigerant and polymer demand. Arkema leverages integrated fluorogas-to-polymer operations across its southern France and Changshu, China manufacturing bases. Daikin Industries, Ltd. anchors fluoropolymer supply for semiconductor cleanroom infrastructure through its global resin production network. Gujarat Fluorochemicals Limited specializes in captive chlorodifluoromethane and tetrafluoroethylene supply for domestic refrigerant and polymer markets.
Fluorochemicals encompass organic and inorganic compounds containing carbon-fluorine bonds, typically manufactured through electrochemical fluorination or hydrofluoric acid-based halogen exchange reactions, valued for thermal stability, chemical resistance, and dielectric properties in extreme environments. Fluoropolymers command premium pricing in aerospace wire insulation and medical implant applications where thermal degradation thresholds exceed standard polymer limits. Refrigerant-grade hydrofluorocarbons face structural contraction under phasedown mandates, while hydrofluoroolefins capture replacement demand in automotive and HVAC retrofit channels.
The US EPA enforces Significant New Alternatives Policy restrictions on high-global-warming-potential refrigerants, compelling OEMs to reformulate cooling systems. The EU F-Gas Regulation mandates stepped reductions in fluorinated gas quotas, redirecting investment toward low-global-warming-potential chemistries. China's Ministry of Ecology and Environment implements dual carbon goals that constrain coal-powered hydrofluoric acid production, tightening feedstock availability. Stakeholders must track regulatory divergence across Washington, Brussels, and Beijing to align product portfolios with divergent compliance timelines and phaseout velocities.
Market Dynamics
The fluorochemicals sector is undergoing a forced chemistry transition as the Kigali Amendment and parallel national regulations systematically dismantle hydrofluorocarbon production quotas, compelling manufacturers to rebuild supply chains around hydrofluoroolefin architectures while semiconductor fabs in Taiwan and South Korea absorb premium volumes of high-purity etching gases.
Growth Catalysts
- Semiconductor fabrication expansion:Taiwan and South Korea fabs are scaling consumption of high-purity fluorinated etching gases for advanced node production, creating dedicated demand channels that bypass commoditized refrigerant markets.
- EU F-Gas Regulation phase-down:The mandated stepped reduction in fluorinated gas quotas is redirecting capital toward low-global-warming-potential chemistries, accelerating hydrofluoroolefin capacity buildouts across signatory nations.
- Medical implant-grade fluoropolymer demand:Aerospace wire insulation and biocompatible implant applications command thermal degradation thresholds exceeding standard polymer limits, sustaining premium pricing power for specialized resin grades.
Market Restraints
- Feedstock concentration risk:Zhejiang and Shandong provinces in China host the bulk of global hydrofluoric acid output, creating single-source dependency for anhydrous hydrogen fluoride feedstock.
- Coal-powered production constraints:China's Ministry of Ecology and Environment dual carbon goals are tightening hydrofluoric acid availability by constraining coal-powered manufacturing capacity.
- Refrigerant-grade HFC structural contraction:Phasedown mandates under the Kigali Amendment and US EPA Significant New Alternatives Policy are compressing addressable volume for legacy hydrofluorocarbon chemistries.
Strategic Opportunities
- Hydrofluoroolefin automotive retrofit channels:Automotive and HVAC service markets are capturing replacement demand as hydrofluorocarbon inventories deplete, creating aftermarket chemistry transition opportunities.
- Electrochemical fluorination technology convergence:Advanced electrochemical fluorination processes are enabling higher-purity gas production for semiconductor applications, opening specialized supply relationships with Taiwan and South Korea fabs.
- Captive chlorodifluoromethane integration:Domestic refrigerant and polymer markets in India are supporting backward integration into tetrafluoroethylene supply, insulating participants from feedstock volatility.
Industry Challenges
- Regulatory divergence complexity:Stakeholders must simultaneously track Washington's EPA restrictions, Brussels' F-Gas quotas, and Beijing's dual carbon enforcement, each with non-aligned compliance timelines.
- High-purity certification timelines:Semiconductor-grade fluorinated gas qualification requires extended fab validation cycles, compressing effective commercialization windows for new chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorochemicals Market |
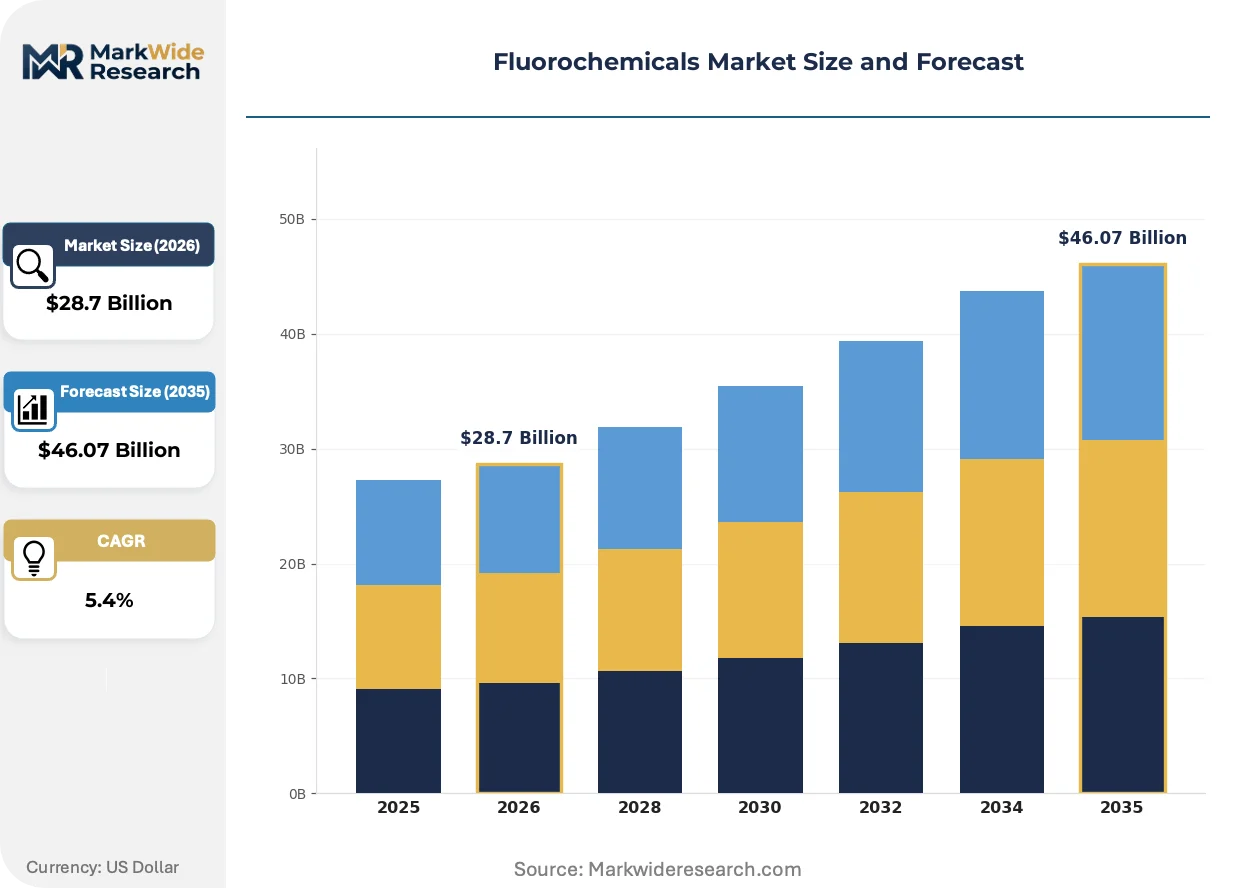
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoropolymers, Fluoroelastomers, Hydrofluoric Acid, Refrigerants Application: Aerospace, Automotive, Electronics, HVAC End User: Manufacturers, Contractors, OEMs, Distributors Delivery Mode: Bulk, Canisters, Fragrance Mixtures, Specialty Packaging |
| Companies Covered | Arkema, DuPont de Nemours, Inc., 3M Company, AGC Group, Solvay SA, Daikin Industries, Ltd., Honeywell International Inc., Gujarat Fluorochemicals Limited, The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorochemicals Market Emerging Trajectories
Fluorochemical manufacturing is pivoting from commodity refrigerant production toward specialized high-purity gas architectures, with technology adoption patterns diverging sharply between legacy HVAC retrofit markets and emerging semiconductor process applications.
Advanced hydrofluoroolefin blends are converging with electrochemical fluorination purification systems to deliver sub-part-per-billion impurity levels required for extreme ultraviolet lithography processes. Taiwan and South Korea semiconductor fabs are qualifying these chemistries on accelerated timelines. This convergence is compressing the viable supplier base to participants with integrated fluorogas-to-polymer operations and captive purification infrastructure.
The EU F-Gas Regulation is mandating stepped reductions in fluorinated gas quotas through 2030, forcing OEMs to reformulate cooling systems ahead of hydrofluorocarbon availability constraints. Automotive and commercial HVAC manufacturers are responding by locking multi-year hydrofluoroolefin supply agreements. The regulation is most acutely affecting stationary air conditioning and commercial refrigeration segments, where equipment replacement cycles lag regulatory phase-down velocities.
Buyer concentration among Taiwan and South Korea semiconductor fabricators is consolidating procurement leverage for high-purity fluorinated gases, displacing fragmented spot-market purchasing with long-term offtake contracts tied to capacity reservation fees. Equipment suppliers are unbundling gas supply from tool maintenance agreements to capture chemistry margin directly. This behavioral shift is most visible in advanced node semiconductor manufacturing, where process gas purity specifications now exceed legacy analytical detection thresholds.
Fluorochemicals Market Segmentation
Fluorochemical procurement decisions hinge on purity specifications, regulatory compliance timelines, and integration depth with downstream manufacturing processes. Buyers across semiconductor, automotive, and HVAC sectors weight these factors differently, creating distinct demand clusters that reshape supplier priorities.
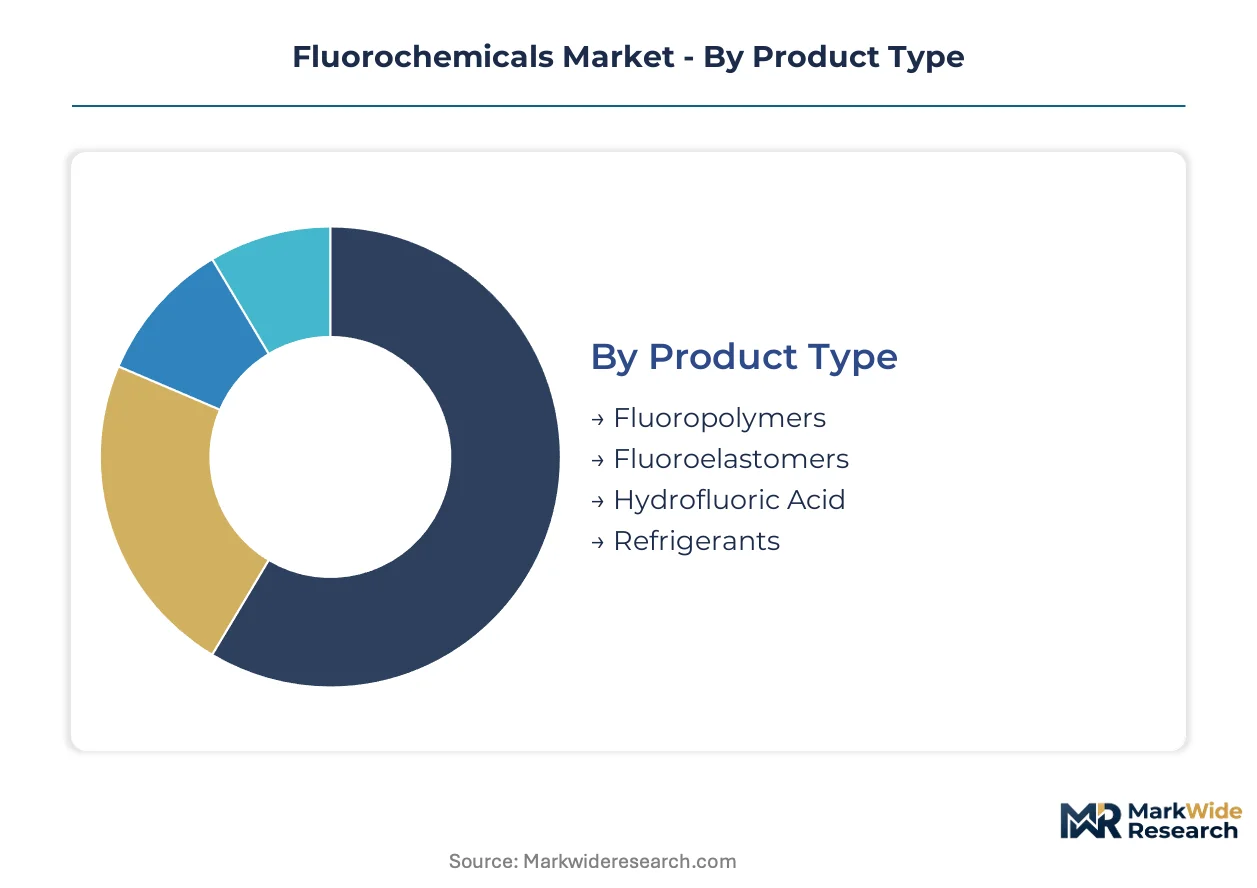
Product Type:
Purchase volume and margin profile separate commodity feedstocks from specialty grades, with semiconductor fabs paying premiums for contamination thresholds below legacy detection limits.
- Fluoropolymers:High-performance resins with carbon-fluorine backbone structures deliver thermal stability exceeding 260°C for wire insulation and medical implants. Taiwan and South Korea fabs absorb premium volumes for cleanroom infrastructure, while aerospace OEMs specify certified grades for fuel system components.
- Hydrofluoric Acid:Anhydrous hydrogen fluoride serves as the universal feedstock for fluorinated gas and polymer production through electrochemical fluorination or halogen exchange. Zhejiang and Shandong provinces in China concentrate global manufacturing capacity, tightening availability under coal-powered production constraints imposed by the Ministry of Ecology and Environment.
- Fluoroelastomers:Sealing materials for extreme chemical and thermal environments in aerospace and automotive systems.
- Refrigerants:Hydrofluorocarbon and hydrofluoroolefin chemistries for cooling systems facing phasedown mandates under the Kigali Amendment and US EPA Significant New Alternatives Policy.
Hydrofluoric Acid leads on scale as the foundational feedstock for all downstream fluorochemistry; Fluoropolymers lead on momentum as semiconductor and medical applications expand most quickly.
Application:
End-use specification intensity varies sharply, with electronics demanding sub-part-per-billion purity while HVAC prioritizes cost-effective regulatory compliance pathways.
- Electronics:Semiconductor fabrication consumes high-purity fluorinated etching gases for advanced node patterning, with Taiwan fabs qualifying electrochemical fluorination outputs on accelerated timelines. Extreme ultraviolet lithography processes now require impurity specifications below legacy analytical thresholds, compressing the viable supplier base to integrated fluorogas-to-polymer operators.
- Automotive:OEMs reformulate cooling systems under EPA and EU F-Gas Regulation mandates, locking multi-year hydrofluoroolefin supply agreements for next-generation vehicle platforms. The transition from hydrofluorocarbon to hydrofluoroolefin architectures dominates engineering priorities across passenger and commercial vehicle segments.
- HVAC:Stationary air conditioning and commercial refrigeration equipment face replacement cycles that lag regulatory phase-down velocities, creating retrofit market opportunities.
- Aerospace:Wire insulation and fuel system sealing applications command certified fluoropolymer grades with thermal degradation thresholds exceeding standard polymer limits.
Electronics leads on scale through concentrated fab procurement; Automotive leads on momentum as regulatory deadlines force chemistry transitions.
End User:
Integration depth with manufacturing processes determines whether buyers source directly from fluorochemical producers or through intermediaries with formulation and logistics capabilities.
- OEMs:Original equipment manufacturers in automotive and HVAC sectors negotiate direct supply agreements for refrigerant and polymer volumes, locking capacity reservation fees to secure chemistry transitions ahead of regulatory deadlines.
- Manufacturers:Downstream polymer processors and component fabricators purchase fluoropolymer resins and fluoroelastomers for conversion into finished goods.
- Contractors:Service providers in automotive and HVAC retrofit channels capture replacement demand as hydrofluorocarbon inventories deplete, sourcing hydrofluoroolefin blends through distributors.
- Distributors:Intermediaries aggregate fragmented demand from smaller contractors and regional manufacturers, managing inventory and logistics for non-captive buyers.
OEMs lead on scale through consolidated procurement leverage; Contractors lead on momentum as aftermarket chemistry transitions accelerate.
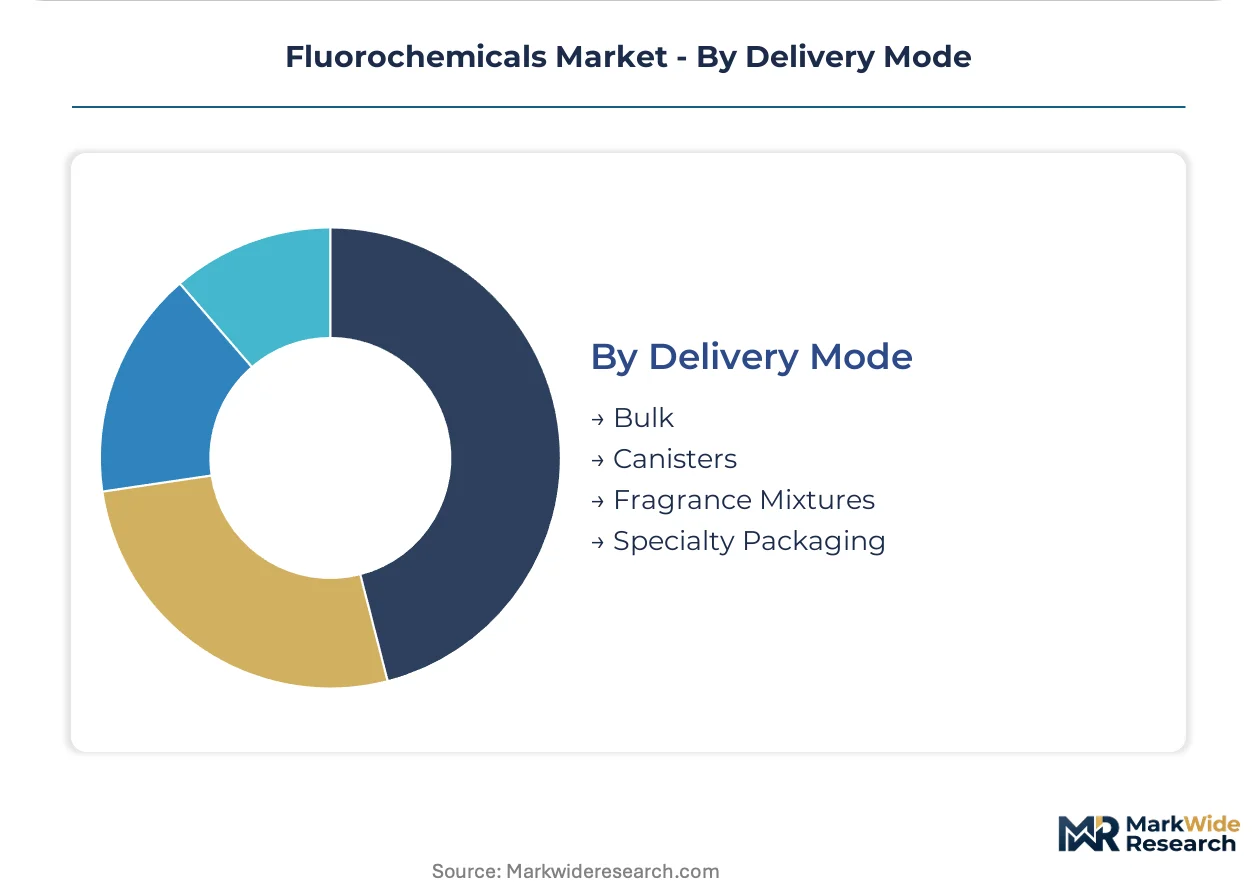
Delivery Mode:
Packaging configuration aligns with volume scale, purity preservation requirements, and regulatory handling restrictions across the fluorochemical portfolio.
- Bulk:Tanker and railcar shipments of hydrofluoric acid and refrigerant-grade gases serve integrated polymer producers and large-scale HVAC manufacturers with captive consumption capacity.
- Canisters:High-pressure cylinders deliver high-purity fluorinated gases to semiconductor fabs, with specialized valve and surface treatment protocols preventing contamination during transfer.
- Specialty Packaging:Barrier-coated containers and moisture-exclusion systems preserve reagent-grade hydrofluoric acid for electronics and pharmaceutical applications.
- Fragrance Mixtures:Pre-blended formulations for specific industrial or consumer applications requiring controlled release characteristics.
Bulk leads on scale through feedstock and refrigerant volume concentration; Canisters lead on momentum as semiconductor gas demand climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting fluorochemical investment toward jurisdictions with phased compliance timelines, as manufacturers seek production bases that defer Kigali Amendment obligations while maintaining access to semiconductor demand clusters.
China
Zhejiang and Shandong provinces concentrate global hydrofluoric acid manufacturing, supplying feedstock for downstream refrigerant and polymer production. The Ministry of Ecology and Environment enforces dual carbon goals that constrain coal-powered capacity, tightening anhydrous hydrogen fluoride availability for domestic fluorogas-to-polymer operations. Changshu in Jiangsu province hosts integrated manufacturing bases serving both captive consumption and export markets.
United States
Semiconductor fabs in Arizona and Texas are scaling high-purity fluorinated gas procurement for advanced node production, creating dedicated demand channels distinct from commoditized refrigerant markets. The EPA enforces Significant New Alternatives Policy restrictions that compel OEMs to reformulate cooling systems ahead of hydrofluorocarbon phase-down deadlines. Gulf Coast chemical corridors maintain fluoropolymer production infrastructure for aerospace wire insulation applications.
South Korea
Memory and logic fabricators in Pyeongtaek and Yongin are qualifying electrochemical fluorination outputs on accelerated timelines for extreme ultraviolet lithography processes. National industrial policy supports domestic fluorochemical supply chain development to reduce import dependency for sub-part-per-billion purity gases. The Korea Semiconductor Industry Association coordinates fab procurement standardization for contamination thresholds.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are locking multi-year hydrofluoroolefin supply agreements for next-generation vehicle platform cooling systems. The EU F-Gas Regulation mandates stepped reductions in fluorinated gas quotas through 2030, redirecting capital toward low-global-warming-potential chemistry capacity. BASF and Lanxess production clusters in Ludwigshafen and Leverkusen anchor fluoropolymer compounding for fuel system sealing applications.
India
Domestic refrigerant and polymer markets in Gujarat are supporting backward integration into chlorodifluoromethane and tetrafluoroethylene supply. The Bureau of Indian Standards implements phased alignment with Montreal Protocol obligations, creating compliance runway for local manufacturers. Dahej and Vadodara industrial corridors concentrate fluorochemical processing capacity serving captive consumption for regional HVAC and automotive sectors.
Fluorochemicals Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized high-purity gas architectures for semiconductor applications. The vendor base stratifies across integrated fluorogas-to-polymer operators, captive feedstock-integrated regional specialists, and technology-licensed pure-play gas purifiers. Three archetypes dominate: multinational chemical conglomerates with diversified fluorinated portfolios, Asia-Pacific feedstock-integrated producers leveraging hydrofluoric acid proximity, and European specialty gas houses focused on sub-part-per-billion certification. Competitive dynamics center on capacity reservation contracting with Taiwan and South Korea fabs, alongside backward integration into anhydrous hydrogen fluoride supply.
Among French chemical conglomerates, Arkema exemplifies integrated fluorogas-to-polymer operations spanning southern France and Chinese manufacturing bases. Japanese industrial groups including Daikin Industries, Ltd. occupy positions within cleanroom infrastructure supply chains for semiconductor fabrication. Indian specialty chemical producers such as Gujarat Fluorochemicals Limited represent captive chlorodifluoromethane integration models insulating participants from feedstock volatility. These three anchors illustrate divergent strategic postures: geographic diversification, application-specific premium positioning, and domestic market vertical control.
| Leading Market Players |
|---|
| Arkema |
| DuPont de Nemours, Inc. |
| 3M Company |
| AGC Group |
| Solvay SA |
| Daikin Industries, Ltd. |
| Honeywell International Inc. |
| Gujarat Fluorochemicals Limited |
| The Chemours Company |
| Others |
Supply Flow & Price Mechanics
Captive fluorogas-to-polymer integration anchors supply position and pricing power for established producers, insulating participants from anhydrous hydrogen fluoride volatility while enabling premium capture on semiconductor-grade outputs. Arkema's dual-base manufacturing across southern France and Changshu exemplifies how integrated operations compress channel margins and sustain margin premiums on high-purity chemistries.
Pricing Analysis
Distributor margins compress pricing realization for non-captive buyers, while direct-to-OEM contracts secure volume commitments with discounted unit economics. Contract-based long-term offtake dominates semiconductor applications, where fab qualification timelines justify capacity reservation fees; spot-market transactional pricing persists in HVAC retrofit channels. Price differentiation hinges on contamination grade and volume scale, with sub-part-per-billion certification commanding substantial premiums. Cost compression in refrigerant-grade hydrofluorocarbon tiers is intensifying because Kigali Amendment phasedown mandates erode addressable volume. Contractors in automotive service channels exhibit highest price sensitivity, whereas Taiwan and South Korea fabs prioritize supply security over unit cost.
Supply Chain Analysis
Semiconductor-grade qualification gating restricts viable supplier participation, compressing the certified base to integrated operators with captive purification infrastructure. Feedstock concentration centers on China, South Korea, and Japan, with Zhejiang and Shandong provinces anchoring global hydrofluoric acid output. Raw material dependencies draw from fluorspar mining, sulfuric acid supply, and coal-powered energy inputs. Single-source vulnerability in Chinese anhydrous hydrogen fluoride production creates structural exposure to MEE dual carbon enforcement. Distribution runs through bulk tanker networks for integrated polymer producers and specialized canister logistics for fab-direct gas delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorochemicals present a margin-expansion trajectory as feedstock constraints and premium-grade demand shift value capture toward integrated operators with captive purification capabilities.
For Market Incumbents: Lock in multi-year offtake agreements with Taiwan and South Korea fabs before electrochemical fluorination capacity expansion saturates high-purity segments. Prioritize backward integration into anhydrous hydrogen fluoride supply to defend against Zhejiang and Shandong production constraints under MEE enforcement. Expand certification investment for extreme ultraviolet lithography gas grades to sustain premium positioning against emerging technology-licensed entrants. For New Entrants and Emerging Players: Semiconductor equipment suppliers represent the most accessible channel partnership, as tool manufacturers unbundle gas supply from maintenance agreements to capture chemistry margin directly. Target automotive HVAC retrofit distributors in markets with lagging regulatory phase-down timelines, where hydrofluoroolefin replacement demand outpaces incumbent supply flexibility. Pursue white-space positioning in medical implant-grade fluoropolymer compounding, where biocompatibility certification barriers limit incumbent expansion velocity. For Investors and Strategic Acquirers: Roll-up economics work for regional feedstock-integrated specialists because coal-powered production constraints in China are tightening hydrofluoric acid availability and fragmenting downstream supply. Target acquisition archetypes include Indian chlorodifluoromethane-integrated producers with captive tetrafluoroethylene supply and European specialty gas houses with sub-part-per-billion certification infrastructure. Watch for inflection in Taiwan fab capital expenditure announcements as the signal for high-purity gas demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anhydrous Hydrogen Fluoride | Secures feedstock autonomy against MEE dual carbon constraints tightening Zhejiang and Shandong output. |
| Electrochemical Fluorination Capacity Expansion | Enables sub-part-per-billion purity qualification with Taiwan and South Korea extreme ultraviolet lithography fabs. |
| Long-term Supply Agreement with Semiconductor OEMs | Locks capacity reservation fees ahead of fab procurement standardization by Korea Semiconductor Industry Association. |
| Joint Venture for Regional Feedstock Security | Distributes single-source risk from Chinese hydrofluoric acid concentration through diversified production bases. |
| Green Manufacturing Transition | Aligns with EU F-Gas Regulation mandates and EPA Significant New Alternatives Policy compliance timelines. |
Methodological Framework
Coverage spans Asia-Pacific, North America, and Europe, with primary inputs from each region combined with secondary validation across trade and regulatory databases. Primary interviews engaged fluorochemical plant managers, procurement leads at semiconductor OEMs, distribution channel partners, and technical R&D directors specializing in electrochemical fluorination processes. Secondary sources drew from customs and trade data, SEC filings, EPA regulatory dockets, and Korea Semiconductor Industry Association procurement standards. Bottom-up volume modeling triangulated against top-down industry aggregate benchmarks.
Granularity-level modeling operated at product-grade tier, end-use industry, packaging format, and regional production hub dimensions across the analysis window. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and regulatory phase-down velocity assumptions. Forecast inputs incorporated fab capacity expansion pipelines, MEE enforcement intensity projections, and automotive platform electrification cooling system specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Kigali Amendment ratification timelines and extreme ultraviolet lithography adoption velocity. Forecasts reflect documented assumptions on feedstock availability and regulatory enforcement intensity. A model refresh is warranted upon material change in Taiwan semiconductor capital expenditure cycles or MEE dual carbon policy implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Chlorosilane Market
Chemicals
Zinc Chemicals Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Perchloric Acid Market
Chemicals
Di Nitro Toluene Market
Chemicals
Morpholine Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Phosgene Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Formalin Market
Chemicals
Potassium Alum Market
Chemicals
Aromatic Polyamine Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Hexafluorosilicic Acid Market