
 Fluoroantimonic Acid Market | 2026-2036
Fluoroantimonic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoroantimonic Acid Market Foresight
Hydrofluoric acid blends are restructuring fluoroantimonic acid procurement economics as semiconductor fabs seek higher-purity etching chemistries with tighter particle specifications. Solvay SA leverages its integrated fluorine value chain to sustain European supply reliability for electronic-grade material. Merck KGaA anchors Asia-Pacific distribution through its life-sciences logistics network, while Thermo Fisher Scientific Inc. competes on research-grade packaging customization and cold-chain compliance.
Fluoroantimonic acid is the strongest known superacid, formed by combining antimony pentafluoride with hydrogen fluoride in ratios typically ranging from 1:1 to 2:1, with a Hammett acidity function exceeding −28; manufacturers produce it under anhydrous conditions using corrosion-resistant nickel alloys or fluoropolymer-lined reactors to prevent catastrophic HF release. Superacid grade dominates value capture due to semiconductor etching requirements, while research grade shows the fastest volume expansion as academic labs scale up fluorine chemistry programs. Chemical synthesis applications retain mature demand patterns, whereas surface treatment for specialty alloys represents an emerging margin pool.
EPA hazardous waste regulations and OSHA permissible exposure limits for antimony compounds shape domestic manufacturing site selection and worker-safety capital allocation in the United States. REACH registration obligations and the EU Green Deal fluorinated-gas phase-down trajectory constrain European import volumes and push local producers toward closed-loop recycling systems. Stakeholders must monitor how China's dual carbon goals and tightening MEE enforcement on fluorochemical emissions reshape global supply availability and regional price formation.
Market Dynamics
Semiconductor node shrinkage below 7nm is compressing etching chemistry tolerances, forcing fabs to source superacid-grade fluoroantimonic acid with sub-ppb metallic impurity specifications and certified anhydrous handling protocols.
Growth Catalysts
- Advanced node etching:Logic and memory fabs at 3nm and below require Hammett acidity functions below −25 for precision substrate removal, pulling demand for 2:1 SbF5:HF ratio formulations.
- China's GB standard convergence:Tighter MEE enforcement on fluorochemical emissions and updated hazardous reagent warehousing rules are consolidating demand around certified domestic suppliers with captive fluorine integration.
- Academic fluorine chemistry expansion:Research institutions scaling organofluorine synthesis programs are lifting volume consumption of analytical-grade material for reaction mechanism studies.
Market Restraints
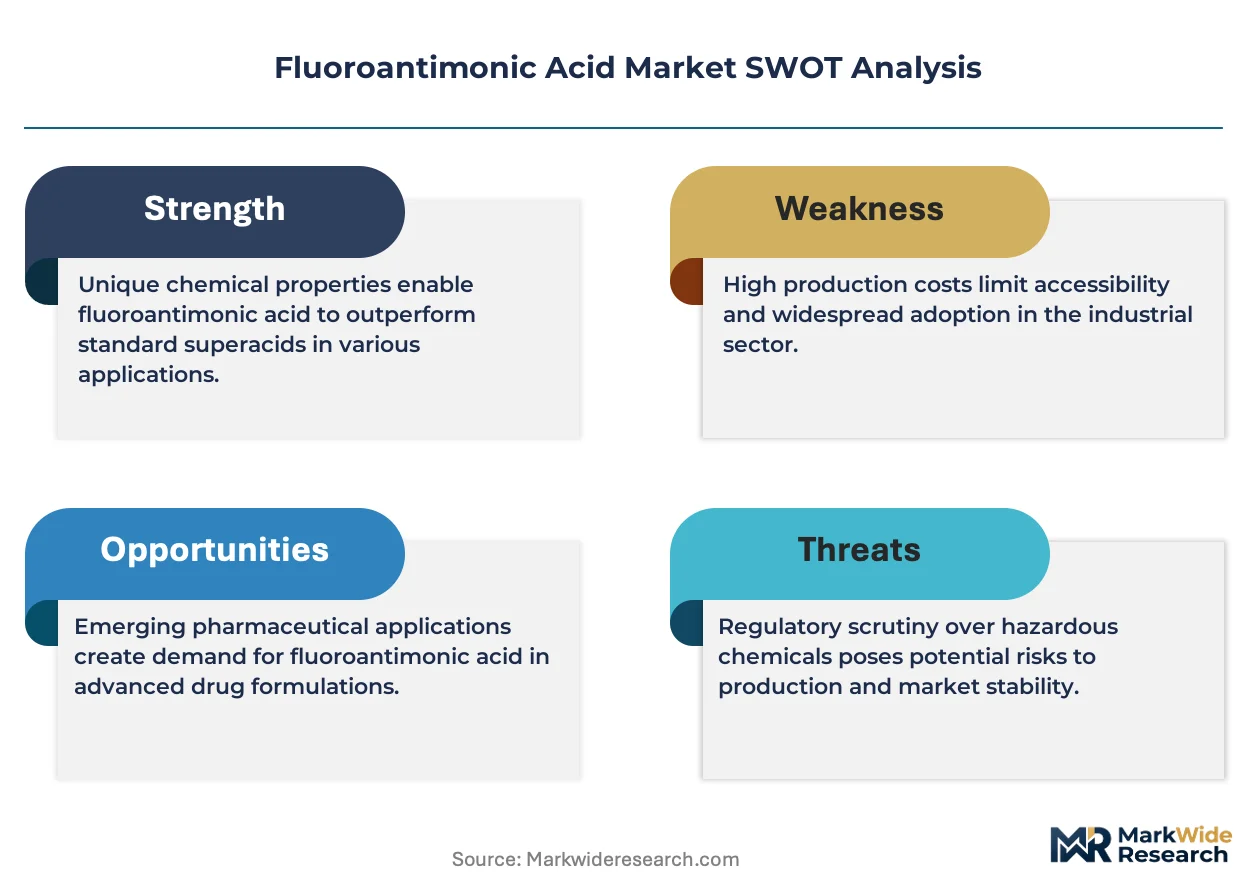
- Antimony pentafluoride supply concentration:SbF5 production clusters in Chinese and Belgian integrated fluorochemical complexes, exposing buyers to single-source risk during force majeure events.
- Anhydrous handling infrastructure costs:Nickel alloy reactor vessels and fluoropolymer-lined transport containers require capital intensity that excludes smaller regional distributors from qualification.
- EU F-Gas phase-down trajectory:REACH registration obligations and the Green Deal fluorinated-gas restrictions are constraining import volumes and forcing closed-loop recycling investments.
Strategic Opportunities
- Captive fluorochemistry in East China:Domestic specialty chemical producers in Jiangsu and Zhejiang provinces are building backward-integrated SbF5 capacity to serve local semiconductor fabs.
- Specialty alloy surface treatment:Aerospace and medical device manufacturers are adopting superacid passivation for titanium and niobium components, opening margin pools outside electronics.
- Research-grade packaging innovation:Cold-chain compliant ampoule configurations and smaller lot sizes are enabling direct-to-lab distribution models bypassing traditional chemical distributors.
Industry Challenges
- Corrosion engineering talent scarcity:Qualified technicians for nickel alloy reactor maintenance and HF release mitigation command premium wages, constraining capacity expansion timelines.
- Multi-jurisdiction certification lag:Obtaining EPA hazardous waste permits, OSHA antimony exposure clearances, and NMPA chemical substance registrations in parallel extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoroantimonic Acid Market |
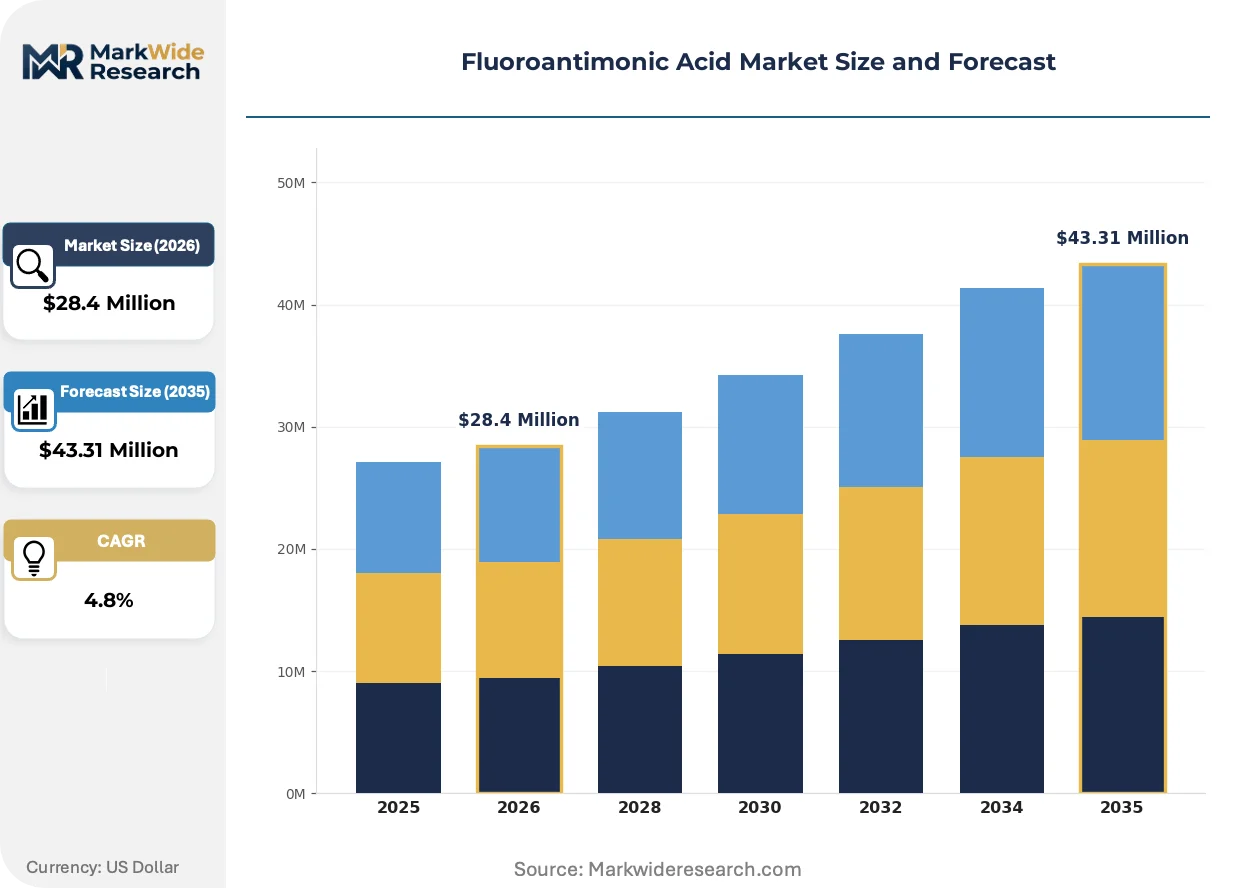
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $43.31 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superacid Grade, Electronic Grade, Industrial Grade, Research Grade Application: Catalysis, Etching, Chemical Synthesis, Surface Treatment, Gas Treatment End User Industry: Semiconductor Fabricators, Chemical Manufacturers, Research Laboratories, Electronics Assembly, Specialty Chemical Producers Packaging Type: Glass Bottles, Teflon Containers, Steel Drums, HDPE Drums, Customized Packaging |
| Companies Covered | City Chemical LLC, TCI Chemicals, Merck KGaA, VWR International LLC, Alfa Aesar, Solvay SA, American Elements, Advance Research Chemicals Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoroantimonic Acid Market Shifts & Advancements
Fluoroantimonic acid production and application are being restructured by three intersecting forces: unified etching chemistry platforms, tightening environmental compliance frameworks, and compressed procurement cycles favoring qualified direct supply relationships.
Integrated superacid systems are unifying etching and cleaning steps in advanced semiconductor manufacturing. These platforms combine fluoroantimonic acid with precision-dosed HF blends in single-loop process tools. Leading memory and logic fabs in Taiwan and South Korea are adopting these configurations at pilot scale. This unification is compressing the number of qualified chemical suppliers per fab site from multiple vendors to one or two with full portfolio coverage.
REACH registration obligations and the EU F-Gas Regulation are tightening fluorochemical lifecycle accountability. ECHA mandates on substance volume tracking and the Green Deal phase-down of fluorinated gases are forcing European importers toward closed-loop recycling partnerships. Electronic-grade material users in Germany and France are responding by qualifying local producers with integrated waste acid recovery capabilities rather than Asian import sources.
Direct technical service contracts are displacing traditional distributor relationships in high-volume semiconductor procurement. Fabs are contracting formulation engineers from chemical suppliers for on-site blend optimization and real-time quality monitoring. This pattern is most visible in East China, where Yangtze River Delta fabs negotiate multi-year supply agreements bundling material, technical support, and waste handling in single vendor relationships.
Fluoroantimonic Acid Market Segmentation
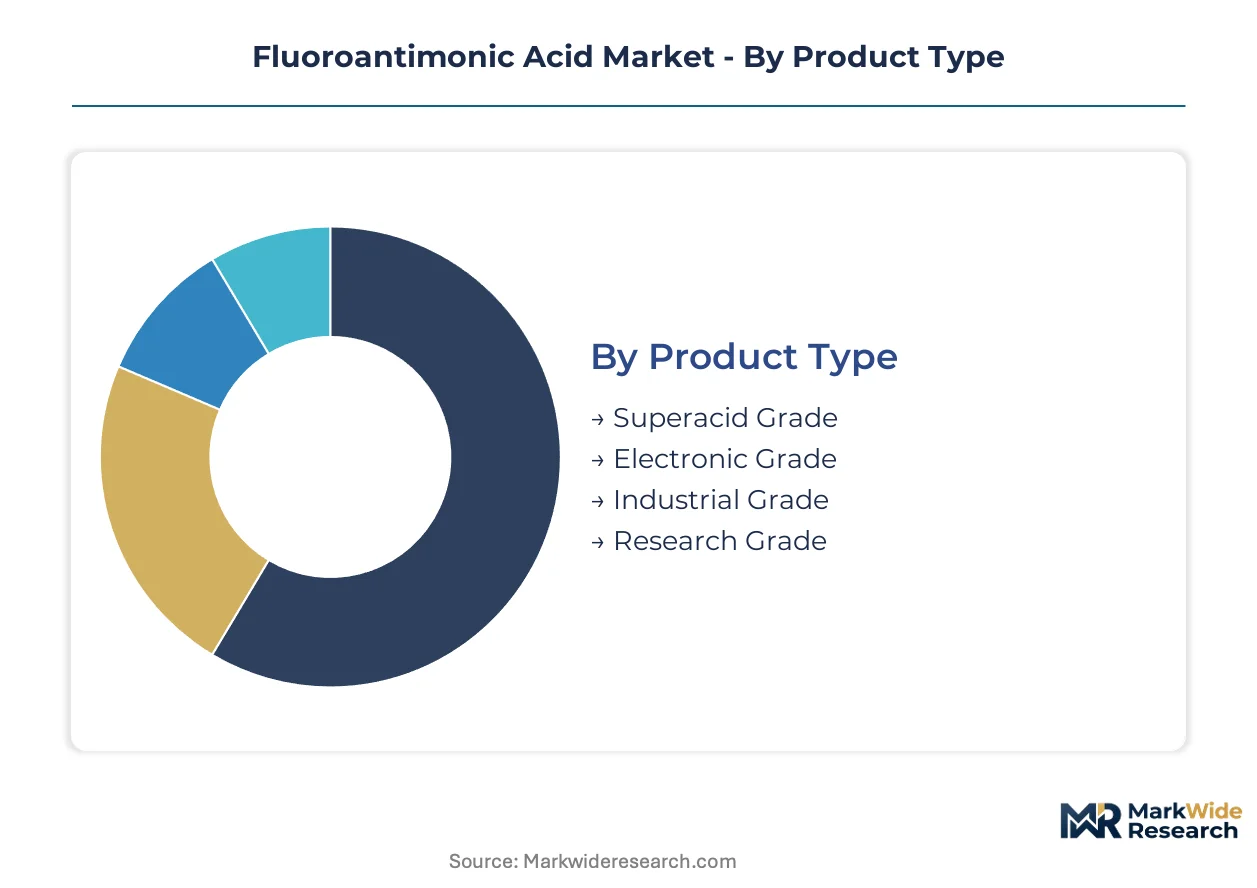
Fluoroantimonic acid procurement decisions pivot on purity thresholds, handling infrastructure, and regulatory compliance costs. Semiconductor fabs prioritize grade specifications above price elasticity, while research buyers trade volume for packaging flexibility. Understanding segment boundaries reveals where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Purity specifications separate qualified suppliers from price competitors, with Hammett acidity tolerance bands determining end-use eligibility.
- Superacid Grade:Formulated at 2:1 SbF5:HF ratio with Hammett acidity below −25, this grade demands sub-ppb metallic impurity certification. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specify this material for 3nm node etching, where particle contamination triggers wafer scrap rates exceeding fabrication economics.
- Electronic Grade:Manufactured under anhydrous conditions with controlled moisture content below 50 ppm, electronic grade serves display panel etching and MEMS fabrication. South Korean OLED producers in Gyeonggi Province consume rising volumes as flexible display manufacturing scales.
- Industrial Grade:Standard purity material for bulk chemical synthesis and metal refining applications.
- Research Grade:Smaller lot sizes with batch-specific certificates of analysis for academic fluorine chemistry programs.
Volume sits with superacid grade; growth tilts toward research grade.
Application:
Process integration intensity determines customer stickiness and technical service bundling requirements.
- Catalysis:Superacidic protonation enables isomerization and alkylation reactions in petrochemical refining. Sinopec and Reliance Industries operate continuous units requiring steady supply contracts with dedicated logistics.
- Etching:Precision substrate removal for logic and memory devices demands real-time blend optimization. TSMC's Arizona fab qualifies suppliers on particle count consistency across quarterly audits.
- Chemical Synthesis:Organofluorine building block production for agrochemical and pharmaceutical intermediates.
- Surface Treatment:Aerospace titanium passivation and medical device niobium finishing are gaining specification traction.
- Gas Treatment:Fluorinated gas scrubbing and exhaust neutralization in semiconductor abatement systems.
Revenue concentrates in etching; surface treatment is climbing the fastest.
End User Industry:
Capital intensity and regulatory sophistication create divergent procurement patterns across buyer categories.
- Semiconductor Fabricators:Advanced node producers negotiate multi-year agreements bundling material, technical support, and waste acid recovery. Yangtze Memory Technologies in Wuhan requires on-site formulation engineers for blend optimization.
- Chemical Manufacturers:Integrated fluorochemical producers consume captive material for downstream derivative synthesis.
- Research Laboratories:University and national lab programs scaling organofluorine research drive analytical-grade consumption.
- Electronics Assembly:PCB and component manufacturers with lower purity requirements.
- Specialty Chemical Producers:Custom synthesis houses serving pharmaceutical and agrochemical contract manufacturing.
Procurement scale favors semiconductor fabricators; research laboratories are expanding most quickly.
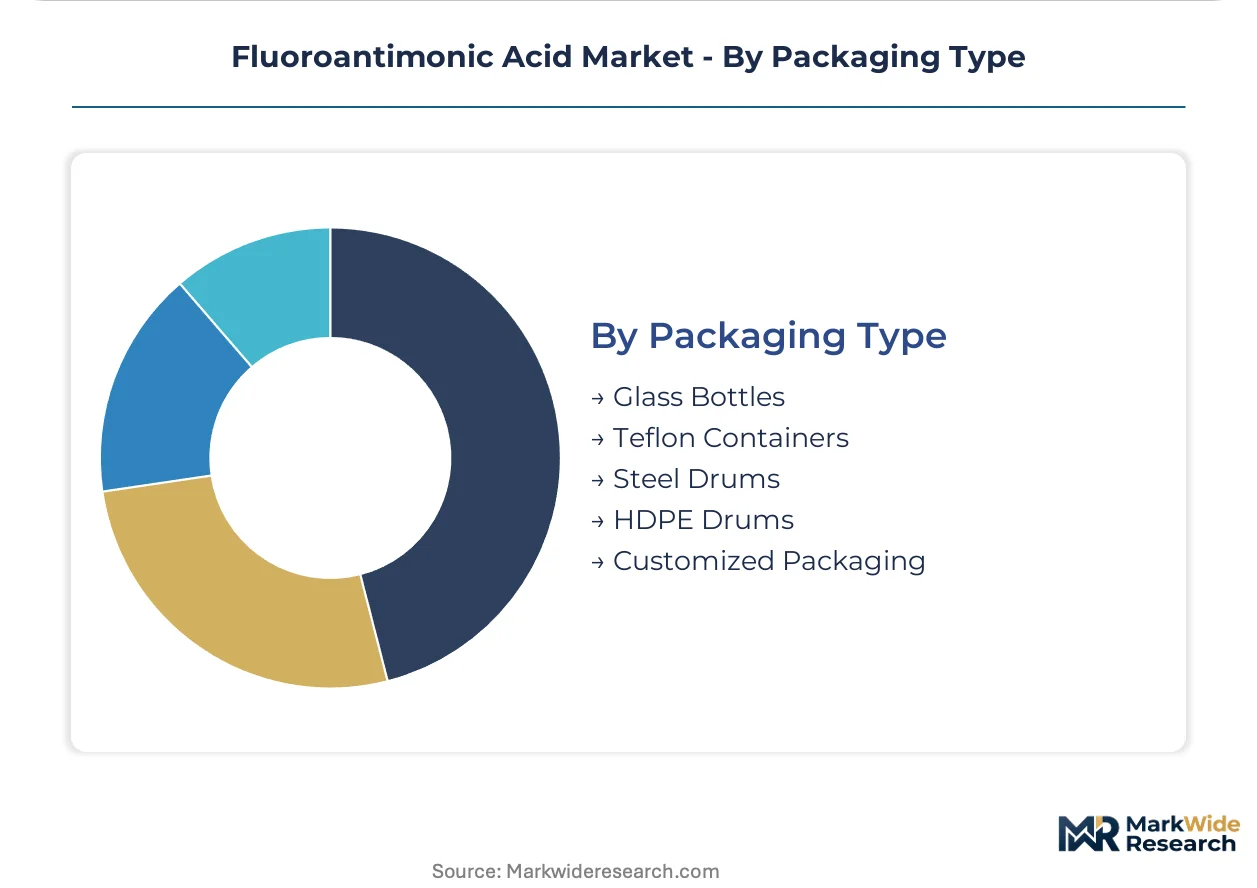
Packaging Type:
Containment material selection directly correlates with corrosion risk, transport mode, and regulatory jurisdiction.
- Teflon Containers:Fluoropolymer-lined vessels prevent HF permeation during extended storage. German chemical distributors serving BASF and Merck KGaA specify PTFE configurations for REACH-compliant substance tracking.
- Steel Drums:Nickel alloy constructions with fluoropolymer internal coatings balance durability against cost for industrial-grade shipments. Chinese domestic logistics favor this format for Jiangsu-to-Shanghai corridor movements.
- Glass Bottles:Limited to research-grade ampoules under 500 mL for laboratory direct distribution.
- HDPE Drums:Restricted to dilute formulations and intermediate transport legs.
- Customized Packaging:Cold-chain compliant configurations for temperature-sensitive high-purity material.
Shipment volume centers on steel drums; customized packaging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in East Asia and North America absorb the majority of superacid-grade fluoroantimonic acid shipments, while European demand shifts toward closed-loop recycling partnerships under tightening fluorochemical regulations.
China
Yangtze Memory Technologies and SMIC drive consumption for 3nm node development. MEE enforcement on fluorochemical emissions and updated GB standards for hazardous reagent warehousing favor domestic producers with captive SbF5 integration. Jiangsu and Zhejiang provinces host backward-integrated specialty chemical facilities serving Shanghai-region fabs.
United States
TSMC's Arizona fab and Intel's New Mexico operations qualify suppliers on particle count consistency. EPA hazardous waste regulations and OSHA permissible exposure limits for antimony compounds shape site selection and worker-safety capital allocation. The Southwest semiconductor corridor concentrates demand around Phoenix-Tucson logistics hubs.
South Korea
Samsung Foundry and SK Hynix specify 2:1 SbF5:HF formulations for advanced memory etching. MFDS chemical substance tracking requirements and national semiconductor cluster subsidies support Gyeonggi Province consumption. Flexible display manufacturers in Paju expand electronic-grade uptake for OLED fabrication.
Germany
BASF and Merck KGaA anchor European electronic-grade distribution. REACH registration obligations and the EU F-Gas Regulation phase-down constrain import volumes and push closed-loop recycling investments. The Rhine-Main chemical corridor hosts integrated waste acid recovery capabilities serving domestic fabs.
Japan
Tokyo Electron and Shin-Etsu Chemical drive precision etching chemistry demand. METI fluorochemical stewardship guidelines and JIS standards for high-purity reagents shape procurement specifications. The Kyushu semiconductor cluster in Kumamoto Prefecture qualifies suppliers for 2nm pilot line trials.
Fluoroantimonic Acid Market Competitive Landscape
Capacity expansion dominates the current landscape as producers scale nickel alloy reactor investments to meet semiconductor-grade specifications. The vendor base stratifies across three tiers: integrated fluorochemical majors with captive antimony pentafluoride production, regional electronic-grade specialists, and research-grade distributors competing on packaging customization. Strategic archetypes include backward-integrated SbF5 producers, logistics-anchored distributors, and technical service bundlers. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players qualifying new fab sites and adding complementary superacid formulations.
Among integrated chemical producers, Solvay SA exemplifies the European archetype with fluorine value chain control, while Merck KGaA occupies a position bridging life-sciences logistics and electronic-grade distribution. Thermo Fisher Scientific Inc. represents the research-grade packaging innovation vector, competing on cold-chain compliance and smaller lot configurations for direct-to-lab distribution.
| Leading Market Players |
|---|
| City Chemical LLC |
| TCI Chemicals |
| Merck KGaA |
| VWR International LLC |
| Alfa Aesar |
| Solvay SA |
| American Elements |
| Advance Research Chemicals Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Superacid-grade certification separates electronic-grade suppliers from industrial-grade competitors, and this bifurcation generates divergent margin structures across procurement channels. Semiconductor fabs absorb premium pricing for sub-ppb purity material with certified anhydrous handling, while research laboratories negotiate smaller-lot flexibility against standardized catalog pricing.
Pricing Analysis
Volume concentrates in contract-based long-term offtake agreements for superacid-grade material, while margins concentrate in research-grade packaging customization. Price differentiation rests on metallic impurity certification and captive SbF5 integration, with integrated producers commanding premiums over merchant suppliers. Cost compression in electronic-grade material is intensifying because fabs are consolidating qualified suppliers from multiple vendors to one or two with full portfolio coverage. Chemical manufacturers exhibit highest price sensitivity due to commoditized synthesis applications, whereas semiconductor fabricators prioritize particle specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from TSMC, Samsung Foundry, and Intel mandate multi-supplier qualification for 2:1 SbF5:HF formulations, preventing single-source dependency despite concentration. Production gravity centers on China, Belgium, and Germany, where integrated fluorochemical complexes control antimony pentafluoride output. Raw material dependencies draw from hydrogen fluoride supply, nickel alloy reactor fabrication, and fluoropolymer liner production. Single-source vulnerability persists because SbF5 synthesis clusters in Jiangsu province and the Antwerp-Rotterdam chemical corridor. Distribution runs through direct technical service contracts displacing traditional chemical distributors, with formulation engineers stationed at fab sites for real-time blend optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as MEE enforcement on fluorochemical emissions and tightening GB standards force capital-constrained regional distributors to exit qualification pipelines.
For Market Incumbents: Anticipate qualification consolidation by securing captive SbF5 integration through backward integration into antimony pentafluoride production or long-term offtake agreements with Chinese integrated complexes. Threat from emerging East China specialty chemical producers with captive fluorochemistry capabilities demands defensive capacity expansion in nickel alloy reactor infrastructure. Certification investment in NMPA chemical substance registration and parallel EPA hazardous waste permitting creates switching costs locking out undercapitalized competitors. For New Entrants and Emerging Players: Capture surface treatment applications for aerospace titanium and medical device niobium passivation, where specification traction is climbing fastest and incumbent technical service bundling is weakest. Research-grade packaging innovation with cold-chain compliant ampoule configurations offers the most penetrable entry vector, bypassing traditional distributor relationships through direct-to-lab distribution models. Go-to-market execution should anchor on academic fluorine chemistry program expansion at institutions scaling organofluorine synthesis research. For Investors and Strategic Acquirers: Re-rating potential sits with backward-integrated specialty chemical producers in Jiangsu and Zhejiang provinces given China's dual carbon goals and tightening MEE enforcement reshaping global supply availability. Long-term viability across the next decade hinges on closed-loop recycling capabilities and waste acid recovery integration serving European demand under REACH and F-Gas Regulation constraints. Signal to watch as inflection indicator: qualification timelines for new nickel alloy reactor capacity at East China facilities, where corrosion engineering talent scarcity extends construction schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SbF5 Production | Jiangsu and Zhejiang producers secure captive fluorine supply chains serving Yangtze River Delta semiconductor clusters. |
| Nickel Alloy Reactor Capacity Expansion | Qualified technicians for HF release mitigation command premium wages, constraining competitor entry timelines. |
| Closed-Loop Recycling Partnerships | BASF and Merck KGaA anchor European electronic-grade distribution under ECHA substance tracking mandates. |
| Direct Technical Service Contracts | TSMC's Arizona fab and Intel's New Mexico operations qualify suppliers bundling material with on-site formulation engineers. |
| Research-Grade Packaging Innovation | Thermo Fisher Scientific competes on cold-chain compliance and smaller lot configurations for academic laboratory direct distribution. |
Research Methodology
SEC 10-K filings, customs and trade data from Chinese and European import registries, and ACC/Cefic fluorochemical industry reports formed the secondary backbone of this analysis. Primary interviews with plant managers at integrated fluorochemical facilities, procurement leads at Taiwan and South Korean semiconductor fabs, distribution channel partners serving German electronic-grade markets, and technical R&D directors for nickel alloy reactor fabrication validated demand assumptions and pricing structures. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down market sizing derived from trade flow analysis.
Historical trendline analysis of semiconductor node shrinkage patterns and superacid-grade material qualification timelines informed the projection framework across the analysis window. Segmentation dimensions modeled include grade tier (superacid, electronic, industrial, research), end-use industry (semiconductor fabrication, chemical manufacturing, research laboratories), packaging format (Teflon containers, steel drums, customized cold-chain configurations), and regional production hub concentration. CAGRs were derived from fitted growth curves applied to segment-specific demand drivers, with inputs from fab capacity expansion announcements and academic research program funding disclosures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE enforcement intensity on fluorochemical emissions, antimony pentafluoride supply disruptions from force majeure events, and corrosion engineering talent availability constraining reactor construction timelines. Deviation in China's dual carbon policy implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Allyl Chloride Market
Chemicals
Phosgene Market
Chemicals
P-Ethylphenol Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Global N-Butanol Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Perchloric Acid Market
Chemicals
Coal Tar Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Hexamine Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Roofing Chemical Market
Chemicals
Asia-Pacific Construction Chemicals Market