
 Benzhydrol Market | 2026-2036
Benzhydrol Market Size, Share, and Industry Trends Forecast 2026-2036
Benzhydrol Market Insights
ISO 9001 and cGMP certification cycles is bifurcating the supplier landscape into qualified pharmaceutical-grade providers and unqualified commodity traders. Capot Chemical leverages backward integration into diphenylmethane feedstock to sustain cost competitiveness in intermediates. Vasudha Chemicals Private anchors its position through dedicated R&D facilities serving Indian generic drugmakers. Sigma-Aldrich Corporation dominates laboratory-grade distribution through channel control over academic and institutional procurement networks.
Benzhydrol, also known as diphenylmethanol, functions as a secondary alcohol with the molecular formula C13H12O, synthesized primarily via sodium borohydride reduction of benzophenone or Grignard reaction pathways. The compound serves as a critical building block for antihistamine APIs, polymer stabilizers, and fragrance intermediates due to its hydroxyl reactivity and aromatic stability. Pharmaceutical-grade powder commands premium positioning as manufacturers face tightening pharmacopeial standards, while liquid delivery modes in industrial antioxidants compete primarily on volume throughput and supply consistency. Research applications represent the fastest-expanding segment as academic institutions scale organometallic chemistry programs across Asia-Pacific markets.
REACH in Europe and cGMP under FDA oversight in the United States enforce divergent purity protocols that reshape formulation requirements and testing burdens for cross-border suppliers. India's CDSCO mandates incremental stability data for cosmetic-grade benzhydrol entering the personal care supply chain, compressing timelines for domestic producers. China's NMPA aligns with ICH Q3C guidelines on residual solvent limits, forcing reformulation of traditional reduction processes. Stakeholders must monitor regulatory harmonization negotiations between major import jurisdictions to anticipate qualification cost shifts.
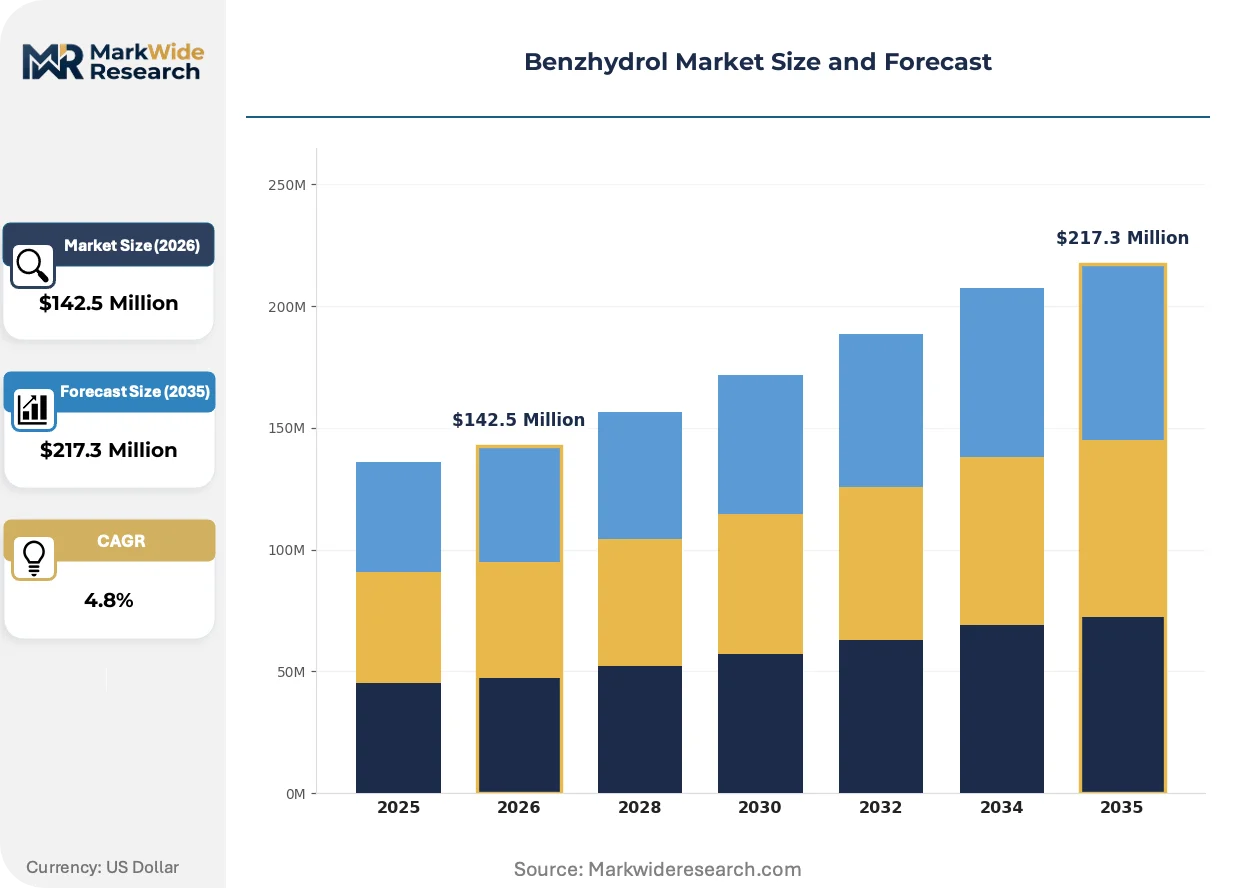
Market Dynamics
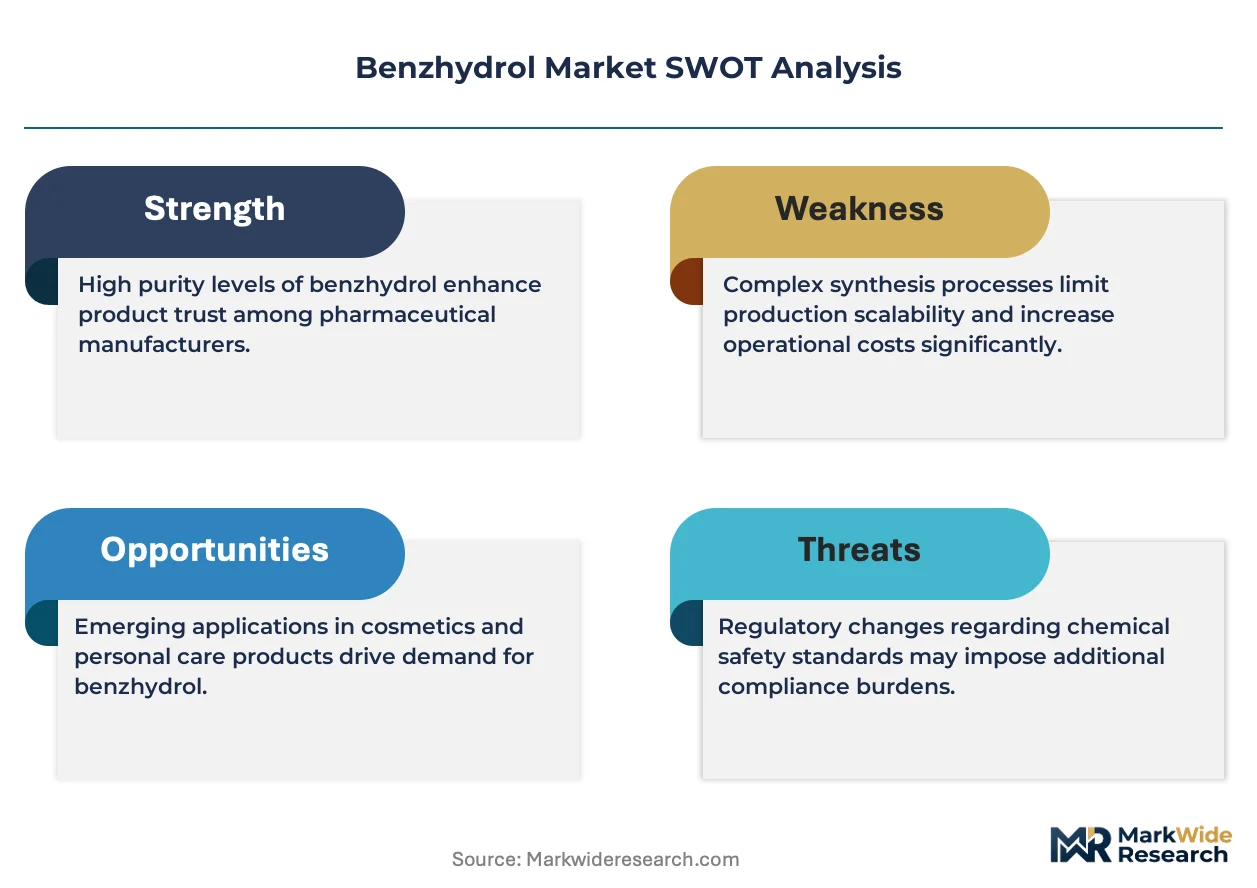
Pharmaceutical-grade certification requirements are splitting the benzhydrol supplier base into qualified API-grade producers and commodity traders, with REACH compliance in Europe and cGMP mandates in the United States forcing parallel qualification tracks that reshape competitive positioning.
Growth Catalysts
- Generic API expansion:Indian pharmaceutical manufacturers scale antihistamine production, pulling benzhydrol demand through Maharashtra's chemical corridor around Mumbai and Pune.
- REACH purity benchmarks:Cosmetic-grade supply into Europe tightens impurity thresholds, rewarding producers with dedicated pharmaceutical-grade infrastructure.
- Organometallic chemistry programs:Academic institutions across Asia-Pacific markets expand research applications, creating fastest-growing consumption segment for laboratory-grade material.
Market Restraints
- Benzophenone feedstock volatility:Sodium borohydride reduction economics tie directly to aromatic ketone pricing, compressing margin buffers for non-integrated producers.
- Residual solvent compliance:China's NMPA alignment with ICH Q3C guidelines forces reformulation of traditional reduction processes, raising capital burdens for legacy facilities.
- Grignard pathway substitution:Alternative synthetic routes using phenylmagnesium bromide threaten established reduction-based supply positions in commodity segments.
Strategic Opportunities
- CDSCO cosmetic-grade stability data:India's incremental testing mandates for personal care supply chain entry compress domestic producer timelines, creating first-mover advantages for qualified local suppliers.
- Continuous flow processing:Microreactor technology convergence with catalytic hydrogenation enables step-change efficiency in pharmaceutical-grade production.
- Direct institutional procurement:Academic and research buyers bypass traditional distribution layers through e-procurement platforms, opening channel innovation for laboratory-grade suppliers.
Industry Challenges
- cGMP certification timelines:FDA and EMA qualification cycles extend 18-24 months for new pharmaceutical-grade entrants, freezing capacity expansion decisions.
- Cross-border specification misalignment:Divergent pharmacopeial standards between USP, EP, and IP create formulation reconciliation burdens for multi-jurisdiction suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzhydrol Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical, Cosmetic, Industrial, Laboratory Application: Antioxidants, Solvents, Intermediates, Research Delivery Mode: Liquid, Powder, Granule, Paste Customer Type: Manufacturers, Distributors, Retailers, End Users |
| Companies Covered | Capot Chemical, Catapharma, Vasudha Chemicals Private, Rita Corporation, Pratap Organics Pvt. Ltd., Wuhan Sunrise Technology Development, Nanjing Xiongwei Chemical, Sigma-Aldrich Corporation, Tokyo Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzhydrol Market Trends and Innovations
Catalytic hydrogenation pathways and continuous processing architectures are actively reshaping production economics, while regulatory divergence between major jurisdictions forces parallel compliance investments.
Continuous flow microreactor systems employing supported palladium catalysts are supplanting batch sodium borohydride reduction in pharmaceutical-grade manufacturing. European API producers adopt these platforms to meet tightening residual solvent specifications under EMA guidance. The shift compresses cycle times from hours to minutes while eliminating boron-containing waste streams that complicate environmental compliance.
REACH authorization requirements for Substances of Very High Concern are extending testing obligations to benzhydrol impurities and degradation products entering cosmetic applications. ECHA's 2024 updated guidance on secondary alcohol classifications forces reformulation of fragrance intermediates and polymer stabilizers. German and French cosmetic formulators now demand comprehensive analytical packages that exceed traditional certificate-of-analysis standards.
Research buyers in South Korea and Japan consolidate laboratory-grade procurement through institutional framework agreements with single-source distributors. Sigma-Aldrich's channel control over academic networks faces pressure from regional competitors offering localized inventory and faster customs clearance. This concentration is most visible in Tokyo and Seoul, where national research funding agencies mandate preferred supplier lists for grant-funded purchases.
Benzhydrol Market Segmentation
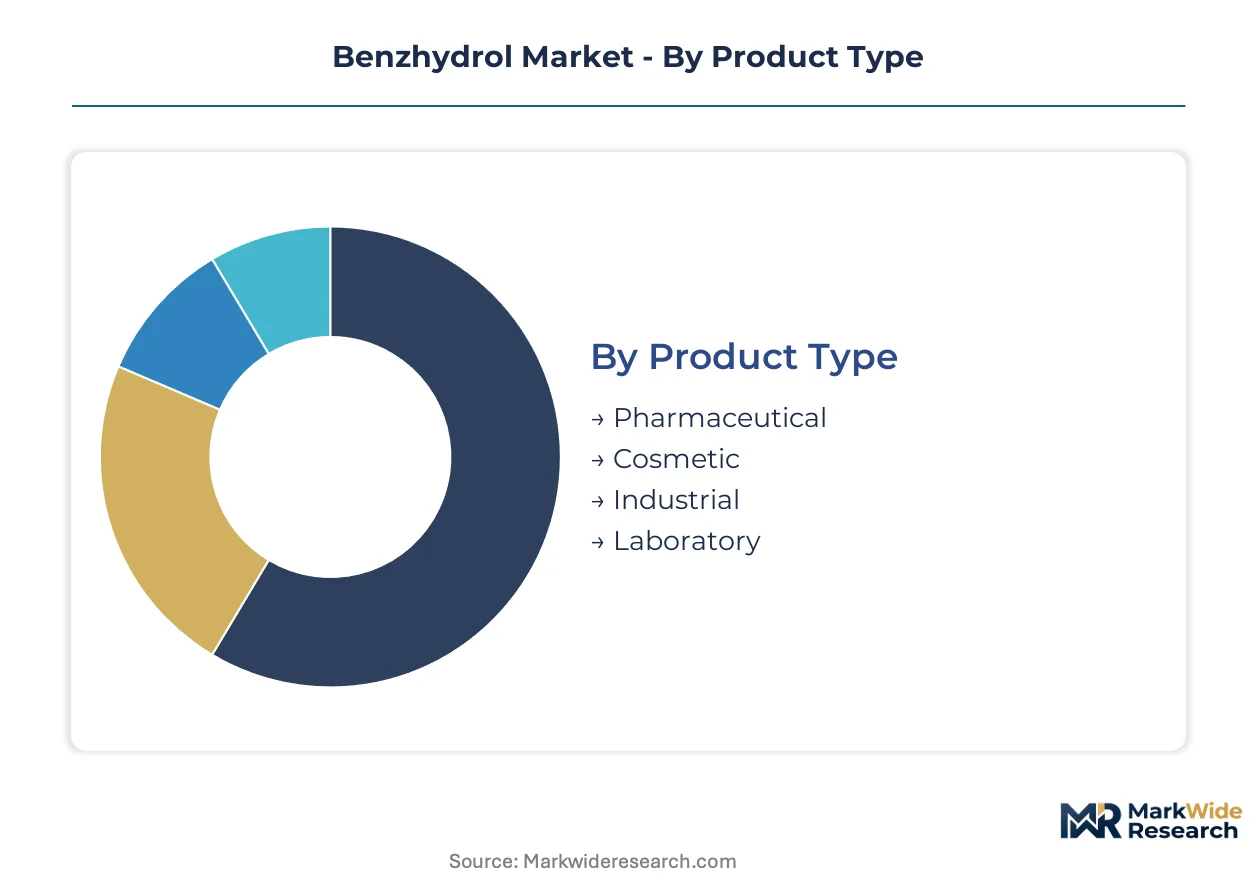
Benzhydrol demand fragments across certification tiers that command divergent pricing premiums and regulatory burdens. Understanding how product grades, application endpoints, and delivery formats align with customer procurement power exposes margin concentration points and qualification barriers.
Product Type:
Pharmaceutical-grade supply concentrates in domestic Indian and Chinese facilities serving export markets, while laboratory-grade flows disproportionately through distributors in Japan and South Korea.
- Pharmaceutical:USP-grade powder meeting FDA cGMP and EMA pharmacopeial standards commands the steepest certification premiums. Indian manufacturers around Maharashtra's Mumbai-Pune corridor anchor global supply for antihistamine API synthesis, with CDSCO stability mandates compressing domestic qualification timelines.
- Cosmetic:REACH-compliant grades face tightening impurity thresholds under ECHA's updated secondary alcohol classifications. German and French formulators now require comprehensive analytical packages exceeding traditional certificate-of-analysis standards for fragrance intermediates and polymer stabilizers entering personal care applications.
- Industrial:Antioxidant-grade liquid serves polymer stabilization with volume-based pricing and minimal regulatory overhead.
- Laboratory:Research-grade material expands most quickly as Tokyo and Seoul academic institutions scale organometallic chemistry programs.
Pharmaceutical commands the established base. The steepest expansion runs through Laboratory.
Application:
Cost tier stratification separates high-margin API intermediates from commodity antioxidant volumes, with research applications capturing premium pricing through institutional procurement frameworks.
- Intermediates:Antihistamine API building blocks drive the largest revenue concentration, with sodium borohydride reduction pathways dominating pharmaceutical-grade production. Capot Chemical's backward integration into diphenylmethane feedstock sustains cost competitiveness against Grignard substitution threats.
- Research:Organometallic chemistry programs across Asia-Pacific markets pull laboratory-grade consumption through institutional framework agreements. Sigma-Aldrich's channel control faces pressure from regional distributors offering localized inventory and faster customs clearance.
- Antioxidants:Polymer stabilization applications compete on throughput consistency and supply reliability rather than purity premiums.
- Solvents:Specialty solvent formulations serve niche extraction and purification processes with moderate specification requirements.
Intermediates lock in the revenue core. Research climbs the fastest on funding inflows.
Delivery Mode:
Volume scale and handling economics favor liquid formats for industrial antioxidants, while powder commands pharmaceutical-grade premiums through packaging integrity and contamination control.
- Liquid:Bulk tanker deliveries serve polymer stabilization with minimal conversion costs and established logistics infrastructure. Continuous flow processing adoption in European API manufacturing is compressing cycle times from hours to minutes while eliminating boron-containing waste streams.
- Powder:Pharmaceutical-grade powder requires controlled-atmosphere packaging and particulate monitoring to meet USP and EP dissolution specifications. Maharashtra's chemical belt producers invest in dedicated milling and classification equipment to serve Indian generic drugmakers.
- Granule:Intermediate flowability grades bridge powder and liquid handling for semi-automated manufacturing environments.
- Paste:High-concentration suspensions serve specialized coating and adhesive applications with limited scale.
Liquid anchors industrial volume. Powder captures margin expansion from tightening pharmacopeial standards.
Customer Type:
Procurement power concentrates with manufacturers integrating backward into captive benzhydrol production, while distributor intermediation faces disintermediation pressure from e-procurement platforms.
- Manufacturers:Pharmaceutical and cosmetic formulators with captive reduction capabilities or long-term supply contracts dominate volume offtake. Vasudha Chemicals serves this tier through dedicated R&D facilities aligned with Indian generic drugmaker specifications.
- Distributors:Traditional channel intermediaries face margin compression as academic and research buyers bypass layers through direct institutional procurement platforms.
- Retailers:Limited specialty chemical retailers serve small-batch laboratory and artisanal cosmetic producers with premium markups.
- End Users:Direct research institution purchasing concentrates in Tokyo and Seoul where national funding agencies mandate preferred supplier lists for grant-funded acquisitions.
Manufacturers control volume flows. End Users gain procurement autonomy fastest through platform disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CDSCO stability mandates for cosmetic-grade benzhydrol compress domestic qualification timelines, while China's NMPA alignment with ICH Q3C guidelines forces reformulation of traditional reduction processes across Asia-Pacific manufacturing bases.
India
Generic API expansion pulls benzhydrol demand through Maharashtra's chemical belt around Mumbai and Pune. CDSCO mandates incremental stability data for cosmetic-grade material entering the personal care supply chain. Vasudha Chemicals anchors supply through dedicated R&D facilities serving domestic generic drugmakers.
China
NMPA residual solvent limits under ICH Q3C guidelines raise capital burdens for legacy sodium borohydride reduction facilities. Continuous flow microreactor adoption accelerates in pharmaceutical-grade manufacturing to meet tightening specifications. Wuhan and Nanjing chemical clusters concentrate production capacity for export markets.
United States
FDA cGMP qualification cycles extend 18-24 months for new pharmaceutical-grade entrants, freezing capacity expansion decisions. Academic institutions scale organometallic chemistry programs, pulling laboratory-grade consumption through institutional procurement networks. Sigma-Aldrich dominates channel control over research-grade distribution.
Germany
ECHA's updated secondary alcohol classifications under REACH force reformulation of fragrance intermediates and polymer stabilizers. German cosmetic formulators demand comprehensive analytical packages exceeding traditional certificate-of-analysis standards. Continuous flow processing adoption accelerates to eliminate boron-containing waste streams.
Japan
Tokyo academic institutions consolidate laboratory-grade procurement through institutional framework agreements with single-source distributors. METI-funded research programs expand organometallic chemistry capacity, creating fastest-growing consumption segment. National funding agencies mandate preferred supplier lists for grant-funded purchases.
Benzhydrol Market Competitive Landscape
Player mix skews toward integrated chemical specialists with backward control over diphenylmethane feedstock and distributor-controlled laboratory-grade channels. The supplier base splits into qualified pharmaceutical-grade producers facing 18-24 month cGMP timelines and commodity traders serving industrial antioxidant applications. Three archetypes dominate: integrated feedstock controllers, research-grade channel specialists, and regional generic API suppliers. Competitive moves concentrate on continuous flow technology licensing and geographic expansion into Maharashtra's chemical corridor.
Within the integrated specialist tier, Capot Chemical represents feedstock-anchored positioning through backward integration into diphenylmethane supply. Vasudha Chemicals Private occupies a position exemplifying dedicated R&D alignment with domestic generic drugmaker specifications. Sigma-Aldrich Corporation anchors the laboratory-grade distribution archetype through channel control over academic and institutional procurement networks in Tokyo and Seoul.
| Leading Market Players |
|---|
| Capot Chemical |
| Catapharma |
| Vasudha Chemicals Private |
| Rita Corporation |
| Pratap Organics Pvt. Ltd. |
| Wuhan Sunrise Technology Development |
| Nanjing Xiongwei Chemical |
| Sigma-Aldrich Corporation |
| Tokyo Chemical Industry Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month cGMP qualification timelines for new pharmaceutical-grade entrants compress inventory buffers and concentrate pricing power with established Indian and Chinese producers holding active FDA and EMA certifications. This lead-time rigidity forces buyers into long-term offtake contracts that lock in premium spreads for qualified suppliers while squeezing commodity traders serving industrial antioxidant segments.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade powder and industrial liquid formats, with USP-grade material commanding substantial premiums over REACH-compliant cosmetic grades and unqualified antioxidant supply. Price differentiation rests on cGMP infrastructure investment, residual solvent testing burdens, and backward integration into diphenylmethane feedstock. Cost compression in commodity industrial tiers is intensifying because Grignard pathway substitution threatens sodium borohydride reduction economics. Generic API manufacturers in Maharashtra exhibit highest price sensitivity, while Tokyo academic institutions show lowest sensitivity through institutional framework agreements.
Supply Chain Analysis
Strategic stockpiling of benzophenone feedstock dominates inventory strategy among integrated producers, while non-integrated buyers face just-in-time vulnerability to aromatic ketone price volatility. Supply concentrates in India, China, and Germany, with Maharashtra's Mumbai-Pune corridor anchoring pharmaceutical-grade output. Production draws from diphenylmethane, sodium borohydride, and phenylmagnesium bromide inputs. Single-source vulnerability around palladium catalyst supply for continuous flow microreactors poses structural risk. Distribution runs through distributor-controlled channels for laboratory-grade material and direct manufacturer relationships for API-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow microreactor adoption represents a technological inflection reshaping production economics, while REACH authorization requirements for Substances of Very High Concern impose regulatory compression on cosmetic-grade formulation. These dual forces create asymmetric opportunity for positioned players.
For Market Incumbents: Fortify certification moats through accelerated cGMP timeline investments and captive diphenylmethane supply integration. Capot Chemical's backward integration model demonstrates feedstock control as defensive leverage against Grignard substitution threats. Prioritize continuous flow licensing partnerships to displace batch reduction capacity before regulatory residual solvent limits tighten further. For New Entrants and Emerging Players: CDSCO cosmetic-grade stability data services present a service-layer gap where incumbents under-serve domestic Indian formulators facing compressed qualification timelines. Target Maharashtra's expanding generic drugmaker base with dedicated analytical packages exceeding certificate-of-analysis standards. Pursue direct e-procurement platform relationships with Tokyo and Seoul academic institutions to bypass Sigma-Aldrich's channel control. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous flow pharmaceutical-grade manufacturing as legacy sodium borohydride facilities face NMPA-mandated reformulation burdens. Five-to-ten year viability favors integrated specialists with backward feedstock control and active multi-jurisdiction certifications. Monitor ECHA secondary alcohol classification enforcement as signal for cosmetic-grade margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Microreactor Adoption | Eliminates boron-containing waste streams while compressing cycle times for EMA compliance. |
| Backward Integration into Diphenylmethane | Secures feedstock cost control against benzophenone volatility for sodium borohydride reduction economics. |
| CDSCO Stability Data Service Expansion | Captures first-mover advantage in India's compressed cosmetic-grade qualification timeline environment. |
| Direct Institutional E-Procurement Platform | Bypasses distributor intermediation in Tokyo and Seoul academic procurement networks. |
| Multi-Jurisdiction cGMP Certification Investment | Builds parallel FDA and EMA qualification tracks for cross-border API-grade supply access. |
Research Methodology
Desk research of customs trade data, CDSCO regulatory filings, and ECHA authorization databases preceded structured interviews with plant managers at Maharashtra chemical facilities, procurement leads at Indian generic drugmakers, and technical R&D directors at European API producers. Primary fieldwork with distribution channel partners and academic procurement officers in Tokyo and Seoul validated secondary findings. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across certification tiers, application endpoints, and regional production hubs informed analytical framework construction over the projection horizon. Segmentation dimensions modeled include pharmaceutical versus industrial grade tiers, antihistamine API versus research versus antioxidant end-use industries, and powder versus liquid packaging formats. CAGRs derived from production capacity buildout trajectories, generic drugmaker expansion plans, and organometallic chemistry program funding inflows across Asia-Pacific markets.
Forecasts assume regulatory continuity in FDA cGMP, EMA pharmacopeial, and REACH authorization regimes; material policy shifts would require re-modeling. Specific risk factors include benzophenone feedstock price spikes, palladium catalyst supply disruption, and divergence in USP-EP-IP pharmacopeial standards. Practitioners should keep alternative scenarios live as ECHA secondary alcohol classification enforcement and NMPA residual solvent alignment evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Aluminum Chemicals Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Global Lactate Salts Market
Chemicals
Elemental Fluorine Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Chemical Distribution Market
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Whitening Ingredients Market
Chemicals
Resorcinol Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Coagulant Market