
 3D Printing Applications Polymers Market | 2026-2036
3D Printing Applications Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Applications Polymers Market Outlook
REACH compliance is realigning the cost-of-entry calculus for polymer suppliers serving European aerospace and medical device channels. BASF SE leverages its integrated materials science platform to sustain formulation leadership across high-performance thermoplastics. Evonik Industries AG anchors its position through specialized polyamide 12 powders optimized for selective laser sintering workflows. Stratasys Ltd. competes by controlling proprietary filament ecosystems that lock in repeat consumables demand.
3D printing applications polymers encompass thermoplastics, thermosetting resins, composite materials, and filaments engineered for layer-by-layer additive manufacturing, typically requiring melt flow indices between 1-10 g/10min and thermal stability above 200°C to prevent degradation during extrusion or sintering. These materials enable functional prototyping, direct tooling, and end-use production across industries seeking geometric complexity without mold capital. Thermoplastics dominate current volume flows due to their recyclability and broad printer compatibility, while composite materials represent the fastest-expanding margin pool as carbon-fiber-reinforced grades penetrate structural aerospace and automotive applications. Fused deposition modeling filaments occupy the most mature price tier, whereas selective laser sintering powders command premium positioning tied to powder bed fusion throughput and surface finish requirements.
The EU Green Deal and REACH framework impose recyclability and substance restriction obligations that filter material eligibility for European end users. FDA 510(k) clearance pathways for patient-specific polymer implants shape healthcare demand specifications in the United States, while China's GB standards and MIIT directives govern industrial additive manufacturing material certifications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode project economics on cross-border contracts.
Market Dynamics
REACH substance restrictions and EU Green Deal recyclability mandates are compressing the addressable polymer formulation space for European aerospace and medical channels, forcing suppliers to rebuild certification portfolios around bio-based feedstocks and closed-loop powder recovery systems.
Growth Catalysts
- Aerospace lightweighting mandates:Cabin bracket and ducting applications in commercial aviation are specifying carbon-fiber-reinforced polyamide grades to meet fuel efficiency targets without metal tooling lead times.
- REACH compliance recertification:European polymer suppliers investing in reformulation are capturing medical device channel volume as competitors exit restricted substance categories.
- Germany's industrial cluster density:Concentrated SLS powder production and filament extrusion capacity around Düsseldorf and Frankfurt reduces logistics friction for just-in-time aerospace supply contracts.
Market Restraints
- PA12 powder supply concentration:Specialized polyamide 12 feedstock for selective laser sintering flows through a narrow supplier base concentrated in European petrochemical corridors, creating input vulnerability.
- Thermal stability thresholds:Melt flow index requirements between 1-10 g/10min and degradation resistance above 200°C eliminate commodity thermoplastics from aerospace and medical qualification pathways.
- Recyclability mandate friction:EU Green Deal circularity requirements impose reverse logistics costs on powder bed fusion operations that thermosetting resin competitors avoid through landfill disposal.
Strategic Opportunities
- Composite material white space:Carbon-fiber-reinforced grades remain underpenetrated in structural automotive applications where geometric complexity justifies additive tooling avoidance.
- FDA 510(k) pathway specialization:Patient-specific implant polymer certification expertise creates defensible positioning in US healthcare procurement where reimbursement codes favor cleared materials.
- China MIIT industrial additive directives:Domestic certification requirements for GB-standard polymer powders are localizing supply chain decisions and creating partnership entry points for compliant foreign formulators.
Industry Challenges
- Cross-border regulatory divergence:Reconciliation between EU REACH substance restrictions, FDA biocompatibility protocols, and China MIIT material certifications multiplies reformulation costs for global contract bids.
- Powder bed fusion technician scarcity:Specialized SLS machine operation and powder handling certification programs lag installed base expansion, constraining throughput at contract manufacturing facilities.
- Legacy injection molding integration:Hybrid production environments require polymer lots qualified across both subtractive and additive workflows, extending validation timelines for tier-one automotive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Applications Polymers Market |
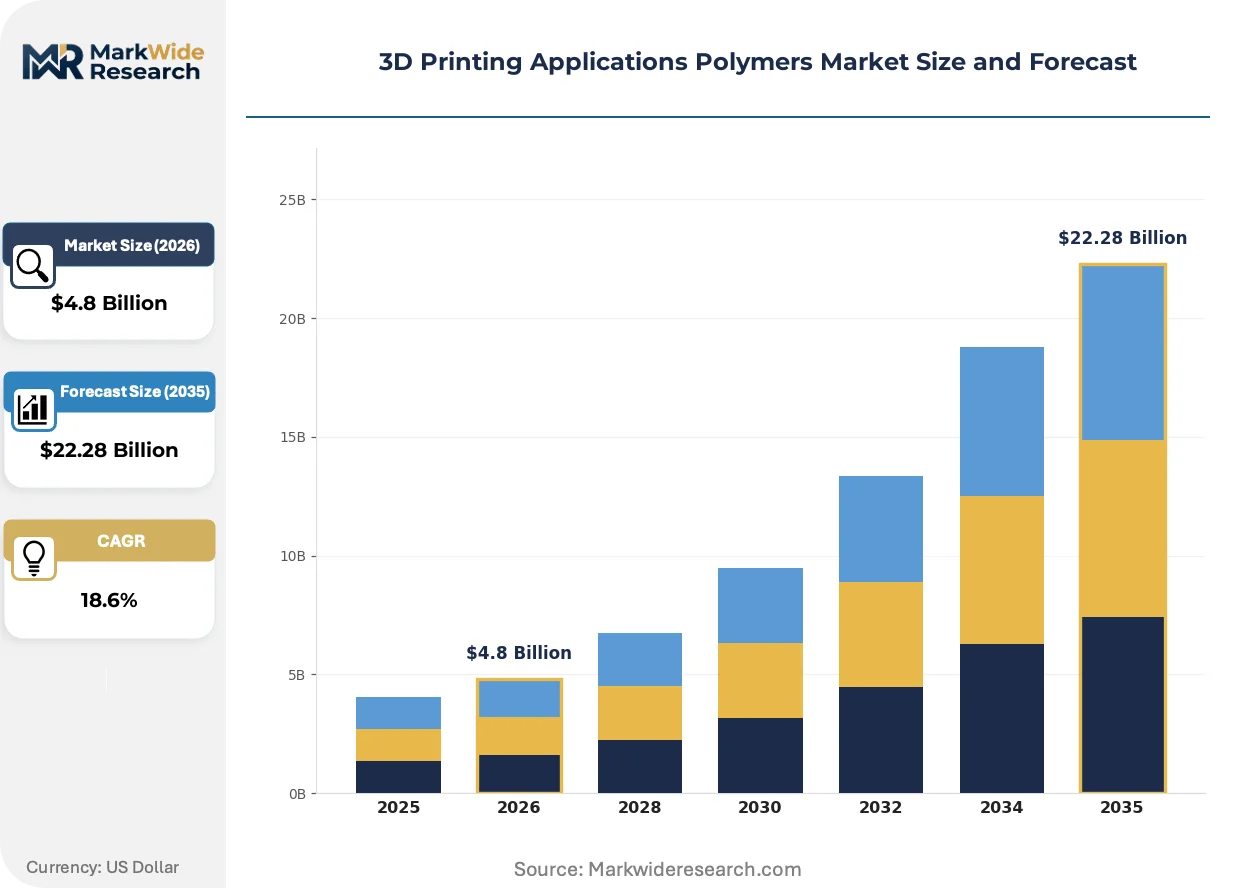
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosetting Resins, Composite Materials, Filaments End User: Aerospace, Automotive, Healthcare, Consumer Goods Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Binder Jetting Application: Prototyping, Tooling, Production Parts, Customization |
| Companies Covered | Stratasys Ltd., Arkema S.A., BASF SE, Evonik Industries AG, 3D Systems Corporation, Covestro AG, Formlabs Inc., Henkel AG & Co. KGaA, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Applications Polymers Market Strategic Shifts
Material science convergence with regulatory compliance engineering is compressing the traditional separation between polymer formulation and end-use certification, collapsing supplier selection criteria into integrated qualification bundles rather than discrete performance specifications.
Continuous fiber-reinforced thermoplastic printing is absorbing structural load-bearing applications previously reserved for machined aluminum and composite layups. Aerospace tier-one suppliers are qualifying these grades for non-critical brackets and ducting at compressed development cycles. The technology is absorbing margin from conventional tooling houses as lead time advantages compound with weight reduction specifications.
EU Green Deal circular economy action plan implementation timelines are hardening recyclability verification requirements for polymer powders and filaments entering European aerospace and medical channels. Industrial users must demonstrate closed-loop material recovery rates or face procurement exclusion from public contract vehicles. German industrial clusters around Düsseldorf are responding with captive powder regeneration facilities that consolidate reformulation and requalification under single-site control.
Consolidated procurement specifications are displacing fragmented material selection across multi-site manufacturing networks. Automotive and aerospace OEMs are mandating enterprise-wide polymer grade approval lists that eliminate site-level formulation autonomy. This concentration is most visible in Germany's Mittelstand supplier base, where family-owned compounders face consolidation pressure to achieve scale thresholds for preferred supplier status.
3D Printing Applications Polymers Market Segmentation
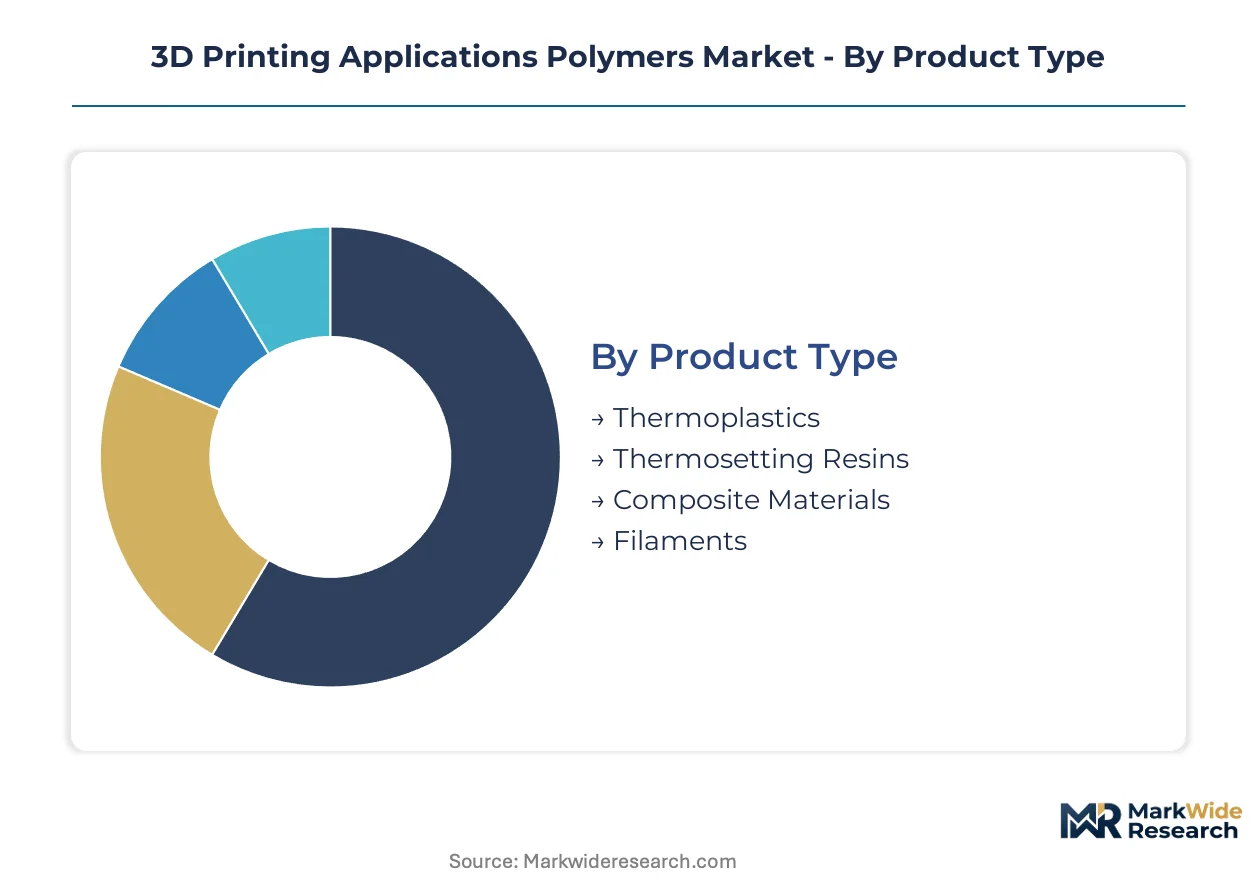
Material selection in 3D printing polymers hinges on thermal stability thresholds and regulatory qualification pathways rather than commodity pricing. Buyers prioritize melt flow indices between 1-10 g/10min and degradation resistance above 200°C to secure aerospace and medical device certifications. Segmentation reveals how formulation chemistry, end-use specifications, and printer technology interlock to determine addressable margin pools.
Product Type:
Cost tier differentiation separates recyclable thermoplastics from premium composite grades, with powder bed fusion throughput requirements driving procurement decisions at the specification stage.
- Thermoplastics:Polycarbonate, ABS, and polyamide formulations dominate current volume flows due to broad printer compatibility and closed-loop recyclability. Demand concentrates in Germany's industrial cluster around Düsseldorf and Frankfurt, where automotive suppliers qualify materials for hybrid injection molding and additive workflows. REACH compliance mandates favor these grades over thermosetting alternatives.
- Composite Materials:Carbon-fiber-reinforced polyamide and continuous fiber thermoplastic grades absorb structural load-bearing applications previously reserved for machined aluminum. Aerospace tier-one suppliers in France and Germany specify these materials for non-critical brackets and ducting to meet fuel efficiency targets. EU Green Deal circularity requirements impose reverse logistics costs that thermosetting competitors avoid.
- Filaments:FDM feedstocks occupy the most mature price tier with standardized diameter tolerances and color consistency requirements.
- Thermosetting Resins:Epoxy and acrylate formulations serve stereolithography workflows where surface finish precision outweighs recyclability concerns.
Volume sits with Thermoplastics; growth tilts toward Composite Materials.
End User:
Application maturity varies sharply by sector, with aerospace lightweighting mandates and FDA 510(k) clearance pathways creating divergent qualification timelines.
- Aerospace:Cabin bracket and ducting applications specify carbon-fiber-reinforced grades to bypass metal tooling lead times. EASA certification requirements and REACH substance restrictions compress the addressable formulation space, forcing suppliers to rebuild portfolios around bio-based feedstocks.
- Healthcare:Patient-specific implants and surgical guides demand biocompatible polyamide 12 powders with ISO 10993 and FDA 510(k) clearance. US reimbursement codes favor cleared materials, creating defensible positioning for certified formulators.
- Automotive:Prototyping and direct tooling applications concentrate in Germany's Mittelstand supplier base, where enterprise-wide polymer grade approval lists eliminate site-level formulation autonomy.
- Consumer Goods:Customization and low-volume production runs prioritize cost efficiency over thermal performance thresholds.
Procurement concentration favors Aerospace; regulatory complexity peaks in Healthcare.
Technology:
Printer hardware lock-in determines material format requirements, with powder bed fusion and filament extrusion representing incompatible supply ecosystems.
- Fused Deposition Modeling:Filament-based systems command the broadest installed base and lowest capital entry point. Proprietary filament ecosystems lock in repeat consumables demand for equipment manufacturers.
- Selective Laser Sintering:Polyamide 12 powders for SLS workflows command premium positioning tied to throughput and surface finish requirements. Specialized feedstock flows through a narrow supplier base concentrated in European petrochemical corridors.
- Stereolithography:Resin vat polymerization serves dental and jewelry applications where layer resolution below 50 microns justifies material costs.
- Binder Jetting:Powder-based systems with liquid binding agents enable sand casting cores and metal infiltration precursors at production scale.
Installed base saturation defines Fused Deposition Modeling; margin expansion concentrates in Selective Laser Sintering.
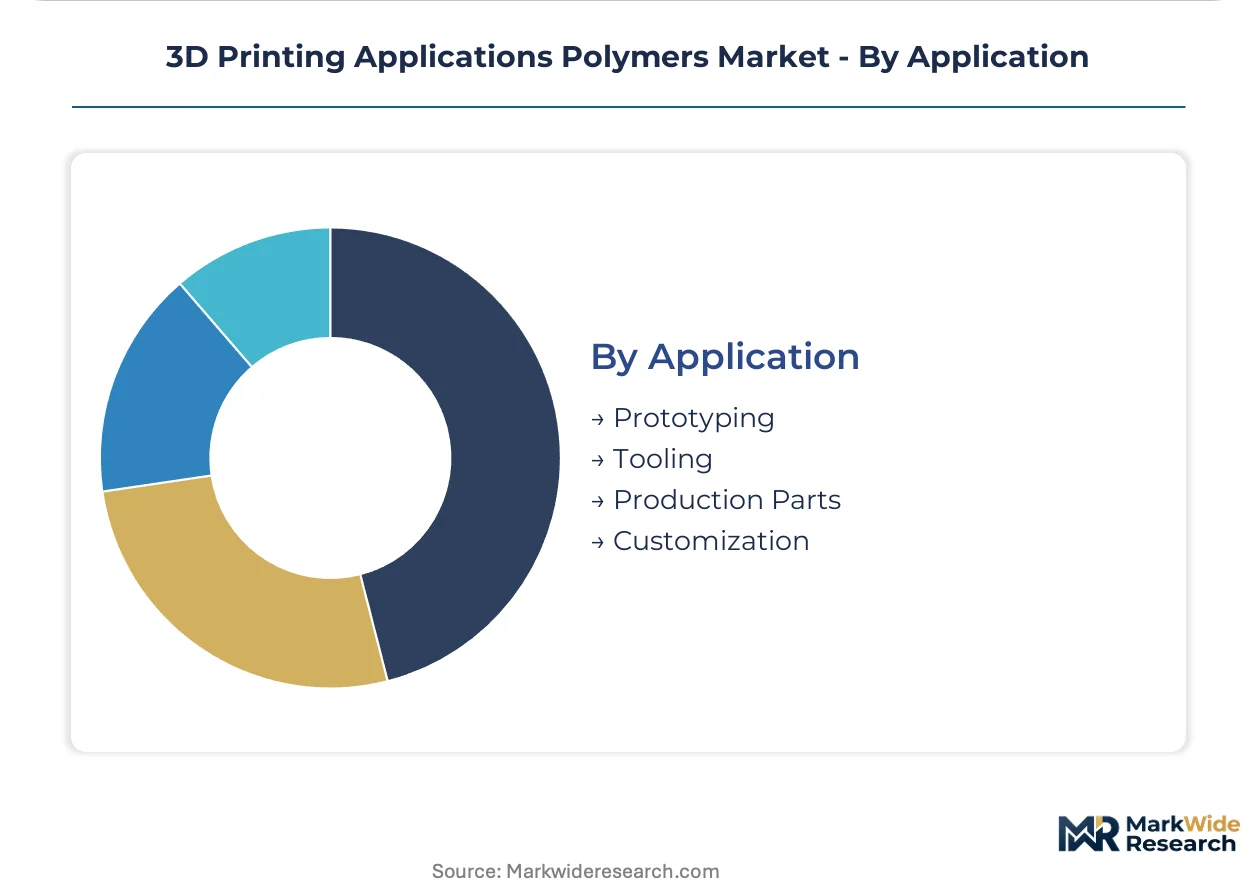
Application:
Functional progression from validation to end-use manufacturing determines material performance specifications and lot size economics.
- Prototyping:Form and fit validation drives demand for economical ABS and PLA grades with rapid print speeds and minimal post-processing. Automotive design studios in Stuttgart and Munich consume high volumes for iterative concept development.
- Production Parts:Direct manufacturing of end-use components requires material lots qualified across thermal cycling and mechanical load profiles. Aerospace ducting and medical device housings in the US and Germany specify certified polyamide and polycarbonate grades.
- Tooling:Injection mold inserts and jigs exploit geometric complexity without hardened steel lead times.
- Customization:Patient-specific implants and consumer personalization leverage layer-by-layer fabrication to eliminate mold capital entirely.
Revenue scale favors Production Parts; volume throughput remains anchored in Prototyping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial cluster around Düsseldorf and Frankfurt concentrates polymer supply capacity within the EU's REACH regulatory perimeter, while aerospace lightweighting mandates in France and medical device certification requirements in the United States create divergent demand specifications across jurisdictions.
United States
FDA 510(k) clearance pathways for patient-specific polymer implants concentrate healthcare demand specifications in the Boston and Minneapolis medical device corridors. The agency's biocompatibility protocols shape procurement decisions for polyamide 12 powders used in surgical guides. Aerospace tier-one suppliers in Seattle and Wichita specify carbon-fiber-reinforced grades for non-critical brackets to bypass metal tooling lead times.
Germany
REACH substance restrictions and EU Green Deal recyclability mandates compress the addressable formulation space for aerospace and medical channels. ECHA enforcement actions force suppliers to rebuild certification portfolios around bio-based feedstocks. The Düsseldorf-Frankfurt industrial cluster hosts captive powder regeneration facilities that consolidate reformulation and requalification under single-site control.
France
EASA certification requirements for cabin bracket and ducting applications specify carbon-fiber-reinforced polyamide grades to meet fuel efficiency targets. ANSM oversight of medical device materials filters polymer eligibility for patient-specific implants. The Toulouse aerospace corridor concentrates SLS powder demand from Airbus tier-one suppliers seeking geometric complexity without mold capital.
China
MIIT directives and GB standards govern industrial additive manufacturing material certifications, localizing supply chain decisions for polymer powders. The Yangtze River Delta manufacturing belt concentrates prototyping demand from automotive design studios. Domestic certification requirements create partnership entry points for compliant foreign formulators seeking access to state-contracted aerospace programs.
Japan
METI industrial policy supports additive manufacturing adoption in precision machinery and dental applications. PMDA oversight of patient-specific implants shapes biocompatible polymer specifications for Tokyo and Osaka medical device manufacturers. The Nagoya aerospace supply base qualifies continuous fiber-reinforced thermoplastics for non-critical structural components.
3D Printing Applications Polymers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. BASF SE and Covestro AG leverage integrated materials science platforms to sustain formulation leadership across high-performance thermoplastics, while Stratasys Ltd. and 3D Systems Corporation control proprietary printer ecosystems that lock in repeat consumables demand. Market structure fragments across three archetypes: petrochemical-backed compounders, equipment-integrated filament suppliers, and specialized powder formulators. Dominant competitive moves include strategic partnerships between polymer suppliers and printer manufacturers, plus capacity expansion in powder bed fusion feedstock production.
Among diversified chemical conglomerates, BASF SE and Evonik Industries AG occupy positions anchored in European petrochemical corridors, with the latter exemplifying specialization through polyamide 12 powder optimization. Stratasys Ltd. represents the equipment-integrated tier, its proprietary filament ecosystems creating captive demand structures that pure-play material suppliers cannot replicate.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| Arkema S.A. |
| BASF SE |
| Evonik Industries AG |
| 3D Systems Corporation |
| Covestro AG |
| Formlabs Inc. |
| Henkel AG & Co. KGaA |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
PA12 powder feedstock costs cascade through three distinct pricing tiers as material moves from European petrochemical corridors through SLS powder formulators to aerospace tier-one suppliers. REACH compliance investments and EU Green Deal circularity requirements accumulate at each handoff, compressing margins for non-integrated compounders while captive regeneration facilities capture value recovery.
Pricing Analysis
Lead-time premiums dominate pricing architecture, with spot inventory of certified polyamide 12 powders trading at discounts against six-month forward contracts for aerospace-qualified lots. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared medical grades from industrial prototyping filaments and commodity ABS feedstocks. Price differentiation hinges on certification tier and volume scale, with automotive procurement committees driving hardest bargains on standardized polycarbonate grades. Cost compression in FDM filament tiers is intensifying because Chinese extrusion capacity expansion erodes European producer margins.
Supply Chain Analysis
Specialized polyamide 12 feedstock draws from a narrow supplier base concentrated in Germany, France, and Belgium, where petrochemical integration sustains precursor availability. Raw material dependencies center on laurolactam monomer, carbon fiber tow, and bio-based feedstock certifications. Single-source vulnerability pervades medical-grade powder supply, with ECHA substance restrictions threatening reformulation timelines for cleared materials. Distribution runs through direct mill relationships for aerospace contracts and distributor networks for prototyping filaments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with powder regeneration capabilities and printer ecosystem control representing the decisive upstream and downstream levers players are pursuing.
For Market Incumbents: Acquire captive powder regeneration facilities to consolidate reformulation and requalification under single-site control. BASF SE and Evonik Industries AG must defend against equipment-integrated filament suppliers by locking aerospace tier-one suppliers into long-term offtake agreements with embedded circularity guarantees. REACH substance restriction shifts threaten incumbent portfolios; backward integration into bio-based feedstock production secures compliance pathways. For New Entrants and Emerging Players: Launch via FDA 510(k) pathway specialization in US healthcare corridors, where reimbursement codes favor cleared materials and create defensible positioning. Target carbon-fiber-reinforced composite grades for structural automotive applications in Germany's Mittelstand supplier base, where enterprise-wide polymer grade approval lists concentrate procurement decisions. White-space exists in continuous fiber thermoplastic printing for non-critical aerospace brackets. For Investors and Strategic Acquirers: EASA certification completion for cabin bracket applications is the leading indicator that carbon-fiber-reinforced polyamide grades are crossing from prototyping to production. Over the projection horizon, vertically integrated compounders with captive powder regeneration and printer ecosystem partnerships represent the viable acquisition archetype. Watch for MIIT GB-standard certification announcements in China as signals of supply chain localization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | REACH compliance investments reposition European suppliers ahead of ECHA substance restriction expansions. |
| Captive Powder Regeneration Facility Buildout | EU Green Deal circularity requirements favor single-site control over reformulation and requalification timelines. |
| FDA 510(k) Clearance Pathway Investment | US reimbursement codes lock in cleared materials against uncertified competitors in patient-specific implants. |
| Printer Ecosystem Partnership | Proprietary filament lock-in replicates Stratasys Ltd.'s consumables capture model for SLS powder workflows. |
| MIIT GB-Standard Certification | Domestic material approvals open state-contracted aerospace programs to compliant foreign formulators. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with polymer formulation scientists, aerospace procurement managers, SLS machine operators, and medical device regulatory affairs directors validated demand specifications and certification timelines. ECHA restriction updates, FDA 510(k) submission databases, and MIIT directive releases provided secondary cross-checks. Bottom-up polymer grade demand modeling triangulated against top-down aerospace and automotive production forecasts.
Segment-level granularity modeled material type, end-use industry, printer technology, and application maturity across the analysis window. Product-type splits captured thermoplastic, composite, filament, and thermosetting resin flows. End-user segmentation tracked aerospace, healthcare, automotive, and consumer goods procurement patterns. Technology dimensions distinguished FDM, SLS, stereolithography, and binder jetting material requirements. CAGRs derived from installation base expansion rates and content-per-application assumptions.
The model assumes a particular technology adoption path; alternative pathways for continuous fiber-reinforced thermoplastic printing would alter the outlook if aerospace qualification timelines accelerate. Forecasts reflect assumptions about REACH substance restriction enforcement, EASA certification completion rates, and China MIIT localization timelines. Regulatory divergence between jurisdictions, powder bed fusion technician scarcity, and legacy injection molding integration friction warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Global 3D Printing Filament Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Aerospace 3D Printing Materials Market