
 APP and SBS Modified Bitumen Membrane Market | 2026-2036
APP and SBS Modified Bitumen Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
APP and SBS Modified Bitumen Membrane Market Insights
REACH compliance is decoupling commodity bitumen suppliers from premium membrane manufacturers across Europe. Soprema Group leverages captive polymer-modification capacity to sustain margin structures that commodity assemblers cannot replicate. Sika AG anchors its position through formulation chemistry leadership in self-adhesive SBS grades. Oriental Yuhong dominates Asia-Pacific production scale, operating integrated bitumen refining and membrane fabrication complexes that control raw material cost volatility.
APP and SBS modified bitumen membranes are asphalt-based waterproofing sheets reinforced with polyester or fiberglass mats and plasticized with atactic polypropylene or styrene-butadiene-styrene rubber to achieve flexibility from minus twenty degrees Celsius to over ninety degrees Celsius; they serve primarily as weatherproof barriers in low-slope roofing and below-grade waterproofing. The SBS segment leads value generation owing to superior elasticity in cold-climate applications where thermal cycling stresses crack APP formulations. Waterproofing applications are expanding fastest as urban densification drives underground construction and green roof assemblies demand redundant membrane protection. Direct sales channels capture the largest margin pools by locking in specification control with national contractor networks and bypassing distributor markups on large commercial projects.
The EPA's stormwater management rules and the EU F-Gas Regulation's indirect pressure on building envelope efficiency are reshaping product certification requirements and installation standards for membrane systems in their respective jurisdictions. Germany's KBA and France's ANSM do not regulate this sector, but national building codes under EU CPR framework mandate CE-marked membranes with declared fire performance and durability characteristics. Stakeholders must monitor polymer supply chain concentration and decide whether backward integration into SBS block copolymer production offers insulation from petrochemical price swings.
Market Dynamics
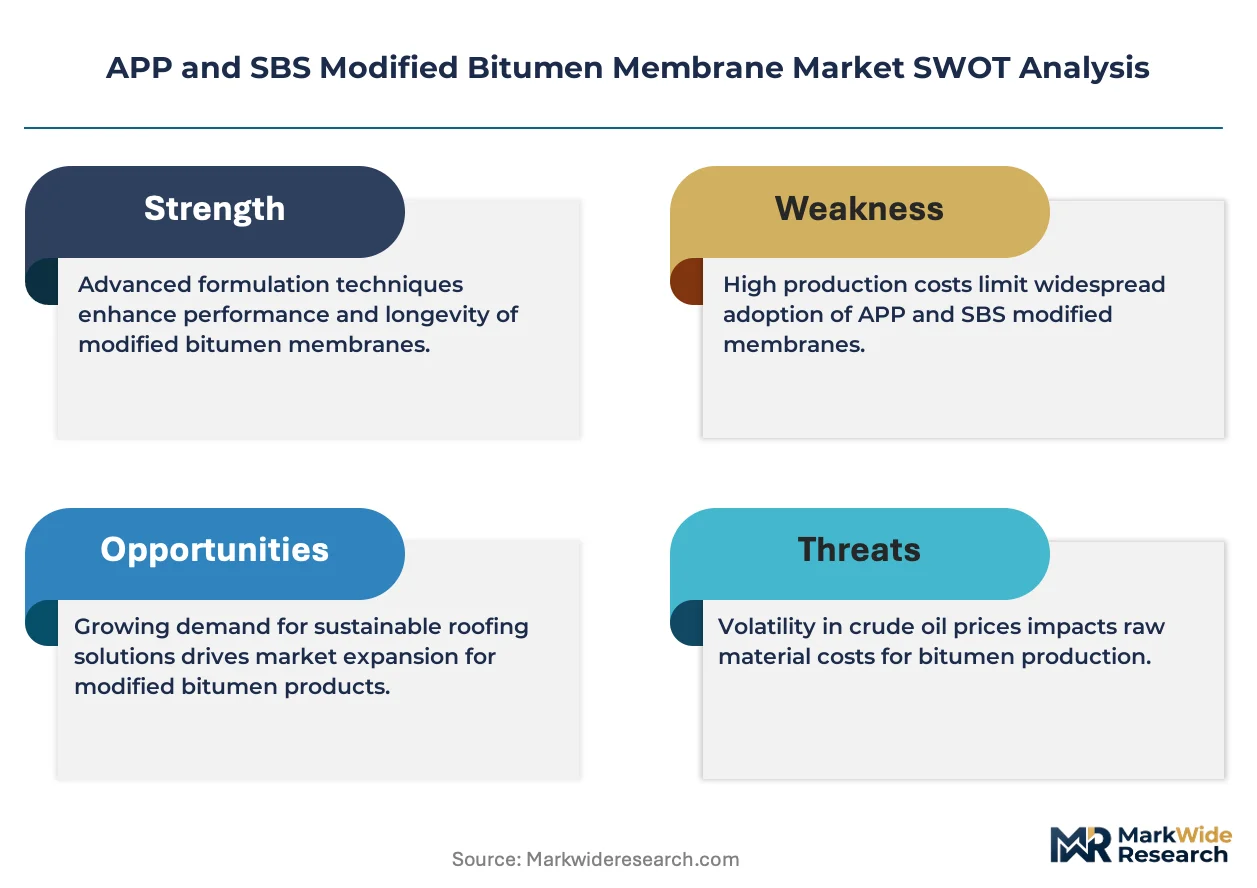
Polymer supply chain concentration is forcing membrane manufacturers to choose between captive SBS block copolymer production and exposure to petrochemical price volatility that compresses margin structures.
Growth Catalysts
- EU Green Deal building renovation targets:Energy-efficiency mandates across Germany, France, and Italy are accelerating commercial roof replacement cycles and tightening thermal performance standards for membrane assemblies.
- Urban densification:Underground construction expansion in Shanghai, Tokyo, and Singapore is driving waterproofing demand for basement and tunnel applications requiring redundant membrane protection.
- SBS cold-climate elasticity:Superior thermal cycling performance in sub-zero temperatures is displacing APP formulations across Nordic and Canadian low-slope roofing specifications.
Market Restraints
- Styrene-butadiene-styrene feedstock volatility:Butadiene price swings tied to naphtha cracking economics create unpredictable raw material cost structures for non-integrated manufacturers.
- Polymer supplier concentration:SBS block copolymer production clusters in South Korea, Taiwan, and the US Gulf Coast expose membrane fabricators to geographic supply disruption risks.
- APP brittleness threshold:Thermal stress cracking below minus ten degrees Celsius limits APP membrane deployment in northern climate zones regardless of cost advantages.
Strategic Opportunities
- Green roof assembly penetration:Vegetated roofing systems in Stuttgart, Copenhagen, and Toronto require dual-membrane waterproofing redundancy that doubles membrane specification per project.
- Self-adhesive SBS grade expansion:Torch-free installation chemistry eliminates open-flame permits and insurance complications, unlocking urban retrofit projects with fire-code restrictions.
- Direct contractor channel development:Bypassing distributor markups through national roofing contractor network partnerships captures margin pools currently absorbed by intermediaries.
Industry Challenges
- Certified installer scarcity:Proper heat-welding and self-adhesive application requires skilled labor that outpaces training program output in rapidly expanding markets.
- REACH compliance timeline compression:ECHA substance evaluation deadlines force reformulation cycles that disrupt production scheduling and inventory management.
- Legacy roof substrate compatibility:Existing built-up roofing adhesion failures create liability exposure when modified bitumen overlays bond unpredictably to aged asphalt surfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APP and SBS Modified Bitumen Membrane Market |
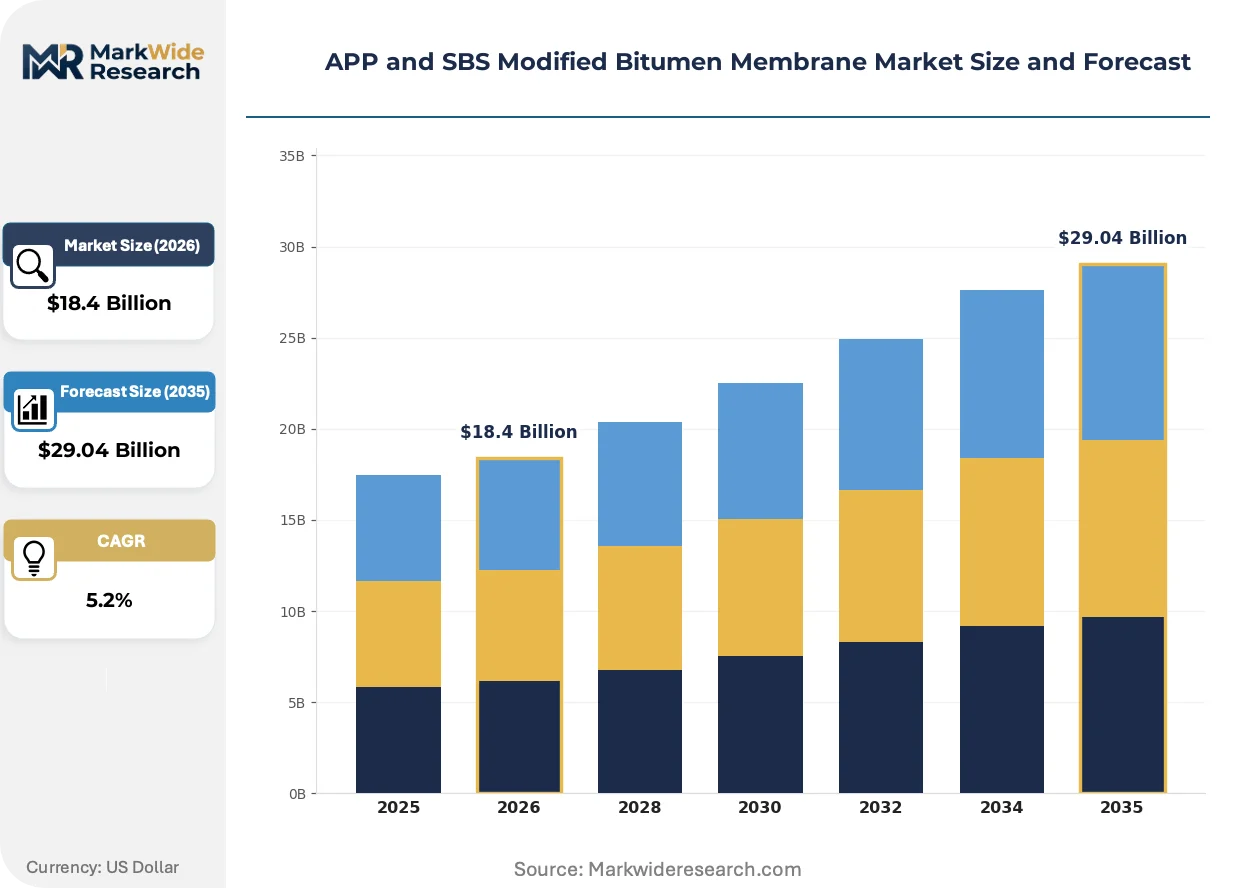
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $29.04 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: APP, SBS, Reinforced, Unreinforced Application: Residential Roofing, Commercial Roofing, Industrial Roofing, Waterproofing End User: Contractors, Builders, Architects, Property Owners Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | GAF Materials Corporation, Soprema Group, Sika AG, Johns Manville, IKO Industries Ltd, BMI Group, Oriental Yuhong, Carlisle Companies, Inc., TehnoNICOL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APP and SBS Modified Bitumen Membrane Market Trends and Innovations
Formulation chemistry advances and installation method evolution are compressing the performance gap between premium and standard membrane grades while reshaping channel economics.
Self-adhesive SBS membrane technology is unifying cold-application convenience with torch-applied durability. Commercial roofing contractors in fire-restricted urban cores are specifying these grades for high-rise retrofits where open-flame permits face extended approval timelines. The technology is unifying two previously separate product categories into a single specification standard that simplifies inventory and reduces jobsite complexity.
REACH substance restrictions under ECHA evaluation are eliminating certain plasticizers and flame retardants from membrane formulations. Manufacturers must reformulate to maintain CE marking compliance under the EU CPR framework without degrading fire performance or low-temperature flexibility. German and French building code enforcement is driving fastest adoption of compliant grades as national inspectors tighten documentation requirements.
Specification authority is migrating from distributor sales representatives to national contractor technical directors. Large commercial roofing firms in the US and Germany are consolidating vendor relationships to secure volume pricing and dedicated technical support. This concentration is most visible in the North American low-slope segment where national account structures now lock in three-year supply agreements with single-source membrane providers.
APP and SBS Modified Bitumen Membrane Market Segmentation
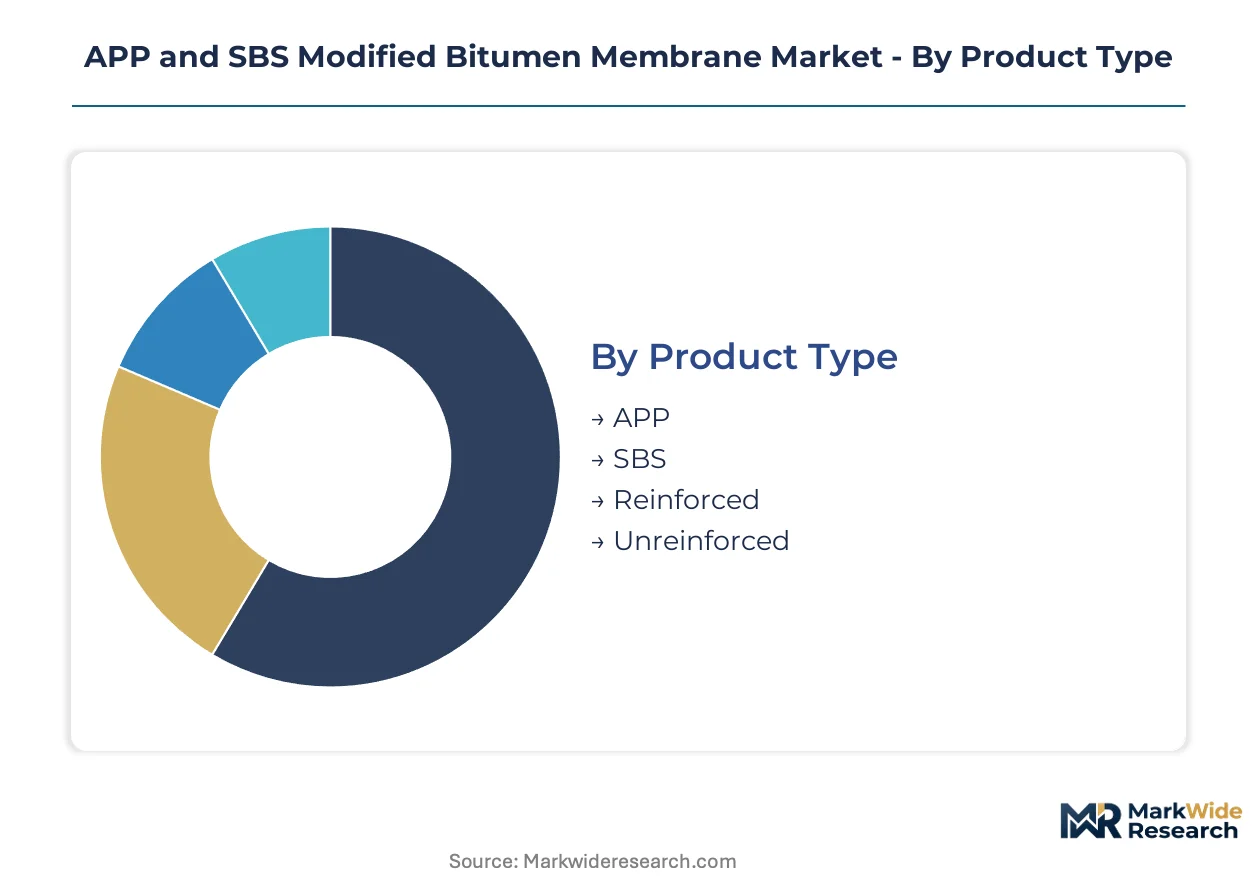
Segmentation in the APP and SBS modified bitumen membrane market reveals how specification authority, installation constraints, and channel economics fragment demand across distinct buyer profiles and use cases. Understanding these divisions exposes where margin pools concentrate and which upgrade cycles drive replacement decisions.
Product Type:
Roof replacement cycles favor membranes that match climate stress with polymer elasticity, creating upgrade pathways from commodity APP to premium SBS grades.
- SBS:Styrene-butadiene-styrene rubber plasticizes asphalt into sheets that maintain flexibility below minus twenty degrees Celsius, making these membranes the default specification across Nordic and Canadian commercial low-slope roofing where thermal cycling would crack APP alternatives.
- APP:Atactic polypropylene modification delivers cost-efficient weatherproofing for warm-climate applications above minus ten degrees Celsius, though specification is narrowing to budget-conscious residential and light commercial projects in southern Europe and the US Sun Belt.
- Reinforced:Polyester or fiberglass mat cores add dimensional stability for multi-layer assemblies and green roof substrates requiring puncture resistance.
- Unreinforced:Homogeneous sheets serve cost-sensitive waterproofing applications where substrate movement is minimal and installation speed outweighs durability premiums.
SBS sits at the top of the volume ranking, with reinforced grades climbing the fastest as green roof assemblies demand redundant membrane protection.
Application:
Cost tier differentiation separates high-specification commercial projects from price-sensitive residential replacements, with waterproofing commanding premium pricing for below-grade redundancy.
- Commercial Roofing:Low-slope membrane assemblies on office, retail, and institutional buildings generate the largest project values, with SBS specifications dominating where energy-efficiency retrofits trigger full roof replacements under tightening EU Green Deal thermal performance mandates.
- Waterproofing:Basement, tunnel, and plaza deck applications in Shanghai, Tokyo, and Singapore require dual-membrane systems that double material specification per project, with urban densification accelerating underground construction demand.
- Industrial Roofing:Manufacturing and logistics facilities specify heavy-duty reinforced grades for mechanical equipment load tolerance and chemical exposure resistance.
- Residential Roofing:Single-family and multi-family housing drives volume through replacement cycles, with APP grades capturing share in warm-climate markets where cost sensitivity outweighs cold-weather performance requirements.
Commercial roofing sits at the top of the volume ranking, with waterproofing climbing the fastest as underground construction expands across Asia-Pacific metropolitan corridors.
End User:
Customer type determines specification authority, with technical directors at national roofing firms consolidating vendor relationships away from fragmented contractor decision-making.
- Contractors:Commercial roofing installation firms in the US and Germany now lock in multi-year supply agreements with single-source membrane providers, capturing volume pricing and dedicated technical support that distributor channels cannot match.
- Architects:Design professionals specify membrane grades during schematic phases, with self-adhesive SBS grades gaining preference for urban retrofits where fire-code restrictions complicate torch-applied installation permits.
- Builders:Residential and light commercial developers prioritize cost efficiency and installation speed, often defaulting to APP or unreinforced grades in warm-climate zones.
- Property Owners:Facility managers and real estate investment trusts drive replacement cycles based on warranty expiration and energy-efficiency upgrade timelines, particularly in Germany's commercial retrofit sector.
Contractors sit at the top of the volume ranking, with architects climbing the fastest as specification authority migrates from distributor sales representatives to design-phase technical directors.
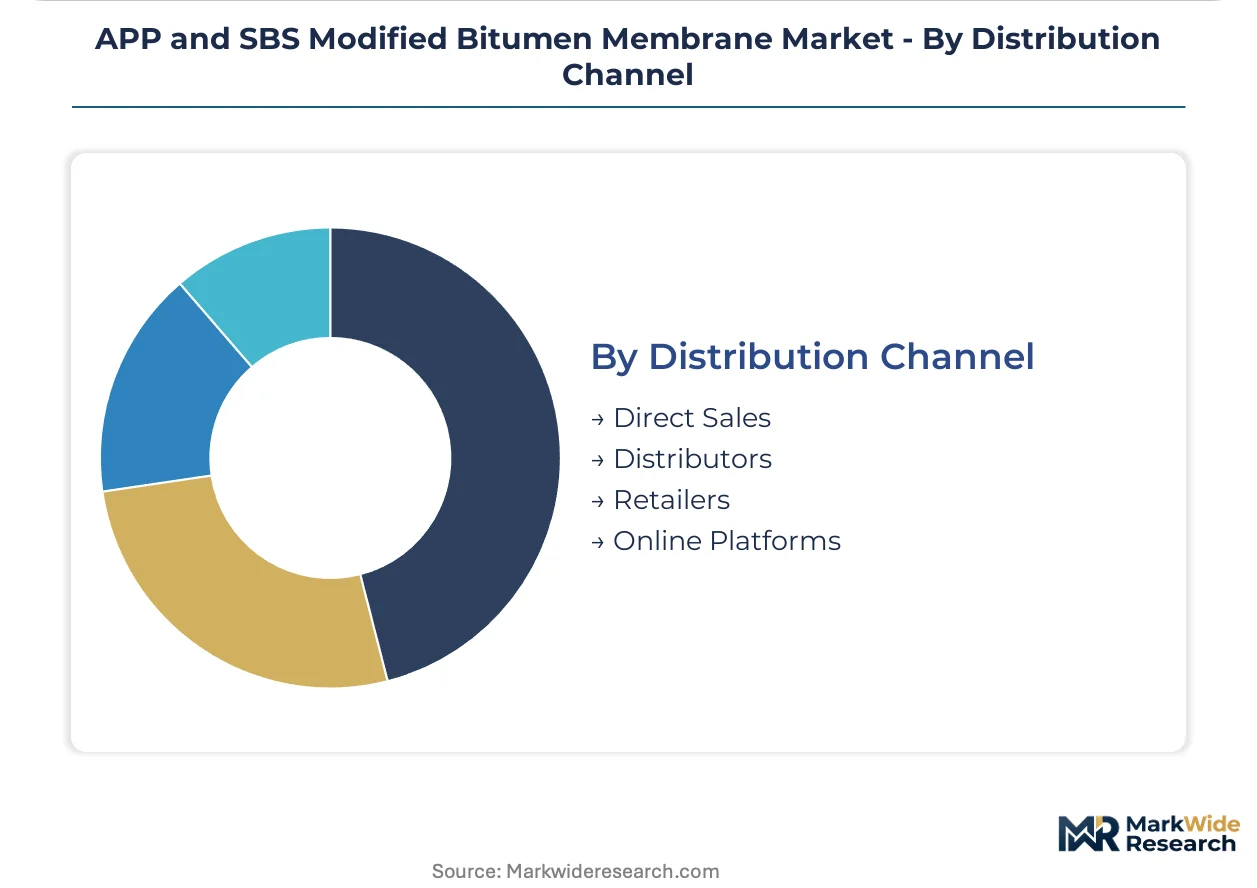
Distribution Channel:
Margin concentration favors direct relationships that eliminate intermediary markups on large commercial projects, though distributor networks retain relevance for fragmented residential demand.
- Direct Sales:National account structures with major roofing contractors capture the largest margin pools by locking in specification control and bypassing distributor markups on projects exceeding defined value thresholds.
- Distributors:Regional and national wholesale networks serve fragmented contractor bases and emergency replacement demand, though their specification influence is eroding as contractor technical directors consolidate vendor relationships.
- Retailers:Building material outlets and home improvement centers reach residential property owners and small contractors for repair and minor replacement projects.
- Online Platforms:Digital procurement channels are emerging for standardized membrane grades and accessory products, though technical specification complexity limits penetration in commercial segments.
Direct sales sits at the top of the volume ranking, with online platforms climbing the fastest as procurement digitization spreads from accessories toward standardized membrane specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modified bitumen membrane production originated in European roofing chemistry laboratories during the 1960s, with German and Swiss manufacturers pioneering polymer-asphalt compounding techniques that later spread to North American and Asian industrial centers.
United States
Commercial roofing contractors in Chicago, Houston, and Phoenix are consolidating vendor relationships under national account structures that lock in three-year supply agreements. EPA stormwater management rules are tightening installation standards for membrane assemblies in municipal projects. The Southeast corridor from Atlanta to Charlotte is experiencing accelerated roof replacement cycles as building owners retrofit for energy-efficiency compliance.
Germany
Energy-efficiency mandates under the EU Green Deal are compressing commercial roof replacement timelines across Stuttgart, Frankfurt, and Munich. National building codes enforced through the EU CPR framework require CE-marked membranes with declared fire performance characteristics. The Rhine-Ruhr industrial belt hosts the densest concentration of membrane fabrication capacity serving retrofit demand from aging commercial building stock.
China
Underground construction in Shanghai, Beijing, and Shenzhen is driving waterproofing demand for basement and tunnel applications requiring redundant membrane protection. Dual carbon goals are pressuring manufacturers to reformulate products for lower embodied carbon without sacrificing durability metrics. The Yangtze River Delta region anchors domestic production scale with integrated bitumen refining and membrane fabrication complexes.
Canada
SBS-modified systems are displacing APP formulations across Toronto, Calgary, and Vancouver commercial low-slope roofing where thermal cycling stresses crack less elastic alternatives. National building code updates are aligning with provincial energy-efficiency programs to accelerate membrane specification in retrofit projects. The Prairie Provinces are experiencing specification migration toward cold-climate-optimized grades as extreme weather events intensify.
Japan
Urban densification in Tokyo, Osaka, and Nagoya is expanding waterproofing applications for underground commercial and transit infrastructure. METI building efficiency standards are tightening thermal performance requirements for membrane assemblies in new construction and renovation. The Kanto region maintains specification authority through technical directors at national roofing firms who consolidate vendor relationships for volume pricing.
APP and SBS Modified Bitumen Membrane Market Competitive Landscape
The competitive structure tilts toward integrated polymer-modification specialists with captive SBS production capacity. Market concentration is moderate, with regional champions commanding specification authority in their home territories through technical service relationships. Three archetypes dominate: European formulation chemistry leaders, Asia-Pacific scale-driven fabricators with backward integration into bitumen refining, and North American distribution-anchored assemblers. Competitive moves center on direct contractor channel development and self-adhesive grade portfolio expansion to capture urban retrofit projects with fire-code restrictions.
Among the integrated European specialists, Soprema Group and Sika AG exemplify the formulation chemistry leadership archetype that sustains margin structures commodity assemblers cannot replicate. At the Asia-Pacific scale-driven end, Oriental Yuhong occupies a position representing integrated production complexes that control raw material cost volatility through captive bitumen refining capacity. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors in membrane specification markets.
| Leading Market Players |
|---|
| GAF Materials Corporation |
| Soprema Group |
| Sika AG |
| Johns Manville |
| IKO Industries Ltd |
| BMI Group |
| Oriental Yuhong |
| Carlisle Companies, Inc. |
| TehnoNICOL Corporation |
| Others |
Pricing and Supply Chain Analysis
SBS-APP grade bifurcation separates premium polymer-modified systems from commodity atactic polypropylene alternatives, with this performance gap manifesting in both pricing spreads and supply chain configurations. Buyers in Germany and Canada pay substantial premiums for SBS block copolymer elasticity that APP formulations cannot replicate in sub-zero thermal cycling, while procurement patterns concentrate around polymer supplier relationships that determine formulation cost stability.
Pricing Analysis
Bundled technical service contracts command premium positioning against unbundled membrane-only transactions. Three-tier pricing structure across premium SBS, standard APP, and economy unreinforced grades separates specification tiers by polymer loading and reinforcement density. Cost compression in APP segments is intensifying because naphtha-derived butadiene feedstock volatility squeezes non-integrated fabricator margins. Residential builders in the US Sun Belt exhibit highest price sensitivity, while national commercial roofing contractors in Chicago and Toronto absorb premium SBS pricing for warranty-backed performance.
Supply Chain Analysis
Dual-sourcing requirements from German and French national roofing contractors mandate qualified supply from at least two SBS block copolymer producers to mitigate disruption risk. SBS production concentrates in South Korea, Taiwan, and the US Gulf Coast, drawing from styrene and butadiene monomer streams tied to regional petrochemical complexes. Single-source vulnerability persists for membrane fabricators lacking captive polymer-modification capacity. Distribution runs through direct national account structures with major contractors alongside regional wholesale networks serving fragmented demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal building renovation targets tighten thermal performance standards and compress commercial roof replacement timelines across member states.
For Market Incumbents: Deploy captive SBS block copolymer production to insulate margin structures from butadiene price volatility that commodity assemblers cannot absorb. Soprema Group and Sika AG already anchor positions through formulation chemistry leadership; others must match this integration depth or cede specification authority to polymer-integrated rivals. Channel control through direct contractor relationships locks out distributor-dependent competitors.
For New Entrants and Emerging Players: Launch via self-adhesive SBS grade specialization targeting urban retrofit projects with fire-code restrictions that complicate torch-applied permits. Stuttgart, Copenhagen, and Toronto green roof assemblies represent penetrable white-space where dual-membrane redundancy doubles material specification per project. Technical partnership with national roofing firms secures specification entry without legacy distributor entrenchment.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional membrane fabricators lack backward integration into bitumen refining or polymer modification. Mid-scale European and North American assemblers face margin compression from feedstock volatility and REACH compliance costs that integrated specialists absorb. The signal to watch is SBS block copolymer spot price divergence from contract rates, indicating supply tension that favors integrated acquirers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SBS Production | Captive polymer supply insulates margin structures from butadiene volatility in South Korea and Taiwan. |
| Self-Adhesive Grade Portfolio Expansion | Torch-free chemistry unlocks urban retrofit projects with extended open-flame permit timelines in fire-restricted cores. |
| Direct Contractor Channel Development | National account structures bypass distributor markups and lock specification control with technical directors. |
| REACH Compliance Reformulation Investment | ECHA substance evaluation deadlines force CE-marking maintenance without degrading fire performance or low-temperature flexibility. |
| Green Roof Assembly Technical Partnership | Vegetated roofing specifications in Stuttgart and Toronto require redundant membrane protection that doubles material volumes. |
Research Methodology
Bottom-up commercial roofing and waterproofing application modeling reconciled against top-down polymer feedstock and membrane fabrication capacity tracking forms the analytical core. Primary interviews with commercial roofing contractors, technical directors at national membrane distributors, plant managers at integrated bitumen refiners, and procurement leads at property investment trusts combined with secondary validation from EU CPR framework documentation, ECHA substance evaluation registers, national building code enforcement records, and customs trade data for bitumen and SBS block copolymer flows.
Historical trendline analysis of specification migration from APP to SBS grades across Nordic, Canadian, and German markets established baseline elasticity assumptions. Segmentation dimensions modeled include polymer modification type, reinforcement configuration, application end-use, end-user specification authority, and distribution channel structure. CAGRs derived from regression analysis of replacement cycle acceleration under energy-efficiency mandates and urban densification-driven waterproofing demand. Industry-specific forecast inputs incorporate EU Green Deal implementation pace and butadiene supply contract renegotiation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polymer supply disruption scenarios or accelerated REACH substance restriction timelines. Deviation in EU member state building code enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Nafion Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
North America Ceramic Membranes Market