
 Myclobutanil Market | 2026-2036
Myclobutanil Market Size, Share, and Industry Trends Forecast 2026-2036
Myclobutanil Market Outlook
ISO 17025 laboratory accreditation is redrawing competitive entry barriers for myclobutanil suppliers. Dow AgroSciences leverages its North American distribution infrastructure to sustain bulk fungicide contracts. Jiangsu Good Harvest anchors Asian supply through integrated triazole production. Yifan Biotech Group specializes in technical-grade exports to regulated EU markets.
Myclobutanil is a systemic triazole fungicide with a molecular formula of C15H17ClN4, inhibiting ergosterol biosynthesis in fungal cell membranes through C14-demethylase interference. The compound delivers curative and protective control against powdery mildew, rusts, and leaf spot pathogens across pome fruits, grapes, and stone fruits. The fungicide product type segment dominates value capture given myclobutanil's established efficacy profile in high-value orchards. Agricultural applications lead volume consumption, though greenhouse deployment is expanding fastest as controlled-environment agriculture intensifies. Farmers represent the core end-user pool, with golf course managers emerging as a premium pricing segment due to turf aesthetic standards.
EPA residue tolerance settings and EU MRL regulations under EFSA oversight govern myclobutanil import eligibility and domestic application rates. REACH compliance requirements and F-Gas Regulation analogues for formulated products shape reformulation investments and label expansion timelines. Stakeholders must monitor regulatory divergence between EPA tolerance reassessments and EU hazard-based cut-off criteria to anticipate market access constraints and portfolio rebalancing needs.
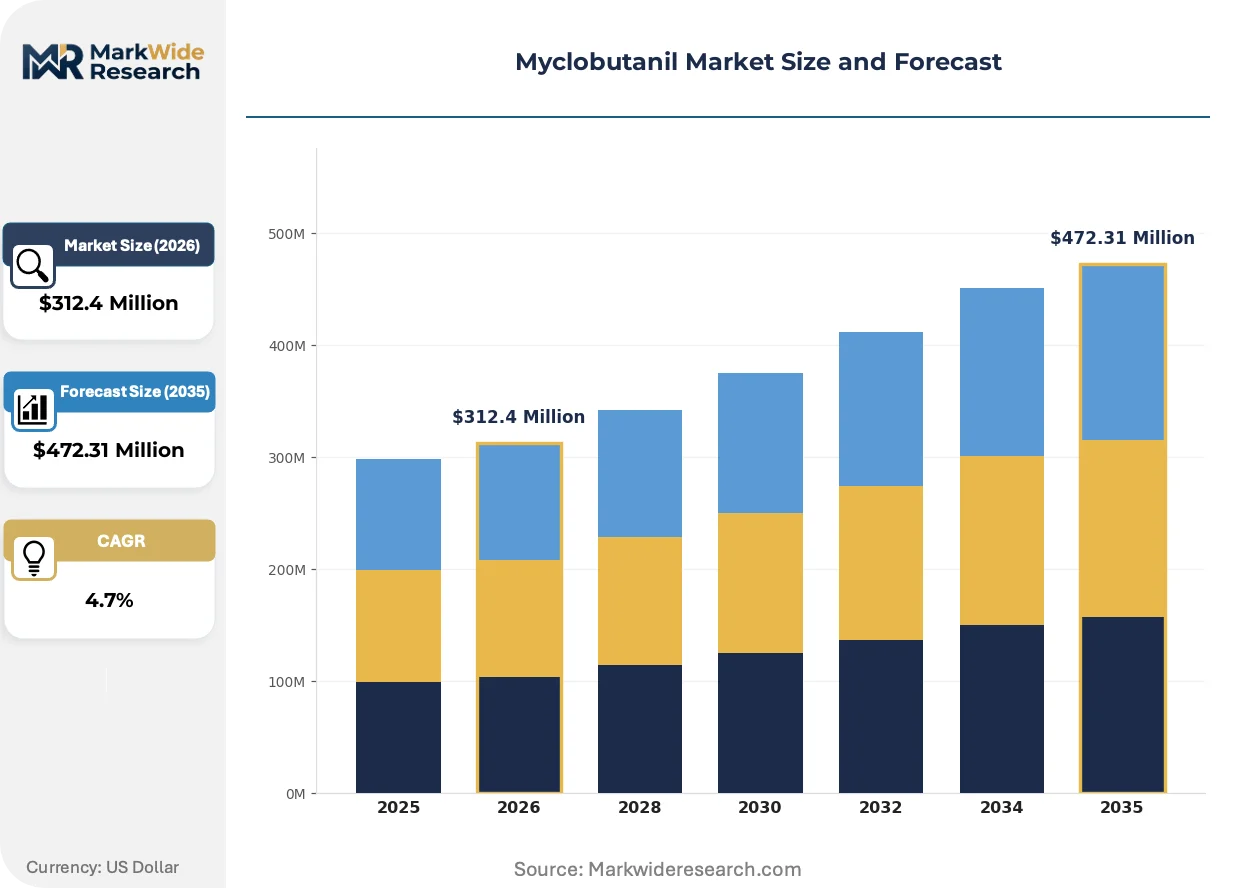
Market Dynamics
EU Green Deal pesticide reduction mandates are forcing myclobutanil manufacturers toward bio-based formulation R&D while vineyard protection programs in France and Italy sustain near-term procurement volumes.
Growth Catalysts
- Powdery mildew pressure:Climate-driven fungal pathogen expansion across Mediterranean pome fruit orchards sustains curative fungicide demand.
- REACH compliance incentives:ECHA registration data requirements accelerate low-toxicity myclobutanil derivative development for retained EU market access.
- Controlled-environment agriculture:Greenhouse strawberry and tomato intensification creates new application vectors for systemic triazole deployment.
Market Restraints
- Azole cross-resistance:Fungal pathogen populations in Spanish vineyards exhibit reduced sensitivity to C14-demethylase inhibitors, limiting treatment efficacy cycles.
- Triazole feedstock concentration:Integrated production of myclobutanil technical grade clusters in Jiangsu province, exposing buyers to single-origin supply risk.
- EU hazard-based cut-off criteria:EFSA endocrine disruption assessments threaten myclobutanil reauthorization under EC 1107/2009 sustainable use directives.
Strategic Opportunities
- Portuguese vineyard expansion:Douro Valley plantings outside traditional French and Italian procurement zones offer untapped distributor relationships.
- Micro-encapsulation technology:Converging polymer science with precision application equipment enables extended-release myclobutanil formulations with reduced spray frequency.
- EU Farm to Fork targets:Integrated pest management mandates create openings for myclobutanil-biological hybrid products in IPM-compliant spray programs.
Industry Challenges
- ISO 17025 accreditation timelines:Analytical method validation for residue testing delays supplier qualification for regulated EU distribution channels.
- Legacy formulation integration:Tank-mix compatibility testing with newer biological fungicides consumes technical resources without guaranteed label expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myclobutanil Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicide, Herbicide, Insecticide, Plant Growth Regulator Application: Agricultural, Horticultural, Turf Management, Greenhouse End User: Farmers, Nursery Operators, Landscape Architects, Golf Course Managers Packaging Type: Bulk, Sachets, Bottles, Cans |
| Companies Covered | Yifan Biotech Group, Dapeng Pharm, Dow AgroSciences, Jiangsu Good Harvest, Shenyang Sciencreat Chemicals, Jiangsu Frey Agrochemicals, Zhejiang Heben Pesticide & Chemicals, Kenso, Rainbow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myclobutanil Market Strategic Shifts
Formulation chemistry advances and regulatory hazard reclassification are bifurcating myclobutanil product development between conventional efficacy optimization and bio-based compatibility engineering.
Nano-emulsion delivery systems are displacing traditional emulsifiable concentrate formulations in high-value vineyard applications. French and Italian wine cooperatives adopt these systems for improved cuticular penetration and rainfastness. The shift compresses margins on standard EC formulations while rewarding surfactant innovation.
EFSA cumulative exposure assessments under EC 1107/2009 are tightening maximum residue limits for triazole fungicides in stone fruits. Processing industries face reformulation costs or sourcing switches to meet baby food and export specifications. Greek peach and nectarine exporters accelerate alternative active ingredient trials to preempt trade barrier imposition.
Cooperative procurement consortia among Provence and Bordeaux vineyard associations are consolidating fungicide purchasing into multi-season framework agreements. Traditional distributor networks lose volume to direct manufacturer negotiations. This concentration is most pronounced in AOC-designated regions where spray records face intensified audit scrutiny.
Myclobutanil Market Segmentation
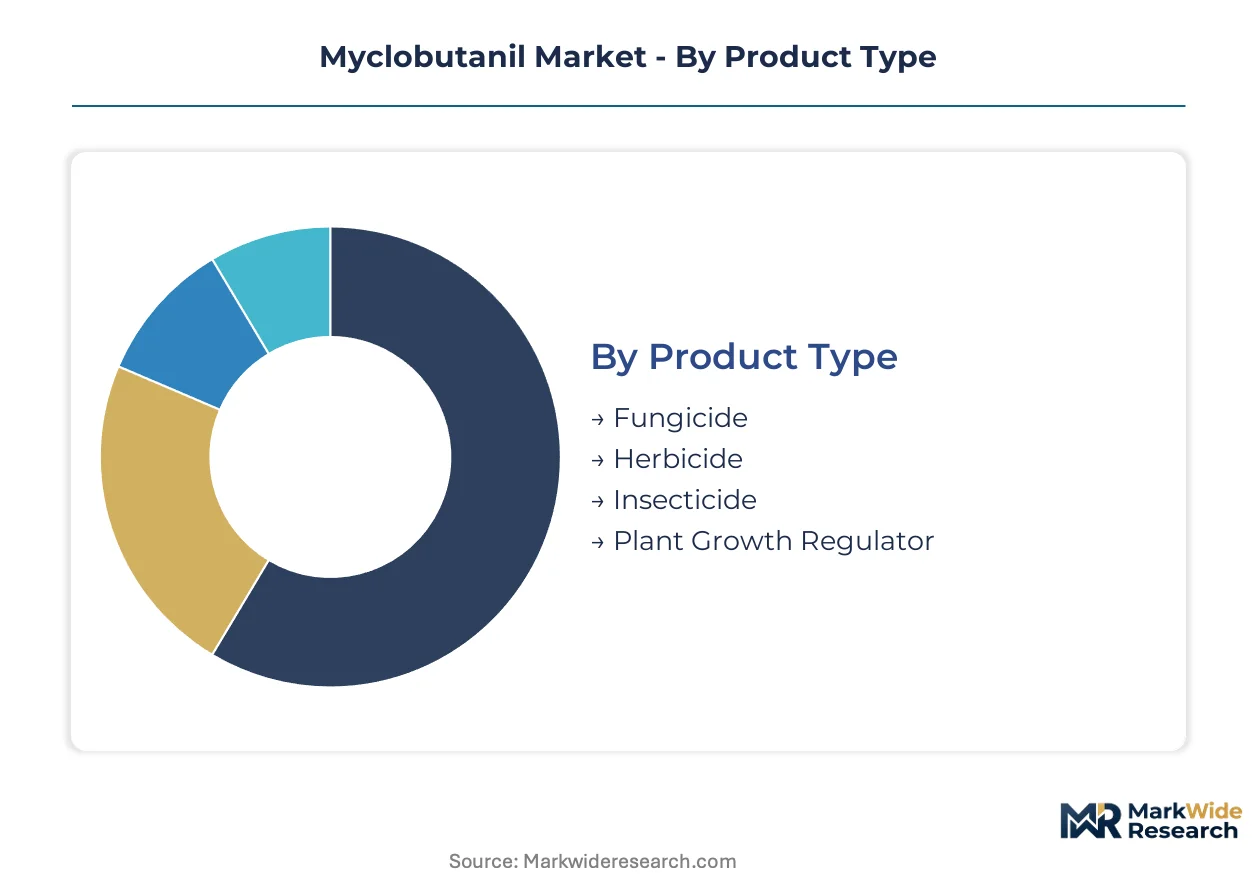
Myclobutanil procurement patterns diverge sharply across use cases, with vineyard protection commanding premium formulations while greenhouse operators prioritize cost-efficient bulk packaging. Understanding these segment-level profit pools clarifies where formulation R&D investments yield maximum returns.
Product Type:
Fungicide formulations capture the deepest margin pools given myclobutanil's established efficacy against powdery mildew in high-value orchards.
- Fungicide:Systemic triazole formulations with C14-demethylase inhibition properties dominate vineyard and pome fruit applications. French AOC-designated regions sustain concentrated procurement of rainfast nano-emulsion variants despite premium pricing.
- Herbicide:Tank-mix compatibility with glyphosate alternatives creates niche positioning in integrated weed management programs. Spanish almond growers represent the primary demand concentration for this off-label deployment.
- Insecticide:Limited myclobutanil incorporation into combination products targets mite suppression in greenhouse tomatoes. Greek protected-culture operations drive sporadic volume for this secondary application.
- Plant Growth Regulator:Minimal myclobutanil utilization as a PGR restricts this segment to experimental trials in Italian citrus nurseries seeking compact growth habit manipulation.
The dominant share belongs to Fungicide, while Plant Growth Regulator is closing the gap fastest through experimental horticulture adoption.
Application:
Volume concentration tracks crop value intensity, with agricultural deployment leading tonnage and greenhouse applications expanding most quickly through controlled-environment intensification.
- Agricultural:Open-field pome fruit, grape, and stone fruit orchards account for bulk myclobutanil consumption. Italian vineyard protection programs under EU Farm to Fork compliance sustain curative spray schedules despite reduction mandates.
- Greenhouse:Controlled-environment strawberry and tomato production in Almeria and Sicily creates new systemic triazole application vectors. Precision irrigation systems enable lower-dose efficacy validation.
- Horticultural:Nursery stock protection against rust diseases generates seasonal demand peaks. Portuguese ornamental exporters drive procurement for phytosanitary certification compliance.
- Turf Management:Golf course aesthetic standards support premium pricing for rapid-acting formulations. French Riviera and Costa del Sol resort maintenance programs concentrate this discretionary spend.
Agricultural deployment retains volume leadership, though Greenhouse applications are gaining share fastest through Mediterranean protected-culture expansion.
End User:
Procurement authority concentrates with direct cultivators rather than intermediaries, though golf course managers extract steepest price premiums for specialized formulations.
- Farmers:Individual vineyard and orchard operators constitute the core demand base. Cooperative consolidation in Bordeaux and Provence shifts bargaining power toward direct manufacturer negotiations.
- Golf Course Managers:Turf aesthetic imperatives justify premium expenditure on extended-release formulations. Maintenance budgets at Spanish and French resort courses sustain this high-margin niche.
- Nursery Operators:Containerized production systems require precise dose control for young plant sensitivity. Italian and Greek ornamental exporters drive quality-assured procurement.
- Landscape Architects:Municipal and commercial planting specifications occasionally specify myclobutanil for established tree protection. Urban canopy programs in Lisbon and Barcelona generate intermittent demand.
Farmers command the dominant procurement volume, while Golf Course Managers are expanding their share fastest through resort sector recovery.
Packaging Type:
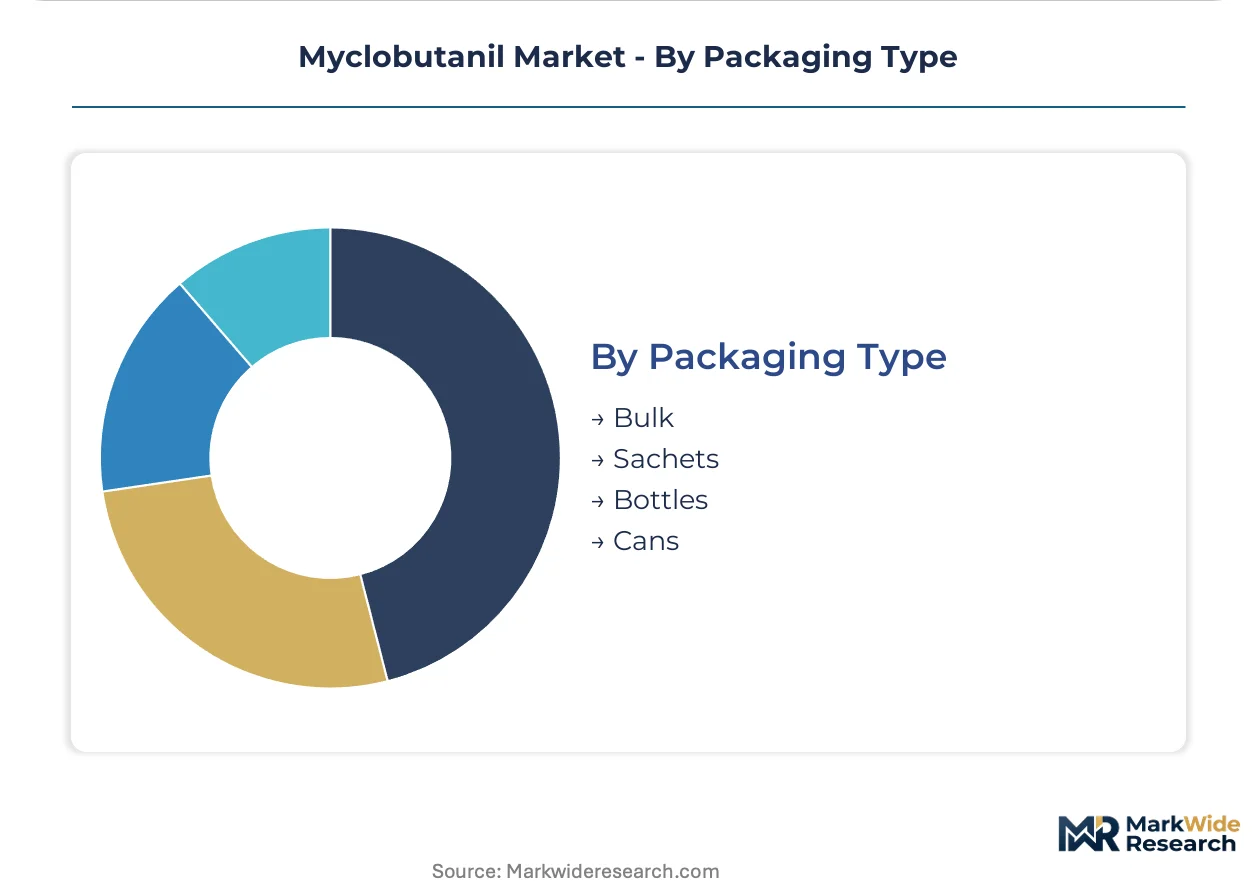
Packaging economics reflect application scale and regulatory documentation requirements, with bulk formats serving integrated operations and sachets penetrating smallholder markets.
- Bulk:Tanker and drum deliveries serve large vineyard cooperatives and formulation tollers. Direct manufacturer relationships in France and Italy minimize per-liter packaging overhead.
- Bottles:Standard 1-5 liter containers dominate distributor-led sales to mid-scale orchard operators. Portuguese and Spanish retail channels prefer this format for inventory flexibility.
- Sachets:Single-dose water-soluble packaging penetrates smallholder vineyard segments in emerging cultivation zones. Douro Valley expansion outside traditional procurement areas favors this low-commitment format.
- Cans:Aerosol and pressurized containers serve specialized turf spot-treatment applications. Limited myclobutanil utilization in this format restricts volume to niche golf course maintenance contracts.
Bulk packaging holds the dominant position, while Sachets are climbing the fastest through smallholder vineyard expansion in peripheral growing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Marseille-Fos liquid bulk terminals anchor French fungicide import flows, handling concentrated triazole formulations bound for Rhône Valley and Provence vineyard cooperatives. Mediterranean container routes from Shanghai and Busan feed Asian technical-grade supply into European formulation plants.
France
Bordeaux and Champagne vineyard protection programs sustain bulk myclobutanil procurement despite EU Green Deal reduction mandates. ANSM residue monitoring protocols under REACH enforcement tighten import documentation requirements for non-EU suppliers. The Rhône Valley formulation cluster around Lyon processes technical-grade imports into nano-emulsion products for AOC-designated regions.
Italy
Piedmont and Veneto wine cooperatives drive concentrated demand for rainfast formulations against powdery mildew pressure. EFSA cumulative exposure assessments under EC 1107/2009 accelerate MRL compliance investments by stone fruit processors in Emilia-Romagna. The Po Valley toll manufacturing network near Milan handles blending operations for Mediterranean export markets.
Spain
Almeria greenhouse complexes expand protected-culture triazole applications for strawberry and tomato intensification. Ministry of Agriculture sustainable use directives align with EU Farm to Fork targets, restricting calendar-based spray schedules. Valencia citrus nurseries generate seasonal demand peaks for rust disease management in containerized propagation systems.
China
Jiangsu province technical-grade production clusters supply bulk active ingredient to European formulation tollers. NMPA pesticide registration reforms and dual carbon goals pressure producers toward cleaner synthesis pathways. The Yangtze River Delta port infrastructure around Shanghai handles concentrated export volumes to Mediterranean markets.
United States
California Central Valley pome fruit orchards and Pacific Northwest vineyard regions sustain agricultural fungicide consumption. EPA tolerance reassessments under FIFRA govern residue limits for domestic and export-bound produce. The Gulf Coast formulation corridor near Houston processes imported technical-grade material for distribution through Midwest agricultural supply networks.
Myclobutanil Market Competitive Environment
Listed leaders compete with private specialists across integrated triazole production and technical-grade export positioning. The vendor base stratifies between multinational agrochemical platforms with North American distribution infrastructure and Asia-based integrated manufacturers with captive feedstock supply. Three archetypes dominate: scale-driven bulk producers, specialty exporters to regulated EU markets, and regional formulation tollers serving cooperative procurement networks. Competitive moves concentrate on REACH compliance investments and micro-encapsulation technology licensing.
Within the regulated-market export tier, Yifan Biotech Group and Jiangsu Good Harvest occupy positions serving EU accreditation requirements. Dow AgroSciences represents the multinational platform archetype with established bulk contract infrastructure. These three entities exemplify the geographic and functional segmentation between Asian technical-grade supply and Western formulation distribution, with each anchoring distinct competitive vectors without overlapping core capabilities.
| Leading Market Players |
|---|
| Yifan Biotech Group |
| Dapeng Pharm |
| Dow AgroSciences |
| Jiangsu Good Harvest |
| Shenyang Sciencreat Chemicals |
| Jiangsu Frey Agrochemicals |
| Zhejiang Heben Pesticide & Chemicals |
| Kenso |
| Rainbow |
| Others |
Value Chain & Pricing Dynamics
Nano-emulsion formulation chemistry displacing traditional emulsifiable concentrates simultaneously redraws supply geography toward French and Italian surfactant innovation clusters and compresses pricing power for standard EC manufacturers. This substitution dynamic concentrates margin capture with polymer science specialists while eroding legacy formulation tollers.
Pricing Analysis
Certification level under ISO 17025 laboratory accreditation creates the primary spread between premium nano-emulsion formulations and economy-grade emulsifiable concentrates. Three-tier pricing structure across REACH-compliant technical grade, standard agricultural formulations, and bulk active ingredient separates EU-accredited suppliers from standard exporters. Pricing pressure stems from EFSA cumulative exposure assessments tightening MRL compliance costs for stone fruit processors. Cooperative procurement consortia in Bordeaux and Provence exhibit lowest price sensitivity; smallholder vineyard segments in Portuguese expansion zones show highest elasticity.
Supply Chain Analysis
Yangtze River Delta port congestion around Shanghai periodically disrupts technical-grade shipments from Jiangsu province production clusters to Mediterranean formulation plants. Raw material dependencies center on chlorinated intermediate feedstocks, triazole ring precursors, and specialty surfactant packages. Single-source vulnerability concentrates in Jiangsu province integrated manufacturing, exposing European tollers to concentrated supply risk. Distribution runs through Marseille-Fos liquid bulk terminals for French vineyard cooperatives and Milan-area toll manufacturing networks for Italian processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greenhouse strawberry and tomato intensification across Almeria and Sicily signals early-cycle expansion for systemic triazole deployment in controlled-environment agriculture.
For Market Incumbents: Fortify REACH registration data portfolios through accelerated low-toxicity derivative development before EFSA endocrine disruption reassessments conclude. Deepen backward integration into chlorinated intermediate production within EU regulatory jurisdiction to mitigate Jiangsu supply concentration risk. Prioritize micro-encapsulation technology licensing to capture extended-release formulation premiums from golf course managers. For New Entrants and Emerging Players: Anchor in Portuguese Douro Valley vineyard expansion outside traditional French and Italian procurement networks, where distributor relationships remain unsettled. Target sachet-format packaging for smallholder segments with low-commitment entry economics. Pursue direct manufacturer negotiations with emerging cooperative procurement consortia rather than legacy distributor channel insertion. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors EU-accredited technical-grade exporters with captive laboratory infrastructure. Long-term viability hinges on bio-based formulation compatibility engineering rather than conventional efficacy optimization. Monitor EFSA hazard-based cut-off criteria rulings under EC 1107/2009 as the critical inflection signal for portfolio rebalancing urgency.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Data Investment | ECHA compliance requirements under EC 1107/2009 secure retained EU market access for technical-grade suppliers. |
| Micro-Encapsulation Technology Licensing | Extended-release formulations capture premium pricing from French Riviera and Costa del Sol resort maintenance programs. |
| Backward Integration into Chlorinated Intermediates | In-house production of feedstock precursors reduces Jiangsu province single-source vulnerability for European tollers. |
| Direct Cooperative Procurement Negotiations | Bypassing traditional distributor networks captures volume concentration in Bordeaux and Provence AOC-designated regions. |
| Bio-Based Formulation R&D Partnership | EU Farm to Fork IPM mandates create openings for myclobutanil-biological hybrid product positioning. |
Study Parameters
Cross-validation between primary interviews with formulation R&D directors, vineyard cooperative procurement managers, regulatory affairs specialists at agrochemical platforms, and greenhouse operations engineers anchors the qualitative findings. Secondary validation draws from EFSA scientific opinions, ECHA registration databases, EU customs trade flows, and SEC filings of listed agrochemical entities. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers.
Sensitivity analysis across the projection horizon tests volume and value outputs against regulatory scenario variants and climate-driven pathogen pressure intensities. Segmentation dimensions span product type, application intensity, end-user procurement authority, and packaging format scale. CAGRs derive from historical trajectory analysis adjusted for EU Green Deal mandate implementation pacing and greenhouse agriculture expansion rates. Forecast inputs incorporate EFSA MRL reassessment timelines and Jiangsu province capacity utilization indicators.
Decision-makers should treat outputs as directional under base assumptions of sustained vineyard protection program funding and stable REACH registration pathways; material deviation in EFSA hazard classification or Chinese environmental enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as EU Farm to Fork pesticide reduction targets and Almeria greenhouse expansion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hexafluorosilicic Acid Market
Chemicals
North America Tartaric Acid Market
Chemicals
Tanning Agents Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
Industrial Odor Management Market
Chemicals
Caustic Soda Market
Chemicals
Morpholine Market
Chemicals
Potassium Permanganate Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Tributyl Phosphate Market
Chemicals
Benzenoid Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Global Organobromine Market
Chemicals
Nonaisoprenol Market
Chemicals
Sodium Cyanide Market