
 Calcium Disodium Ethylene Diamine Tetra-Acetate Market | 2026-2036
Calcium Disodium Ethylene Diamine Tetra-Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Disodium Ethylene Diamine Tetra-Acetate Market Outlook
A capital-intensity divergence between integrated manufacturers and trading-focused distributors is reorganizing competitive tiers in calcium disodium EDTA supply. New Alliance Fine Chem Private Limited leverages captive synthesis capabilities to control input costs across powder and granule grades. Mubychem Group anchors its position through specialized pharmaceutical-grade production serving Indian and export markets. Spectrum Chemical differentiates via certified reference standards and analytical-grade formulations for laboratory and research institutions.
Calcium disodium ethylene diamine tetra-acetate is a chelating agent formed by neutralizing ethylenediaminetetraacetic acid with calcium and sodium hydroxides, typically supplied at minimum 99% purity for food and pharmaceutical applications, where it sequesters metal ions to prevent oxidation and preserve product stability. The powder format dominates volume due to lower logistics costs and broader compatibility with dry-blend food and agricultural formulations, while liquid concentrates command premium positioning in industrial water treatment systems requiring rapid dispersal. Food preservatives and pharmaceuticals represent the most structurally attractive application segments, with environmental agencies emerging as a fast-growing end-user category driven by heavy-metal remediation mandates.
The FDA governs calcium disodium EDTA under food additive regulations with specified maximum usage levels, while REACH in Europe mandates registration and hazard communication for industrial chemical handlers, collectively elevating compliance costs for non-specialized suppliers. China's SAMR and NMPA enforce parallel standards for food-grade and pharmaceutical-grade imports, creating multi-jurisdictional certification requirements for exporters. Stakeholders must monitor evolving purity thresholds and regional authorization timelines to align capacity investments with qualifying demand.
Market Dynamics
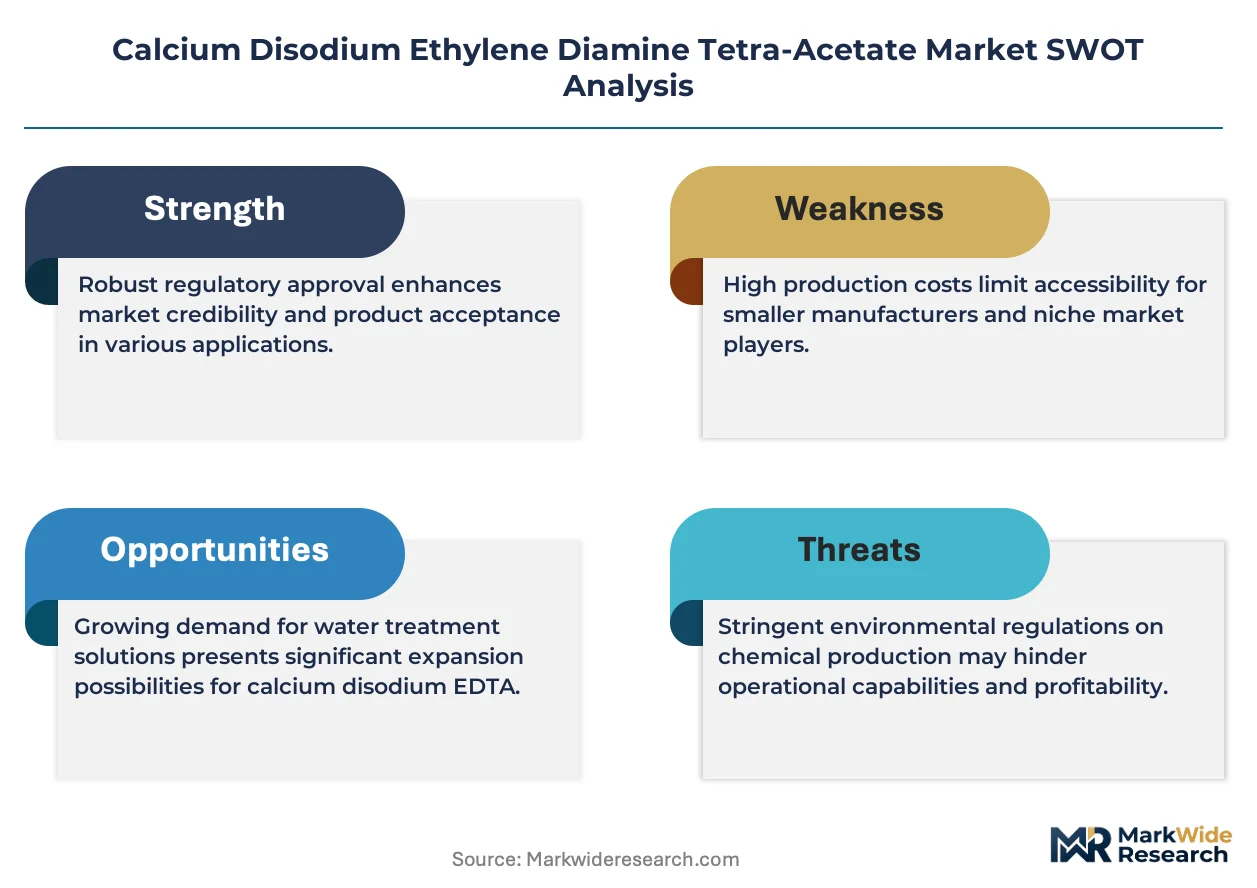
Regulatory tightening across food additive purity specifications is forcing manufacturers to recalibrate synthesis pathways and certification investments, compressing margins for non-integrated suppliers while rewarding captive production networks.
Growth Catalysts
- Heavy-metal remediation mandates:Environmental agencies in industrial corridors are mandating chelating agents for soil and wastewater treatment, creating new demand streams beyond traditional food and pharmaceutical applications.
- REACH registration requirements:ECHA's hazard communication protocols for industrial chemical handlers are elevating compliance barriers that favor established European manufacturers with dedicated regulatory affairs capabilities.
- Shelf-life extension protocols:Food processors in the United States are expanding chelate adoption in canned goods and dressings to replace synthetic antioxidants facing consumer scrutiny.
Market Restraints
- Ethylenediaminetetraacetic acid price volatility:Input costs fluctuate with petrochemical feedstock markets, squeezing formulation margins for distributors lacking backward integration into acid synthesis.
- Chinese supply concentration:A significant share of technical-grade powder originates from Shandong and Jiangsu province clusters, creating geographic risk exposure for buyers dependent on single-source procurement.
- Biodegradable chelate substitution:Gluconates and citrates are gaining formulation share in eco-sensitive European cosmetics and personal care applications where EDTA persistence draws regulatory attention.
Strategic Opportunities
- Pharmaceutical-grade water treatment:Dialysis centers and biotechnology manufacturing facilities require ultra-high-purity chelates for pyrogen-free water systems, commanding substantial price premiums over technical grades.
- India's FSSAI enforcement expansion:Stricter food additive monitoring in processed food corridors around Mumbai and Delhi is accelerating import substitution opportunities for domestic manufacturers achieving BIS certification.
- Closed-loop agricultural systems:Hydroponic and aquaponic operators are adopting chelated micronutrient formulations to prevent iron and manganese precipitation in recirculating nutrient solutions.
Industry Challenges
- Analytical chemist scarcity:Validating parts-per-billion metal content in pharmaceutical-grade batches requires specialized atomic absorption spectroscopy expertise that commands premium labor costs in manufacturing clusters.
- Multi-jurisdictional certification timelines:Simultaneous FDA food additive petitions, EFSA re-evaluations, and NMPA pharmaceutical registrations can extend market entry cycles by 18-36 months for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Disodium Ethylene Diamine Tetra-Acetate Market |
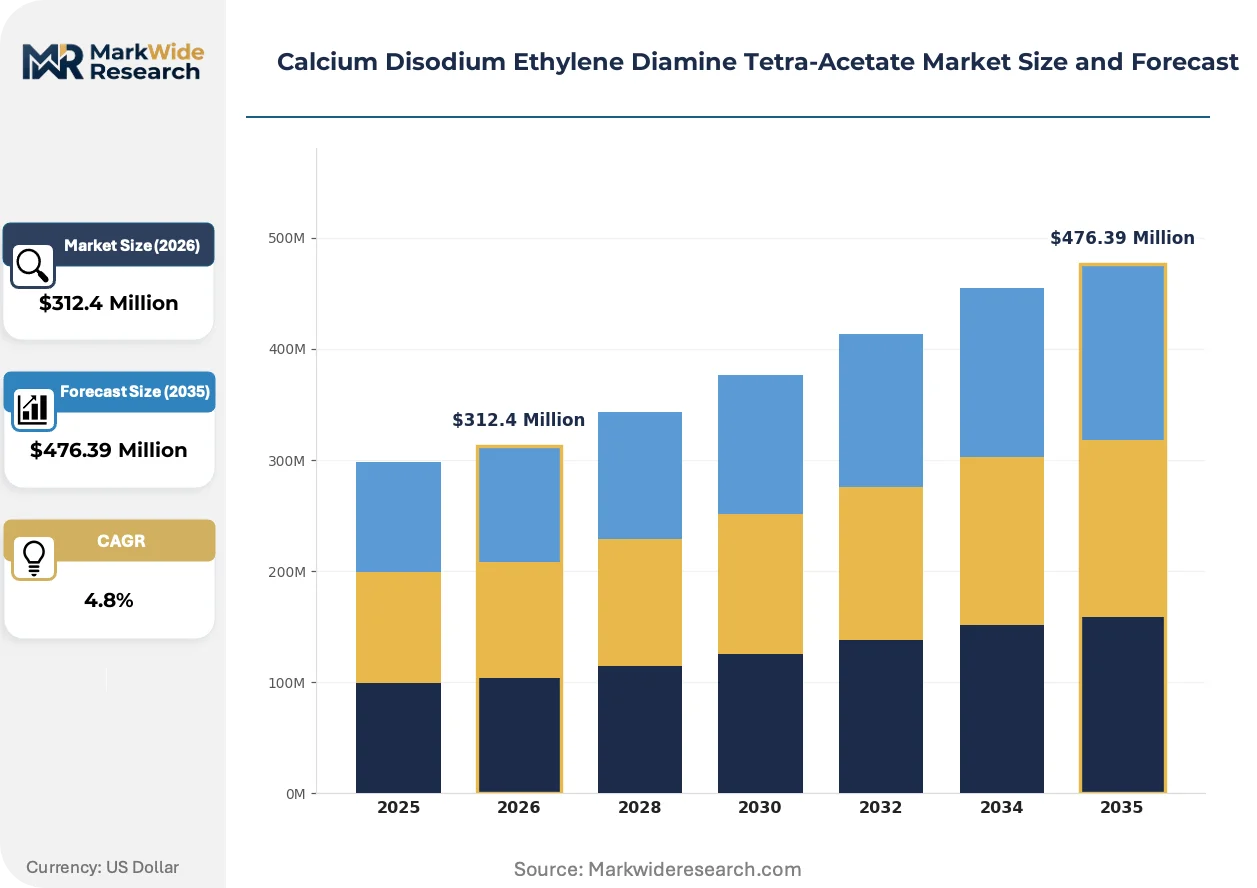
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Liquid, Tablets Application: Water Treatment, Food Preservatives, Pharmaceuticals, Agriculture End User: Manufacturers, Environmental Agencies, Food Processors, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | New Alliance Fine Chem Private Limited, Mubychem Group, Spectrum Chemical, Hunan Xuan Resources Co., Ltd, Nanjing Jiayi Sunway Chemical Co., Ltd., Hangzhou Union Biotechnology Co., Ltd., Charkit, Ataman Kimya, Anmol Chemicals Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Disodium Ethylene Diamine Tetra-Acetate Market Strategic Shifts
Continuous processing technology is reshaping cost structures in chelate manufacturing, while regulatory data transparency requirements and buyer consolidation are compressing traditional distribution hierarchies.
Continuous flow reactors are supplanting batch synthesis in large-scale EDTA salt production, enabling tighter temperature control and reduced solvent waste. German and Swiss chemical manufacturers are retrofitting existing batch plants with modular flow chemistry skids. This technology is supplanting legacy stirred-tank operations by cutting energy intensity and enabling real-time quality monitoring that satisfies pharmaceutical audit requirements.
EFSA's systematic re-evaluation of food additive safety profiles is tightening acceptable daily intake thresholds for calcium disodium EDTA in preserved vegetables and seafood. Manufacturers serving European retail channels are reformulating at lower inclusion rates or pursuing alternative chelates for label-friendly positioning. The canned fish segment in Spain and Portugal faces particular pressure as traditional preservation protocols confront revised exposure assessments.
Direct procurement contracts between food multinationals and integrated chelate manufacturers are eroding distributor margins in North American supply chains. Bulk buyers with internal formulation laboratories are negotiating specification-grade supply agreements that bypass regional chemical distributors. This pattern is most pronounced in midwestern United States meat processing corridors where Tyson, Cargill, and Conagra maintain centralized ingredient sourcing functions.
Calcium Disodium Ethylene Diamine Tetra-Acetate Market Segmentation
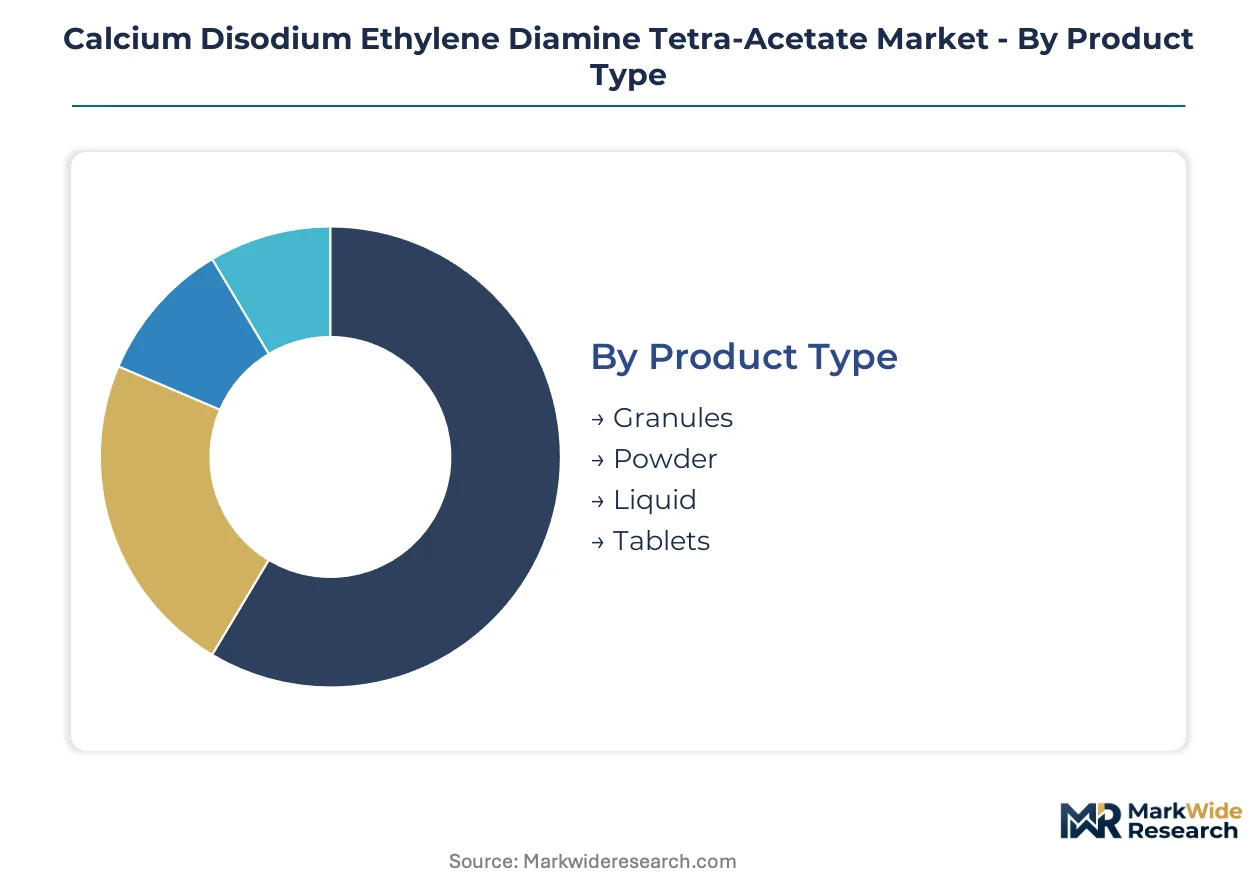
Calcium disodium EDTA's functional versatility across metal-sequestration applications creates distinct specification requirements by product form and end-use. Regulatory purity thresholds diverge sharply between food-grade and pharmaceutical-grade supply chains, forcing manufacturers to maintain parallel certification portfolios.
Product Type:
FDA and EFSA food additive regulations enforce minimum 99% purity specifications for powder and granule grades entering preservation applications, while REACH-registered liquid concentrates face separate hazard communication protocols for industrial handlers.
- Powder:Dry-blend formulations dominate volume throughput due to lower logistics costs and compatibility with automated dosing systems in food processing plants. United States canneries and dressings manufacturers drive steady demand as shelf-life extension protocols tighten.
- Liquid:Rapid-dispersal concentrates command premium positioning in water treatment systems requiring immediate metal ion binding. Municipal utilities in industrial corridors favor liquid delivery for continuous-feed remediation operations.
- Granules:Controlled-release agglomerates serve agricultural micronutrient formulations where gradual dissolution prevents iron precipitation in hydroponic recirculation systems.
- Tablets:Compressed solid forms target laboratory and field-testing applications requiring precise unit-dose chelation for analytical calibration standards.
Powder handles the majority of throughput; liquid is the fastest mover on share.
Application:
Cost-tier differentiation separates commodity technical grades from certified pharmaceutical and food additive specifications, with environmental remediation emerging as a mid-tier growth corridor.
- Food Preservatives:FDA-regulated maximum usage levels in canned goods, dressings, and seafood products drive formulation precision. United States processors expand chelate adoption as synthetic antioxidant alternatives face consumer scrutiny.
- Water Treatment:Heavy-metal remediation mandates from EPA and state environmental agencies create institutional demand streams. Industrial wastewater facilities in manufacturing corridors require continuous chelate feed for compliance discharge limits.
- Pharmaceuticals:USP-grade specifications for dialysis water systems and parenteral manufacturing command substantial price premiums over technical grades. Pyrogen-free certification requirements limit qualified supplier pools.
- Agriculture:Chelated micronutrient formulations prevent manganese and iron precipitation in precision irrigation systems. Hydroponic operators in controlled-environment agriculture adopt recirculating nutrient solutions.
Food preservatives anchor volume demand; water treatment is expanding most quickly on regulatory mandate acceleration.
End User:
Procurement sophistication varies sharply: institutional buyers with internal laboratories negotiate direct specification-grade contracts, while smaller processors rely on distributor intermediaries for technical support.
- Food Processors:Multinationals with centralized sourcing functions bypass regional distributors for bulk powder supply. Midwestern United States meat processing corridors maintain dedicated ingredient qualification laboratories.
- Environmental Agencies:Municipal and state remediation authorities mandate chelating agents for soil and groundwater treatment. Procurement concentrates in industrial corridors with legacy heavy-metal contamination.
- Manufacturers:Formulation houses blend technical-grade chelates into downstream products for resale. Backward integration pressures mount as raw material costs fluctuate.
- Research Institutions:Analytical-grade requirements for atomic absorption spectroscopy calibration sustain niche demand for certified reference materials. Academic laboratories require lot-traceable documentation.
Food processors command the dominant procurement volume; environmental agencies are gaining share fastest on remediation mandate expansion.
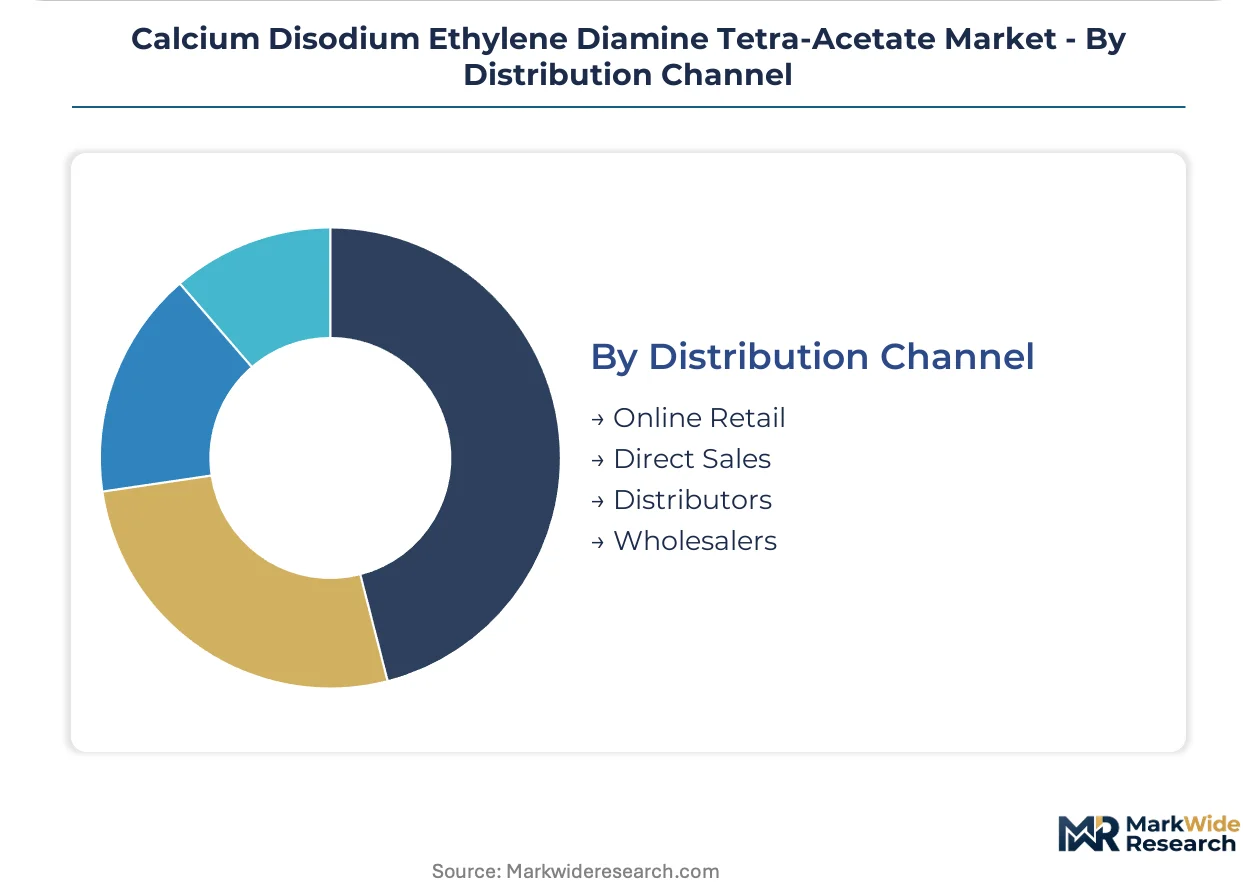
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements, with direct sales eroding traditional distributor margins among qualified large-volume accounts.
- Direct Sales:Integrated manufacturers serve multinational food and pharmaceutical accounts through specification-locked supply agreements. Technical service teams support formulation optimization and regulatory documentation.
- Distributors:Regional chemical distributors maintain inventory positions for mid-tier processors lacking bulk storage infrastructure. Value-added services include just-in-time delivery and safety compliance training.
- Online Retail:E-commerce platforms capture small-laboratory and research institutional demand for analytical-grade quantities. Digital procurement reduces transaction costs for geographically dispersed buyers.
- Wholesalers:Bulk commodity handlers aggregate technical-grade powder for resale to agricultural and industrial formulators. Price-sensitive procurement favors lowest-landed-cost sourcing.
Direct sales channels handle the largest volume throughput; online retail is climbing the fastest on digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China exhibit acute price sensitivity on technical-grade powder, while pharmaceutical-grade purchasers in Germany and the United States absorb substantial premiums for USP-certified supply.
United States
Food processors in the Midwestern meat processing corridor drive steady powder demand for shelf-life extension in canned goods and dressings. FDA food additive regulations enforce maximum usage levels with strict purity documentation requirements. Chicago-area formulation laboratories negotiate direct specification-grade contracts with integrated manufacturers, bypassing traditional distributor channels.
Germany
REACH registration requirements elevate compliance barriers for industrial chemical handlers, favoring established manufacturers with dedicated regulatory affairs capabilities. ECHA hazard communication protocols mandate detailed safety data sheets for liquid concentrate formulations. The Rhine-Ruhr industrial cluster hosts retrofit operations converting batch synthesis plants to continuous flow reactor systems for energy efficiency gains.
China
Shandong and Jiangsu province clusters concentrate technical-grade powder production, creating geographic supply risk for dependent buyers. SAMR and NMPA enforce parallel standards for food-grade and pharmaceutical-grade domestic output and imports. Qingdao-area exporters navigate multi-jurisdictional certification timelines for FDA, EFSA, and NMPA registrations simultaneously.
India
FSSAI enforcement expansion in Mumbai and Delhi processed food corridors accelerates import substitution opportunities for domestic manufacturers. BIS certification requirements for food additive safety tighten purity specifications across powder and granule grades. Gujarat-based producers leverage captive synthesis capabilities to control input costs and serve export markets.
Japan
Pharmaceutical-grade demand concentrates in Osaka-area biotechnology manufacturing facilities requiring pyrogen-free chelates for water systems. METI industrial standards govern chelating agent specifications for precision manufacturing applications. The Kansai region maintains specialized atomic absorption spectroscopy expertise for validating parts-per-billion metal content in certified batches.
Calcium Disodium Ethylene Diamine Tetra-Acetate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in calcium disodium EDTA supply. The upper tier commands pricing power through captive acid synthesis and multi-jurisdictional certification portfolios. Mid-scale specialists differentiate via pharmaceutical-grade purity capabilities or regional regulatory expertise. Dominant competitive moves include backward integration into ethylenediaminetetraacetic acid production and geographic expansion through direct sales force establishment in food processing corridors.
Among India-based manufacturers, New Alliance Fine Chem Private Limited and Mubychem Group occupy positions within the integrated production tier, leveraging domestic chemical synthesis infrastructure. Spectrum Chemical exemplifies the analytical-grade specialist archetype serving laboratory and research institutional demand. These three entities represent contrasting strategic postures: captive manufacturing control versus certified reference material differentiation.
| Leading Market Players |
|---|
| New Alliance Fine Chem Private Limited |
| Mubychem Group |
| Spectrum Chemical |
| Hunan Xuan Resources Co., Ltd |
| Nanjing Jiayi Sunway Chemical Co., Ltd. |
| Hangzhou Union Biotechnology Co., Ltd. |
| Charkit |
| Ataman Kimya |
| Anmol Chemicals Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles among North American food processors concentrate procurement leverage in the hands of integrated manufacturers with captive ethylenediaminetetraacetic acid synthesis, compressing margins for distributors dependent on spot-market acid purchases. This lead-time band aligns with FDA-mandated lot-traceability documentation requirements, reinforcing pricing power for suppliers with multi-jurisdictional certification portfolios.
Pricing Analysis
Service and technical support contracts drive lifetime value for pharmaceutical-grade suppliers serving dialysis centers and biotechnology manufacturing facilities. Three-tier pricing structure across USP-certified, food-grade, and technical-grade levels separates premium pyrogen-free batches from standard preservation applications. Cost compression in technical-grade powder is intensifying because Shandong province exporters compete on volume, while food processors in the United States exhibit acute price sensitivity compared to German pharmaceutical buyers absorbing substantial certification premiums.
Supply Chain Analysis
Strategic stockpile preferences dominate among municipal water utilities managing heavy-metal remediation mandates, contrasting with just-in-time powder deliveries to midwestern United States canneries. Manufacturing concentrates in China, India, and Germany, with ethylenediaminetetraacetic acid, sodium hydroxide, and calcium carbonate feeding production lines. Single-source vulnerability runs through Shandong and Jiangsu province clusters for technical-grade output. Distribution runs through direct specification-grade contracts for multinational food processors, with regional chemical distributors serving mid-tier accounts lacking bulk storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gluconates and citrates present a substitution defense for incumbents, as these biodegradable chelates gain formulation share in European cosmetics and personal care applications where EDTA persistence draws regulatory attention from ECHA.
For Market Incumbents: Consolidate backward integration into ethylenediaminetetraacetic acid production to buffer petrochemical feedstock volatility, while deepening regulatory affairs capabilities for simultaneous FDA, EFSA, and NMPA registration maintenance. Captive synthesis networks defend margin position against trading-focused distributors exposed to Chinese supply concentration. For New Entrants and Emerging Players: Anchor in India's FSSAI enforcement expansion around Mumbai and Delhi processed food corridors, where import substitution opportunities accelerate for domestic manufacturers achieving BIS certification. Pharmaceutical-grade water treatment for dialysis centers offers penetrable white-space with substantial price premiums, accessible through technical service teams supporting pyrogen-free documentation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core chelate production lines lacking pharmaceutical-grade purity capabilities. Long-term viability hinges on regulatory data transparency investments and continuous processing technology adoption. Watch EFSA acceptable daily intake threshold revisions as the inflection indicator for reformulation demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EDTA Acid Synthesis | Captive production buffers petrochemical feedstock cost volatility for margin protection. |
| Continuous Flow Reactor Retrofit | German and Swiss manufacturers cut energy intensity while satisfying pharmaceutical audit requirements. |
| Multi-Jurisdictional Certification Investment | Simultaneous FDA, EFSA, and NMPA registrations extend market entry cycles but lock in premium pricing tiers. |
| Direct Sales Force Establishment | Midwestern United States meat processing corridors favor specification-locked supply agreements bypassing distributors. |
| Pharmaceutical-Grade Capacity Expansion | USP-certified output commands substantial premiums over technical grades in dialysis water systems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA food additive petitions, EFSA safety evaluations, customs and trade data, and SEC filings from listed chemical manufacturers. Interviews with plant managers at integrated synthesis facilities, procurement leads at downstream food processors, distribution channel partners, and technical R&D directors informed supply-side and demand-side validation. Bottom-up volume modeling triangulates against top-down market sizing from regulatory filings and industry association data.
Segmentation dimensions modeled include product form, application category, end-user archetype, and distribution channel across the projection horizon. Grade-tier differentiation separates pharmaceutical, food-additive, and technical specifications, while regional production hub clustering captures supply concentration effects. CAGRs derive from trend extrapolation of historical volume movements adjusted for regulatory mandate acceleration and substitution threat progression.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EFSA purity enforcement and stable petrochemical feedstock pricing; material deviation would warrant model refresh. Revision becomes warranted when biodegradable chelate substitution rates in European formulations cross thresholds that trigger cascade adoption in North American personal care applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Global Construction Chemical Market
Chemicals
Lead Tetracetate Market
Chemicals
Global Syringaldehyde Market
Chemicals
Muriatic Acid Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
HATU Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Ammonia Market
Chemicals
Calcium Methoxide Market
Chemicals
Di Nitro Toluene Market
Chemicals
Coal Tar Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
1, 4 Butanediol Market
Chemicals
Asia-Pacific Methanol Market