
 Versatile Cryosurgical Devices Market | 2026-2036
Versatile Cryosurgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Versatile Cryosurgical Devices Market Analytics
A capital-intensity divergence between integrated system manufacturers and probe-only suppliers is redrawing competitive boundaries in cryosurgical devices. Medtronic leverages its end-to-end cryoablation platform to dominate high-acuity hospital installations. IceCure Medical specializes in percutaneous oncology applications, anchoring its position in image-guided tumor ablation workflows.
Versatile cryosurgical devices employ pressurized cryogens—typically argon or nitrous oxide—delivered through closed-loop or open-loop circuits to achieve tissue temperatures below minus 40 degrees Celsius for targeted cell destruction. These systems serve primary commercial purposes in minimally invasive oncology, dermatology, and interventional cardiology where precise thermal necrosis replaces excisional surgery. Cryoablation systems command the largest installed base among product categories, while cryospray devices capture expanding share in outpatient dermatology settings. Closed-loop technology leads hospital procurement for its gas recovery economics, though high-pressure systems are gaining traction in pain management clinics seeking faster freeze-thaw cycles.
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and market access costs for cryosurgical device manufacturers. ISO 13485 quality management standards and IEC 60601 electrical safety benchmarks further constrain design choices for international commercialization. Stakeholders must monitor evolving reimbursement codes for percutaneous cryoablation across public and private payers to anticipate volume shifts between hospital and ambulatory settings.
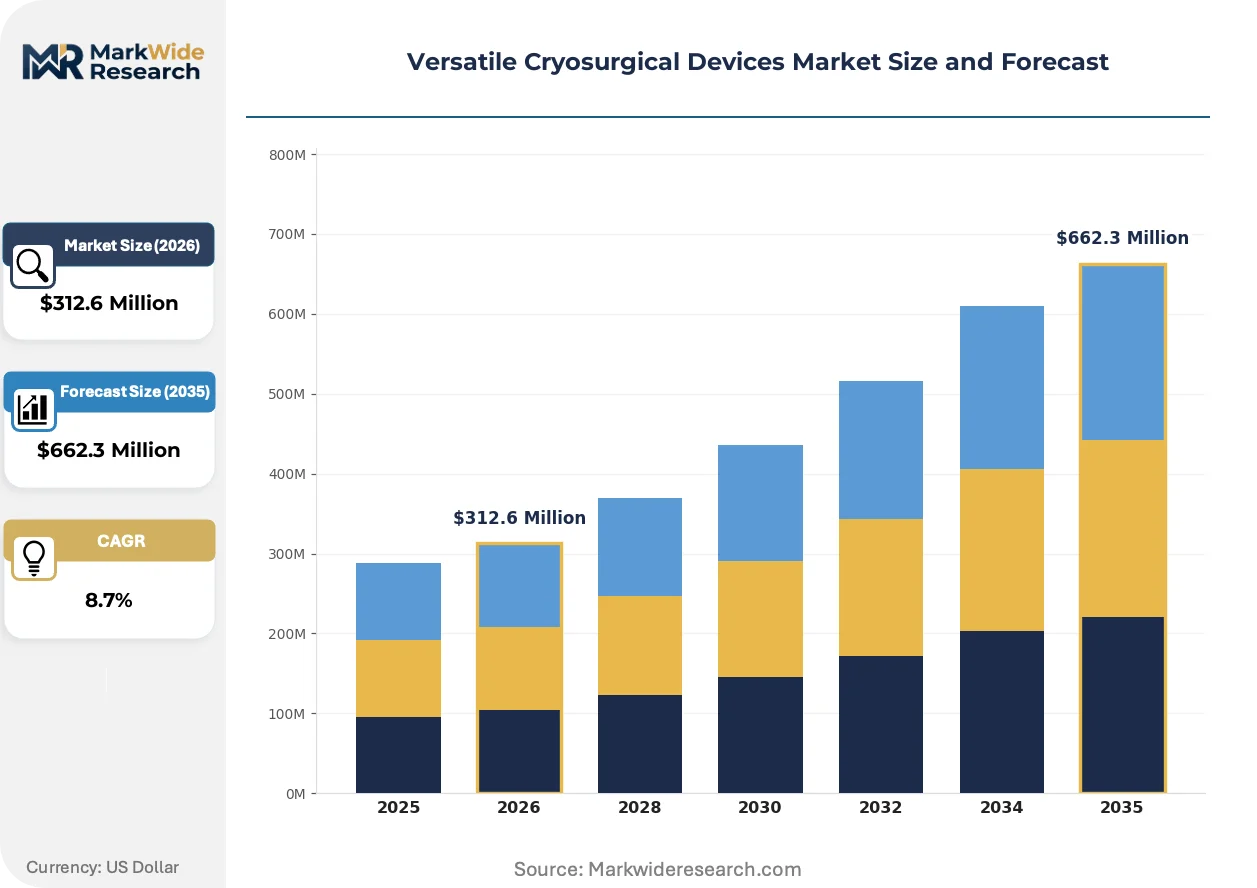
Market Dynamics
Closed-loop argon recovery systems are compressing operating costs for high-volume hospital installations while elevating barriers for probe-only suppliers lacking integrated gas management infrastructure.
Growth Catalysts
- Minimally invasive oncology protocols:Interventional radiology departments in tertiary hospitals are embedding cryoablation into liver and kidney tumor treatment pathways, displacing partial resection procedures.
- EU MDR Article 10 technical documentation:Stricter clinical evidence requirements for class IIa/IIb devices are filtering out marginal competitors and consolidating procurement around established platform vendors.
- Japan's aging surgical population:PMDA reimbursement expansion for percutaneous cryoablation in patients over 75 is channeling demand toward outpatient interventional suites.
Market Restraints
- Argon gas supply concentration:Industrial gas production clusters in the United States Gulf Coast and German Ruhr Valley expose device operators to regional supply disruptions and price volatility.
- Probe thermal mapping limitations:Current sensor arrays cannot reliably monitor ice-ball margins beyond 2.5 centimeters, constraining safe ablation zones in hepatic applications near major vessels.
- MDR notified body capacity:Bottlenecks at designated conformity assessment bodies are extending EU market entry timelines to 18-24 months for novel device submissions.
Strategic Opportunities
- India's tier-2 city hospital expansion:CDSCO streamlined licensing for cryosurgical devices under the 2017 Medical Device Rules is opening procurement channels in Hyderabad, Pune, and Ahmedabad.
- Combination with irreversible electroporation:Hybrid thermal-electric ablation protocols are emerging in pancreatic oncology, creating integrated system demand beyond standalone cryo platforms.
- Direct-to-ambulatory distribution:Specialty distributors are bypassing traditional hospital supply chains to serve pain management clinics with compact nitrous oxide spray units.
Industry Challenges
- Interventional radiology fellowship pipeline:Training program expansion has not matched procedural volume growth, creating operator bottlenecks for complex multi-probe liver ablations.
- ISO 13485 audit backlogs:Certification body scheduling delays are freezing design control documentation for manufacturers pursuing simultaneous FDA and EU submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Versatile Cryosurgical Devices Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryoablation Systems, Cryoprobes, Cryo-Extractors, Cryospray Devices End User: Hospitals, Outpatient Clinics, Surgical Centers, Research Institutions Application: Oncology, Dermatology, Pain Management, Cardiology Technology: Cryo-Control Systems, Closed-Loop Systems, Open-Loop Systems, High-Pressure Systems |
| Companies Covered | Medtronic, IceCure Medical, CooperSurgical, Brymill Cryogenic Systems, Metrum Cryoflex, Galil Medical, Boston Scientific, ERBE Elektromedizin, CryoConcepts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Versatile Cryosurgical Devices Market Evolving Landscape
Real-time magnetic resonance thermometry is redefining procedural confidence boundaries in cryoablation, while reimbursement code consolidation and procurement centralization are reshaping how systems reach end-users.
Ultrathin 17-gauge cryoprobes with integrated thermocouple arrays are displacing standard 14-gauge instruments in renal and lung applications where parenchymal trauma minimization determines patient selection. Interventional radiology departments at academic medical centers are adopting these instruments for same-day discharge protocols. The shift is compressing average probe consumption per procedure while elevating per-unit pricing power for precision-engineered alternatives.
EU MDR Annex XIV post-market clinical follow-up requirements are mandating systematic cryoablation outcome registries across member states. Manufacturers must now fund prospective studies tracking local recurrence rates at 24 and 36 months. High-volume ablation centers in Germany and the Netherlands are responding by consolidating purchasing around vendors with established PMCF infrastructure, disadvantaging smaller entrants lacking clinical affairs scale.
Hospital value analysis committees are unbundling cryosurgical system procurement from disposable probe contracts, forcing separate negotiation tracks for capital equipment and consumables. This bifurcation is disrupting traditional bundled pricing models that cross-subsidized system placement. The pattern is most pronounced in United States integrated delivery networks where procurement centralization has concentrated negotiating leverage with regional system administrators.
Versatile Cryosurgical Devices Market Segmentation
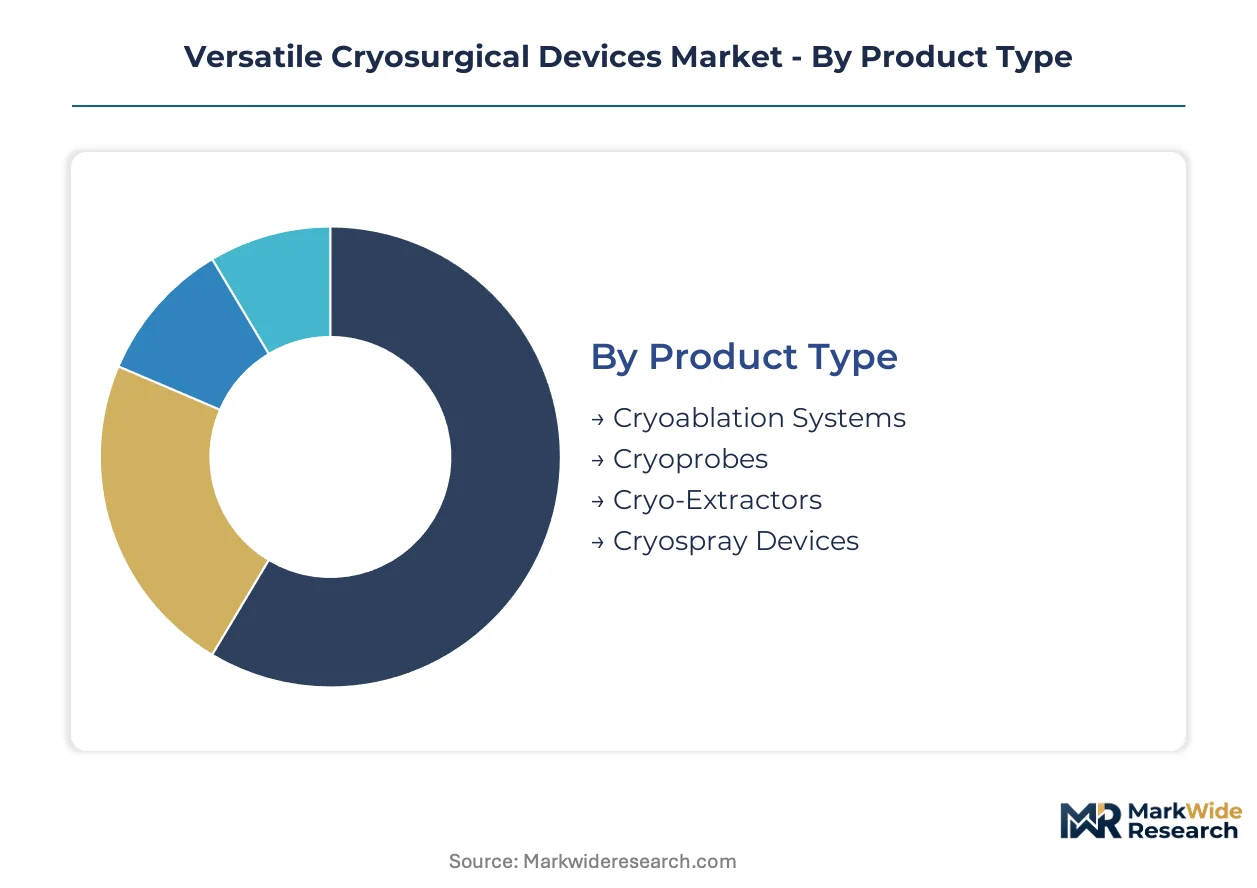
Cryosurgical device procurement follows distinct regulatory and clinical pathways across product configurations. Segmentation reveals where FDA 510(k) clearance complexity, EU MDR class stratification, and reimbursement coding divergences concentrate commercial leverage.
Product Type:
FDA class II device regulations and EU MDR technical documentation requirements create divergent compliance burdens across hardware categories, reshaping vendor specialization patterns.
- Cryoablation Systems:Integrated platforms combine gas delivery consoles with probe interfaces and thermal monitoring arrays. Tertiary hospitals in the United States concentrate procurement here, driven by bundled reimbursement for percutaneous tumor ablation procedures under established CPT codes.
- Cryoprobes:Disposable 14-gauge to 17-gauge instruments with integrated thermocouples define the consumable revenue stream. German university hospitals are expanding probe consumption fastest, responding to EU MDR post-market clinical follow-up mandates that favor high-volume ablation centers with systematic outcome tracking infrastructure.
- Cryo-Extractors:Handheld devices for dermatologic lesion removal operate under simpler regulatory pathways.
- Cryospray Devices:Compact nitrous oxide units target outpatient pain management workflows.
Cryoablation systems handle the majority of throughput; cryoprobes are expanding most quickly on share as procedure volumes outpace console replacement cycles.
End User:
Capital deployment intensity and reimbursement sophistication separate customer tiers, with procurement centralization reshaping how vendors reach decision-makers.
- Hospitals:Integrated delivery networks command multi-million-dollar capital equipment budgets and negotiate unbundled contracts for systems and disposables separately. United States health systems are consolidating cryoablation service lines into interventional radiology hubs, concentrating purchasing authority with value analysis committees.
- Outpatient Clinics:Pain management and dermatology practices acquire compact spray units through specialty distributors bypassing traditional supply chains. Japan's PMDA reimbursement expansion for elderly patients is channeling cryoablation volume toward these settings.
- Surgical Centers:Ambulatory surgical facilities pursue same-day discharge protocols with streamlined cryosurgical workflows.
- Research Institutions:Academic medical centers drive protocol innovation and training program development.
Hospitals absorb the dominant capital share; outpatient clinics are climbing the fastest as reimbursement shifts toward ambulatory settings.
Application:
Clinical evidence thresholds and procedure reimbursement rates determine where manufacturers concentrate product development resources.
- Oncology:Percutaneous liver, kidney, and lung tumor ablation demands real-time imaging integration and precise ice-ball monitoring. Interventional radiology departments at academic medical centers in Germany and the Netherlands are embedding these procedures into standard treatment pathways, displacing partial resection surgeries.
- Dermatology:Cryospray and contact cryotherapy for benign and premalignant skin lesions operate in high-volume, low-acuity settings. Outpatient dermatology clinics in the United States are capturing expanding share as procedure migration accelerates from hospital to office-based settings.
- Pain Management:Cryoneurolysis for chronic neuropathic conditions targets peripheral nerve ablation.
- Cardiology:Cardiac cryoablation for arrhythmia treatment competes with radiofrequency alternatives.
Oncology commands the steepest expansion trajectory; dermatology maintains the broadest installed base across outpatient settings.
Technology:
Gas management economics and freeze-thaw cycle performance specifications divide procurement preferences between closed-loop recovery and high-pressure alternatives.
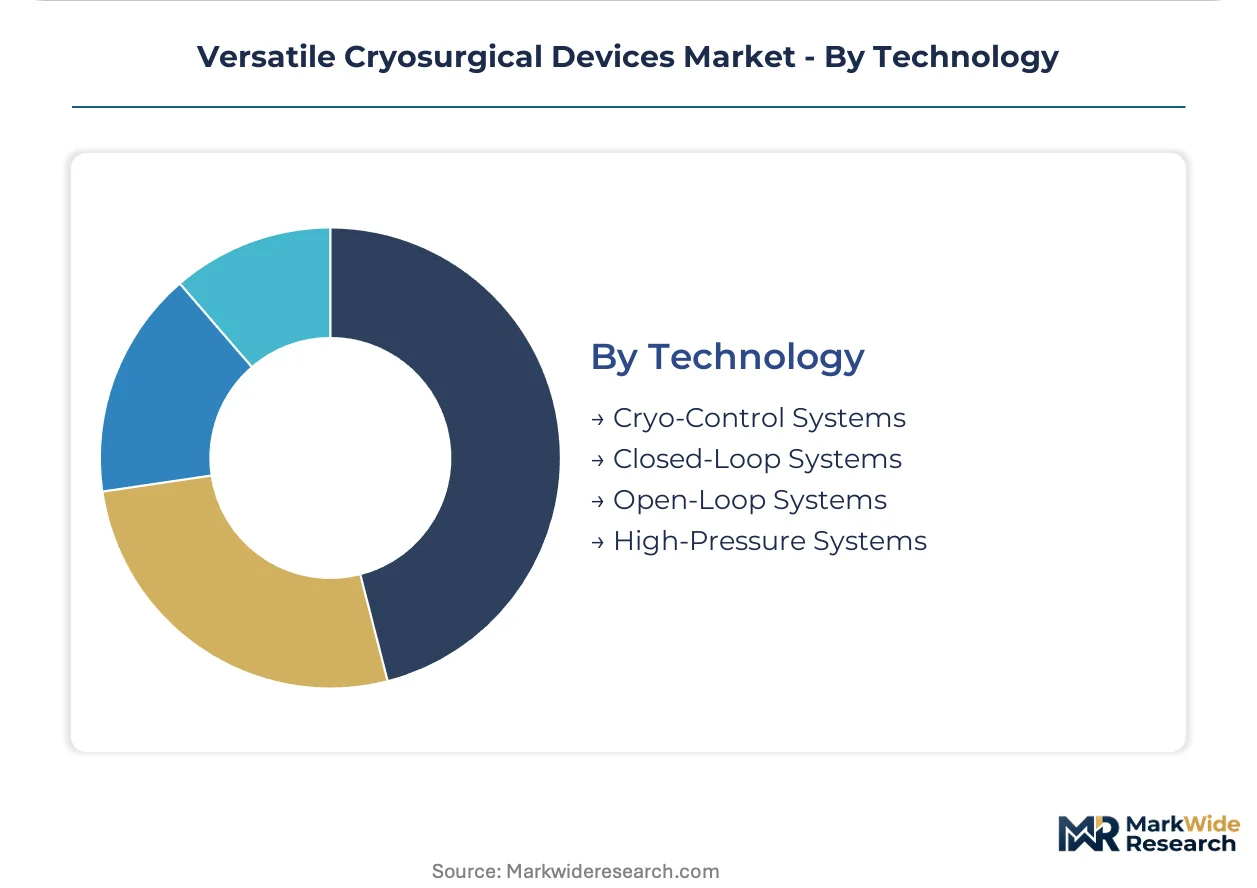
- Closed-Loop Systems:Argon recovery circuits compress operating costs for high-volume hospital installations by capturing and recompressing exhausted cryogen. These systems dominate procurement in the United States where industrial gas supply concentration in the Gulf Coast creates price volatility exposure.
- High-Pressure Systems:Faster freeze-thaw cycles using nitrous oxide at elevated pressures serve pain management clinics prioritizing procedure throughput over gas recovery economics. Japanese outpatient interventional suites are adopting these systems for elderly patient populations requiring rapid session completion.
- Cryo-Control Systems:Thermal monitoring and automated probe regulation software.
- Open-Loop Systems:Simpler exhaust-to-atmosphere designs for lower-volume applications.
Closed-loop systems retain the dominant installed position; high-pressure configurations are gaining share fastest in ambulatory specialty settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across major markets. Japanese outpatient clinics absorb premium pricing for rapid-cycle systems, while Indian tier-2 hospitals negotiate aggressively on capital equipment costs. German university hospitals balance both, demanding advanced thermal monitoring while pressing for unbundled probe contracts.
United States
Interventional radiology departments at tertiary hospitals embed cryoablation into liver and kidney tumor pathways. FDA 510(k) clearance complexity elevates barriers for novel entrants. The Texas Medical Center cluster in Houston concentrates multi-probe ablation volume and drives console replacement demand.
Germany
University hospitals in Baden-Württemberg and North Rhine-Westphalia expand percutaneous oncology procedures under EU MDR post-market clinical follow-up mandates. The Ruhr Valley industrial gas production cluster exposes operators to argon supply price volatility. Munich and Heidelberg academic centers consolidate purchasing around vendors with established PMCF infrastructure.
Japan
PMDA reimbursement expansion for patients over 75 channels cryoablation volume toward outpatient interventional suites. METI industrial standards shape device quality benchmarks for domestic distribution. The Kansai region around Osaka leads ambulatory adoption of compact nitrous oxide systems for elderly populations.
India
CDSCO streamlined licensing under 2017 Medical Device Rules opens procurement channels in Hyderabad, Pune, and Ahmedabad. Tier-2 city hospital expansion drives demand for cost-optimized cryospray units. The Delhi-NCR corridor concentrates training program development for interventional radiology fellows.
United Kingdom
NHS England value analysis committees unbundle system procurement from disposable probe contracts. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment timelines. London and Manchester academic medical centers drive protocol innovation for same-day discharge renal ablation workflows.
Versatile Cryosurgical Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. Integrated platform vendors dominate high-acuity hospital installations with end-to-end cryoablation systems, while probe-only suppliers compete on consumable pricing power. The market structure concentrates around three strategic archetypes: diversified medical technology conglomerates, specialized percutaneous oncology device firms, and regional cryogenic equipment fabricators. M&A activity targets thermal monitoring software capabilities, and strategic partnerships link gas management infrastructure with disposable probe distribution networks.
Within the diversified medical technology tier, Medtronic anchors integrated system provision through its end-to-end platform architecture. IceCure Medical exemplifies the specialized percutaneous oncology archetype, anchoring position in image-guided tumor ablation workflows. Among European cryogenic equipment fabricators, ERBE Elektromedizin occupies a position reflecting German engineering concentration in electrosurgical and thermal ablation device manufacturing.
| Leading Market Players |
|---|
| Medtronic |
| IceCure Medical |
| CooperSurgical |
| Brymill Cryogenic Systems |
| Metrum Cryoflex |
| Galil Medical |
| Boston Scientific |
| ERBE Elektromedizin |
| CryoConcepts |
| Others |
Value Network & Pricing Analysis
Take-or-pay argon supply contracts lock United States hospital systems into multi-year price visibility while insulating Gulf Coast production clusters from spot market volatility. These arrangements tether cryoablation console economics to industrial gas infrastructure concentration, compressing procurement flexibility for high-volume ablation centers.
Pricing Analysis
After-sales probe service contracts and extended warranty tiers drive lifetime value capture for integrated system vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with real-time thermometry from CE-marked alternatives and unbundled probe-only configurations. Pricing pressure stems from hospital value analysis committees unbundling capital equipment from disposable negotiations. Outpatient pain management clinics exhibit highest price sensitivity, while German university hospitals absorb premium positioning for PMCF-compliant platforms.
Supply Chain Analysis
Argon liquefaction capacity chokepoints in the United States Gulf Coast and German Ruhr Valley tether device operators to regional industrial gas production. Cryosurgical manufacturing draws from precision-machined probe components, cryogenic-grade stainless steel, and medical-grade gas delivery systems. Single-source vulnerability concentrates in argon refining infrastructure exposed to hurricane season disruption. Distribution runs through specialty medical device distributors serving interventional radiology departments and hospital supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Versatile cryosurgical devices sit at an early-cycle expansion story where Japan's PMDA reimbursement expansion for elderly patients accelerates ambulatory penetration beyond hospital anchoring.
For Market Incumbents: Consolidate probe manufacturing capacity in Germany to satisfy EU MDR post-market clinical follow-up mandates while absorbing smaller competitors lacking clinical affairs scale. Vertical integration into argon recovery circuit fabrication defends margin position against probe-only suppliers. Lock hospital integrated delivery networks into unbundled yet sticky service contracts that cross-subsidize console placement. For New Entrants and Emerging Players: Anchor in India's tier-2 city hospital expansion where CDSCO streamlined licensing under 2017 Medical Device Rules opens procurement channels absent entrenched vendor relationships. Pain management clinics in Japanese outpatient interventional suites represent the most penetrable end-user segment. Pursue direct-to-ambulatory distribution partnerships bypassing traditional hospital supply chain gatekeepers. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors integrated system vendors with established PMCF infrastructure over probe-only specialists. Thermal monitoring software capabilities and gas management integration represent priority acquisition archetypes over the coming decade. Watch FDA 510(k) clearance timelines for novel probe configurations as the signal indicating whether competitive entry windows are compressing or widening.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex XIV compliance accelerates vendor consolidation around established clinical affairs infrastructure. |
| Hospital System Partnership | Integrated delivery network contracts lock multi-probe ablation volume into interventional radiology hubs. |
| Software Companion Development | Real-time magnetic resonance thermometry integration redefines procedural confidence boundaries. |
| Reimbursement Strategy | PMDA expansion for patients over 75 channels cryoablation toward outpatient interventional suites. |
| Backward Integration | In-house argon recovery circuit production compresses operating costs for high-volume installations. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body submissions, and hospital procurement contract disclosures preceded structured interviews with interventional radiologists, biomedical engineers, GPO contracts managers, and industrial gas supply specialists. Primary fieldwork with tertiary hospital purchasing committees and ambulatory clinic operators combined with secondary validation against CMS Medicare reimbursement data and PMDA pricing bulletins. Bottom-up procedure volume estimates and top-down equipment replacement cycles were triangulated to anchor market sizing.
Variance decomposition across product type, end user, application, and technology segments shaped the analytical framework over the projection horizon. Modeled dimensions included cryoablation system versus cryoprobe revenue splits, hospital versus outpatient clinic procurement patterns, oncology versus dermatology application shares, and closed-loop versus high-pressure technology adoption curves. CAGRs were derived from installed base replacement cycles and procedure volume elasticity to reimbursement expansion. Forecast inputs incorporated interventional radiology fellowship pipeline constraints and EU MDR notified body capacity bottlenecks.
Material uncertainties — argon supply disruptions, MDR conformity assessment delays, and reimbursement code consolidation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and procedural volume growth trajectories. Practitioners should keep alternative scenarios live as industrial gas infrastructure concentration and training program expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Smart Bassinet Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Temperature Sensing Foley Catheter Market