
 Global Anesthesia Delivery Systems Market | 2026-2036
Global Anesthesia Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anesthesia Delivery Systems Market Analysis
Hospital procurement consolidation across North America and Western Europe is recalibrating how anesthesia delivery vendors secure long-term contracts. GE Healthcare leverages its installed base of imaging and monitoring platforms to bundle anesthesia workstations into enterprise agreements. Drägerwerk AG & Co. KGaA anchors its position through specialized ventilation expertise and intensive care interoperability. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. competes on cost-engineered digital monitoring modules tailored to mid-tier hospital budgets in emerging markets.
Anesthesia delivery systems encompass the integrated mechanical, pneumatic, and electronic assemblies that precisely blend medical gases with volatile or intravenous anesthetic agents while continuously monitoring patient respiratory parameters. These systems typically operate at fresh gas flow rates between 0.5 and 15 liters per minute and incorporate vaporizer units calibrated for desflurane, sevoflurane, and isoflurane at 20 degrees Celsius. Integrated systems command the dominant revenue share as hospitals prioritize space-consolidated platforms combining anesthesia machines with patient monitors and ventilator circuits. Digital monitoring technology represents the fastest-expanding segment as automated gas analysis and closed-loop anesthesia control reduce agent waste and improve titration accuracy. General surgery applications sustain the largest procedure volume base, though cardiac procedures generate disproportionate equipment margins due to hemodynamic monitoring complexity.
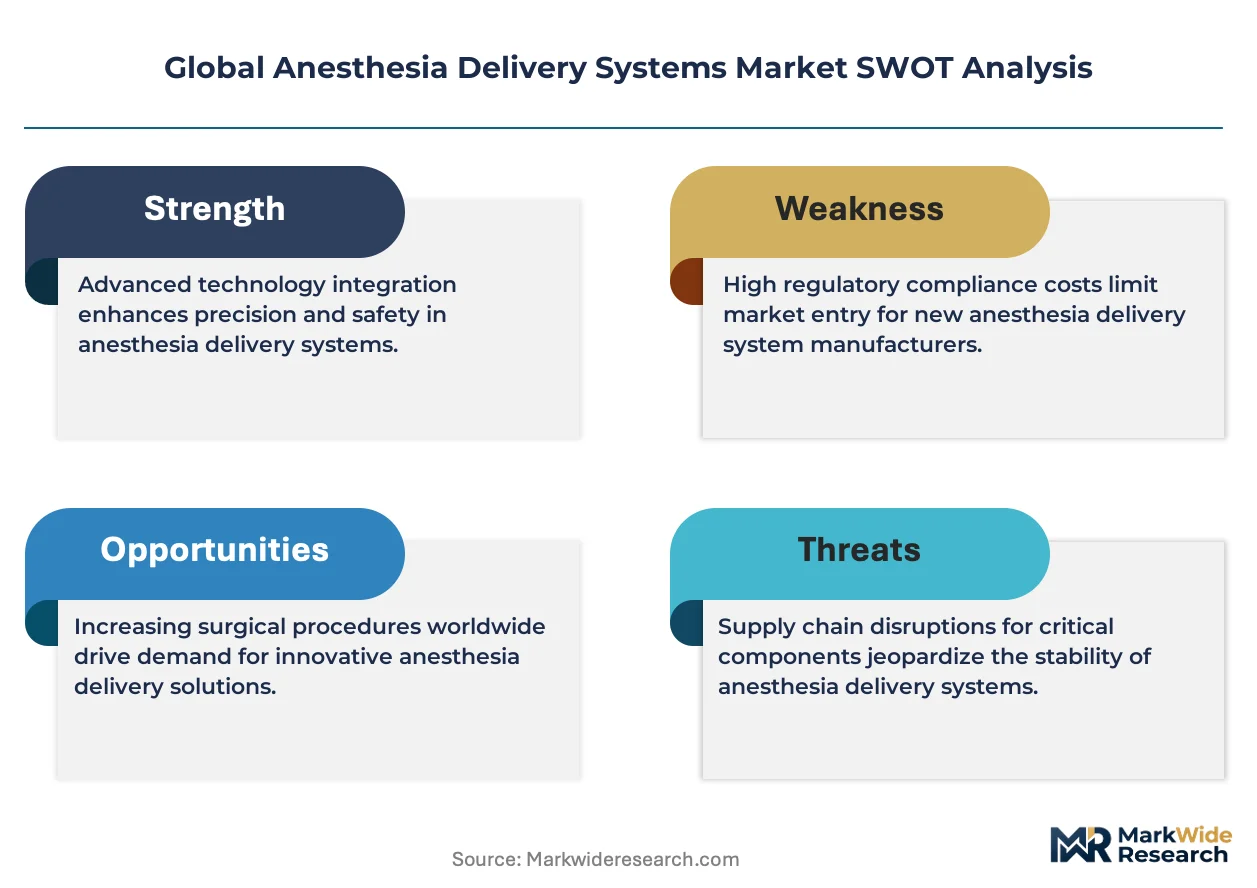
The FDA's premarket notification requirements for anesthesia workstations under 21 CFR 868.5160 and the EU MDR's enhanced clinical evaluation obligations for Class IIb devices elevate barriers for new entrants lacking established quality management systems. China's NMPA implements GB standards for medical electrical equipment safety that diverge from IEC 60601-1 harmonization, creating separate technical file burdens for multinational manufacturers. Stakeholders must monitor how software-as-a-medical-device classifications for automated anesthesia closed-loop algorithms reshape regulatory pathways and post-market surveillance obligations across jurisdictions.
Market Dynamics
Hospital procurement consolidation across North America and Western Europe is concentrating purchasing power into fewer hands, forcing anesthesia delivery vendors to compete through integrated platform offerings rather than standalone machines. This structural shift favors suppliers with broad medical device portfolios capable of enterprise-level contracting.
Growth Catalysts
- Ambulatory surgical center expansion:The United States, Germany, and China are modernizing aging hospital infrastructure while building outpatient surgical networks that require compact, portable anesthesia systems.
- EU MDR Class IIb requirements:Stricter clinical evidence mandates for anesthesia workstations are accelerating replacement cycles as hospitals upgrade to compliant equipment ahead of enforcement deadlines.
- Closed-loop anesthesia algorithms:Software-driven gas titration is reducing agent waste and improving patient safety metrics, creating pull from academic medical centers pursuing quality accreditation.
Market Restraints
- Specialized component supply concentration:Precision vaporizer manufacturing concentrates among German and Japanese suppliers, exposing assemblers to single-source risk for calibrated desflurane and sevoflurane delivery modules.
- Input cost volatility:Medical-grade aluminum and specialized polymers used in breathing circuit housings face price instability tied to energy-intensive smelting operations.
- Regulatory friction:China's NMPA maintains GB standards for medical electrical equipment safety that diverge from IEC 60601-1 harmonization, requiring separate technical file preparation for multinational manufacturers.
Strategic Opportunities
- India's surgical infrastructure buildout:Government hospital modernization programs and private chain expansion create demand for cost-engineered digital monitoring modules suited to mid-tier budgets.
- Software-as-a-medical-device pathways:Automated anesthesia closed-loop algorithms are triggering new regulatory classifications that favor vendors with established quality management systems and post-market surveillance infrastructure.
- Perioperative data integration:Convergence of anesthesia machines with electronic health record systems and surgical scheduling platforms enables predictive maintenance and utilization optimization services.
Industry Challenges
- Biomedical engineering talent scarcity:Shortages of professionals trained in both pneumatic system design and embedded software development are extending product development timelines for integrated platforms.
- Legacy system interoperability:Hospital IT departments face complex integration requirements when connecting new anesthesia workstations to existing patient monitoring networks and data architectures.
- Certification timeline compression:Simultaneous FDA premarket notification, EU MDR conformity assessment, and NMPA registration processes are straining regulatory affairs capacity at mid-sized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anesthesia Delivery Systems Market |
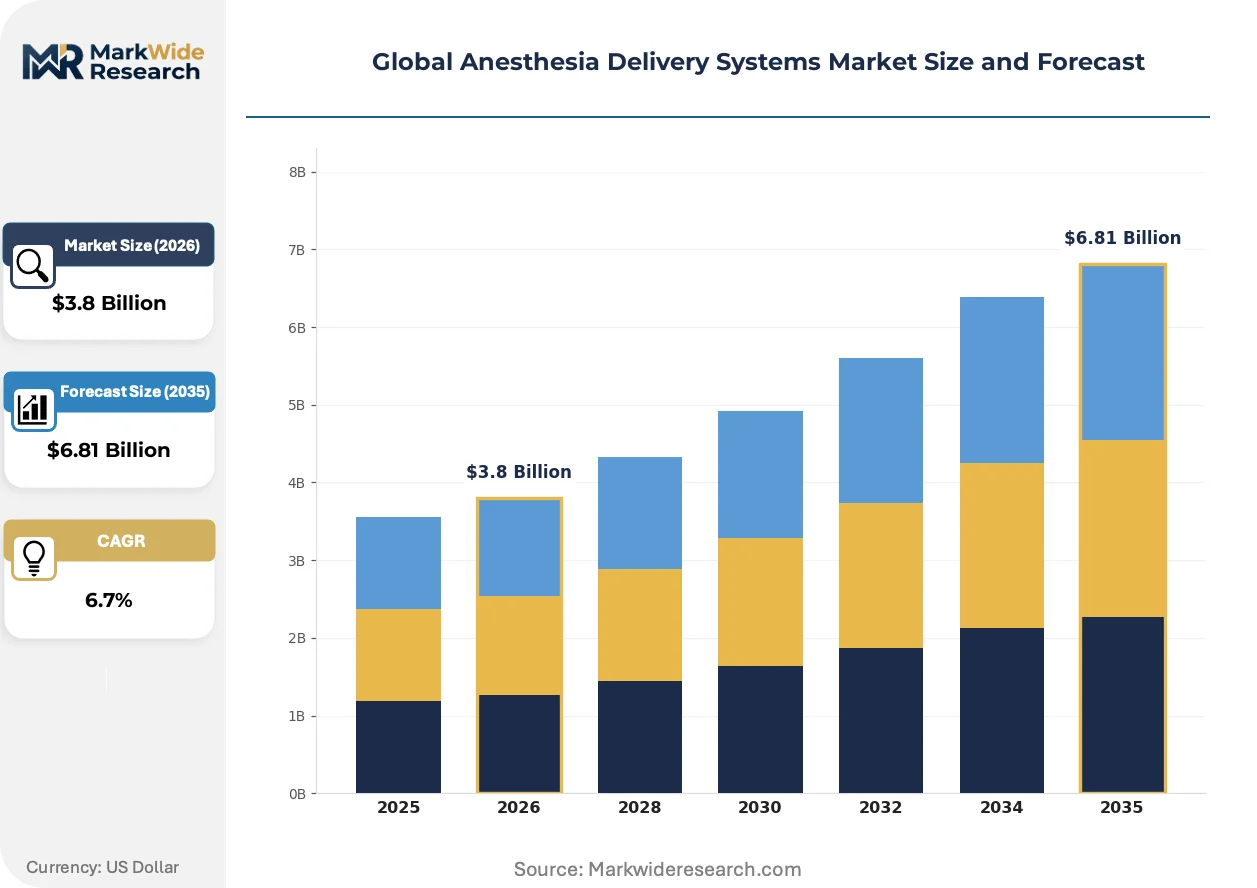
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Anesthesia Machine Workstations, Monitors End User: Hospitals, Surgical Centers, Clinics, Emergency Departments Technology: Volatile Anesthetics, Intravenous Anesthetics, Digital Monitoring, Automated Systems Application: General Surgery, Pain Management, Orthopedic Surgery, Cardiac Procedures |
| Companies Covered | GE Healthcare, Drägerwerk AG & Co. KGaA, Medtronic, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Koninklijke Philips N.V., Getinge AB, Teleflex Incorporated, ICU Medical, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anesthesia Delivery Systems Market Emerging Trajectories
Digital monitoring technology is displacing conventional gas analysis methods across anesthesia delivery platforms, compressing the gap between physiological measurement and automated therapeutic response. Vendors are racing to embed predictive algorithms that anticipate patient state changes before clinical deterioration.
Closed-loop target-controlled infusion systems are unifying pharmacokinetic modeling with real-time respiratory monitoring to automate anesthetic depth management. Academic medical centers in the United States and Germany are piloting these platforms for complex cardiac and neurosurgical procedures. The technology is unifying previously separate ventilation, gas delivery, and patient monitoring workflows into single-screen command interfaces that reduce cognitive load on anesthesia providers.
The EU MDR's enhanced clinical evaluation obligations for Class IIb devices are extending premarket approval timelines and elevating documentation burdens for anesthesia workstation manufacturers. European notified bodies are prioritizing submissions from vendors with robust post-market clinical follow-up systems already operational. Mid-sized manufacturers without established European quality management infrastructure are redirecting commercial focus toward Asian markets with less stringent evidence requirements.
Hospital procurement departments are consolidating anesthesia machine purchasing into multi-year enterprise agreements that bundle equipment, consumables, and preventive maintenance. Integrated delivery networks in the United States are displacing traditional capital equipment purchasing with subscription-based utilization models. This shift is most visible among Catholic health systems and for-profit hospital chains seeking to standardize equipment fleets across dozens of facilities.
Global Anesthesia Delivery Systems Market Segmentation
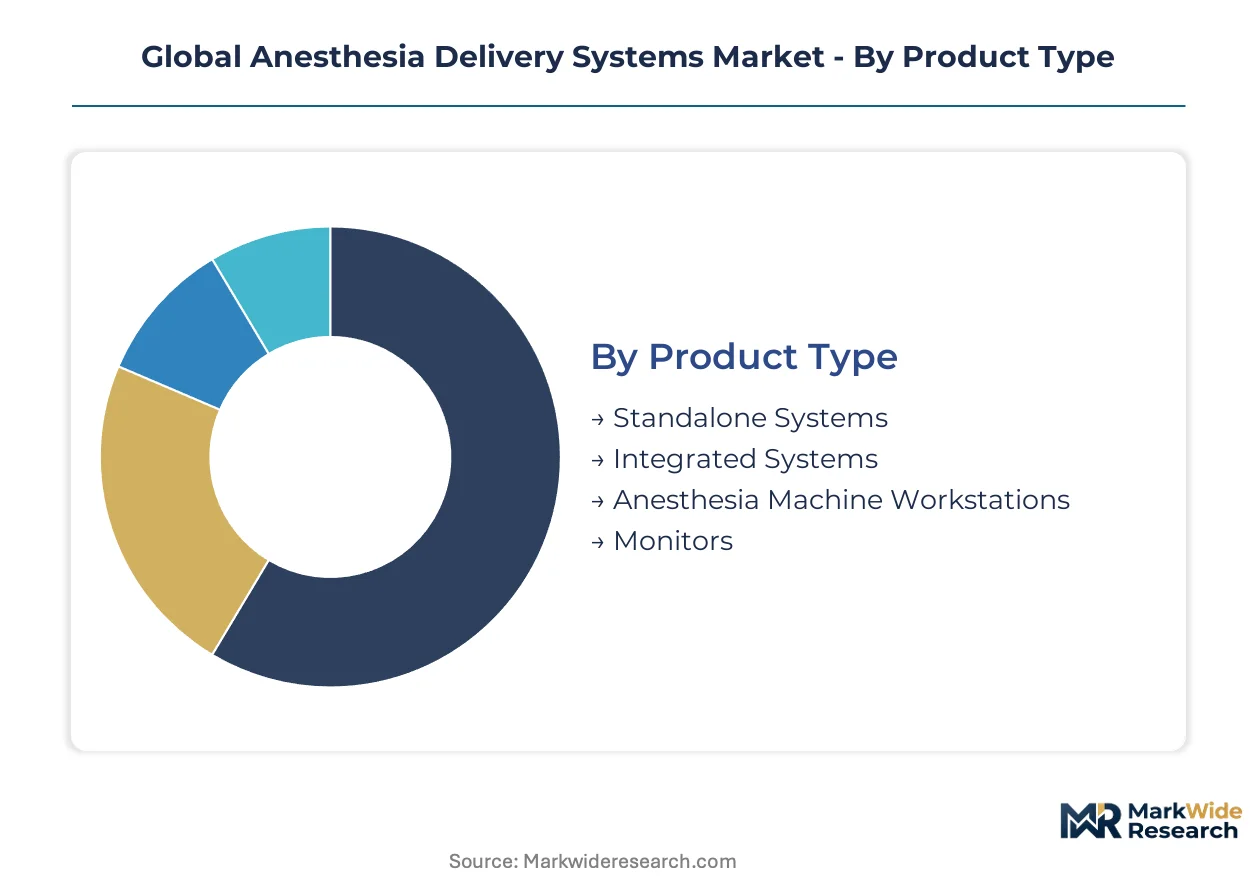
Anesthesia delivery systems fragment across four distinct classification axes that determine procurement patterns, regulatory pathways, and service revenue potential. Product architecture and end-user setting exert the strongest influence on vendor pricing power and replacement cycle timing.
Product Type:
Customization intensity varies sharply across this spectrum, from standardized standalone units to highly configured integrated platforms.
- Integrated Systems:These platforms consolidate anesthesia machines with patient monitors, ventilator circuits, and gas analysis modules into space-optimized footprints. Demand clusters at academic medical centers in the United States and Germany pursuing enterprise fleet standardization. Procurement departments favor these configurations for reduced biomedical engineering training overhead and unified service contracts.
- Standalone Systems:Modular designs permit hospitals to retain existing monitoring infrastructure while upgrading gas delivery capabilities. These units dominate replacement cycles at mid-tier hospitals in India and Southeast Asia where capital constraints limit full-platform investments. Vendors compete on vaporizer calibration accuracy and breathing circuit compatibility with legacy equipment.
- Anesthesia Machine Workstations:Configurable platforms designed for specific surgical disciplines, incorporating specialized ventilation modes for cardiac or neurosurgical procedures.
- Monitors:Dedicated gas analysis and respiratory parameter displays, often deployed as redundancy layers in high-acuity settings.
Leading the category by volume: Integrated Systems. Expanding most quickly: Anesthesia Machine Workstations.
End User:
Facility scale and case complexity create divergent performance requirements and purchasing authority structures.
- Hospitals:These facilities command the largest installed base, with purchasing decisions centralized through value analysis committees and multi-year capital planning cycles. Integrated platform suppliers anchor relationships through enterprise agreements spanning imaging, monitoring, and anesthesia equipment.
- Surgical Centers:Ambulatory settings prioritize compact footprints, rapid turnover capabilities, and simplified user interfaces for nursing staff cross-trained across multiple roles. The United States and China are expanding these networks fastest, driving demand for portable systems with quick-connect gas supply architecture.
- Clinics:Limited procedure volumes favor basic standalone units with minimal monitoring integration, concentrated in pain management and minor orthopedic interventions.
- Emergency Departments:Unpredictable case mix requires rapid-deployment systems with broad ventilation mode flexibility and robust battery backup for transport scenarios.
Capturing the largest revenue share: Hospitals. Steepest expansion trajectory: Surgical Centers.
Technology:
Agent delivery modality and automation level determine regulatory classification and clinical workflow integration depth.
- Digital Monitoring:Real-time gas analysis, spirometry, and capnography with automated alarm thresholds and trend visualization. Academic medical centers in Germany and the United States are deploying these modules for quality accreditation and closed-loop research protocols.
- Automated Systems:Target-controlled infusion pumps and closed-loop anesthesia algorithms that unify pharmacokinetic modeling with respiratory feedback. Regulatory pathways for these software-as-a-medical-device platforms remain unsettled across FDA, EU MDR, and NMPA jurisdictions.
- Volatile Anesthetics:Conventional vaporizer-based delivery of desflurane, sevoflurane, and isoflurane through precision-calibrated modules.
- Intravenous Anesthetics:Syringe pumps and infusion controllers for propofol, remifentanil, and adjunctive agents, typically deployed in total intravenous anesthesia protocols.
Highest margin concentration: Automated Systems. Gaining share fastest: Digital Monitoring.
Application:
Procedure-specific hemodynamic and ventilatory demands drive configuration differentiation and monitoring complexity.
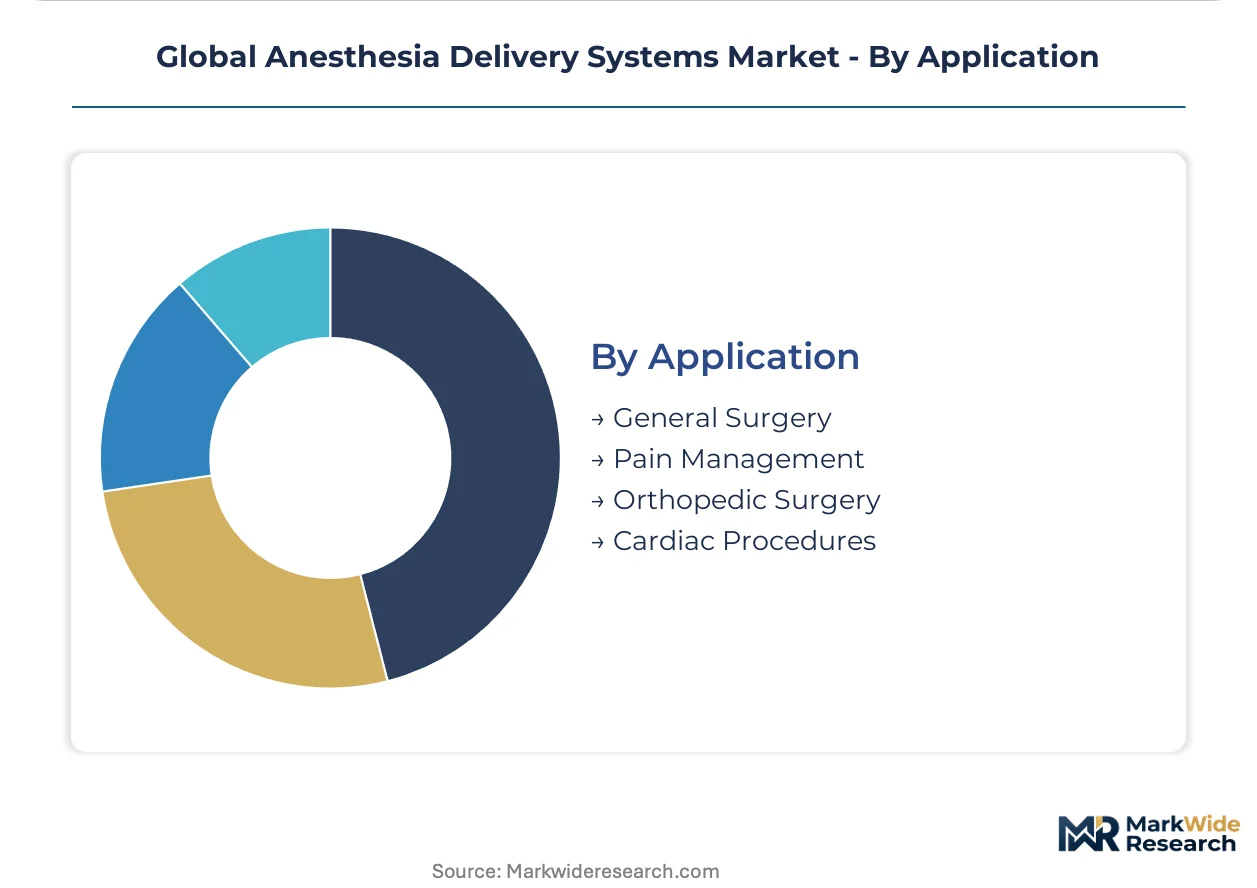
- General Surgery:The broadest procedure category spanning abdominal, thoracic, and soft tissue interventions, sustaining the largest equipment volume base. Standard ventilation modes and basic gas monitoring satisfy most requirements, limiting premium pricing potential.
- Cardiac Procedures:Cardiopulmonary bypass coordination, transesophageal echocardiography integration, and advanced hemodynamic monitoring generate disproportionate equipment margins. Demand concentrates at tertiary centers in the United States, Germany, and China with established cardiothoracic surgery programs.
- Orthopedic Surgery:Positioning requirements and tourniquet management create specialized ventilation and nerve monitoring needs, particularly for spine and major joint reconstruction.
- Pain Management:Sedation depth monitoring and respiratory depression detection predominate, with lighter anesthesia requirements enabling compact system designs.
Dominating procedure volume: General Surgery. Generating highest equipment margins: Cardiac Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for anesthesia delivery systems concentrates in the United States, Germany, and China as these nations expand ambulatory surgical center networks and modernize aging hospital infrastructure. Each geography presents distinct regulatory pathways and procurement dynamics that reshape vendor competitive positioning.
United States
Ambulatory surgical center expansion drives procurement of compact, portable anesthesia systems with quick-connect gas supply architecture. The FDA's premarket notification requirements under 21 CFR 868.5160 extend approval timelines for workstation manufacturers. Hospital procurement consolidation across Catholic health systems and for-profit chains concentrates purchasing power into enterprise agreements spanning multiple facilities.
Germany
Academic medical centers in Bavaria and Baden-Württemberg pursue enterprise fleet standardization of integrated platforms combining anesthesia machines with patient monitors. The EU MDR's enhanced clinical evaluation obligations for Class IIb devices accelerate replacement cycles ahead of enforcement deadlines. Precision vaporizer manufacturing clusters in southwestern industrial zones expose assemblers to single-source supply risk for calibrated delivery modules.
China
Government hospital modernization programs and private chain expansion create demand for cost-engineered digital monitoring modules suited to mid-tier budgets. The NMPA implements GB standards for medical electrical equipment safety that diverge from IEC 60601-1 harmonization, requiring separate technical file preparation. Manufacturing concentrates in Shenzhen and surrounding Pearl River Delta electronics corridors.
India
Government hospital modernization programs and private chain expansion generate procurement volume for standalone systems compatible with legacy monitoring infrastructure. The CDSCO's medical device regulations create registration pathways distinct from European and American frameworks. Demand clusters in Maharashtra and Karnataka where tertiary care networks are expanding cardiothoracic surgery capabilities.
Japan
Aging hospital infrastructure and surgical volume growth sustain replacement demand for anesthesia workstations with advanced ventilation modes. The PMDA's quality management system requirements align with international standards while maintaining distinct documentation protocols. Industrial concentration in the Chubu region around Nagoya supports precision component supply chains for vaporizer calibration systems.
Global Anesthesia Delivery Systems Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-driven automation and closed-loop anesthesia algorithms as differentiation vectors. Market structure tilts toward consolidation as hospital procurement departments bundle anesthesia machine purchasing into multi-year enterprise agreements covering equipment, consumables, and preventive maintenance. Three archetypes dominate: diversified medical technology conglomerates with imaging and monitoring portfolios, specialized ventilation and respiratory equipment manufacturers, and cost-engineered digital module suppliers targeting emerging market budgets. Competitive moves center on strategic partnerships for perioperative data integration and portfolio diversification into automated anesthesia closed-loop systems.
Within the diversified technology tier, GE Healthcare leverages its installed base of imaging platforms to anchor enterprise contracting relationships. Drägerwerk AG & Co. KGaA exemplifies the specialized ventilation archetype through intensive care interoperability and precision gas delivery expertise. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. occupies a position among cost-engineered module suppliers targeting mid-tier hospital budgets in Asia-Pacific and emerging markets.
| Leading Market Players |
|---|
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Koninklijke Philips N.V. |
| Getinge AB |
| Teleflex Incorporated |
| ICU Medical |
| Ambu A/S |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation across the United States and Germany is forcing anesthesia delivery vendors toward multi-year enterprise agreements that bundle equipment, consumables, and preventive maintenance, compressing margins on standalone machines while elevating pricing power for integrated platform suppliers with broad medical device portfolios.
Pricing Analysis
Volume concentrates in standardized standalone units for mid-tier hospitals, while margins accrue to automated systems with closed-loop algorithms and cardiac procedure configurations. Price differentiation hinges on FDA 510(k) clearance tier and EU MDR Class IIb certification status alongside after-sales service bundling. Pricing pressure stems from cost-engineered digital modules from Shenzhen-based manufacturers penetrating Asian and Latin American markets. Surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers in Germany and the United States prioritize interoperability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with precision vaporizer manufacturing clusters in southwestern Germany and Japan's Chubu region around Nagoya, exposing assemblers to concentrated supply risk for calibrated desflurane and sevoflurane delivery modules. Component sourcing draws from German precision engineering, Japanese electronics, and Chinese aluminum and polymer processing for breathing circuit housings. Supply chain risk centers on energy-intensive smelting operations creating medical-grade aluminum price volatility. Distribution runs through hospital GPO contracts in the United States, centralized procurement consortia in Germany, and government tender systems in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anesthesia delivery market sits in a technology-transition phase as digital monitoring and closed-loop algorithms displace conventional gas analysis methods, creating asymmetric opportunities for vendors with embedded software capabilities versus legacy pneumatic specialists.
For Market Incumbents: Extend enterprise contracting relationships by bundling anesthesia workstations with imaging and monitoring platforms into multi-facility agreements that raise switching costs. Incumbents must accelerate backward integration into precision vaporizer manufacturing to mitigate single-source supply exposure from German and Japanese component suppliers. Investment in FDA 510(k) and EU MDR quality management infrastructure defends against software-as-a-medical-device entrants targeting automated anesthesia algorithms. For New Entrants and Emerging Players: EU MDR Class IIb requirements in Germany and neighboring European markets open a window for compliant mid-tier systems as established vendors face documentation burdens and extended approval timelines. New entrants should target India's surgical infrastructure buildout with cost-engineered standalone units compatible with legacy monitoring infrastructure. A software-first go-to-market angle emphasizing closed-loop anesthesia algorithms for academic medical centers bypasses capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: The window for entry favors specialized ventilation and respiratory equipment manufacturers with intensive care interoperability expertise and established European notified body relationships. Long-term viability over the coming decade rests on perioperative data integration capabilities and automated anesthesia algorithm portfolios. The signal to watch is FDA guidance finalization on software-as-a-medical-device classifications for closed-loop control systems, which would trigger acquisition premiums for algorithm developers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for automated anesthesia workstations in the United States. |
| CE Marking Pathway | EU MDR Class IIb compliance enables replacement cycle capture across German hospital networks. |
| Hospital System Partnership | Enterprise agreements with Catholic health systems lock out competing vendors. |
| Software Companion Development | Closed-loop algorithms integrated with EHR systems create recurring revenue streams. |
| Reimbursement Strategy | Coverage for automated anesthesia monitoring drives adoption at academic medical centers. |
Methodological Framework
Independent corroboration across primary interviews with anesthesia department heads, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers, combined with secondary validation through FDA 510(k) filings, EU MDR notified body submissions, hospital procurement databases, and CMS Medicare reimbursement data, underwrites the qualitative findings. Bottom-up unit demand modeling triangulates against top-down market sizing from equipment manufacturer revenue disclosures and regional healthcare infrastructure investment tracking.
Rate-of-change decomposition separates volume growth from value expansion across product type, technology tier, end-user setting, application complexity, and regional regulatory cluster dimensions over the projection horizon. CAGRs derive from procedure volume trajectories, replacement cycle timing, and pricing elasticity assumptions. Forecast inputs incorporate ambulatory surgical center expansion rates in the United States, China, and Germany alongside EU MDR compliance-driven replacement acceleration.
The model assumes a particular technology adoption path; alternative pathways for closed-loop anesthesia algorithms would alter the outlook if regulatory classifications delay software-as-a-medical-device approvals or if hospital IT integration timelines extend beyond baseline assumptions. Forecasts reflect documented assumptions about procurement consolidation velocity and component supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Epinephrine Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Aspirating System Market