
 Liver-On-Chip Market | 2026-2036
Liver-On-Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Liver-On-Chip Market Analysis
Physiologically relevant hepatic models is redrawing competitive boundaries in liver-on-chip development. Emulate, Inc. leverages its human emulation system to anchor high-value partnerships with pharmaceutical developers. CN Bio Innovations Ltd sustains technology leadership through its PhysioMimix platform, while MIMETAS B.V. specializes in organ-on-a-chip applications with its OrganoPlate technology for perfused 3D tissue culture.
Liver-on-chip devices integrate microfluidic channels with living hepatic cells to replicate organ-level physiology, typically incorporating primary human hepatocytes, Kupffer cells, and stellate cells within polydimethylsiloxane or thermoplastic constructs to enable real-time metabolic and toxicological assessment. Microfluidics dominates current product architecture due to its precision in controlling shear stress and nutrient gradients, while drug testing commands the largest application share as sponsors seek alternatives to animal models. 3D bioprinting represents the fastest-growing technology segment, though organ-on-a-chip platforms retain the broadest installed base across academic and commercial laboratories.
The FDA's Modernization Act 2.0 explicitly authorizes alternatives to animal testing, directly expanding addressable demand for liver-on-chip validation studies. EMA guidelines on non-clinical safety evaluation increasingly reference microphysiological systems, while ISO 10993 biocompatibility standards shape material selection for device manufacturers. Stakeholders must monitor evolving qualification pathways between regulator-accepted methods and platform-specific validation requirements.
Market Dynamics
Microphysiological systems are consolidating preclinical testing workflows as pharmaceutical sponsors face mounting pressure from FDA Modernization Act 2.0 mandates to validate alternatives to animal models.
Growth Catalysts
- FDA Modernization Act 2.0:The US mandate explicitly authorizes non-animal testing methods, compelling pharmaceutical sponsors to commission liver-on-chip validation studies for IND submissions.
- EMA microphysiological system guidelines:European safety evaluation protocols increasingly reference organ-on-chip data, creating regulatory pull for platform adoption across toxicology departments.
- Primary human hepatocyte sourcing:Biobank networks in Germany and Japan are expanding cryopreserved cell availability, reducing supply bottlenecks for model construction.
Market Restraints
- PDMS material constraints:Polydimethylsiloxane absorbs hydrophobic compounds, creating analytical interference that limits predictive confidence for lipophilic drug candidates.
- Primary cell supply concentration:Viable human hepatocyte sourcing clusters among three US tissue recovery organizations, creating price volatility and batch-to-batch inconsistency.
- ISO 10993 qualification timelines:Biocompatibility certification for thermoplastic device materials extends development cycles by 14-18 months versus conventional cultureware.
Strategic Opportunities
- Non-alcoholic steatohepatitis modeling:Drug developers lack validated in vitro systems for NASH progression, creating white space for stellate cell-inclusive platform extensions.
- Japan PMDA qualification pathway:METI funding for organ-on-chip standardization positions Japanese pharmaceutical partnerships as early regulatory precedents.
- 3D bioprinting convergence:Integration of extrusion-based deposition with microfluidic perfusion enables spatially patterned co-culture architectures unavailable in molded devices.
Industry Challenges
- Microfluidic engineering talent scarcity:Device manufacturers compete with semiconductor and diagnostics sectors for finite pools of chip fabrication specialists.
- Multi-site reproducibility certification:Sponsors require cross-laboratory validation studies that consume 24-36 months and strain early-stage platform economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver-On-Chip Market |
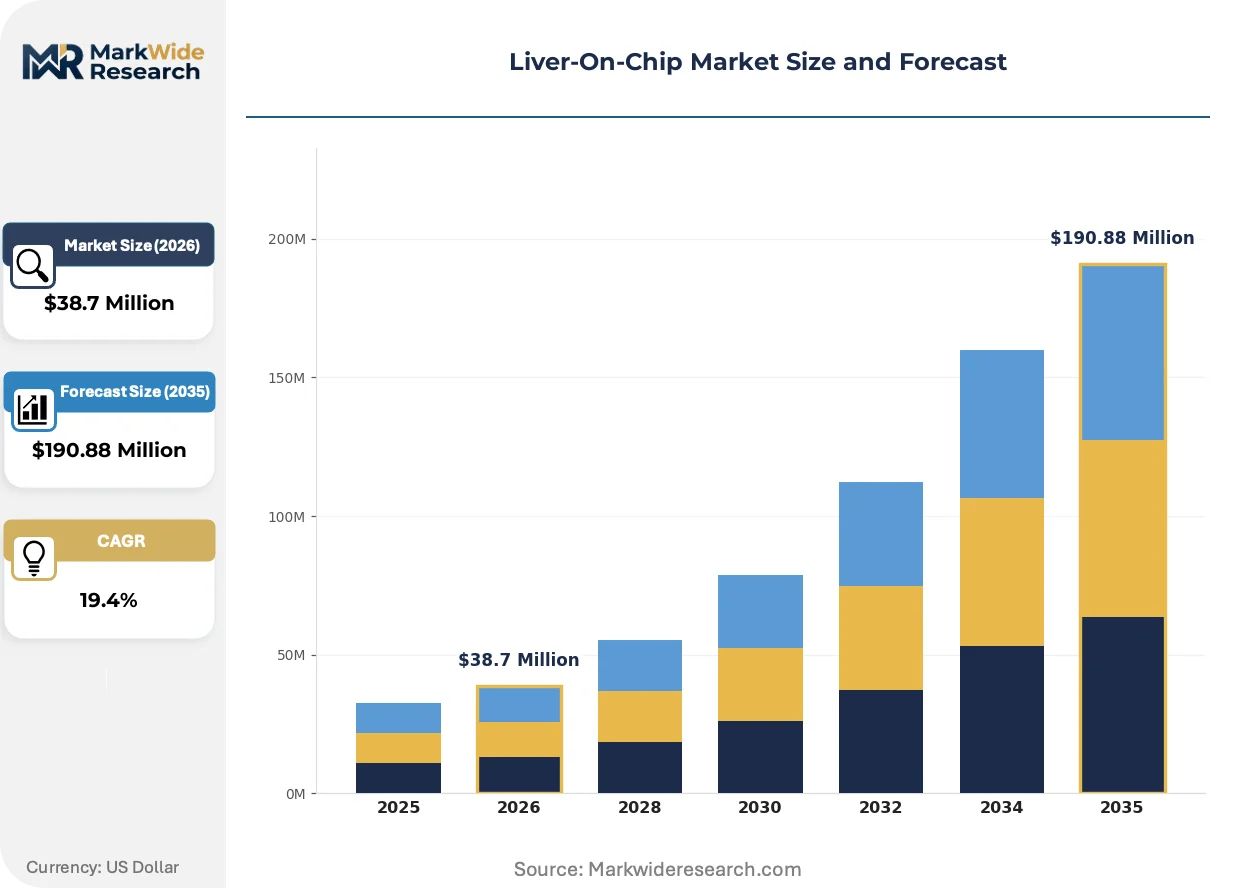
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $190.88 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidics, Biomaterials, Sensors, Culture Systems Application: Drug Testing, Toxicity Assessment, Disease Modeling, Personalized Medicine End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations Technology: 3D Bioprinting, Organ-on-a-Chip, Cell Culture, Tissue Engineering |
| Companies Covered | Emulate, Inc., CN Bio Innovations Ltd, InSphero AG, MIMETAS B.V., TissUse GmbH, Hesperos, Inc., Nortis, Inc., Kirkstall Ltd, Tara Biosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver-On-Chip Market Emerging Trajectories
Bioprinting workflows are compressing the fabrication timeline for complex hepatic tissue architectures while regulatory qualification frameworks mature across multiple jurisdictions.
Thermoplastic cyclic olefin polymers are supplanting polydimethylsiloxane as the substrate of choice for pharmaceutical toxicology applications. Bristol-Myers Squibb and Roche have specified COC devices for 2024-2025 hepatic metabolism studies. The shift is supplanting incumbent PDMS platforms in high-value regulatory submission workflows where compound absorption artifacts compromise data integrity.
EMA's 2023 reflection paper on microphysiological systems established evidentiary standards for organ-on-chip data in marketing authorization dossiers. The framework requires sponsors to demonstrate physiological relevance against reference compounds with known clinical toxicities. German and French toxicology consortia are coordinating multi-site qualification studies to satisfy these thresholds.
Pharmaceutical procurement departments are unbundling device supply from analytical service contracts, forcing platform vendors to compete on hardware margins rather than integrated study fees. Contract research organizations in Massachusetts and North Carolina are building captive liver-on-chip capabilities to recapture outsourced revenue. The disaggregation is most pronounced among top-20 sponsors with internal microphysiological systems groups.
Liver-On-Chip Market Segmentation
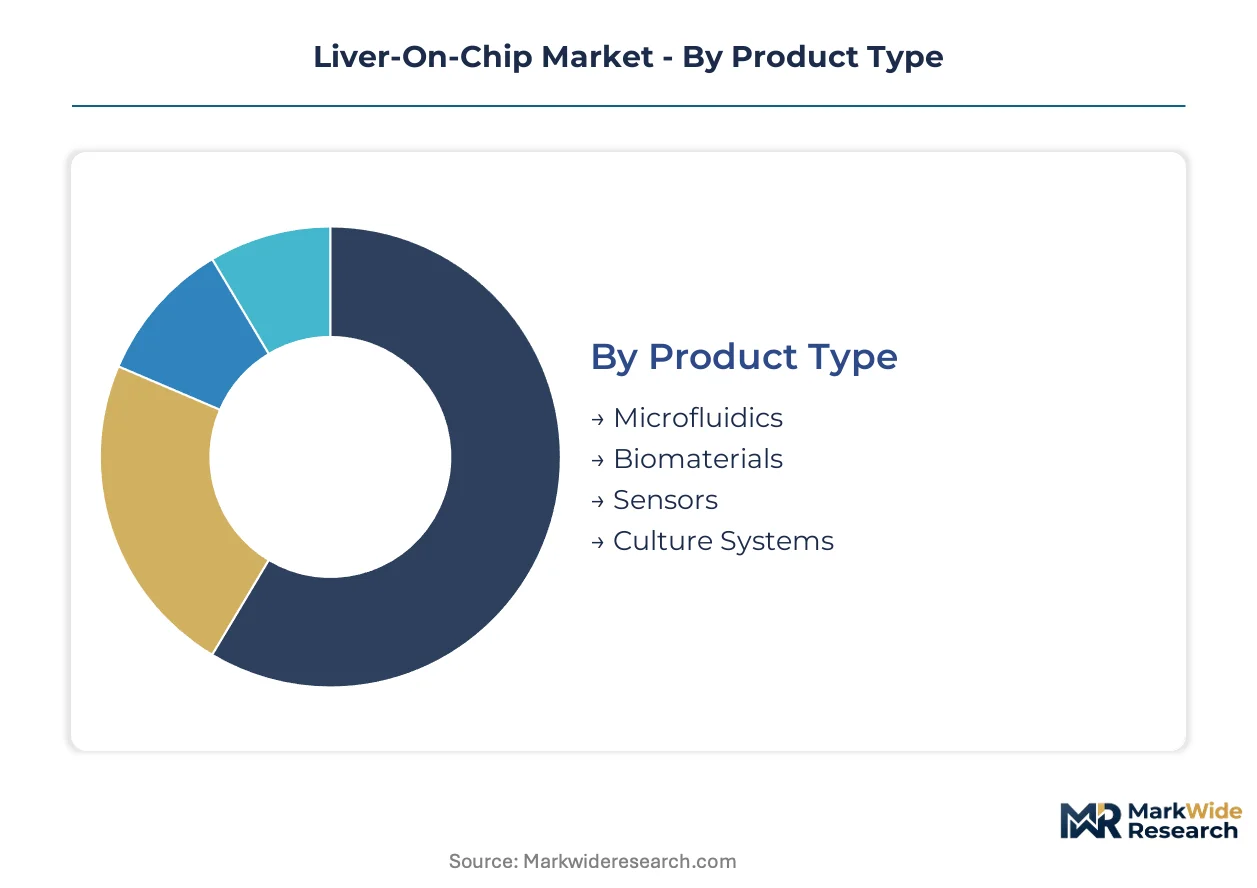
Liver-on-chip platforms fragment across four distinct taxonomies that determine procurement patterns and validation requirements. Product architecture choices directly constrain compound compatibility, while application focus shapes regulatory submission pathways. End-user sophistication and technology maturity further stratify vendor selection criteria.
Product Type:
Microfluidic substrates face the most acute substitution pressure from thermoplastic alternatives as pharmaceutical sponsors reject PDMS absorption artifacts in high-stakes IND workflows.
- Microfluidics:Precision-engineered channels in polydimethylsiloxane or cyclic olefin polymer control shear stress and nutrient gradients at micron-scale resolution. Bristol-Myers Squibb and Roche have specified thermoplastic devices for hepatic metabolism studies, displacing legacy PDMS platforms where lipophilic compound absorption compromises data integrity.
- Biomaterials:Extracellular matrix scaffolds and hydrogel formulations enable 3D hepatic cell embedding with tunable stiffness profiles matching native liver tissue. German biobank networks are expanding cryopreserved matrix availability, reducing supply bottlenecks for model construction.
- Sensors:Integrated electrochemical and optical transducers enable real-time metabolic readouts.
- Culture Systems:Perfusion bioreactors and multi-well plates support longitudinal hepatocyte viability.
Microfluidics retains volume leadership; biomaterials holds the steepest expansion curve.
Application:
Cost tiering separates commodity toxicology screening from premium disease modeling contracts with bespoke cell sourcing requirements.
- Drug Testing:Hepatic metabolism and drug-drug interaction studies dominate current commercial deployment as sponsors seek alternatives to animal models under FDA Modernization Act 2.0 mandates. Contract research organizations in Massachusetts and North Carolina are building captive capabilities to recapture outsourced revenue from top-20 pharmaceutical sponsors.
- Toxicity Assessment:Hepatotoxicity prediction against reference compounds with known clinical outcomes anchors regulatory qualification frameworks. EMA's reflection paper requires physiological relevance demonstrations for marketing authorization dossiers.
- Disease Modeling:Non-alcoholic steatohepatitis progression systems remain technically immature.
- Personalized Medicine:Patient-derived hepatocyte platforms command premium pricing for rare disease applications.
Drug testing captures the largest contract value; disease modeling is climbing the fastest.
End User:
Customer type determines validation burden and procurement autonomy.
- Pharmaceutical Companies:Internal microphysiological systems groups at top-20 sponsors are unbundling device supply from analytical service contracts, forcing platform vendors to compete on hardware margins. FDA IND submission requirements drive qualification study investments spanning 24-36 months.
- Biotechnology Firms:Venture-funded developers prioritize rapid assay turnaround over cross-laboratory reproducibility certification.
- Academic Institutions:NIH and METI funding supports exploratory organ-on-chip research without regulatory submission pressures.
- Research Organizations:German and French toxicology consortia coordinate multi-site qualification studies to satisfy EMA evidentiary thresholds.
Pharmaceutical companies dominate procurement volume; biotechnology firms are expanding most aggressively.
Technology:
Maturity gaps separate established cell culture methods from emerging fabrication approaches.
- 3D Bioprinting:Extrusion-based deposition integrated with microfluidic perfusion enables spatially patterned co-culture architectures unavailable in molded devices. Japan METI funding for organ-on-chip standardization positions Japanese pharmaceutical partnerships as early regulatory precedents for bioprinted hepatic tissues.
- Organ-on-a-Chip:Microphysiological systems retain the broadest installed base across academic and commercial laboratories. Multi-site reproducibility certification requirements strain early-stage platform economics.
- Cell Culture:Conventional 2D hepatocyte plating faces displacement pressure from 3D alternatives.
- Tissue Engineering:Decellularized scaffold approaches remain confined to research applications.
Organ-on-a-chip maintains installed base leadership; 3D bioprinting is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across procurement contexts. Academic laboratories prioritize lowest per-assay costs. Pharmaceutical sponsors accept premium pricing for regulatory-grade validation data.
United States
FDA Modernization Act 2.0 mandates are compelling Bristol-Myers Squibb and Roche to commission liver-on-chip validation studies for IND submissions. The agency's explicit authorization of non-animal methods creates regulatory pull across toxicology departments. Greater Boston and Research Triangle Park clusters host contract research organizations building captive microphysiological capabilities.
Germany
EMA microphysiological system guidelines are reshaping evidentiary requirements for marketing authorization dossiers. German toxicology consortia coordinate multi-site qualification studies to satisfy these thresholds. Berlin and Heidelberg biobank networks are expanding cryopreserved hepatocyte availability, reducing supply bottlenecks for model construction.
Japan
METI funding for organ-on-chip standardization positions Japanese pharmaceutical partnerships as early regulatory precedents. PMDA qualification pathways for microphysiological systems are advancing through government-industry collaboration. Kanto and Kansai industrial corridors concentrate device fabrication and cell sourcing infrastructure.
United Kingdom
CN Bio Innovations anchors domestic technology leadership through its PhysioMimix platform. UK Research and Innovation funding supports academic-commercial translation partnerships. Cambridge and Oxford clusters integrate microfluidic engineering with hepatocyte biology expertise.
Netherlands
MIMETAS B.V. specializes in organ-on-chip applications with its OrganoPlate technology for perfused 3D tissue culture. Dutch semiconductor fabrication heritage supplies microfluidic engineering talent pools. Eindhoven and Leiden clusters bridge chip manufacturing precision with biological application development.
Liver-On-Chip Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The vendor base spans microfluidic platform specialists, biomaterials suppliers, and integrated service providers. Three strategic archetypes dominate: regulatory-grade platform vendors, academic spin-outs with novel fabrication methods, and contract research organizations building captive capabilities. M&A activity concentrates on cell sourcing networks and biocompatibility certification assets. Strategic partnerships between device manufacturers and pharmaceutical sponsors are displacing pure hardware procurement.
Among platform specialists, Emulate, Inc. and CN Bio Innovations Ltd occupy positions exemplifying the regulatory-grade archetype, while MIMETAS B.V. represents the European microfluidic technology tier. These companies anchor competitive positioning through differentiated approaches to physiological relevance and pharmaceutical partnership structures.
| Leading Market Players |
|---|
| Emulate, Inc. |
| CN Bio Innovations Ltd |
| InSphero AG |
| MIMETAS B.V. |
| TissUse GmbH |
| Hesperos, Inc. |
| Nortis, Inc. |
| Kirkstall Ltd |
| Tara Biosystems |
| Others |
Supply Flow & Price Mechanics
Thermoplastic cyclic olefin polymers replacing polydimethylsiloxane simultaneously relocate device fabrication toward pharmaceutical-grade manufacturing clusters and compress margins on legacy PDMS platforms as sponsors reject absorption-compromised data in regulatory submissions.
Pricing Analysis
Service contracts and validation study fees generate lifetime value exceeding hardware margins by substantial multiples as pharmaceutical sponsors unbundle procurement. Three-tier pricing structure across regulatory-grade, research-grade, and exploratory tiers separates IND-ready platforms from academic configurations. Cost compression in research-grade segments is intensifying because contract research organizations are building captive capabilities. Biotechnology firms exhibit highest price sensitivity; top-20 pharmaceutical sponsors accept premium positioning for cross-laboratory reproducibility certification.
Supply Chain Analysis
The United States, Germany, and Japan anchor hepatocyte sourcing networks and microfluidic fabrication infrastructure for liver-on-chip production. Primary human hepatocyte supply draws from cryopreserved biobank networks, polydimethylsiloxane and cyclic olefin polymer substrates, and integrated electrochemical sensor arrays. Single-source vulnerability concentrates viable hepatocyte recovery among three US tissue recovery organizations. Distribution runs through direct pharmaceutical procurement channels and contract research organization captive facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in liver-on-chip markets hinge on interoperability standards emerging from Japan METI-funded consortia, which will determine whether device vendors capture value through hardware margins or integrated analytical services.
For Market Incumbents: Consolidate cell sourcing networks through exclusive biobank partnerships to secure hepatocyte supply against emerging entrants. Deepen in-house production of thermoplastic device substrates to defend margin position against commodity fabrication competitors. Prioritize ISO 10993 certification assets that extend development cycle advantages over unqualified challengers. For New Entrants and Emerging Players: Differentiate on NASH progression modeling capabilities where stellate cell-inclusive platforms remain technically immature and validation frameworks are unsettled. Target Japanese pharmaceutical partnerships for early PMDA qualification precedents. Pursue academic co-development agreements that provide cell sourcing access without direct biobank infrastructure investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed platform vendors that have completed initial pharmaceutical validation studies but require capital for multi-site reproducibility certification. Long-term viability favors companies positioned for regulatory-grade data acceptance across FDA, EMA, and PMDA jurisdictions. Watch for EMA marketing authorization dossiers incorporating microphysiological system data as inflection signal for platform economics normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Pathway | FDA Modernization Act 2.0 mandates IND submission alternatives that validate non-animal hepatic metabolism studies. |
| Cell Sourcing Network Acquisition | Exclusive hepatocyte biobank partnerships secure supply against batch-to-batch inconsistency and price volatility. |
| Platform Integration Partnership | Strategic alliances with top-20 pharmaceutical sponsors displace pure hardware procurement with embedded analytical services. |
| Geographic Expansion | Japanese pharmaceutical collaborations leverage METI standardization funding for early PMDA qualification precedents. |
| Technology Licensing | 3D bioprinting convergence agreements enable spatially patterned co-culture architectures unavailable in molded devices. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, toxicology laboratory directors, and hepatocyte biobank procurement managers and refined through secondary validation against FDA Modernization Act legislative records, EMA reflection papers on microphysiological systems, ISO 10993 biocompatibility standards, and NIH funding disclosure databases. Bottom-up platform deployment estimates and top-down pharmaceutical R&D spending allocations were triangulated to constrain forecast variance.
Variance decomposition across product architecture, application focus, end-user sophistication, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Hepatocyte sourcing capacity expansion timelines and thermoplastic substrate adoption curves in pharmaceutical toxicology workflows provided industry-specific forecast anchors throughout the projection horizon.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EMA regulatory pull for microphysiological systems; material deviation in qualification timeline acceleration or hepatocyte supply disruption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hearing Loop Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Global Prosthetics Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Operating Room Integration Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Catheter Coatings Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Biological Microscope Market
Medical Devices
Infertility Devices Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Cervical Dilators Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market