
 United States Diabetes Devices Market | 2026-2036
United States Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Diabetes Devices Market Analytics
Hospital procurement channels for diabetes devices is tilting toward direct manufacturer contracts and value-based purchasing agreements. Abbott Laboratories leverages its vertically integrated sensor manufacturing to secure long-term supply agreements with major health systems. Dexcom sustains premium positioning through proprietary factory calibration technology that reduces patient burden. Medtronic anchors its competitive stance via deep endocrinology specialist relationships and installed-base upgrade cycles.
United States diabetes devices encompass instruments for glucose measurement, insulin administration, and metabolic data management, typically operating via electrochemical enzymatic sensing with measurement ranges of 40 to 400 mg/dL and wireless transmission protocols enabling real-time remote monitoring. Their primary purpose centers on enabling precise glycemic control to prevent microvascular and macrovascular complications in diabetic populations. Continuous glucose monitors capture disproportionate margin pools as sensor-software recurring revenue models displace one-time meter sales. Automated insulin delivery represents the fastest-expanding technology segment, integrating algorithm-driven pump modulation with predictive suspend capabilities. Blood glucose meters occupy a mature, price-compressed position concentrated in Medicare-reimbursed populations and cash-pay retail channels.
FDA premarket review under the De Novo and 510(k) pathways shapes device classification, clinical evidence requirements, and interoperability standards for connected diabetes systems. The Centers for Medicare and Medicaid Services reimbursement determinations directly dictate patient access thresholds and manufacturer pricing negotiations for therapeutic continuous glucose monitors. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-enabled insulin dosing algorithms and state-level Medicaid expansion variations that alter addressable patient populations.
Market Dynamics
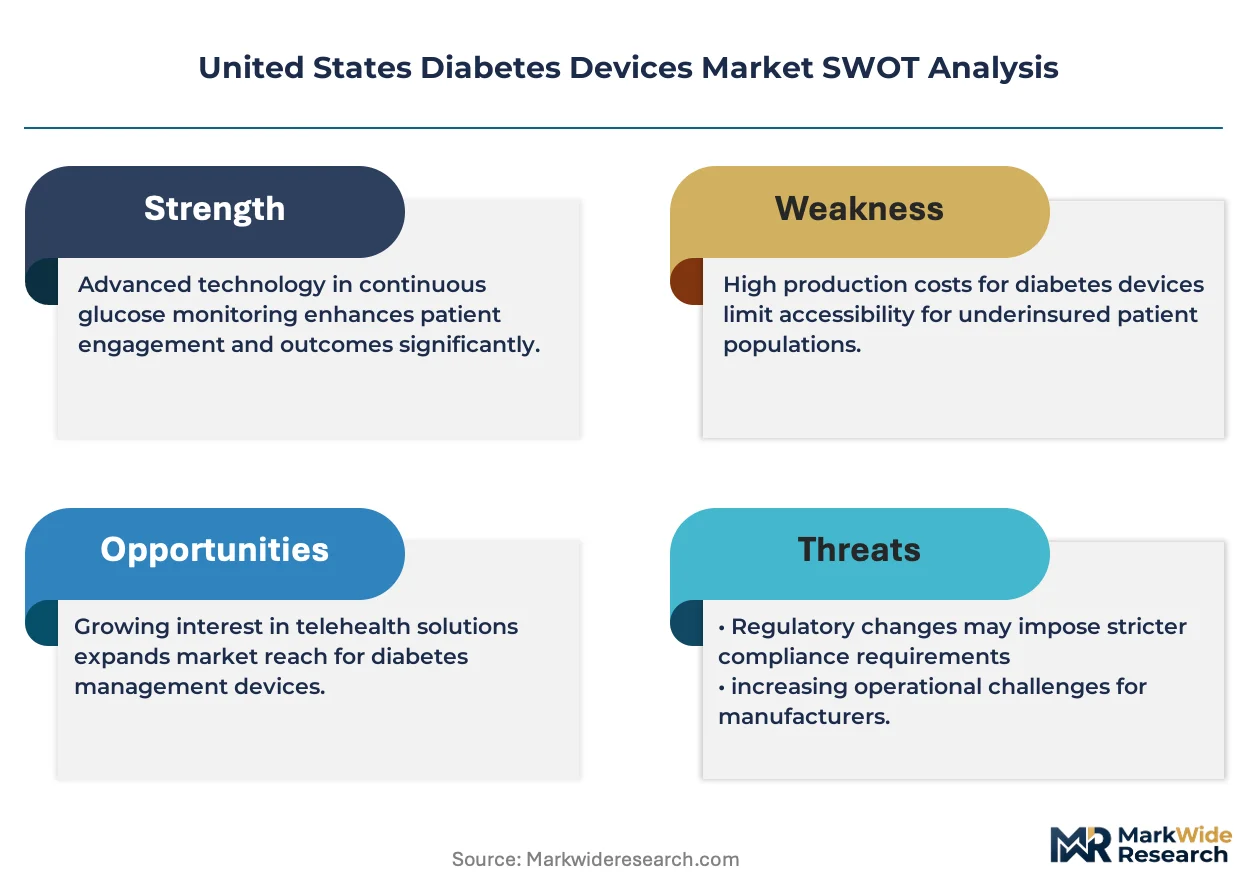
FDA's De Novo pathway for interoperable automated insulin delivery systems is compressing product development timelines while CMS reimbursement determinations for therapeutic continuous glucose monitors dictate patient access thresholds across state Medicaid programs.
Growth Catalysts
- CMS Therapeutic CGM Coverage Expansion:Medicare reimbursement for continuous glucose monitors in non-insulin-using Type 2 populations removes prior authorization barriers. This extends addressable patient pools into prediabetic monitoring segments.
- Algorithm-Enabled Closed Loop Systems:Predictive suspend and hybrid closed-loop insulin delivery technologies reduce hypoglycemic events. Endocrinology practices in Texas and California are deploying these systems at scale within integrated delivery networks.
- Home Care Migration:Hospital-at-home programs and remote patient monitoring mandates accelerate self-managed glucose tracking. Patients in Medicare Advantage plans demonstrate higher CGM adherence rates than fee-for-service counterparts.
Market Restraints
- Sensor Manufacturing Concentration:Electrochemical enzymatic sensor production concentrates among three domestic contract manufacturers. Supply disruptions at any single facility cascade across multiple OEM brands.
- Medicaid State Variation:State-level coverage determinations for therapeutic CGMs create patchwork access. Patients in non-expansion states face higher out-of-pocket burdens than those in expansion states.
- Legacy Meter Price Compression:Blood glucose meters face reimbursement rate reductions under Medicare competitive bidding. Retail pharmacy chains are exiting low-margin private-label meter distribution.
Strategic Opportunities
- AI-Enabled Insulin Dosing Algorithms:FDA draft guidance on machine learning-based dosing systems creates regulatory clarity. Developers can pursue pre-submission pathways for adaptive algorithms that learn patient-specific glycemic patterns.
- Underserved Rural Markets:Federally Qualified Health Centers in Appalachian and Southwestern regions show CGM penetration rates below one-third of urban benchmarks. Telehealth-integrated device distribution models address access gaps.
- Interoperable Device Ecosystems:The iCGM designation enables sensor-pump communication across manufacturer boundaries. Patients gain flexibility to mix Dexcom sensors with Tandem or Insulet pump platforms.
Industry Challenges
- Clinical Evidence Generation Burden:FDA premarket submissions for automated insulin delivery require randomized controlled trials measuring time-in-range outcomes. Smaller developers face capital constraints for pivotal studies.
- Legacy Health Record Integration:CGM data streams lack standardized interoperability with Epic and Cerner EHR systems. Health information technology departments must build custom interfaces for endocrinology workflows.
- Specialist Workforce Constraints:Certified diabetes care and education specialists are concentrated in coastal metropolitan areas. Rural patients experience median wait times exceeding ninety days for device training appointments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Diabetes Devices Market |
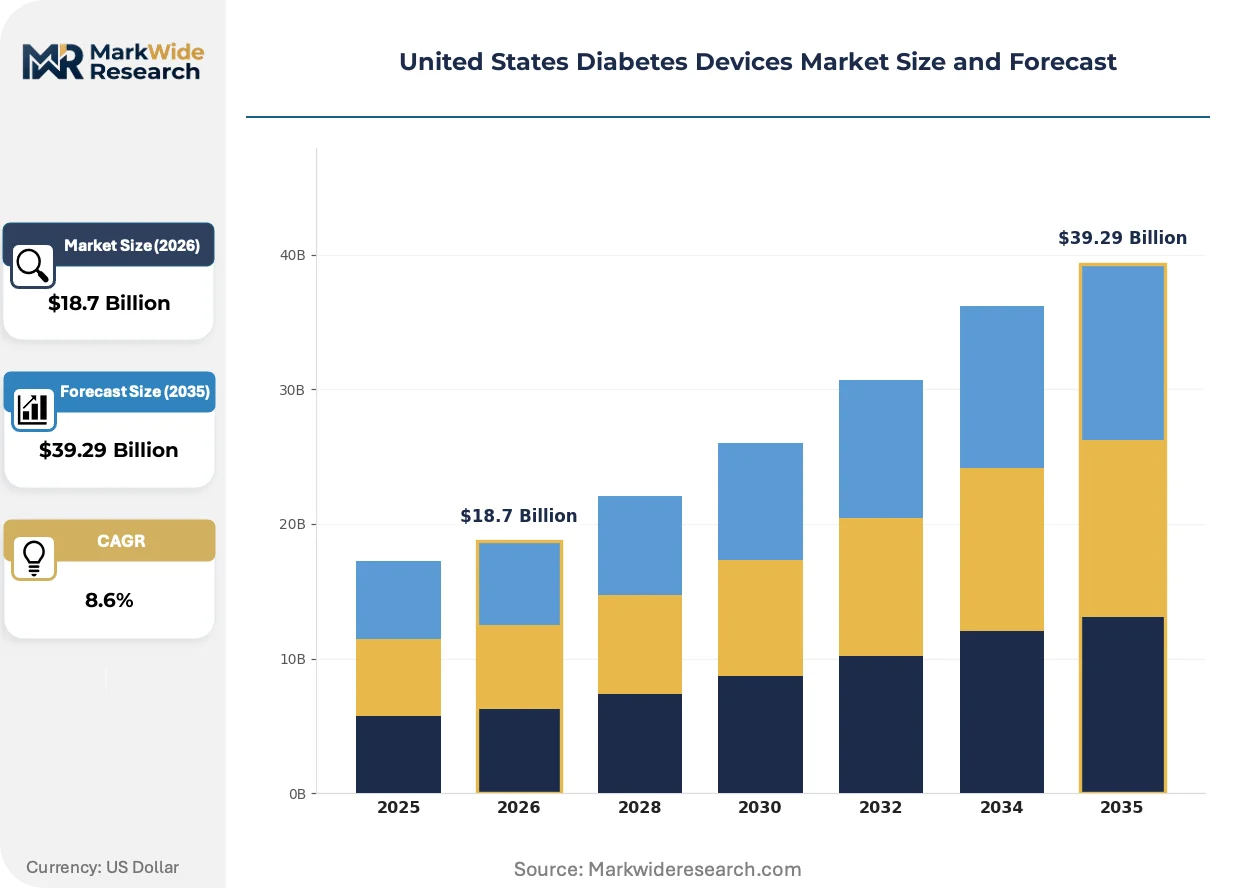
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Insulin Pumps, Blood Glucose Meters, Smart Pens End User: Hospitals, Clinics, Home Care, Diabetes Management Centers Technology: Wearable Devices, Mobile Applications, Cloud Solutions, Automated Insulin Delivery Application: Personal Monitoring, Chronic Disease Management, Telehealth, Preventative Care |
| Companies Covered | Abbott Laboratories, Dexcom, Medtronic, F. Hoffmann-La Roche, LifeScan, Ascensia Diabetes Care Holdings, Insulet Corporation, Tandem Diabetes Care, Becton Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Diabetes Devices Market Evolving Landscape
Cloud-native glucose data platforms are virtualizing traditional device-centric business models, while regulatory frameworks for artificial intelligence in dosing algorithms and shifting procurement channels through integrated delivery networks reshape competitive terrain.
Continuous glucose monitoring software is virtualizing the value capture mechanism in diabetes care. Health systems in California are adopting enterprise licenses for remote monitoring dashboards that aggregate patient glycemic data across ambulatory networks. This shift compresses standalone meter manufacturer margins while expanding recurring SaaS revenue pools for sensor-integrated platforms.
FDA's draft guidance on predetermined change control plans for AI-enabled devices establishes a pathway for adaptive insulin dosing algorithms. Manufacturers can now deploy algorithm updates without supplemental 510(k) submissions if changes remain within validated boundaries. Automated insulin delivery developers are restructuring quality systems to support continuous learning model deployments.
Hospital procurement is consolidating diabetes device purchasing through value-based arrangements with integrated delivery networks. Texas-based health systems are negotiating multi-year sensor supply contracts tied to population glycemic outcome metrics. This displaces traditional distributor-mediated transactions and concentrates volume with manufacturers demonstrating real-world evidence portfolios.
United States Diabetes Devices Market Segmentation
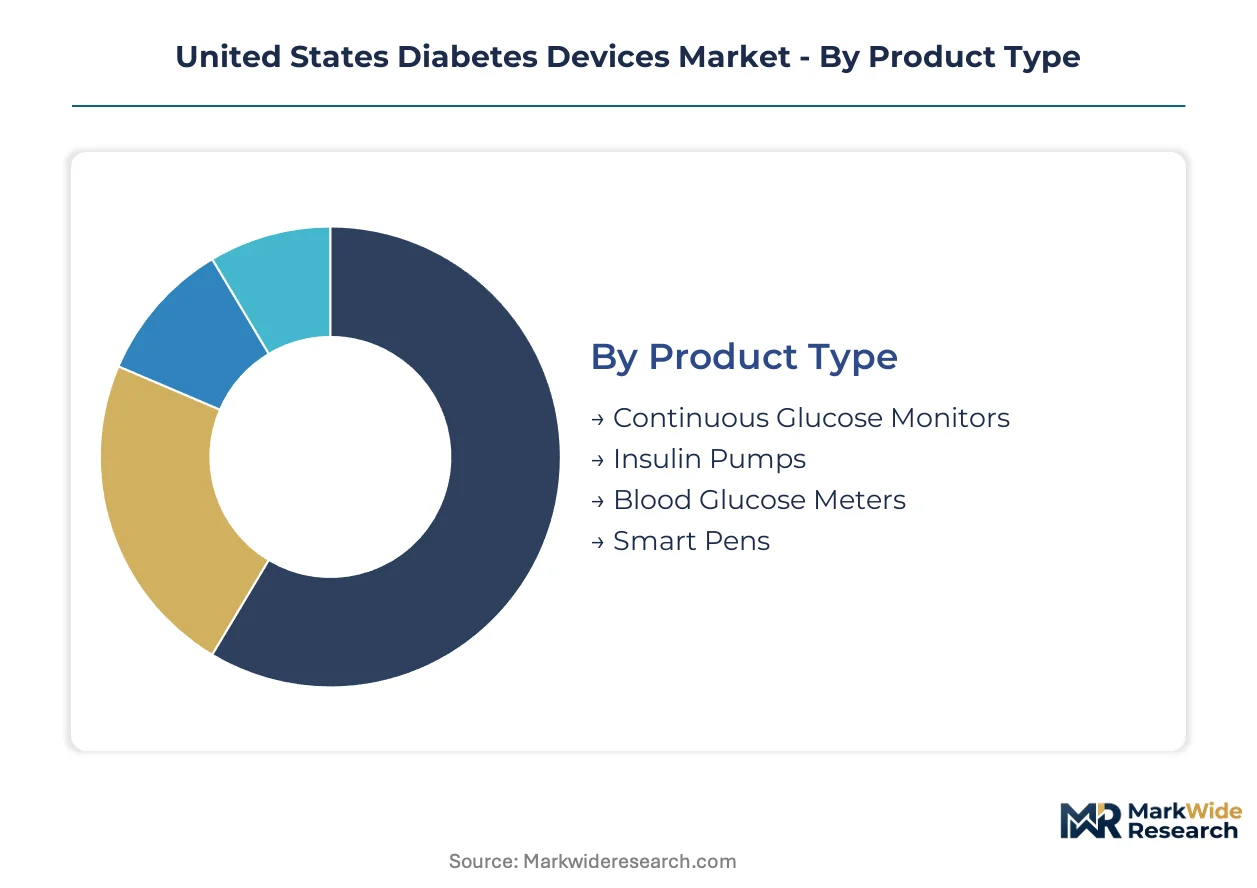
Diabetes device purchasing patterns diverge sharply across care settings and technology platforms. Product specifications, reimbursement pathways, and patient self-management capabilities create distinct demand profiles that manufacturers must address through targeted portfolio positioning.
Product Type:
Cost tier stratification separates premium sensor-based systems from commoditized legacy devices, with reimbursement intensity determining commercial viability.
- Continuous Glucose Monitors:Electrochemical enzymatic sensors with factory calibration capture glucose readings at 5-minute intervals through subcutaneous filaments. Demand concentrates in Medicare Advantage plans and integrated California health networks where remote monitoring incentives align with sensor-software recurring revenue models.
- Insulin Pumps:Electromechanical infusion systems with basal-bolus programming and predictive suspend capabilities. Texas-based endocrinology practices within integrated delivery networks are deploying these devices at scale for Type 1 populations.
- Blood Glucose Meters:Enzymatic test strip systems for capillary blood sampling face Medicare competitive bidding compression. Retail pharmacy chains are exiting low-margin distribution.
- Smart Pens:Bluetooth-enabled injection devices with dose logging and reminder functionality serve insulin-requiring Type 2 patients seeking adherence support without pump complexity.
Continuous Glucose Monitors hold installed capacity. Smart Pens are rotating up the share rankings.
End User:
Application context determines device complexity requirements, training burden, and data integration needs across acute and ambulatory environments.
- Home Care:Self-managed glucose tracking with smartphone-connected devices and cloud data transmission. Medicare Advantage beneficiaries demonstrate higher adherence rates than fee-for-service counterparts in remote patient monitoring programs.
- Hospitals:Inpatient glycemic management with point-of-care meters and networked insulin dosing protocols. Value-based purchasing agreements are consolidating procurement through direct manufacturer contracts.
- Clinics:Outpatient endocrinology practices with CGM interpretation and pump titration services face specialist workforce constraints in rural markets.
- Diabetes Management Centers:Dedicated education and device training facilities concentrated in coastal metropolitan areas with ninety-day appointment backlogs for rural referrals.
Home Care commands volume leadership. Diabetes Management Centers are rotating up the share rankings.
Technology:
Customer type differentiation separates consumer-directed mobile solutions from clinical-grade therapeutic systems requiring prescription pathways.
- Automated Insulin Delivery:Algorithm-driven pump modulation with predictive suspend and hybrid closed-loop capabilities reduces hypoglycemic events. FDA De Novo pathway clearances are compressing development timelines for interoperable systems.
- Wearable Devices:Skin-adhesive sensors and patch pumps with wireless transmission protocols enable continuous data streams without patient intervention.
- Mobile Applications:Smartphone platforms for glucose logging, carbohydrate counting, and insulin dose calculation lack standardized EHR interoperability with Epic and Cerner systems.
- Cloud Solutions:Enterprise remote monitoring dashboards aggregate patient glycemic data across ambulatory networks in California health systems.
Wearable Devices hold installed capacity. Automated Insulin Delivery is climbing the fastest.
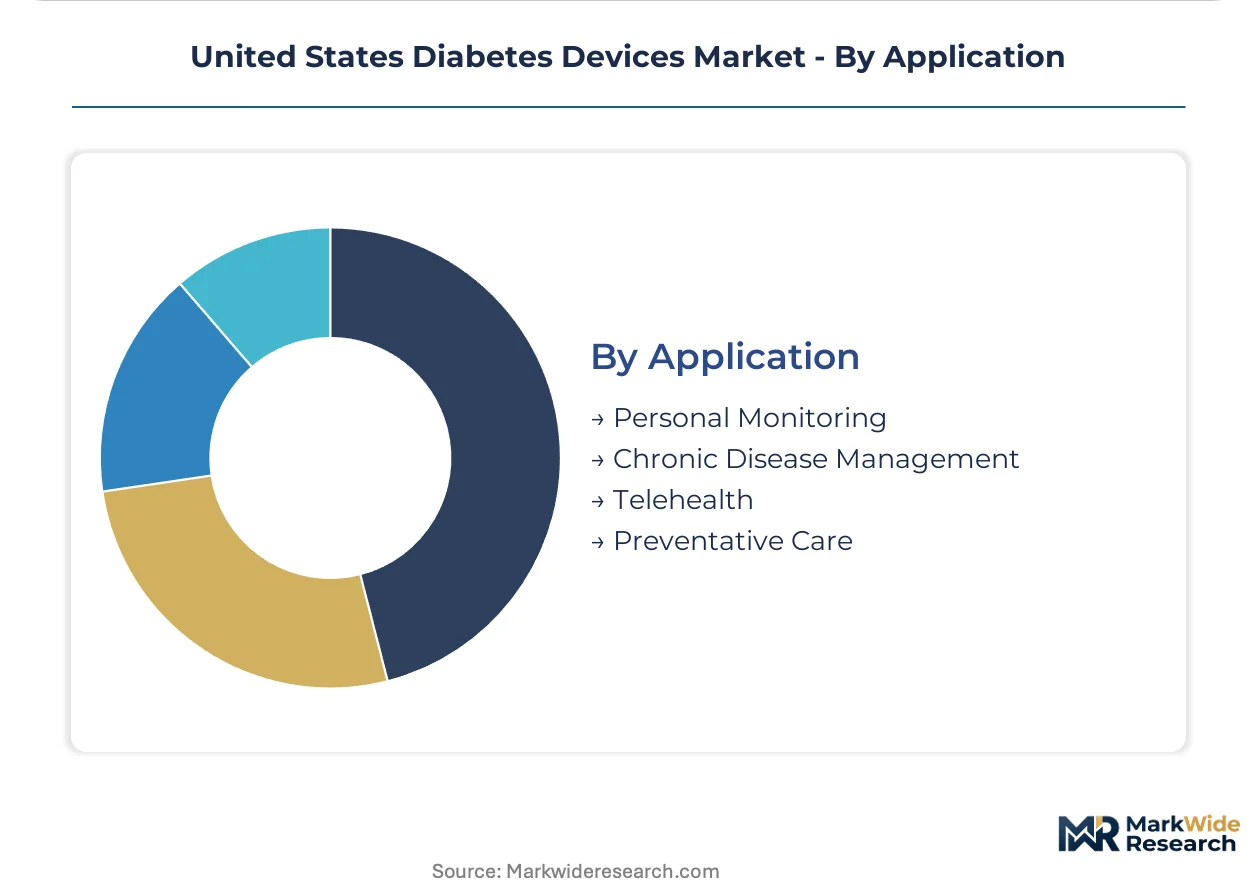
Application:
Volume concentration varies across preventive, acute, and chronic care use cases with distinct outcome measurement requirements.
- Chronic Disease Management:Long-term glycemic optimization to prevent microvascular and macrovascular complications through time-in-range targeting. Texas integrated delivery networks negotiate multi-year sensor contracts tied to population outcome metrics.
- Telehealth:Remote patient monitoring with real-time data transmission to clinical teams. Federally Qualified Health Centers in Appalachian regions show CGM penetration below one-third of urban benchmarks.
- Personal Monitoring:Individual glucose awareness for prediabetic and non-insulin-using Type 2 populations following CMS coverage expansion.
- Preventative Care:Early glycemic surveillance in high-risk populations with lifestyle intervention protocols.
Chronic Disease Management holds installed capacity. Telehealth is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulatory frameworks and CMS reimbursement policies anchor demand concentration across United States sub-regions. State-level Medicaid expansion status and integrated delivery network density create divergent market access profiles.
California
Kaiser Permanente and Sutter Health networks drive volume procurement of continuous glucose monitors through enterprise remote monitoring contracts. Medi-Cal expansion under the Affordable Care Act extends therapeutic CGM access to non-insulin-using Type 2 populations. The San Francisco Bay Area hosts concentrated endocrinology specialist practices deploying hybrid closed-loop systems at scale.
Texas
Memorial Hermann and Baylor Scott & White integrated delivery networks negotiate multi-year sensor supply agreements tied to population glycemic outcomes. State Medicaid coverage for therapeutic CGMs varies by managed care organization contract. Houston and Dallas medical centers anchor automated insulin delivery deployment for Type 1 populations.
Northeast Corridor
Medicare Advantage penetration rates exceed national averages in Massachusetts and New York, accelerating home care migration for glucose monitoring. FDA premarket review timelines for interoperable devices compress product launches through Boston-area regulatory consulting clusters. Philadelphia and New York City hospital systems consolidate procurement through value-based purchasing arrangements.
Midwest
Cleveland Clinic and Mayo Clinic anchor clinical evidence generation for automated insulin delivery systems through prospective registry studies. State Medicaid programs in Ohio and Minnesota maintain prior authorization requirements for therapeutic CGMs that delay patient access. Chicago-based health systems face specialist workforce constraints with median diabetes educator appointment wait times exceeding sixty days.
Southeast
Non-expansion states including Florida and Georgia impose higher out-of-pocket burdens for therapeutic CGM access compared to expansion states. Federally Qualified Health Centers in Appalachian regions show CGM penetration rates below one-third of urban benchmarks. Atlanta and Miami metropolitan areas concentrate telehealth-integrated device distribution models addressing rural access gaps.
United States Diabetes Devices Market Competitive Landscape
Vertically integrated sensor manufacturers and algorithm-focused pump specialists split the market along technology-platform lines. Abbott Laboratories and Dexcom occupy the sensor tier through proprietary manufacturing and calibration capabilities. Medtronic and Tandem Diabetes Care anchor the automated insulin delivery segment via endocrinology specialist relationships. Consolidation pressure intensifies as health systems demand single-source contracts spanning sensors, pumps, and data platforms.
Within the sensor-manufacturing tier, Abbott Laboratories exemplifies backward integration into electrochemical enzymatic production, while Dexcom occupies a position defined by factory calibration technology. Among pump-system specialists, Tandem Diabetes Care and Insulet Corporation represent divergent form-factor approaches to automated insulin delivery. Medtronic anchors the installed-base upgrade cycle segment through deep clinical channel relationships. These three strategic archetypes—captive sensor production, calibration-differentiated platforms, and algorithm-integrated delivery systems—define competitive positioning.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| Medtronic |
| F. Hoffmann-La Roche |
| LifeScan |
| Ascensia Diabetes Care Holdings |
| Insulet Corporation |
| Tandem Diabetes Care |
| Becton Dickinson and Company |
| Others |
Value Network & Pricing Analysis
FDA premarket review bottlenecks for interoperable automated insulin delivery systems compress development timelines while simultaneously concentrating pricing power among established sensor manufacturers. This regulatory chokepoint widens the spread between premium factory-calibrated continuous glucose monitors and commoditized blood glucose meters, while electrochemical enzymatic sensor production concentration among three domestic contract manufacturers shapes procurement risk profiles across OEM brands.
Pricing Analysis
The customization-premium spread separates configured-to-order automated insulin delivery systems from standard continuous glucose monitor subscriptions. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by factory calibration certification and volume scale procurement through integrated delivery networks. Cost compression in legacy blood glucose meters intensifies because Medicare competitive bidding reduces reimbursement rates, while hospital systems demonstrate lowest price sensitivity due to value-based purchasing agreements tied to population glycemic outcomes.
Supply Chain Analysis
Extended payment terms from Texas and California integrated delivery networks to sensor manufacturers compress working capital cycles for upstream component suppliers. Electrochemical enzymatic sensor production draws from domestic contract manufacturing facilities, with platinum-based electrode materials and medical-grade adhesives as critical inputs. Single-source vulnerability concentrates in subcutaneous filament winding equipment, where distribution runs through direct manufacturer contracts with major health systems rather than traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States diabetes devices market functions as a defensive-moat story anchored in regulatory entrenchment. FDA De Novo pathway clearances and CMS reimbursement determinations create structural barriers that protect installed-base positions while complicating challenger entry.
For Market Incumbents: Insulate sensor manufacturing positions through backward integration into electrochemical enzymatic production and captive supply of medical-grade adhesive components. Algorithm-enabled closed-loop upgrade cycles defend against emerging pump-specialist entrants, while direct contracting with Memorial Hermann and Kaiser Permanente networks secures volume commitments against price erosion.
For New Entrants and Emerging Players: Build out telehealth-integrated distribution models targeting Federally Qualified Health Centers in Appalachian and Southwestern regions where CGM penetration rates sit below one-third of urban benchmarks. Rural diabetes management centers present the most penetrable segment, with software companion development for remote patient monitoring dashboards as the primary go-to-market angle.
For Investors and Strategic Acquirers: FDA draft guidance on predetermined change control plans for AI-enabled devices reshapes the acquisition landscape by reducing regulatory uncertainty for adaptive insulin dosing algorithm developers. Long-term viability centers on platforms demonstrating real-world evidence portfolios across Medicare Advantage populations, with state Medicaid expansion variations as the critical signal to watch for addressable market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Premarket clearance for interoperable automated insulin delivery systems compresses development timelines under FDA review protocols. |
| Hospital System Partnership | Direct contracting with Texas and California integrated delivery networks displaces distributor-mediated transactions. |
| Software Companion Development | Cloud-native glucose data platforms aggregate patient glycemic data across ambulatory networks in California health systems. |
| Reimbursement Strategy | CMS therapeutic CGM coverage expansion for non-insulin-using Type 2 populations removes prior authorization barriers. |
| CE Marking Pathway | European regulatory clearance enables sensor-pump communication across manufacturer boundaries under iCGM designation. |
Research Methodology
Cross-validation between hospital procurement database analysis and CMS Medicare reimbursement filings anchors the qualitative findings. Primary interviews with endocrinology practice administrators, biomedical engineers at integrated delivery networks, GPO contracts managers, and certified diabetes care and education specialists combined with secondary validation against FDA 510(k) and De Novo submissions, hospital supply chain records, and state Medicaid coverage determinations. Bottom-up patient population modeling and top-down manufacturer revenue triangulation establish volume and value estimates.
Calibration against historical CGM adoption curves and insulin pump upgrade cycles refines the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user setting, technology platform, and application use case, with regional Medicaid expansion status as an additional industry-specific dimension. CAGRs derive from fitted adoption curves applied to addressable patient populations, incorporating algorithm-enabled closed-loop penetration rates and Medicare Advantage plan growth as forecast inputs.
Stress conditions across FDA review timeline variations, state Medicaid coverage reversals, and sensor manufacturing supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement stability and regulatory pathway clarity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
North America Wheelchair Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Gamma Knife Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Penile Implants Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Skin Revitalizing Handheld Devices Market