
 Brazil Ultrasound Devices Market | 2026-2036
Brazil Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Ultrasound Devices Market Outlook
Maternal-fetal medicine departments across Brazilian public hospitals are restructuring their capital equipment priorities, shifting volume toward portable and point-of-care ultrasound platforms. GE Healthcare leverages its installed base of radiology suites to sustain service contract revenue across the Southeast region. Mindray Medical International competes aggressively on digital console pricing, while Philips anchors premium positioning through its software-driven cardiac imaging portfolio. Samsung Electronics differentiates via compact system design tailored to ambulatory clinic footprints.
Brazil ultrasound devices encompass electronic systems that generate acoustic waves typically between two and eighteen megahertz, converting returning echoes into tomographic images for non-invasive diagnostic visualization of soft tissue structures and hemodynamic function. Their primary commercial purpose spans obstetric monitoring, cardiac assessment, abdominal screening, and musculoskeletal intervention across inpatient and outpatient settings. Portable and 3D/4D product types command expanding margin pools as outpatient clinics seek workflow flexibility without image fidelity trade-offs. Diagnostic applications dominate hospital purchasing, though therapeutic segments gain traction in physiatry and sports medicine practices.
ANVISA governs medical device registration and post-market surveillance, while the Ministry of Health's RENISUS registry tracks strategic equipment distribution across the unified health system. These frameworks shape demand by determining which technology tiers qualify for public procurement tenders and federal reimbursement codes. Stakeholders must monitor pending regulatory harmonization with Mercosur technical standards, as alignment would reshape import documentation requirements for multinational suppliers. The pace of digital platform adoption hinges on how quickly ANVISA streamlines software-as-medical-device classifications.
Market Dynamics
Portable ultrasound platform adoption is compressing capital cycles across Brazilian maternal-fetal departments, forcing incumbents to defend service revenue through software lock-in rather than hardware refresh.
Growth Catalysts
- ANVISA pathway compression:Digital platform registration timelines now align with hardware-only devices, accelerating software-as-medical-device market entry for console vendors.
- São Paulo imaging center density:Metropolitan corridor concentration exceeds national benchmarks by substantial margins, creating clustered demand for compact system footprints.
- Point-of-care workflow integration:Emergency departments and ambulatory clinics are prioritizing bedside diagnostic capability over centralized radiology queue dependency.
Market Restraints
- Import documentation friction:Pending Mercosur technical standard harmonization uncertainty delays multinational supplier customs clearance for replacement parts.
- Semiconductor input volatility:Transducer array controller chip sourcing concentrates in East Asian foundries, exposing Brazilian assemblers to extended lead time variance.
- Public procurement budget rigidity:Ministry of Health RENISUS registry qualification thresholds filter out mid-tier digital platforms from unified health system tenders.
Strategic Opportunities
- Northeast regional underpenetration:Bahia and Pernambuco states exhibit imaging center density below one-third of Southeast levels, creating whitespace for portable system distributors.
- Therapeutic ultrasound expansion:Physiatry and sports medicine practices are adopting focused acoustic energy devices for soft tissue intervention outside traditional diagnostic settings.
- Software subscription unbundling:Vendors can separate image analysis algorithms from hardware sales, creating recurring revenue streams independent of capital equipment cycles.
Industry Challenges
- Sonographer training pipeline gaps:Federal university programs graduate insufficient point-of-care ultrasound operators to match ambulatory clinic deployment targets.
- Legacy PACS integration complexity:Public hospital archive systems run incompatible DICOM versions, forcing middleware development costs onto equipment vendors.
- Post-market surveillance compliance:ANVISA adverse event reporting requirements demand dedicated regulatory affairs staffing that mid-size distributors struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Ultrasound Devices Market |
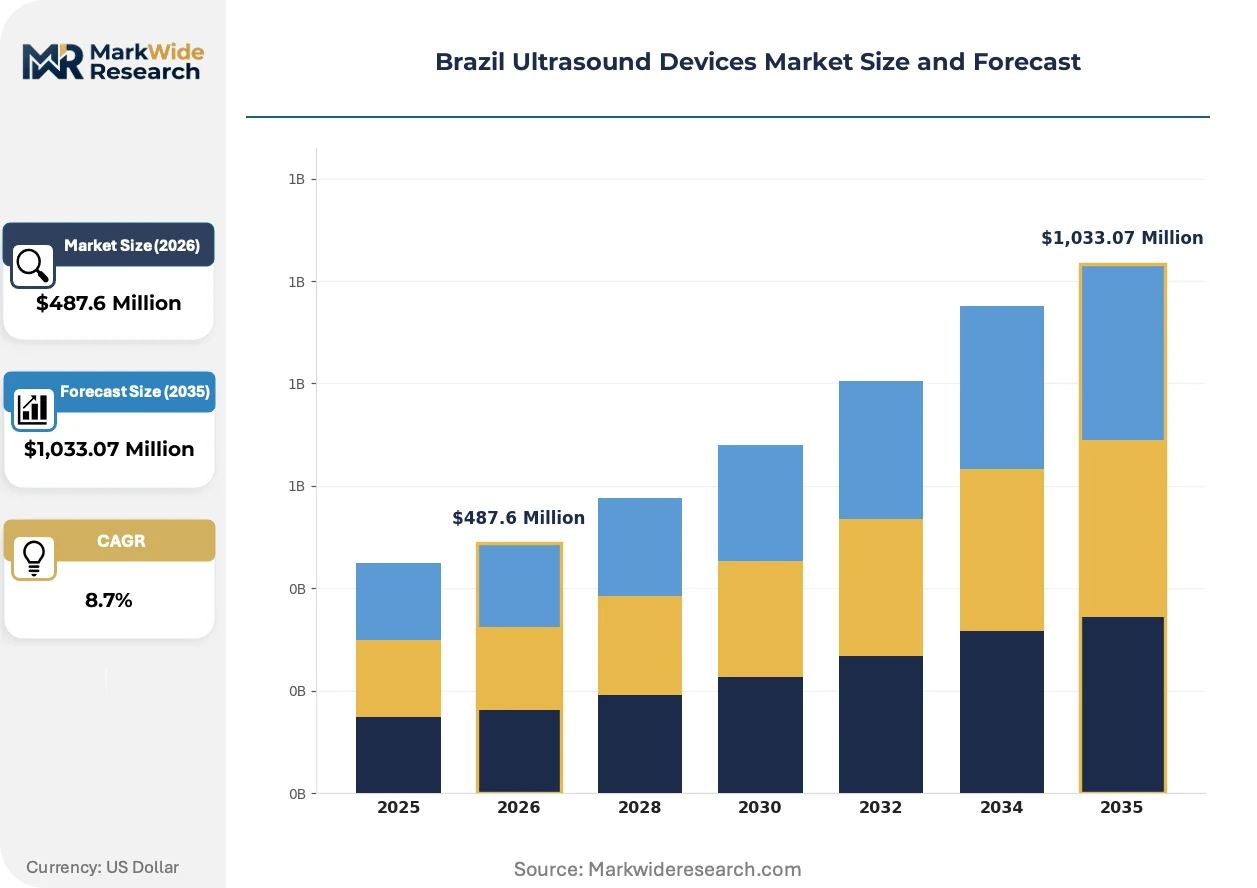
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic, Therapeutic, Portable, 3D/4D End User: Hospitals, Clinics, Imaging Centers, Research Institutes Technology: Analog, Digital, Hybrid, Software-Driven Application: Abdominal, Cardiovascular, Obstetrics, Musculoskeletal |
| Companies Covered | Canon Medical Systems Corporation, Fujifilm Holdings Corporation, GE Healthcare, Hologic, Samsung Electronics, Siemens Healthineers, Mindray Medical International, Esaote, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Ultrasound Devices Market Strategic Shifts
Digital platform architecture is fragmenting traditional hardware-centric business models across Brazilian diagnostic imaging, compressing margins on console sales while expanding addressable spend on algorithmic analysis tools.
Cart-based system design is modularizing around detachable tablet interfaces and swappable transducer connectors. Municipal hospital networks in Minas Gerais and Rio de Janeiro are piloting shared-device pools where a single console chassis rotates across departments with specialty-specific probe kits. This architecture is modularizing vendor revenue recognition, forcing recognition of hardware and software components across divergent depreciation schedules.
ANVISA's updated software-as-medical-device classification guidance eliminates separate registration tracks for AI-powered image analysis tools bundled with ultrasound hardware. Diagnostic imaging centers in São Paulo's metropolitan corridor must now validate algorithm performance through local clinical studies to maintain registration compliance. Cardiac imaging suites face the steepest adaptation burden, as automated ejection fraction calculations trigger the new oversight tier.
Leasing arrangements are displacing outright purchase for high-end systems in private imaging chains. Diagnostic operators in Curitiba and Porto Alegre now favor per-procedure fee structures that bundle maintenance, software updates, and transducer replacement. This reconfiguration concentrates credit risk with financing subsidiaries of equipment manufacturers rather than clinic balance sheets.
Brazil Ultrasound Devices Market Segmentation
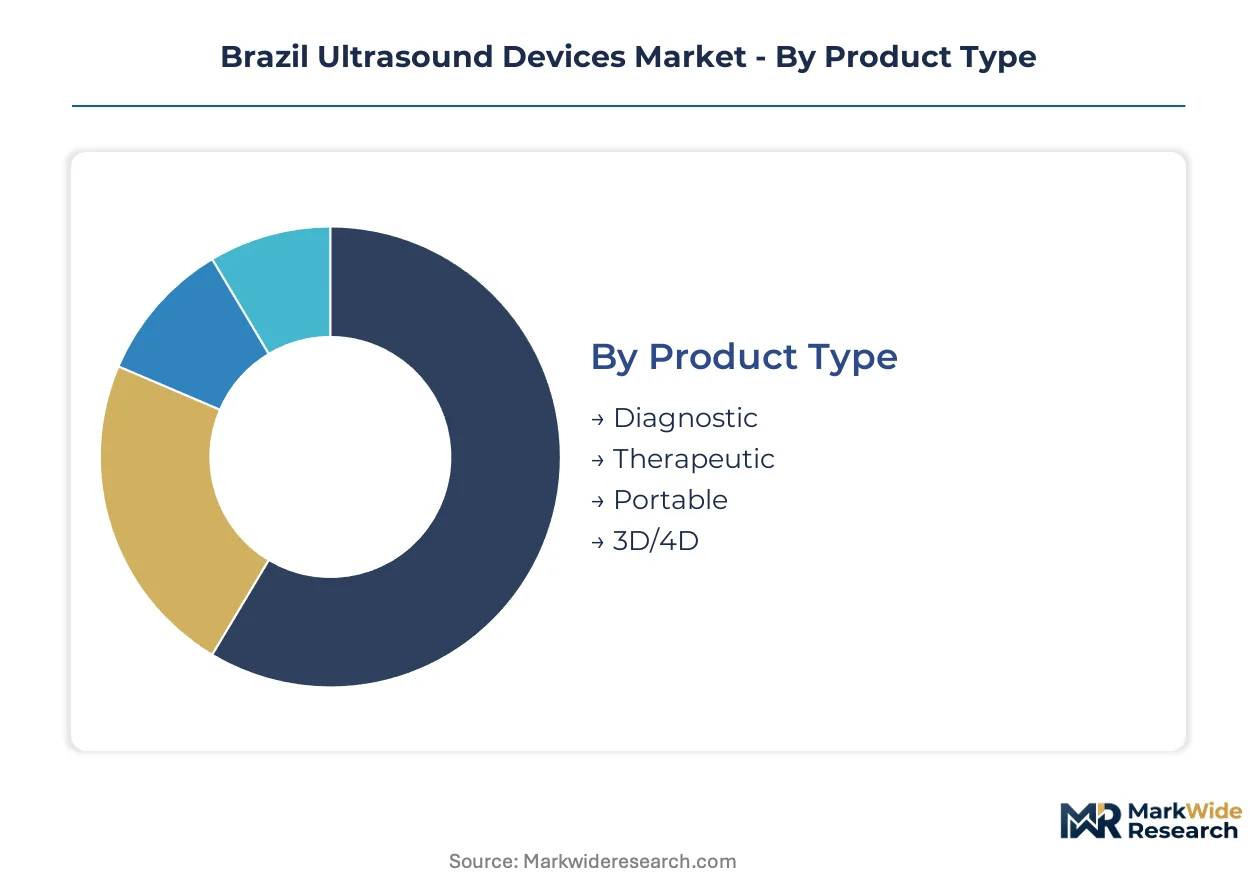
Ultrasound device segmentation in Brazil reflects divergent capital deployment strategies across public and private healthcare infrastructure. Procurement patterns vary sharply between ministry-funded hospital networks and metropolitan imaging chains.
Product Type:
Diagnostic systems demand the heaviest upfront capital outlay, with cart-based consoles requiring dedicated procedure rooms and climate-controlled storage for transducer arrays.
- Diagnostic:Cart-based platforms with specialized probe configurations dominate hospital radiology departments. São Paulo's metropolitan corridor concentrates procurement for high-channel-count systems used in tertiary cardiac and abdominal imaging.
- Therapeutic:Focused acoustic energy devices deliver thermal and mechanical tissue effects for physiatry intervention. Sports medicine clinics in Rio de Janeiro and Belo Horizonte are expanding adoption for soft tissue rehabilitation outside traditional diagnostic settings.
- Portable:Battery-operated systems with tablet interfaces enable point-of-care deployment. Municipal networks in Minas Gerais pilot shared-device pools rotating across maternal-fetal departments.
- 3D/4D:Real-time volumetric rendering systems command premium positioning in private obstetric practices. ANVISA registration complexity for software-as-medical-device algorithms constrains mid-tier vendor entry.
Most installed capacity flows through Diagnostic systems. Expansion is steepest in Portable platforms.
End User:
Customer type determines procurement channel access, with public tenders favoring established vendors capable of meeting RENISUS registry documentation requirements.
- Hospitals:Tertiary facilities concentrate demand for multi-modality suites integrating ultrasound with PACS infrastructure. Legacy DICOM version incompatibility forces middleware investment onto equipment suppliers.
- Clinics:Ambulatory settings prioritize compact footprints and rapid boot sequences. Point-of-care workflow integration is displacing centralized radiology dependency in emergency departments.
- Imaging Centers:Private diagnostic chains in Curitiba and Porto Alegre favor per-procedure leasing structures bundling maintenance and software updates.
- Research Institutes:Federal university hospitals drive adoption of experimental transducer technologies for clinical validation studies.
Procurement volume concentrates in Hospitals. Imaging Centers are gaining share fastest through private capital expansion.
Technology:
Architecture choices determine software update cadence and regulatory pathway complexity under ANVISA's evolving digital platform classifications.
- Analog:Legacy beam-forming electronics persist in budget-constrained municipal facilities. Replacement parts sourcing concentrates vulnerability in East Asian semiconductor supply chains.
- Digital:FPGA-based signal processing enables real-time image optimization. São Paulo imaging centers drive demand for AI-powered analysis tools now subject to consolidated registration timelines.
- Hybrid:Mixed-signal architectures balance cost and performance for mid-tier hospital segments. Transducer array controller chip volatility extends lead times for Brazilian assemblers.
- Software-Driven:Cloud-connected platforms separate hardware from algorithmic functionality. ANVISA's updated guidance compresses market entry for console vendors unbundling image analysis subscriptions.
Deployment tilts toward Digital systems. Software-Driven platforms are climbing the fastest as vendors pursue recurring revenue models.
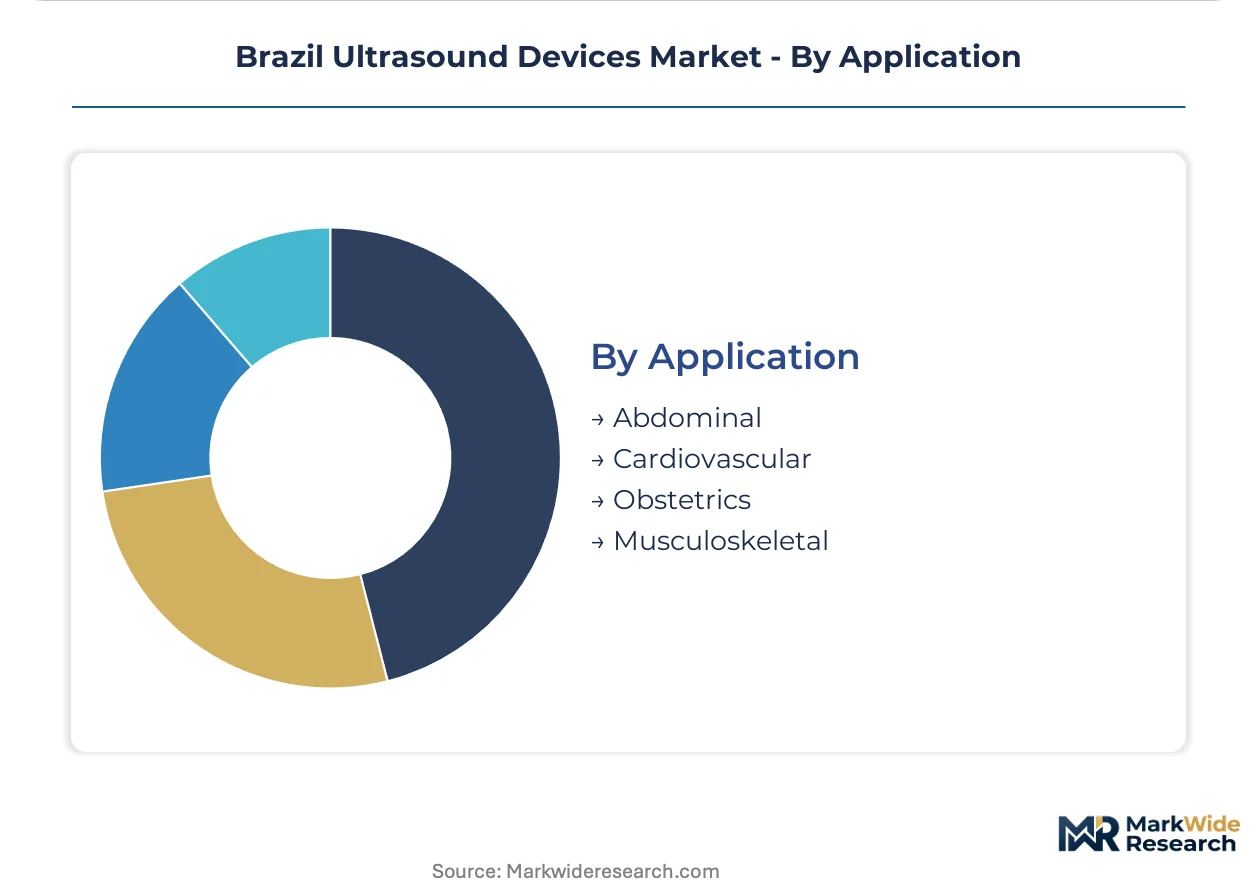
Application:
Clinical use case shapes transducer specification requirements and determines reimbursement pathway eligibility under Ministry of Health protocols.
- Abdominal:Curved-array probes for hepatobiliary and renal visualization dominate generalist settings. Public hospital procurement prioritizes versatile systems serving multiple organ targets.
- Cardiovascular:Phased-array transducers with spectral Doppler capability command specialized operator training. Automated ejection fraction calculations trigger ANVISA's heightened oversight tier for algorithm validation.
- Obstetrics:Maternal-fetal medicine departments restructure priorities toward portable platforms. Northeast regional underpenetration creates whitespace for compact system distributors in Bahia and Pernambuco.
- Musculoskeletal:High-frequency linear probes enable tendon and joint surface imaging. Sports medicine practices outside traditional diagnostic settings drive therapeutic segment expansion.
Procedure volume concentrates in Obstetrics. Musculoskeletal applications are expanding most quickly through physiatry clinic adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers exploit cost-of-compliance gaps between ANVISA's streamlined digital platform pathways and lengthier legacy registration tracks, concentrating assembly investments in São Paulo's industrial corridor where regulatory proximity accelerates market entry.
São Paulo
Metropolitan imaging center density exceeds national benchmarks by substantial margins, clustering demand for compact system footprints. ANVISA's headquarters proximity enables rapid regulatory consultation for software-as-medical-device classifications. Campinas and São José dos Campos anchor transducer manufacturing and digital console assembly operations serving Southeast hospital networks.
Minas Gerais
Municipal hospital networks pilot shared-device pools where single console chassis rotate across maternal-fetal departments with specialty-specific probe kits. State health secretariat procurement frameworks prioritize portable platforms qualifying for RENISUS registry documentation. Belo Horizonte concentrates diagnostic imaging chain headquarters negotiating per-procedure leasing structures.
Rio de Janeiro
Sports medicine clinics expand therapeutic ultrasound adoption for soft tissue rehabilitation outside traditional diagnostic settings. Municipal health authorities face legacy PACS integration complexity with incompatible DICOM versions forcing middleware costs onto equipment vendors. Rio de Janeiro city imaging centers drive demand for high-channel-count cardiac systems.
Rio Grande do Sul
Private diagnostic chains in Porto Alegre favor per-procedure fee structures bundling maintenance, software updates, and transducer replacement. State procurement tribunals enforce strict RENISUS registry qualification thresholds filtering mid-tier digital platforms from unified health system tenders. Caxias do Sul hosts regional distribution hubs for multinational equipment suppliers.
Bahia
Imaging center density sits below one-third of Southeast levels, creating whitespace for portable system distributors targeting maternal-fetal departments. Federal university hospitals in Salvador drive adoption of experimental transducer technologies for clinical validation studies. Northeast regional underpenetration attracts leasing subsidiaries concentrating credit risk on manufacturer balance sheets.
Brazil Ultrasound Devices Market Competitive Environment
Strategic partnerships dominate the current landscape as multinational suppliers align with regional distributors to navigate ANVISA registration complexity. The vendor base fragments across three tiers: diversified imaging conglomerates defending installed base service revenue, mid-tier digital console specialists competing on price, and compact system designers targeting ambulatory footprints. Archetypes include hardware-software integrators pursuing recurring revenue through algorithm subscriptions, scale-driven manufacturers absorbing semiconductor volatility, and niche therapeutic device specialists. Geographic expansion and technology licensing represent the dominant competitive moves.
Among diversified imaging conglomerates, GE Healthcare anchors premium positioning through software-driven cardiac imaging portfolios, while Koninklijke Philips exemplifies the hardware-software integrator archetype pursuing unbundled algorithm subscriptions. Mindray Medical International occupies a position within the mid-tier digital console segment competing aggressively on pricing. Samsung Electronics represents the compact system design specialist targeting ambulatory clinic footprints with tailored form factors.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| GE Healthcare |
| Hologic |
| Samsung Electronics |
| Siemens Healthineers |
| Mindray Medical International |
| Esaote |
| Koninklijke Philips |
| Others |
Value Chain & Pricing Dynamics
Specialized sonographer training programs concentrated in São Paulo's federal universities create labor-cost differentials that widen pricing-tier spreads between premium cardiac imaging suites and economy-tier municipal hospital contracts. ANVISA registration pathway compression for digital platforms intensifies margin pressure on hardware-only vendors while rewarding software-integrated suppliers with pricing power.
Pricing Analysis
Distributor margins on imported console systems compress final pricing by 18-25 percentage points before reaching hospital procurement committees. Three-tier pricing structure across premium, standard, and economy levels separates AI-powered cardiac suites from mid-tier abdominal systems and refurbished analog platforms. Cost compression in the economy tier is intensifying because semiconductor input volatility forces Brazilian assemblers to absorb lead time variance. Public hospital tender participants exhibit highest price sensitivity due to RENISUS registry qualification thresholds, while private imaging chains in Curitiba and Porto Alegre prioritize per-procedure bundling over capital outlay minimization.
Supply Chain Analysis
Direct-to-hospital channels handle unified health system tender demand, while specialized distributors serve ambulatory clinic segments with compact system footprints. Transducer array controller chip sourcing draws from Taiwan, South Korea, and Japan, exposing Brazilian assemblers to East Asian foundry concentration risk. FPGA-based signal processors and high-frequency linear probe ceramics constitute critical input dependencies. Single-source vulnerability in semiconductor controller supply creates procurement bottlenecks during foundry allocation cycles. Distribution runs through São Paulo industrial corridor assembly facilities to Southeast hospital networks, with regional hubs in Caxias do Sul serving South and Northeast territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil ultrasound devices constitute a late-cycle quality story as maternal-fetal medicine departments restructure priorities toward portable platforms with software-driven image fidelity. Demand is shifting toward premium specifications featuring AI-powered cardiac analysis and cloud-connected algorithm subscriptions.
For Market Incumbents: Extend service contract lock-in across GE Healthcare's installed base of radiology suites to defend recurring revenue against Mindray's aggressive digital console pricing. Anchor premium positioning through software-driven cardiac imaging portfolios that trigger ANVISA's heightened oversight tier for algorithm validation, creating regulatory moats. Deepen backward integration into transducer manufacturing within Campinas industrial parks to offset East Asian semiconductor volatility. For New Entrants and Emerging Players: Municipal hospital networks in Bahia and Pernambuco represent the most penetrable buyer archetype, with imaging center density sitting below one-third of Southeast levels. Target point-of-care workflow integration in emergency departments seeking bedside diagnostic capability over centralized radiology dependency. Pursue ANVISA software-as-medical-device registration for unbundled image analysis algorithms to bypass hardware capital cycle compression. For Investors and Strategic Acquirers: Diversified imaging conglomerates with software subscription revenue streams are the most active acquirer in this space, consolidating mid-tier digital console specialists. Long-term viability hinges on algorithmic analysis tool penetration displacing hardware-centric business models. Watch ANVISA harmonization with Mercosur technical standards as the inflection signal for import documentation simplification and multinational supplier customs clearance acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Registration | ANVISA pathway compression accelerates market entry for AI-powered analysis tools bundled with hardware. |
| Point-of-Care Platform Deployment | Municipal hospital networks in Minas Gerais pilot shared-device pools reducing capital intensity per department. |
| Per-Procedure Leasing Structures | Private imaging chains in Curitiba and Porto Alegre shift credit risk onto manufacturer financing subsidiaries. |
| Northeast Regional Distribution Expansion | Bahia and Pernambuco whitespace attracts portable system distributors targeting maternal-fetal departments. |
| Therapeutic Ultrasound Segment Development | Sports medicine clinics in Rio de Janeiro adopt focused acoustic energy devices for soft tissue intervention. |
Study Parameters
Coverage spans Southeast, Northeast, South, and Midwest Brazil, with primary inputs from each regional cluster. Interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and maternal-fetal department heads combined with secondary validation from ANVISA registration databases, Ministry of Health RENISUS equipment distribution records, and customs import documentation. Bottom-up triangulation across municipal hospital procurement frameworks and top-down reconciliation against imaging center density benchmarks anchored volume estimates.
Rate-of-change decomposition across the projection horizon isolates technology substitution effects, regulatory pathway acceleration, and regional penetration dynamics. Segmentation dimensions modeled include product architecture, end-user facility type, signal processing technology, and clinical application area. CAGRs were derived from installed base replacement cycles and software subscription adoption curves. ANVISA software-as-medical-device classification guidance and Mercosur harmonization timeline uncertainty constitute key forecast sensitivity inputs.
Inputs from ANVISA registration filings and Ministry of Health procurement databases were available through the study window; gaps in real-time semiconductor supply chain data introduce uncertainty bands around hardware cost assumptions. Forecasts reflect documented assumptions regarding digital platform adoption velocity and public budget allocation stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
India Medical Devices Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
United Kingdom Minimally Invasive Surgery Devices Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Spinal Fusion Market
Medical Devices
Education Microscope Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Digital Impression System Market