
 Asia-Pacific General Surgical Devices Market | 2026-2036
Asia-Pacific General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific General Surgical Devices Market Outlook
Premium-grade sterilization compliance is collapsing the cost gap between imported and locally manufactured surgical devices across the Asia-Pacific region. Medtronic leverages its established distribution infrastructure to sustain leadership in electrosurgical systems across Japan and Australia. Johnson & Johnson anchors its position through R&D intensity in absorbable suture technology, while B. Braun Melsungen AG differentiates via specialized manufacturing of laparoscopic instrumentation for minimally invasive procedures.
General surgical devices encompass instruments, apparatus, and consumables designed for tissue manipulation, wound closure, and hemostasis during operative procedures, typically manufactured from medical-grade stainless steel, titanium alloys, or biocompatible polymers with tolerances measured in micrometers for precision performance. These tools serve the fundamental purpose of enabling safe, effective surgical intervention across acute care settings. Electrosurgical devices and laparoscopic devices capture expanding margin pools as hospitals prioritize minimally invasive outcomes, while surgical sutures retain volume dominance due to universal applicability across general surgery applications. Robotic-assisted technology segments demonstrate the steepest trajectory as capital investment flows into tertiary hospitals seeking surgical precision advantages.
Japan's PMDA and Australia's TGA enforce stringent biocompatibility and electrical safety standards that shape product registration timelines and compliance costs for device manufacturers entering these markets. India's CDSCO and China's NMPA maintain evolving regulatory frameworks that increasingly recognize international standards while requiring localized clinical validation, directly influencing market access strategies. Stakeholders must monitor harmonization progress between national regulators and the pace of domestic certification capacity building as determinants of competitive positioning.
Market Dynamics
India's PLI scheme for medical device manufacturing is compressing import dependency by subsidizing domestic electrosurgical instrument production, while China's tier-one hospitals accelerate capital deployment into robotic-assisted surgical systems.
Growth Catalysts
- Japan's PMDA Fast-Track Pathway:Expedited approval timelines for breakthrough surgical devices are shortening commercialization cycles for minimally invasive instrumentation entering tertiary hospital systems.
- Chronic Disease Surgical Burden:Southeast Asian hospital expansion programs are scaling operating theater capacity to address cardiovascular and oncological intervention backlogs.
- Medical-Grade Titanium Alloy Localization:Chinese domestic smelting capabilities are reducing raw material costs for precision-manufactured laparoscopic graspers and retractors.
Market Restraints
- Biocompatibility Certification Costs:Australia's TGA electrical safety and ISO 10993 testing requirements impose six-figure validation expenses on mid-scale manufacturers.
- Single-Source Component Dependency:German and Japanese suppliers dominate high-frequency electrosurgical generator subassemblies, creating supply concentration risk.
- Reusable Instrument Disinfection Infrastructure:Steam sterilization autoclave capacity constraints in Indonesian provincial hospitals limit adoption of premium surgical toolsets.
Strategic Opportunities
- Vietnam's Underpenetrated Provincial Networks:Secondary city hospital clusters lack laparoscopic device coverage, creating first-mover advantage for distribution partnerships.
- 5G-Enabled Remote Surgical Consultation:Convergence of telepresence platforms with robotic arm interfaces enables intraoperative specialist support across archipelago geographies.
- India's CDSCO Harmonization Initiative:Mutual recognition agreements with FDA and EU MDR are streamlining dual-market registration for export-oriented manufacturers.
Industry Challenges
- Robotic Surgery Technician Scarcity:Shortage of certified console operators in South Korean and Australian regional hospitals constrains system utilization rates.
- Legacy Electrosurgical System Interoperability:Integration friction between new energy platforms and existing grounding pad infrastructure delays operating room commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific General Surgical Devices Market |
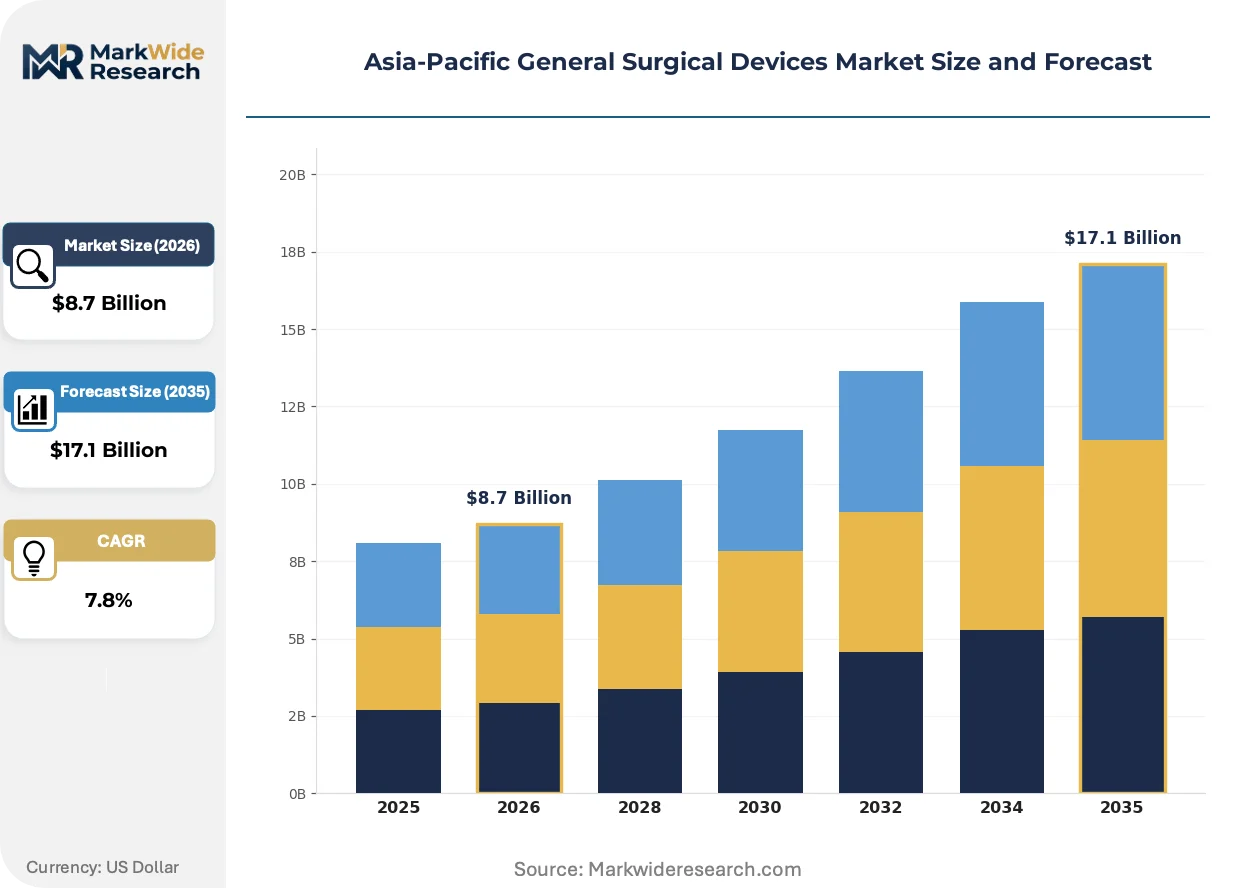
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Sutures, Surgical Staplers, Electrosurgical Devices, Laparoscopic Devices End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Laboratories Technology: Minimally Invasive, Robotic-Assisted, Conventional Surgery, Advanced Imaging Application: General Surgery, Orthopedic Surgery, Cardiac Surgery, Neurosurgery |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun Melsungen AG, Boston Scientific Corporation, Stryker Corporation, Conmed Corporation, Olympus Corporation, Smith & Nephew, Karl Storz, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific General Surgical Devices Market Strategic Shifts
Disposable instrument kits are displacing traditional reusable sets across Asia-Pacific ambulatory surgical centers, while regulatory convergence and procurement centralization reshape competitive access pathways.
Single-use electrosurgical pencils with integrated smoke evacuation are supplanting conventional reusable handles in Australian and Japanese day-surgery facilities. Tertiary hospitals in Seoul and Singapore are adopting these devices to eliminate cross-contamination protocols and reduce sterilization labor costs. This shift is compressing aftermarket service revenue pools while expanding consumables margin capture for manufacturers with sterile packaging capabilities.
China's NMPA revised medical device classification rules are re categorizing certain laparoscopic staplers from Class II to Class III, extending clinical trial requirements by twelve to eighteen months. Domestic manufacturers are responding by prioritizing registration dossiers for highest-volume SKUs while deferring niche instrument submissions. Japanese and Australian subsidiaries of multinational firms face parallel documentation burdens as regional regulators tighten predicate device equivalence standards.
Hospital procurement consortia in Thailand and Malaysia are consolidating vendor panels through centralized tendering platforms, displacing decentralized purchasing authority previously held by individual surgical department heads. This concentration is favoring suppliers with national distribution infrastructure and multi-year total cost-of-ownership contracting capabilities. The shift is most visible in Malaysia's Ministry of Health integrated supply chain program, where electrosurgical device awards now span five-year performance-based agreements.
Asia-Pacific General Surgical Devices Market Segmentation
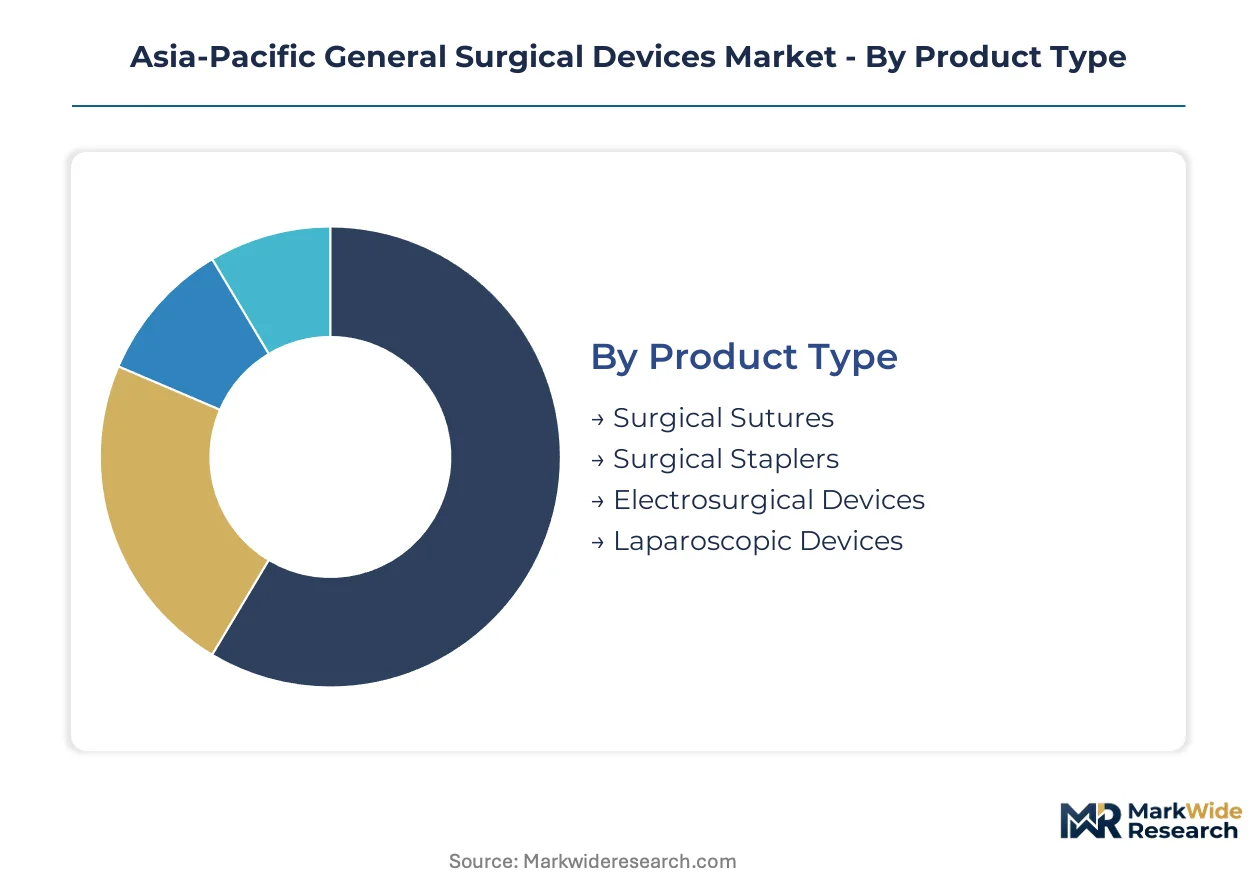
Surgical device purchasing across the Asia-Pacific region fragments sharply across facility tiers and reimbursement systems. Product selection criteria diverge materially between China's tier-one robotic surgery centers and Indonesia's provincial sterilization-constrained hospitals.
Product Type:
Japan's PMDA and Australia's TGA impose divergent electrical safety testing protocols on powered surgical instruments, creating registration cost asymmetries that favor certain product categories over others.
- Electrosurgical Devices:High-frequency generators and active electrodes manufactured with medical-grade titanium alloys dominate margin pools in tertiary hospital systems. China's NMPA Class III reclassification timeline is compressing domestic manufacturer R&D cycles for advanced energy platforms.
- Laparoscopic Devices:Graspers, retractors, and trocar systems enable minimally invasive access through 5-12mm ports with precision tolerances measured in micrometers. Korean MFDS certification requirements for reusable instrumentation are accelerating single-use kit adoption in Seoul's day-surgery facilities.
- Surgical Sutures:Absorbable and non-absorbable wound closure threads retain universal applicability across all surgical disciplines and facility tiers.
- Surgical Staplers:Linear and circular stapling platforms for gastrointestinal and thoracic anastomosis face extended clinical trial requirements under China's revised classification rules.
Surgical sutures handle the majority of throughput; electrosurgical devices are gaining share fastest as energy platform upgrades accelerate across Asia-Pacific tertiary centers.
End User:
Procurement centralization is redistributing purchasing authority from individual surgeons to hospital consortia and ministry-level tendering platforms.
- Hospitals:Tertiary medical centers in China's Beijing-Shanghai-Guangzhou corridor and Japan's university hospital networks deploy capital-intensive robotic systems and advanced energy platforms. Australia's public hospital purchasing consortia are consolidating electrosurgical device awards into five-year performance-based agreements.
- Ambulatory Surgical Centers:Day-surgery facilities in Australian and Japanese metropolitan areas prioritize single-use instrument kits to eliminate cross-contamination protocols and reduce sterilization labor overhead.
- Clinics:Outpatient surgical settings concentrate on wound closure consumables and basic hemostasis tools with lower capital requirements.
- Diagnostic Laboratories:Tissue sampling and biopsy procedures drive demand for precision cutting and retrieval instruments.
Hospitals absorb the dominant share of device procurement value; ambulatory surgical centers are expanding most quickly as same-day discharge protocols proliferate across Asia-Pacific healthcare systems.
Technology:
Capital deployment patterns vary dramatically by technology maturity, with robotic platforms requiring dedicated console operators and infrastructure investment.
- Robotic-Assisted:Da Vinci and competing surgical robot systems enable tremor-filtered precision with 3D visualization in China's tier-one hospitals. South Korean and Australian regional facilities face certified technician scarcity that constrains system utilization rates.
- Minimally Invasive:Laparoscopic and thoracoscopic approaches reduce recovery times and complication rates versus open procedures. Vietnam's underpenetrated provincial hospital networks lack laparoscopic device coverage, creating first-mover distribution opportunities.
- Conventional Surgery:Open surgical techniques retain dominance in resource-constrained settings with limited capital equipment access.
- Advanced Imaging:Intraoperative fluorescence and augmented reality navigation systems integrate with laparoscopic and robotic platforms.
Minimally invasive technology commands the largest installed base; robotic-assisted systems show the steepest expansion trajectory as capital investment flows into precision surgery programs.
Application:
Chronic disease burden distribution shapes procedure volume concentration across surgical disciplines.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair procedures generate consistent instrument demand across all facility tiers. Southeast Asian hospital expansion programs are scaling operating theater capacity specifically to address general surgery backlogs.
- Orthopedic Surgery:Joint replacement and trauma fixation procedures drive demand for powered instruments and specialized retractor systems. India's PLI scheme for medical device manufacturing is accelerating domestic production of orthopedic surgical tools.
- Cardiac Surgery:Coronary artery bypass and valve replacement procedures concentrate in specialized tertiary centers with cardiopulmonary bypass capability.
- Neurosurgery:Cranial and spinal procedures require microsurgical instruments with sub-millimeter precision specifications.
General surgery manages the highest procedure volume; orthopedic surgery is climbing fastest as aging demographics and trauma incidence expand intervention requirements across Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency persists across Southeast Asian markets while China and India compress foreign device reliance through domestic manufacturing subsidies and localized supply chain buildouts. Japan and Australia maintain net importer status for premium electrosurgical systems despite mature regulatory frameworks. Tier-one hospital capital deployment in Beijing, Seoul, and Sydney concentrates demand for robotic-assisted platforms.
China
Robotic-assisted surgical programs scale rapidly in Beijing-Shanghai-Guangzhou corridor hospitals. NMPA revised classification rules extend clinical trial timelines for laparoscopic staplers from Class II to Class III. Domestic titanium alloy smelting in Jiangsu and Zhejiang provinces reduces raw material costs for precision-manufactured graspers.
Japan
PMDA fast-track pathways accelerate breakthrough device approvals for minimally invasive instrumentation. Tertiary university hospital networks in Tokyo and Osaka deploy capital-intensive energy platforms. Electrical safety testing protocols under PMDA guidance shape registration cost structures for powered surgical instruments.
India
PLI scheme subsidies compress import dependency for electrosurgical instrument production. CDSCO harmonization initiatives with FDA and EU MDR streamline dual-market registration pathways. Maharashtra and Gujarat manufacturing clusters scale domestic output of orthopedic and general surgical tools.
Australia
TGA biocompatibility and ISO 10993 testing requirements impose six-figure validation expenses on market entrants. Public hospital purchasing consortia consolidate electrosurgical awards into five-year performance-based agreements. Sydney and Melbourne metropolitan day-surgery facilities prioritize single-use instrument kits.
South Korea
MFDS certification requirements for reusable laparoscopic instrumentation accelerate disposable kit adoption in Seoul facilities. Certified robotic surgery console operator scarcity constrains system utilization rates in regional hospitals. Daegu-Gyeongbuk industrial zones support component fabrication for surgical device supply chains.
Asia-Pacific General Surgical Devices Market Competitive Environment
Concentration sits with diversified multinational conglomerates holding established distribution infrastructure across developed Asia-Pacific markets. Japanese and Australian subsidiary networks of global firms leverage predicate device equivalence standards to defend market positions. Three strategic archetypes dominate: integrated energy platform suppliers, specialized minimally invasive instrumentation manufacturers, and consumables-focused suture and staple producers. Competitive moves center on five-year total cost-of-ownership contracting with hospital procurement consortia and sterile packaging capability investments for disposable kit transitions.
Among diversified medical technology conglomerates, Medtronic, Johnson & Johnson, and Stryker Corporation represent the integrated platform archetype with broad electrosurgical and laparoscopic portfolios. These entities occupy positions sustained by national distribution infrastructure and multi-year hospital agreements. B. Braun Melsungen AG exemplifies the specialized instrumentation tier with focused manufacturing capabilities. Olympus Corporation and Karl Storz sit within the visualization and access device segment, while Smith & Nephew and Boston Scientific Corporation anchor positions in wound closure and advanced energy applications respectively.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| Stryker Corporation |
| Conmed Corporation |
| Olympus Corporation |
| Smith & Nephew |
| Karl Storz |
| Others |
Value Chain & Pricing Dynamics
Five-year performance-based agreements with hospital procurement consortia lock in supply access for electrosurgical device manufacturers while compressing price visibility for mid-scale competitors. Australia's TGA validation expenses and China's NMPA reclassification timelines embed compliance costs into contract structures across the Asia-Pacific region.
Pricing Analysis
Hospital procurement consortia anchor three-tier pricing structure across premium, standard, and economy levels in Australia's public health system. Price differentiation hinges on ISO 13485 certification grade and after-sales service bundling for energy platform maintenance. Pricing pressure stems from India's PLI-subsidized domestic production of titanium alloy instruments. Provincial hospital networks in Indonesia exhibit highest price sensitivity due to sterilization infrastructure constraints, while Japan's university hospitals show lowest sensitivity given fast-track PMDA pathway preferences.
Supply Chain Analysis
German and Japanese suppliers of high-frequency electrosurgical generator subassemblies constitute a chokepoint that constrains margin flexibility for downstream device integrators. Component fabrication concentrates in China, Germany, and Japan for precision-machined titanium graspers and active electrodes. Raw material dependencies rest on medical-grade titanium alloy smelting in Jiangsu and Zhejiang provinces, biocompatible polymer feedstocks, and ceramic insulator substrates. Single-source vulnerability from concentrated generator subassembly supply creates structural risk. Distribution runs through national hospital procurement consortia and ministry-level tendering platforms displacing decentralized surgical department purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable instrument kit transitions represent a service-attach opportunity where sterile packaging and logistics capabilities expand faster than capital equipment hardware sales. Recurring consumables revenue pools are displacing aftermarket service contracts across Australian and Japanese day-surgery facilities.
For Market Incumbents: Consolidate distribution infrastructure control through multi-year total cost-of-ownership contracting with Thailand's Ministry of Health and Malaysia's integrated supply chain programs. Deepen backward integration into medical-grade titanium alloy smelting to offset China's domestic cost advantages. Threat from CDSCO-FDA harmonization enabling Indian export-oriented manufacturers demands certification investment leverage. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated provincial hospital networks where laparoscopic device coverage gaps create first-mover distribution partnerships. Target secondary city clusters in Indonesia constrained by steam sterilization autoclave capacity. Pursue 5G-enabled remote surgical consultation platforms as go-to-market angle for archipelago geographies. For Investors and Strategic Acquirers: Capital is best deployed toward specialized minimally invasive instrumentation manufacturers with sterile packaging capabilities and robotic-assisted surgery technician training infrastructure. Long-term viability over the projection horizon favors consumables-focused producers over capital-intensive energy platform suppliers. Signal to watch is NMPA classification rule harmonization progress as inflection indicator for China market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Five-year agreements with Australia's public hospital consortia secure electrosurgical device volume commitments. |
| CE Marking Pathway | Streamlined EU MDR recognition accelerates dual-market registration for Indian export-oriented manufacturers. |
| Software Companion Development | Telepresence platform integration with robotic arm interfaces enables intraoperative specialist support. |
| Reimbursement Strategy | Alignment with Japan's PMDA fast-track pathway shapes premium pricing for breakthrough minimally invasive devices. |
| Backward Integration | Captive titanium alloy smelting in Jiangsu province reduces raw material cost exposure for precision graspers. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads and refined through secondary validation. Sources included hospital procurement databases, GPO contract filings, NMPA registration dossiers, PMDA approval records, and customs trade data. Bottom-up facility-level demand modeling triangulated with top-down national healthcare expenditure projections.
Variance decomposition across product type, end user tier, technology maturity, application discipline, and country regulatory cluster shaped analytical framework development. CAGRs were derived from segmented demand modeling throughout the forecast period. Industry-specific inputs incorporated PLI scheme subsidy trajectories, NMPA reclassification timeline impacts, and 5G infrastructure deployment curves for remote surgical applications.
Decision-makers should treat outputs as directional under assumptions of continued regulatory harmonization progress and chronic disease surgical burden expansion; material deviation in CDSCO-FDA mutual recognition pace or robotic technician training capacity would warrant model refresh. Practitioners should keep alternative scenarios live as hospital procurement centralization and single-use kit transition rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gastric Bands Market
Medical Devices
Pulse Lavage Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Netherlands Respiratory Devices Market
Medical Devices
Immunoadsorption Columns Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
EMG Biosensors Market
Medical Devices
Global Gastric Balloons Market