
 Intracranial Pressure (ICP) Monitoring Devices Market | 2026-2036
Intracranial Pressure (ICP) Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Intracranial Pressure (ICP) Monitoring Devices Market Intelligence
The divergence in R&D investment for non-invasive sensor technologies versus mature catheter systems is reorganizing the market structure. Medtronic leverages its extensive distribution network and broad portfolio in neuromodulation to maintain a significant presence. In contrast, specialists like Raumedic differentiate through deep expertise in neuro-monitoring and rapid innovation in specific sensor technologies. Integra LifeSciences sustains its market position through a combination of surgical and critical care solutions for neurosurgery.
Intracranial pressure monitoring devices are medical instruments used to measure pressure within the skull. These systems typically consist of a sensor or catheter placed inside the head and a transducer that converts the pressure reading into a digital signal with high fidelity. Invasive devices, particularly catheter-based systems, remain the gold standard in hospitals for traumatic brain injury management due to their accuracy. However, non-invasive devices using ultrasound or optical sensors are gaining traction for applications in clinics and emergency medical services where lower risk is paramount.
Market access is governed by stringent regulatory approvals from bodies such as the US FDA and requirements for CE marking in Europe. These regulations, along with standards from bodies like the PMDA in Japan, mandate rigorous clinical validation for both accuracy and patient safety. The key decision for manufacturers will be balancing investment in next-generation non-invasive technologies against the established reimbursement pathways for invasive methods.
Market Dynamics
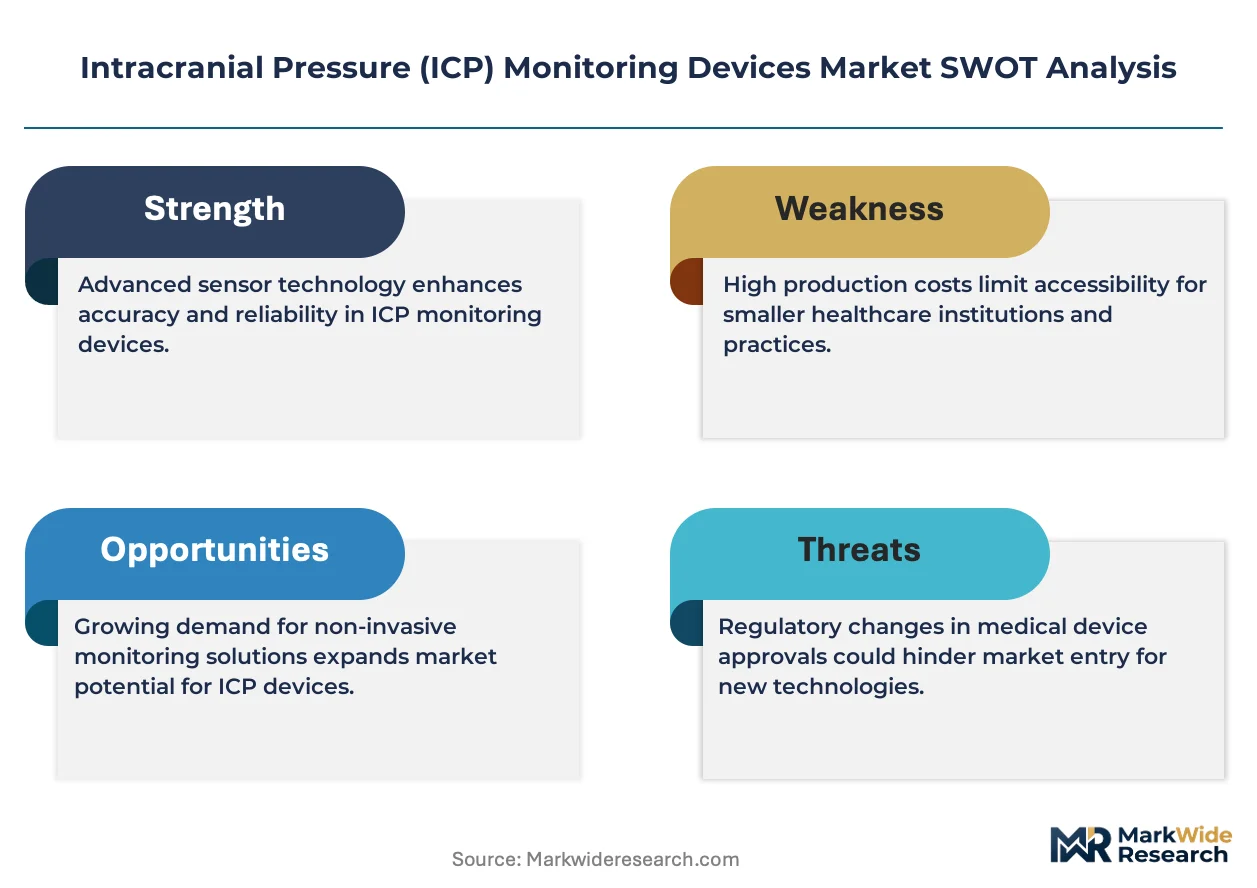
The central force shaping the ICP monitoring market is the technological and clinical divergence between highly accurate, invasive catheter systems and the development of lower-risk, non-invasive sensors. This bifurcation influences R&D investment, regulatory strategy, and clinical adoption pathways.
Growth Catalysts
- Traumatic Brain Injury Management:The rising incidence of TBIs from traffic accidents and sports activities sustains demand for precise monitoring within hospital neuro-intensive care units.
- Advanced Trauma Infrastructure:Investment in specialized trauma centers in developed economies like Germany and Japan creates concentrated demand for high-fidelity ICP monitoring systems.
- Sensor Technology Development:Continuous innovation in less invasive sensor materials and designs is improving patient outcomes and expanding the potential applications beyond critical care.
Market Restraints
- High Cost of Invasive Procedures:The expense associated with surgical implantation and intensive care for catheter-based systems restricts their use primarily to severe, life-threatening cases.
- Accuracy of Non-Invasive Methods:Emerging non-invasive technologies using ultrasound or optical methods have not yet consistently matched the accuracy of invasive devices, limiting their approval by bodies like the US FDA for primary diagnosis.
- Reimbursement Disparities:Existing reimbursement frameworks in many healthcare systems are structured around established invasive procedures, creating a financial barrier for the adoption of novel non-invasive technologies.
Strategic Opportunities
- Telemedicine and Remote Monitoring:Integrating ICP data with telehealth platforms offers an opportunity to monitor patients post-discharge or in decentralized clinical trials, expanding care beyond the hospital.
- Pediatric and Neonatal Care:There is a significant opportunity to develop smaller, less invasive monitoring systems specifically designed for the anatomical and physiological needs of pediatric patients.
- Pre-Hospital Diagnostics:Developing portable, rugged, and easy-to-use non-invasive devices for emergency medical services (EMS) can enable earlier triage and treatment of head injuries.
Industry Challenges
- Data Integration and Interoperability:Ensuring that new ICP monitoring devices can seamlessly connect and share data with existing hospital electronic health record (EHR) and patient monitoring systems remains a major technical hurdle.
- Clinical Validation Timelines:The lengthy and costly clinical trials required to secure regulatory approval from agencies like Japan's PMDA and the US FDA delay the market introduction of new sensor technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intracranial Pressure (ICP) Monitoring Devices Market |
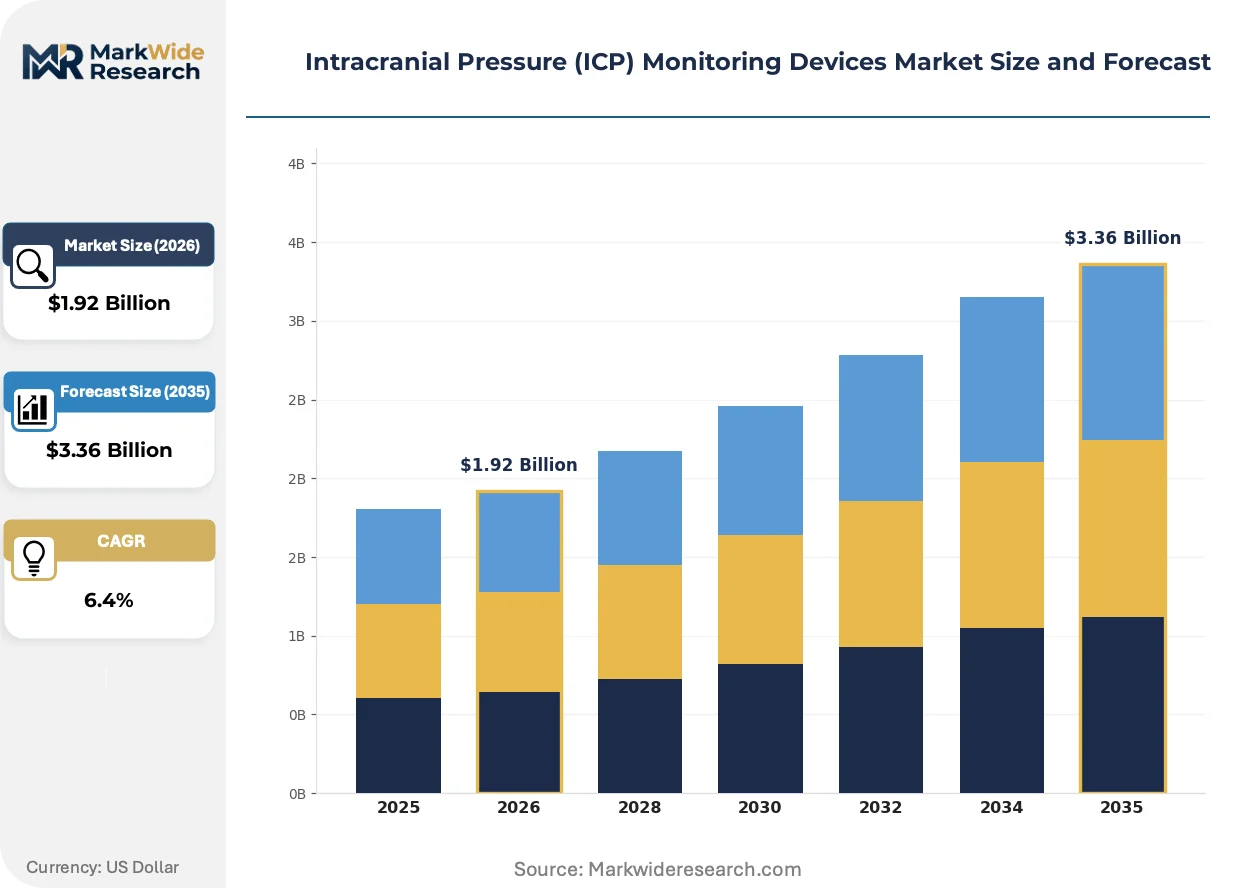
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Devices, Non-Invasive Devices, Catheter-Based Devices, Wearable Sensors Technology: Optical Sensors, Electrical Sensors, Fluid Displacement Sensors, Ultrasound Sensors End User: Hospitals, Clinics, Research Institutions, Emergency Medical Services Application: Traumatic Brain Injury, Hemorrhagic Stroke, Hydrocephalus, Brain Tumors |
| Companies Covered | Sophysa, Raumedic, Integra LifeSciences, Natus Medical, Depuy Synthes, Medtronic, Spiegelberg, Gaeltec Devices, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intracranial Pressure (ICP) Monitoring Devices Market Strategic Shifts & Innovations
The pursuit of high-fidelity monitoring without the risks of invasive surgery defines current market evolution. This objective drives innovation in sensor technology, reshapes regulatory compliance strategies, and alters how healthcare providers acquire and utilize these critical diagnostic tools.
Miniaturized fiber optic sensors provide a less invasive method for direct pressure measurement by translating light interference into a digital signal. Neuro-intensive care units are increasingly using these for post-operative monitoring where short-term, high-accuracy data is essential. This development is fragmenting the market, moving it from a single gold standard toward a portfolio of specialized monitoring solutions.
Europe's Medical Device Regulation (MDR) mandates more stringent clinical evidence and post-market surveillance for all devices, including ICP monitors. This regulation increases the burden of proof for demonstrating safety and efficacy throughout a product's lifecycle. Consequently, manufacturers of both legacy and new systems face higher compliance costs and longer development timelines to maintain CE marking.
Hospital systems are increasingly favoring subscription or pay-per-use models over traditional outright capital purchases for monitoring equipment. This shift disrupts the one-time sales cycle, forcing vendors to develop service-based revenue streams. The trend is most pronounced in large, budget-conscious hospital networks in the United States and parts of Europe seeking to manage operational expenses.
Intracranial Pressure (ICP) Monitoring Devices Market Segmentation
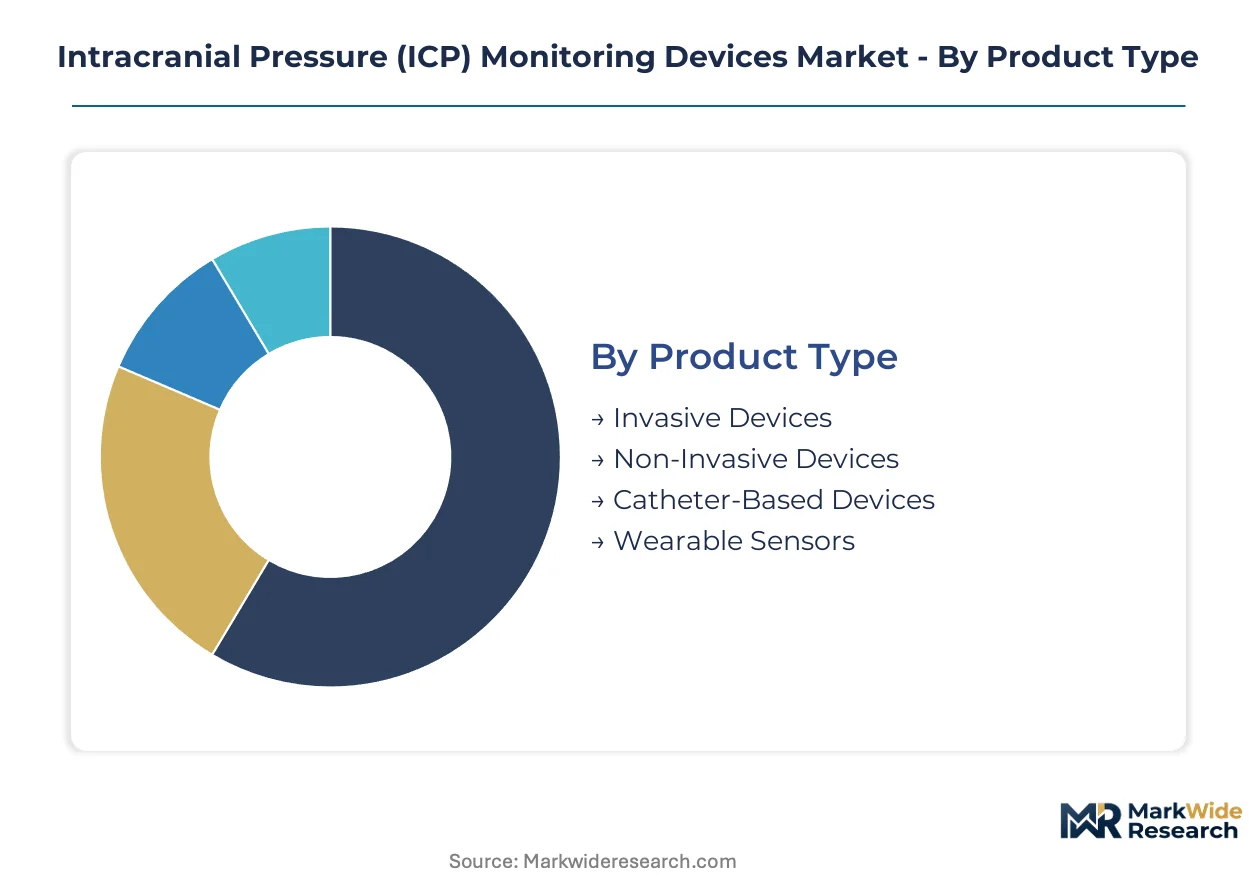
The Intracranial Pressure (ICP) monitoring market segments across distinct product types, underlying technologies, primary end-users, and critical clinical applications. Understanding these divisions helps clarify where innovation is concentrating and how different device categories meet specific clinical needs. This granular view reveals distinct adoption patterns across diverse healthcare settings.
Product Type:
The distribution channels for ICP monitoring devices vary significantly depending on their invasiveness, influencing procurement and clinical deployment strategies across healthcare providers.
- Invasive Devices:These systems involve direct intracranial placement of a sensor or catheter, providing highly accurate, continuous pressure readings. Demand in hospital neuro-intensive care units for severe traumatic brain injury management remains consistent due to their established clinical efficacy.
- Non-Invasive Devices:These technologies measure ICP indirectly through external means, such as ultrasound or optical methods, avoiding surgical intervention. Their adoption is expanding in clinics and emergency medical services where lower procedural risk and ease of use are prioritized over gold-standard accuracy.
- Catheter-Based Devices:These invasive systems use fluid-filled or fiber-optic catheters inserted into brain ventricles or parenchyma.
- Wearable Sensors:These emerging non-invasive solutions enable continuous, long-term monitoring outside acute hospital settings, prioritizing patient comfort.
By volume, Invasive Devices lead the market. By growth pace, Non-Invasive Devices are expanding most quickly.
Technology:
Technological advancements in ICP monitoring directly impact device accuracy, cost-effectiveness, and suitability for various clinical applications, from critical care to remote diagnostics.
- Optical Sensors:These miniaturized fiber optic sensors translate light interference into digital pressure signals, offering high fidelity and less invasive direct measurement. Their use is increasing for post-operative monitoring where precise, short-term data is essential for patient management.
- Ultrasound Sensors:These non-invasive technologies utilize sound waves to infer intracranial pressure changes, providing a safer alternative for initial assessment. Adoption is growing in emergency medical services and pediatric care due to their portability and absence of surgical risk.
- Electrical Sensors:These devices measure pressure via electrical resistance or capacitance, common in both invasive and non-invasive ICP monitoring systems.
- Fluid Displacement Sensors:These traditional invasive systems rely on fluid column displacement to measure intracranial pressure.
Optical Sensors offer superior precision for specific clinical needs, while Ultrasound Sensors provide a balance of safety and utility in less acute settings.
End User:
Different end-user environments for ICP monitoring devices dictate requirements for device complexity, portability, and integration with existing healthcare infrastructure.
- Hospitals:These institutions represent the primary consumer of ICP monitoring devices, particularly invasive catheter-based systems, for managing severe neurological conditions in neuro-intensive care units. Stringent regulatory requirements and established reimbursement pathways drive their continued reliance on gold-standard accuracy.
- Emergency Medical Services:EMS providers require portable, rugged, and easy-to-use non-invasive ICP monitoring solutions for rapid pre-hospital assessment and triage of head injury patients. The need for immediate, actionable data without invasive procedures is paramount in this setting.
- Clinics:Outpatient facilities are increasingly adopting non-invasive ICP monitoring for follow-up care and screening, prioritizing patient comfort.
- Research Institutions:Academic and private research entities utilize specialized ICP monitoring systems for clinical trials and next-generation sensor development.
Hospitals continue to anchor ICP monitoring demand for critical care, while Emergency Medical Services represent a significant expansion opportunity for non-invasive technologies.
Application:
The clinical application of ICP monitoring devices directly correlates with disease prevalence and the severity of neurological conditions, influencing device design and required performance.
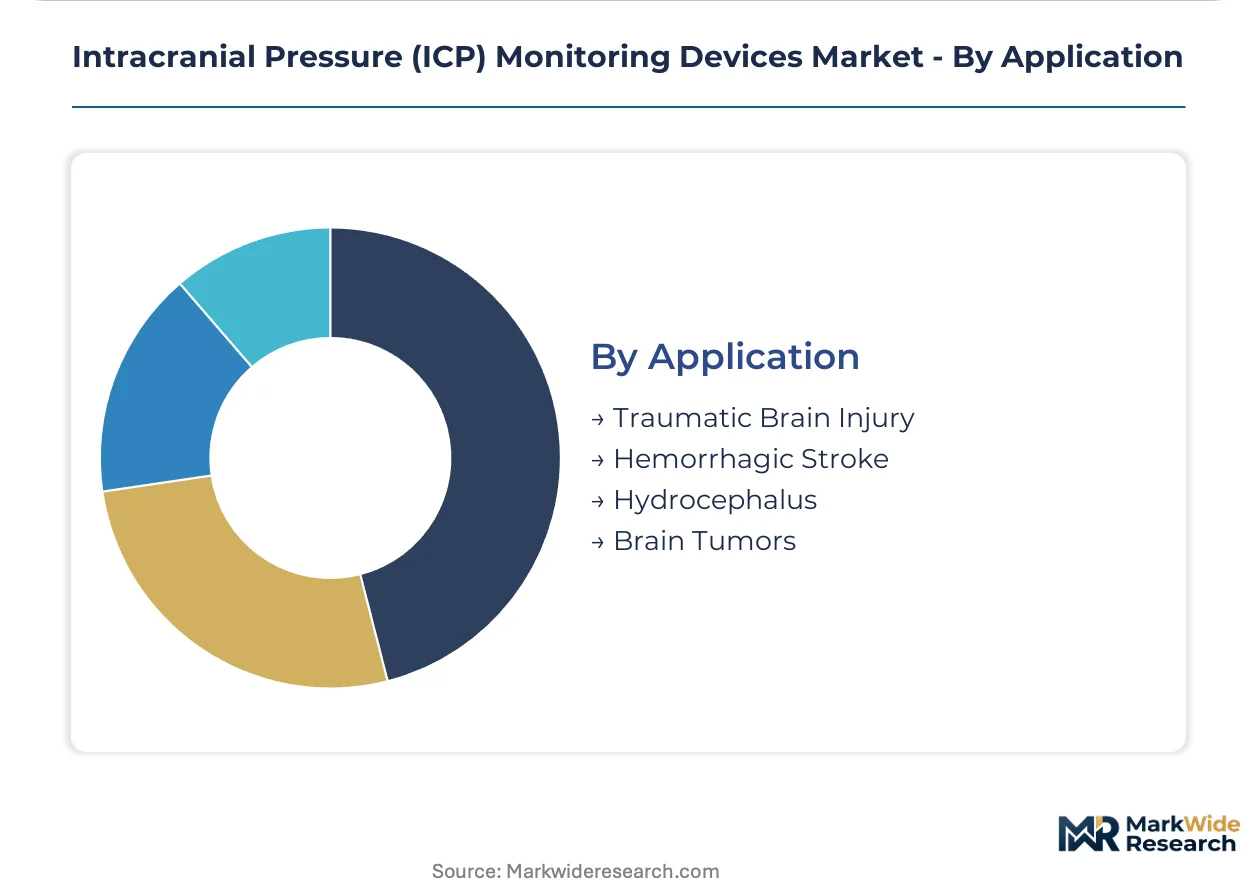
- Traumatic Brain Injury:This application constitutes a major driver for ICP monitoring, particularly for severe cases requiring precise, continuous intracranial pressure management in hospital settings. The rising incidence of TBIs from accidents sustains demand for high-fidelity systems.
- Hemorrhagic Stroke:ICP monitoring is crucial for managing patients with hemorrhagic stroke, where elevated intracranial pressure can lead to secondary brain injury. Timely detection and intervention are vital for improving patient outcomes in these critical scenarios.
- Hydrocephalus:ICP monitoring aids hydrocephalus management, assessing shunt function and guiding treatment for cerebrospinal fluid accumulation.
- Brain Tumors:Patients with brain tumors often undergo ICP monitoring to detect and manage mass effect or edema-related pressure increases post-operatively.
Traumatic Brain Injury and Hemorrhagic Stroke collectively drive the most significant clinical demand, necessitating accurate and reliable ICP monitoring solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Different regions exhibit varying consumption patterns for ICP monitoring devices, reflecting diverse healthcare priorities and infrastructure. The United States and European nations show strong demand for advanced invasive systems in critical care settings. Japan, conversely, emphasizes both high-accuracy invasive methods and emerging non-invasive technologies for broader applications.
United States
The United States market for ICP monitoring devices is driven by a high incidence of traumatic brain injuries and a well-established neuro-intensive care infrastructure. US FDA regulations mandate rigorous clinical trials for all new medical devices, ensuring patient safety and efficacy. Boston's medical device hub, including companies and research institutions, actively develops next-generation sensor technologies.
Germany
Germany showcases significant demand due to its advanced trauma care infrastructure and emphasis on high-fidelity patient monitoring. CE marking under Europe's Medical Device Regulation (MDR) sets stringent standards for ICP device approval and post-market surveillance. University hospitals in Munich and Berlin serve as key centers for clinical adoption and research into novel monitoring solutions.
Japan
Japanese demand for ICP monitoring is influenced by an aging population and a strong focus on effective stroke management. The PMDA, Japan's pharmaceutical and medical devices agency, enforces strict regulatory approvals for all medical instruments. Medical technology firms in Tokyo concentrate on miniaturization and developing non-invasive applications suitable for broader clinical use.
France
France's public health system and well-developed neurosurgery centers generate consistent demand for ICP monitoring solutions. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) supervises medical device safety and market access within the country. University hospitals in Paris are crucial sites for integrating advanced ICP monitoring into complex neurosurgical procedures.
Intracranial Pressure (ICP) Monitoring Devices Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the ICP monitoring market. The market structure features both diversified medical technology giants and highly focused neuro-monitoring innovators. Two distinct strategic archetypes emerge: broad-portfolio providers leveraging extensive distribution networks, and niche players specializing in rapid sensor technology advancements. Portfolio diversification and strategic partnerships represent dominant competitive moves among these firms seeking to expand their clinical reach.
Among the market's key participants, Medtronic, a globally recognized medical technology firm, leverages its extensive distribution network and broad portfolio to maintain a significant presence. Raumedic, a German-based company, exemplifies the specialist tier through deep expertise in neuro-monitoring and rapid innovation in specific sensor technologies. Integra LifeSciences, an American medical device company, occupies a position through its combination of surgical and critical care solutions for neurosurgery.
| Leading Market Players |
|---|
| Sophysa |
| Raumedic |
| Integra LifeSciences |
| Natus Medical |
| Depuy Synthes |
| Medtronic |
| Spiegelberg |
| Gaeltec Devices |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Advanced miniaturized components substituting traditional sensor materials simultaneously reshape supply geography and the pricing economics for Intracranial Pressure (ICP) monitoring devices.
Pricing Analysis
Contract-based long-term offtake agreements increasingly define pricing for integrated ICP monitoring systems within large hospital networks. Price differentiation stems from clinical accuracy for invasive devices and the level of integration with existing hospital electronic health records. Pricing pressure stems from the rising competition from emerging non-invasive technologies and healthcare budget constraints. Emergency Medical Services and clinics represent the most price-sensitive buyers, while neuro-intensive care units prioritize accuracy over cost for severe cases.
Supply Chain Analysis
Inventory management for specialized ICP monitoring components demands careful planning due to extended lead times for highly specialized sensor materials. Supply concentration for advanced microelectronics and fiber optic components centers on countries like Germany, Japan, and the United States. Raw material dependencies include medical-grade polymers, miniaturized fiber optics, and advanced micro-electromechanical systems (MEMS). Regulatory restrictions from bodies like the US FDA and Europe's MDR represent a structural supply chain risk. Distribution runs through a combination of direct sales forces to major hospitals and specialized medical distributors serving smaller clinics and emergency services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital systems consolidating into larger purchasing groups represent a significant buyer-power shift within the ICP monitoring market, impacting procurement strategies.
For Market Incumbents:Fortify established market share by expanding into service-based revenue models and enhancing data integration capabilities with existing hospital IT infrastructure. Medtronic should leverage its extensive distribution network to introduce next-generation non-invasive solutions, mitigating the threat from specialized sensor developers. Investment in advanced manufacturing for miniaturized components can reduce reliance on external suppliers. Protecting core invasive device revenue streams requires continuous clinical evidence generation for superior patient outcomes against emerging non-invasive alternatives.
For New Entrants and Emerging Players:Expedited CE marking pathways for novel non-invasive technologies offer a significant opportunity to access European markets quickly. Target pediatric and neonatal care segments with smaller, less invasive monitoring systems, which represent a significant white-space opportunity. Partnering with telehealth providers for remote monitoring solutions offers a compelling go-to-market angle for continuous patient management outside acute settings. Focus on developing rugged, portable devices specifically for pre-hospital diagnostics in emergency medical services.
For Investors and Strategic Acquirers:The market sits at a transitional phase that favors specialists with proprietary non-invasive sensor technology. Long-term viability in this sector is strong, driven by persistent demand from traumatic brain injury and an aging population. Acquisition targets should include niche firms excelling in miniaturization, data analytics, or specific non-invasive modalities. Regulatory approval for non-invasive devices to be used for primary diagnosis in the US or Europe serves as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Non-Invasive Device | Secures market access for novel technology in the critical US market. |
| Hospital System Partnership | Expands clinical adoption and integration within established care pathways. |
| Software Companion Development | Enhances data integration and remote monitoring capabilities for patient management. |
| CE Marking Pathway Acceleration | Ensures compliance and broadens market reach across European healthcare systems. |
| Pediatric Device Miniaturization | Addresses unmet needs for smaller, less invasive monitoring systems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive understanding of the Intracranial Pressure (ICP) monitoring devices market. Primary interviews with neurosurgeons, intensivists, hospital procurement managers, and biomedical engineers provided direct insights. This primary research was validated against secondary sources including US FDA approval databases, CE marking registries, PMDA reports, and medical device company SEC filings. A bottom-up and top-down triangulation approach ensured robust data integrity.
Forecasting across the analysis window utilized an analytical framework that integrated historical market trends with projected growth drivers. Segmentation dimensions modeled included product type, technology, end user, clinical application, and regional healthcare infrastructure. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of historical performance and anticipated shifts in technology adoption. Key industry-specific forecast inputs included traumatic brain injury incidence rates and regulatory approval timelines for non-invasive devices.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory changes or major disruptions in global supply chains would require recalibration. Forecasts reflect assumptions regarding technological advancements and evolving healthcare policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Cardioscope Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Digital Impression System Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
Cyberknife Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
Global IVF Devices Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Conduction Vaporizers Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
United Kingdom Aesthetic Devices Market