
 Canada Aesthetic Devices Market | 2026-2036
Canada Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Aesthetic Devices Market Outlook
Premium-grade laser specifications is collapsing into the mid-market tier as manufacturers scale diode-array production and drive unit economics downward. Alma Lasers leverages its multi-wavelength platform architecture to sustain cross-selling across dermatology clinics and medical spas. Cutera Inc. differentiates through specialized vascular and pigmentation modules that occupy niche high-margin positions in major Canadian metropolitan markets.
Aesthetic devices comprise electromechanical and energy-delivery systems engineered to modify skin, adipose, or follicular tissue through controlled thermal, optical, or acoustic mechanisms, typically operating at wavelengths between 532 nm and 10,600 nm with pulse durations calibrated to target chromophore specificity. Their primary commercial purpose centers on elective cosmetic procedures performed outside traditional surgical settings. Laser systems anchor the installed base due to decade-long clinician familiarity and reimbursable adjacent applications, while radiofrequency machines represent the fastest-growing category as fractional and microneedling configurations expand body contouring indications. Injectable technology commands concentrated margin pools despite capital-light delivery, since neurotoxin and filler protocols require minimal equipment overhead yet generate recurring consumable revenue streams.
Health Canada oversees medical device licensing under the Medical Devices Regulations, while the PMRA governs pharmaceutical components in combination products such as toxin-based injectables, creating a dual-track compliance burden for manufacturers. Provincial regulatory variations across Ontario, Quebec, and British Columbia fragment reimbursement coding and clinic accreditation standards, forcing vendors to navigate jurisdiction-specific market access protocols. Stakeholders must monitor pending amendments to the Canadian Medical Devices Regulations that could reclassify certain energy-based systems from Class II to Class III, fundamentally altering clinical evidence requirements and timeline-to-market economics.
Market Dynamics
Diode-array manufacturing scale is collapsing premium laser specifications into mid-market price tiers, forcing vendors to defend margin through platform modularity rather than hardware premiumization.
Growth Catalysts
- Medical spa channel expansion:Outpatient aesthetic settings in Ontario and Quebec capture patient volume previously directed toward hospital-based dermatology departments.
- Radiofrequency platform versatility:Fractional and microneedling configurations extend body contouring indications beyond facial applications into abdomen and thigh protocols.
- Health Canada Class II pathway:Streamlined licensing for energy-based systems accelerates commercialization timelines relative to pharmaceutical-equivalent interventions.
Market Restraints
- Import compliance burden:Health Canada and PMRA dual-track oversight increases documentation costs for combination toxin-injectable devices.
- Provincial reimbursement fragmentation:Ontario, Quebec, and British Columbia maintain non-uniform clinic accreditation standards that complicate national rollout strategies.
- Consumable dependency:Recurring neurotoxin and filler purchases concentrate supplier power with three global pharmaceutical manufacturers.
Strategic Opportunities
- Western Canada penetration gap:British Columbia and Alberta clinic density remains below Ontario levels despite comparable disposable income profiles.
- Combination device convergence:Integrated radiofrequency-microneedle systems address multiple chromophores in single treatment sessions.
- Private-pay channel expansion:Direct-to-consumer financing platforms reduce upfront procedure cost barriers for millennial demographic segments.
Industry Challenges
- Laser technician certification delays:Provincial training hour requirements vary across Ontario, Quebec, and British Columbia, constraining workforce mobility.
- Legacy system integration friction:Clinic software stacks require custom API development to connect new energy-based devices with patient management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Aesthetic Devices Market |
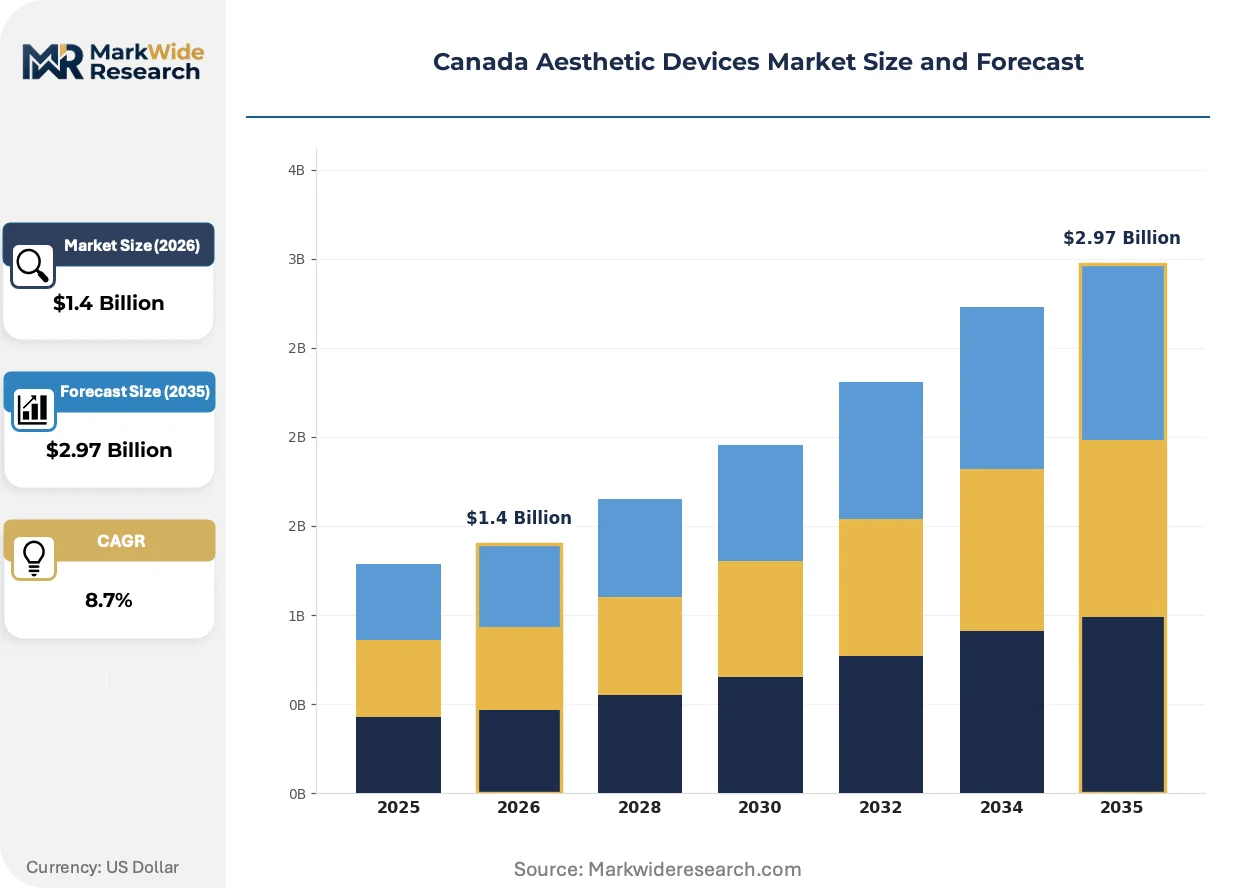
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Systems, Ultrasound Devices, Radiofrequency Machines, Light Therapy Devices End User: Dermatology Clinics, Aesthetic Clinics, Hospitals, Medical Spas Application: Skin Rejuvenation, Hair Removal, Body Contouring, Acne Treatment Technology: Non-Invasive, Minimally Invasive, Energy-Based, Injectable |
| Companies Covered | Allergan Aesthetics, Alma Lasers, Cutera Inc., Bausch Health, Cynosure, Lumenis, Merz Pharma, Venus Concept, Galderma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Aesthetic Devices Market Strategic Shifts
Platform architecture decisions now determine competitive survival more than single-device performance specifications, as buyers prioritize upgrade pathways over point solutions.
Portable diode laser systems is miniaturizing through chip-scale packaging advances that reduce cooling infrastructure requirements. Medical spas in Toronto and Montreal deploy these units for mobile pop-up services at events and corporate wellness programs. The form-factor reduction is compressing capital barriers to entry for independent aesthetic practitioners.
Pending amendments to the Canadian Medical Devices Regulations threaten reclassification of certain energy-based systems from Class II to Class III. This regulatory trajectory would triple clinical evidence requirements and extend timeline-to-market economics by eighteen to twenty-four months. Vendors with existing Class III portfolios in vascular and pigmentation modules possess structural advantage.
Service unbundling is fragmenting traditional equipment-plus-consumable contracts into separate financing arrangements. Clinics in Vancouver and Calgary increasingly lease hardware while purchasing disposables through third-party distributors. This procurement model shift concentrates price negotiation leverage with group purchasing organizations representing multi-site medical spa chains.
Canada Aesthetic Devices Market Segmentation
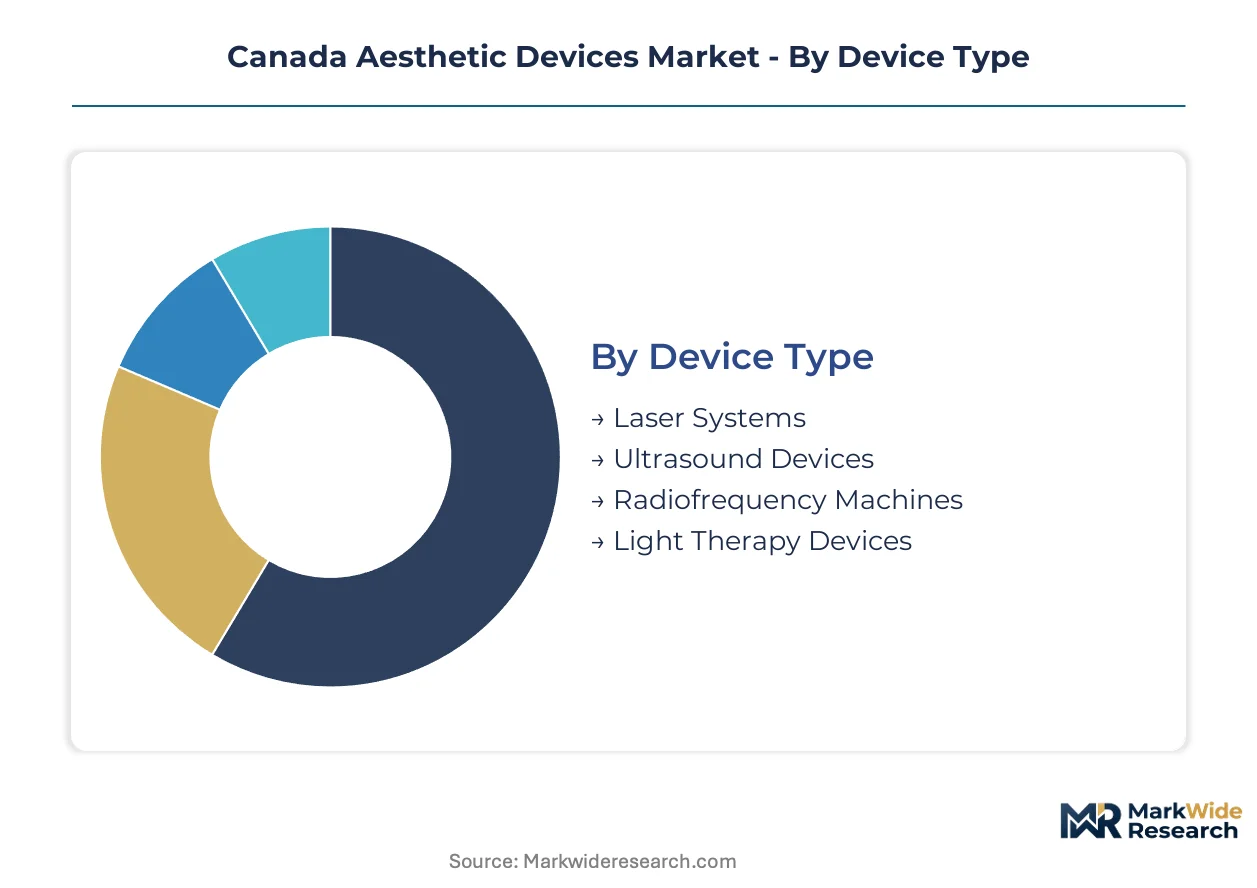
Device categorization in the Canadian aesthetic market reveals distinct margin architectures tied to consumable dependencies and regulatory pathways. Understanding where revenue concentrates across these dimensions determines vendor positioning and channel investment priorities.
Device Type:
Margin pools concentrate in platforms with recurring cartridge revenue and multi-indication versatility rather than single-purpose hardware.
- Laser Systems:These electromechanical platforms operate across 532 nm to 10,600 nm wavelengths with pulse-duration calibration for chromophore specificity. Ontario and Quebec dermatology clinics drive replacement demand as decade-old installed bases reach end-of-life. The dominant share belongs to Laser Systems, while Radiofrequency Machines is closing the gap fastest.
- Radiofrequency Machines:Fractional and microneedling configurations extend body contouring beyond facial applications into abdomen and thigh protocols. Medical spas in Toronto and Montreal deploy these for non-ablative tightening with minimal downtime requirements.
- Ultrasound Devices:Focused ultrasound systems target adipose tissue at specific depths without surface thermal damage.
- Light Therapy Devices:LED and IPL platforms occupy entry-level price tiers with lower capital barriers for independent practitioners.
Hardware margins compress as diode-array manufacturing scales, forcing vendors toward platform modularity strategies.
End User:
Channel economics diverge sharply between institutional procurement and private-pay outpatient settings.
- Medical Spas:Outpatient aesthetic settings in Ontario and Quebec capture patient volume previously directed toward hospital-based dermatology departments. These facilities prioritize lease-friendly hardware with minimal technician certification requirements.
- Dermatology Clinics:Physician-supervised settings demand reimbursable adjacent applications and documented clinical evidence for Health Canada Class II pathways.
- Aesthetic Clinics:Standalone facilities concentrate in Vancouver and Calgary with procedure-mix tilted toward injectable protocols.
- Hospitals:Academic medical centers maintain limited aesthetic service lines with capital allocation favoring multi-use surgical platforms.
Medical Spas command the steepest volume expansion trajectory, while Dermatology Clinics retain pricing power through clinical authority positioning.
Application:
Procedure frequency and price per session create divergent revenue concentration patterns across treatment categories.
- Skin Rejuvenation:Fractional laser and radiofrequency protocols address photodamage and texture concerns across broad patient demographics. Ontario urban markets show particular density of combination-device deployments targeting multiple chromophores in single sessions.
- Hair Removal:Diode laser systems dominate this high-frequency category with wavelength optimization for Fitzpatrick skin type diversity in metropolitan Canadian populations.
- Body Contouring:Non-invasive fat reduction and skin tightening protocols extend device utilization beyond traditional facial applications.
- Acne Treatment:Light therapy and targeted energy delivery address inflammatory and scarring presentations with lower per-session economics.
Skin Rejuvenation generates the highest absolute revenue pool, though Hair Removal sustains superior device utilization rates through repeat visit frequency.
Technology:
Regulatory classification and capital intensity separate technology tiers with fundamentally different commercial models.
- Injectable:Neurotoxin and filler protocols require minimal equipment overhead yet generate recurring consumable revenue streams concentrated with three global pharmaceutical manufacturers. Health Canada and PMRA dual-track oversight increases documentation costs for combination toxin-injectable devices.
- Energy-Based:Laser, radiofrequency, and ultrasound platforms operate under streamlined Class II licensing with clinical evidence requirements below pharmaceutical-equivalent interventions.
- Non-Invasive:Surface-level light and thermal modalities occupy the lowest capital tier with minimal technician training barriers.
- Minimally Invasive:Microneedle and subdermal energy delivery systems bridge efficacy and recovery time considerations for patient segments seeking measurable results without surgical intervention.
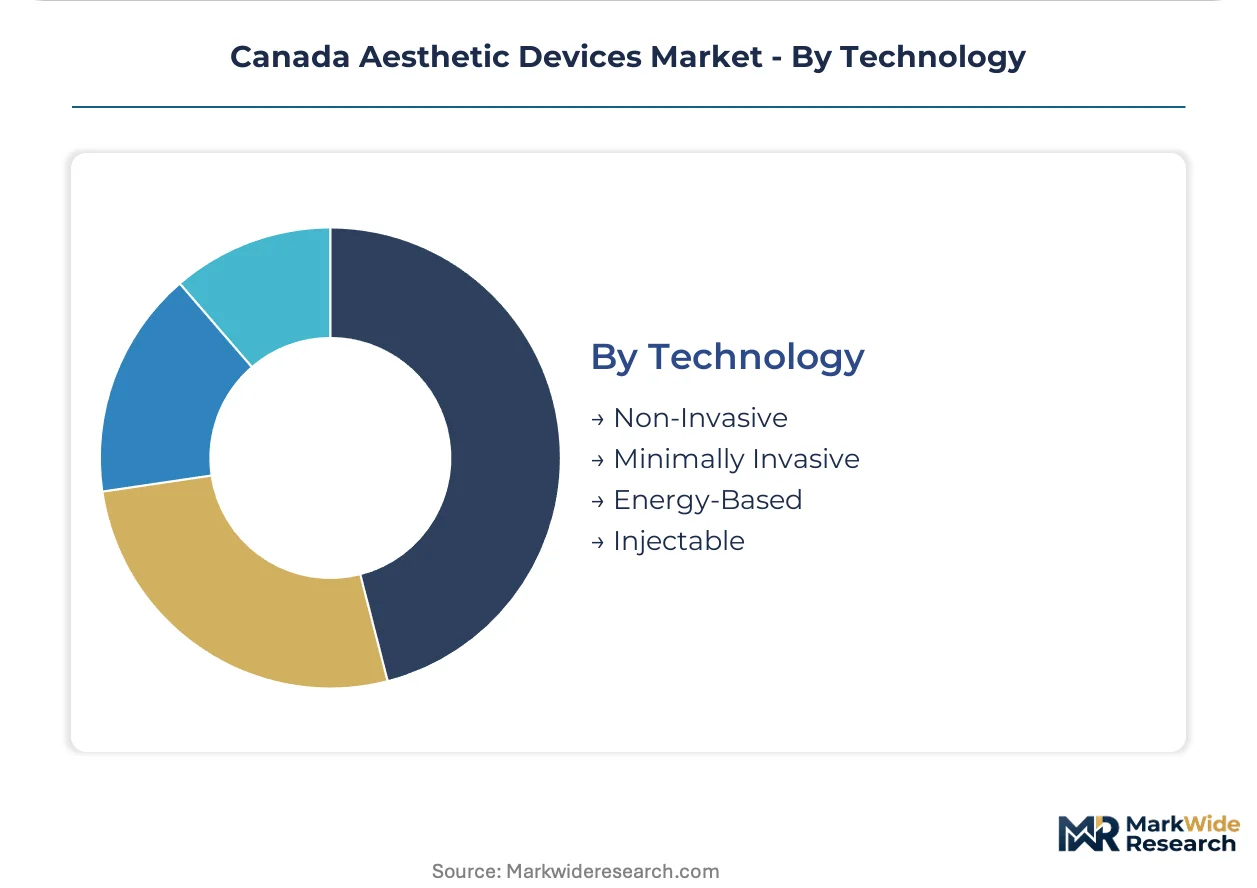
Injectable technology captures concentrated margin pools despite capital-light delivery, while Energy-Based systems anchor the installed base through platform versatility and upgrade pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's aesthetic devices market relies heavily on import flows from US and Israeli manufacturers, with domestic distribution networks concentrated in major metropolitan corridors. Health Canada licensing requirements create regulatory friction that shapes regional market access patterns.
Ontario
Toronto's medical spa density exceeds any other Canadian city, driven by concentrated disposable income and proximity to US border logistics. Health Canada maintains its headquarters in Ottawa, streamlining Class II device applications for Ontario-based distributors. The Greater Toronto Area anchors national procurement decisions for multi-site clinic chains.
Quebec
Montreal's francophone consumer base demands French-language training protocols and device interfaces, creating localization barriers for foreign vendors. The province's college of physicians imposes distinct laser technician certification requirements separate from Ontario standards. Laval and Quebec City form secondary clusters with growing medical spa penetration.
British Columbia
Vancouver's Pacific trade position enables direct Asian supply relationships that bypass central Canadian distribution hubs. The province's regulatory alignment with US FDA precedents accelerates device approval timelines relative to eastern provinces. Victoria and Kelowna sustain boutique clinic concentrations serving high-net-worth retirees.
Alberta
Calgary's energy-sector wealth sustains premium procedure pricing despite lower overall clinic density than Ontario. The province's private healthcare delivery tradition supports direct-pay aesthetic models with minimal insurance intermediation. Edmonton medical spas target younger demographics through corporate wellness partnerships.
Canada Aesthetic Devices Market Competitive Environment
Listed leaders compete with private specialists across platform architecture and service bundling dimensions. The vendor base clusters around three tiers: multinational device manufacturers with Class III regulatory expertise, mid-market platform specialists emphasizing lease economics, and consumable-focused pharmaceutical houses with minimal capital equipment exposure. Strategic moves concentrate on platform modularity investments and provincial distribution partnerships that navigate reimbursement fragmentation.
Within the multinational tier, Allergan Aesthetics and Galderma exemplify pharmaceutical-origin players that anchor injectable revenue streams despite minimal hardware footprints. Alma Lasers, referenced in market documentation, occupies a position among Israeli-origin platform vendors with multi-wavelength architectures. These three represent divergent archetypes: toxin-dominant consumable models, energy-based capital equipment, and hybrid combination-device strategies.
| Leading Market Players |
|---|
| Allergan Aesthetics |
| Alma Lasers |
| Cutera Inc. |
| Bausch Health |
| Cynosure |
| Lumenis |
| Merz Pharma |
| Venus Concept |
| Galderma |
| Others |
Value Chain & Pricing Dynamics
Equipment-plus-consumable contracts lock in multi-year revenue visibility for vendors while compressing upfront capital barriers for Ontario and Quebec medical spas seeking Health Canada Class II device access. This bundled structure concentrates price negotiation leverage with group purchasing organizations representing multi-site chains.
Pricing Analysis
Medical spa procurement teams anchor three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by Health Canada certification tier and after-sales service bundling. Cost compression in diode-array laser systems is intensifying because Israeli and US manufacturers scale production, forcing mid-market vendors toward lease-friendly hardware economics. Independent aesthetic practitioners in Vancouver and Calgary exhibit highest price sensitivity, while academic medical centers retain lowest sensitivity due to capital allocation flexibility.
Supply Chain Analysis
Israel and the United States anchor energy-based device manufacturing, with Taiwan and South Korea supplying precision optical components and semiconductor controls. Canadian distribution draws from US border logistics hubs and direct Asian supply relationships through Vancouver's Pacific trade position, creating single-source vulnerability for specialized vascular and pigmentation modules. Distribution runs through domestic distributors concentrated in Toronto and Montreal, with provincial regulatory variations fragmenting national rollout strategies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where Health Canada Class II pathway expertise and existing clinical evidence portfolios create switching costs that protect incumbent positions.
For Market Incumbents: Consolidate platform modularity investments to defend against diode-array price erosion, while deepening Health Canada relationships ahead of pending Class III reclassification amendments. Acquire or partner with Alberta and British Columbia distributors to close western penetration gaps before mid-market specialists establish provincial footholds. For New Entrants and Emerging Players: Lead with portable diode laser systems targeting mobile pop-up service demand in Toronto and Montreal corporate wellness channels, where minimal technician certification requirements lower workforce barriers. Pursue lease-only hardware models with third-party disposable financing to circumvent group purchasing organization concentration. For Investors and Strategic Acquirers: Capital is best deployed toward Israeli-origin platform vendors with existing Class III portfolios in vascular and pigmentation modules, as regulatory trajectory favors pre-cleared clinical evidence. Watch Health Canada amendment timelines as inflection indicator for timeline-to-market economics shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Pre-Submission | Positions vendors ahead of pending energy-based system reclassification amendments. |
| Western Canada Distribution Partnership | Captures underpenetrated British Columbia and Alberta clinic density relative to Ontario. |
| Combination Device Platform Development | Addresses multiple chromophores through integrated radiofrequency-microneedle architectures. |
| Medical Spa GPO Contract Negotiation | Secures multi-site chain volume commitments amid procurement model fragmentation. |
| French Localization Investment | Unlocks Quebec market access through college of physicians-aligned training protocols. |
Study Parameters
A standing panel of biomedical engineers, medical spa operations directors, Health Canada regulatory consultants, and hospital purchasing committee members provided ongoing calibration across primary interview rounds, with secondary validation against Health Canada device licensing databases, provincial college of physician certification standards, and GPO contract disclosure records. Bottom-up installed base modeling and top-down provincial expenditure estimates were triangulated to anchor volume projections.
Cross-checking against US FDA 510(k) clearance timelines and Israeli export shipment records validated analytical consistency across the projection horizon. Segmentation dimensions modeled include device type, end-user channel, application category, and provincial regulatory cluster, with CAGRs derived from replacement cycle analysis and medical spa expansion trajectories. Forecast inputs incorporated diode-array manufacturing scale curves and pending Canadian Medical Devices Regulations amendment probability assessments.
The analysis sits within stated boundaries; outcomes outside Health Canada regulatory trajectory assumptions or provincial reimbursement harmonization would require recalibration. Forecasts reflect documented assumptions regarding Class II pathway continuity and medical spa channel growth sustainability. Recalibration cycles align with material shifts in Health Canada classification amendments or provincial technician certification standard changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Eye Massage Device Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Morcellators Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Brazil Respiratory Devices Market