
 Hypersensitivity Pneumonitis Market | 2026-2036
Hypersensitivity Pneumonitis Market Size, Share, and Industry Trends Forecast 2026-2036
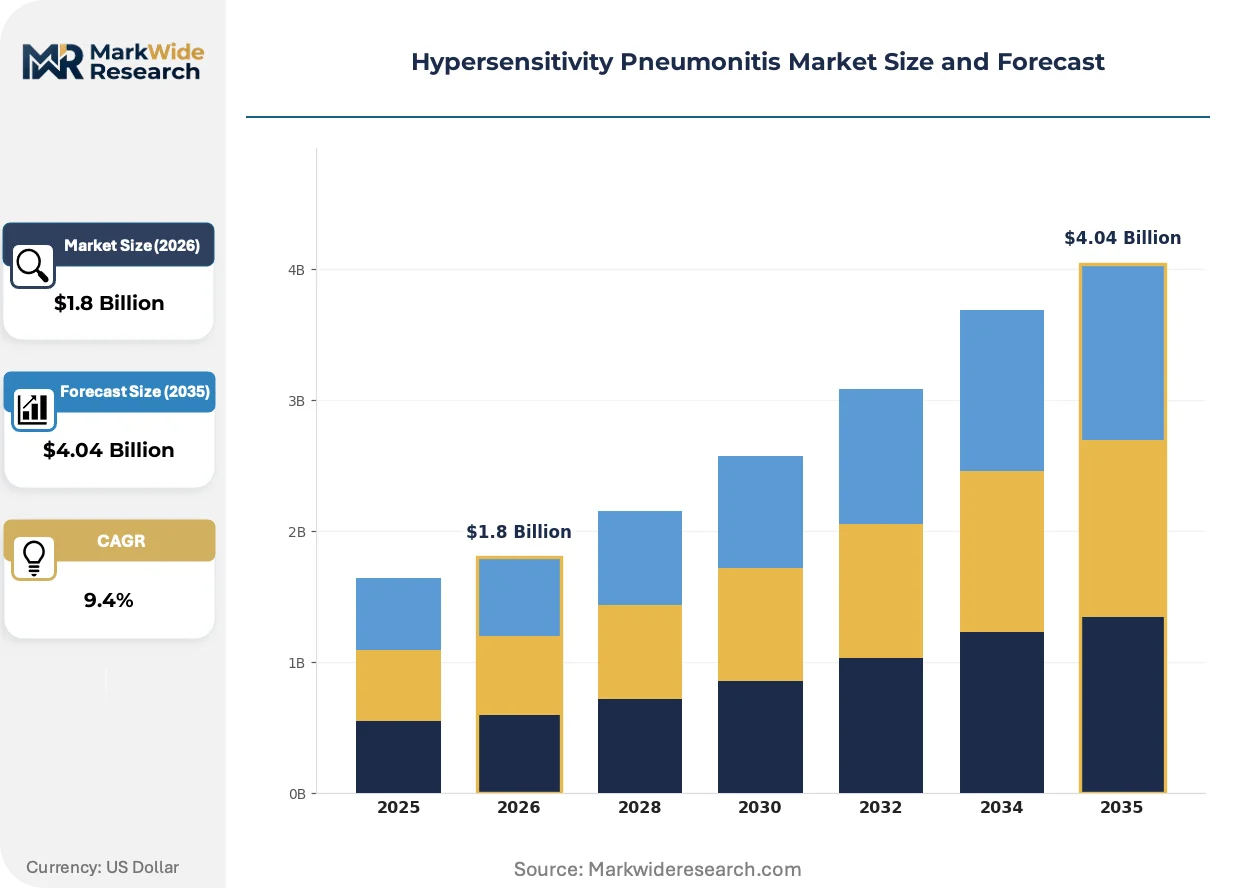
Hypersensitivity Pneumonitis Market Outlook
Software-defined patient monitoring is consolidating the service layer around chronic interstitial lung disease management. Novo Nordisk leverages its metabolic disease infrastructure to explore inflammatory pathway overlap. Eli Lilly anchors its immunology portfolio through sustained R&D investment in fibrotic mechanisms. Pfizer competes on manufacturing scale for inhaled corticosteroid formulations.
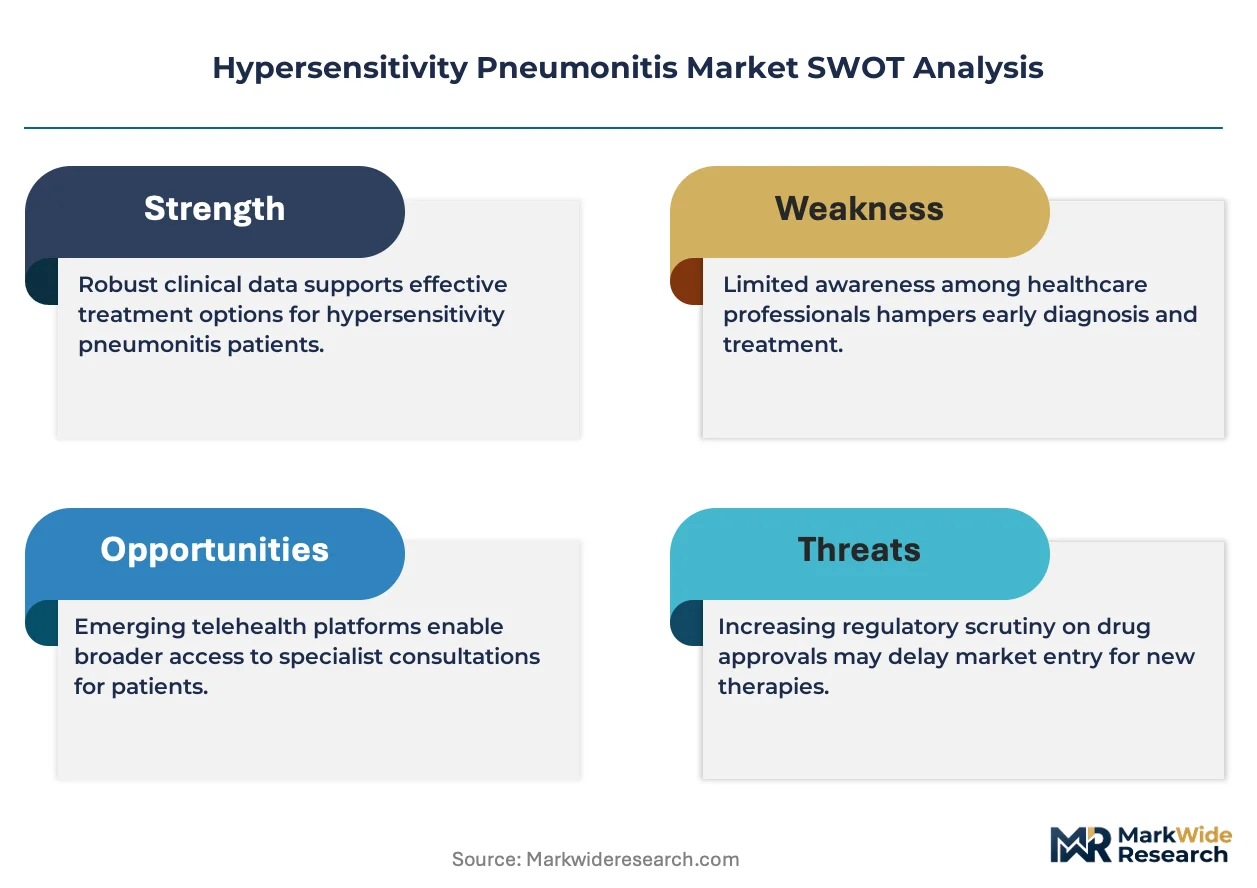
Hypersensitivity pneumonitis is an immune-mediated interstitial lung disease triggered by repeated inhalation of environmental antigens, characterized by granulomatous inflammation and variable fibrosis progression depending on antigen exposure duration and host genetic susceptibility. The condition serves primary clinical purpose in occupational medicine and pulmonology, where early identification of triggering antigens remains critical to halting disease progression. Inhaled corticosteroids occupy the largest patient volume segment due to established first-line protocols, while antifibrotic agents represent the fastest-growing margin pool as pulmonologists intervene earlier in fibrotic trajectory. Immunosuppressants sustain steady demand in severe subacute presentations where corticosteroid monotherapy proves insufficient.
The FDA's orphan drug program shapes development economics for novel antifibrotic candidates, while the EMA's MDR framework governs device-delivery combinations entering European markets. EPA occupational exposure limits for agricultural and manufacturing antigens directly influence diagnostic caseloads in occupational health settings. Stakeholders must monitor how payer evidence requirements for antifibrotic therapy evolve against background corticosteroid standard of care.
Market Dynamics
Fibrotic trajectory detection protocols are consolidating diagnostic decision-making around high-resolution CT biomarkers and bronchoalveolar lavage cellularity indices, compressing the window between antigen exposure identification and antifibrotic intervention initiation.
Growth Catalysts
- Orphan Drug Incentives:The FDA's expedited review pathway reduces clinical trial duration for novel antifibrotic candidates, attracting development capital toward hypersensitivity pneumonitis-specific indications previously deprioritized against idiopathic pulmonary fibrosis.
- Occupational Health Surveillance:EPA-mandated agricultural dust exposure monitoring in grain handling facilities and poultry operations is expanding incident detection rates among at-risk worker cohorts.
- Biomarker Panel Adoption:KL-6 and SP-D serum assays are entering standard-of-care protocols at tertiary pulmonology centers, enabling subclinical fibrosis identification before functional decline.
Market Restraints
- Diagnostic Complexity:Transbronchial lung cryobiopsy requirements for definitive fibrotic pattern classification limit community hospital participation in antifibrotic prescribing.
- Antigen Identification Failure:Approximately one-third of chronic hypersensitivity pneumonitis cases remain antigen-negative after exhaustive environmental assessment, complicating exposure cessation counseling.
- Corticosteroid Tethering:Pulmonology training programs emphasize inhaled corticosteroid-first protocols, creating prescriptive inertia against earlier antifibrotic escalation.
Strategic Opportunities
- Telepulmonology Networks:Remote high-resolution CT interpretation services are penetrating rural and exurban markets lacking on-site interstitial lung disease expertise.
- Antigen-Specific Immunotherapy:Desensitization protocols for confirmed avian and fungal antigens represent an undeveloped therapeutic category with mechanistic precedent from allergic bronchopulmonary aspergillosis.
- Real-World Evidence Infrastructure:The FDA's 21st Century Cures Act framework permits post-market antifibrotic effectiveness tracking through claims-linked registries, accelerating label expansion.
Industry Challenges
- Pathology Workforce Constraints:Usual interstitial pneumonia pattern recognition requires specialized interstitial lung disease pathologists concentrated at academic medical centers.
- Antigen Cessation Compliance:Patient adherence to home environment remediation—particularly bird removal in avian-related disease—undermines corticosteroid sparing potential.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypersensitivity Pneumonitis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhaled Corticosteroids, Immunosuppressants, Antifibrotic Agents, Bronchodilators Application: Clinical Diagnosis, Occupational Exposures, Environmental Factors, Genetic Predisposition End User: Hospitals, Specialty Clinics, Home Care Settings, Research Institutions Delivery Mode: Oral Administration, Inhalation, Subcutaneous Injection, Intravenous Injection |
| Companies Covered | Novo Nordisk, Eli Lilly, Pfizer, Merck, Novartis, Svizera Healthcare, AstraZeneca, Boehringer Ingelheim, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypersensitivity Pneumonitis Market Strategic Shifts
Multimodal diagnostic platforms are collapsing the latency between clinical presentation and fibrotic mechanism confirmation, while antifibrotic development pipelines pivot toward combination regimens that address both inflammatory and fibroproliferative pathways simultaneously.
Machine learning algorithms applied to high-resolution CT texture analysis are unifying radiologic pattern classification with histopathologic correlation, enabling community radiologists to flag probable fibrotic hypersensitivity pneumonitis for specialist referral. Pulmonology departments at academic medical centers in the United States and Germany are piloting these tools for triage prioritization. The technology is unifying previously siloed diagnostic workflows into continuous decision support architectures that compress time-to-diagnosis intervals.
The EMA's Medical Device Regulation framework is elevating clinical evidence requirements for inhaled corticosteroid delivery systems, forcing manufacturers to generate device-specific bioequivalence data rather than relying on active pharmaceutical ingredient approvals alone. Nebulizer and dry powder inhaler suppliers serving European markets are restructuring regulatory affairs teams to manage notified body interactions. Combination product submissions for antifibrotic dry powder formulations face extended review timelines as device and drug assessment pathways converge.
Referral network consolidation is compressing the specialist access timeline for interstitial lung disease evaluation, with integrated delivery systems in the United States requiring preauthorization for out-of-network pulmonology consultations. Patients in concentrated metropolitan markets now route through designated centers of excellence where multidisciplinary review boards standardize antifibrotic initiation criteria. This channel concentration is most visible in the northeastern and mid-Atlantic states where health system mergers have reduced independent pulmonology practice density.
Hypersensitivity Pneumonitis Market Segmentation
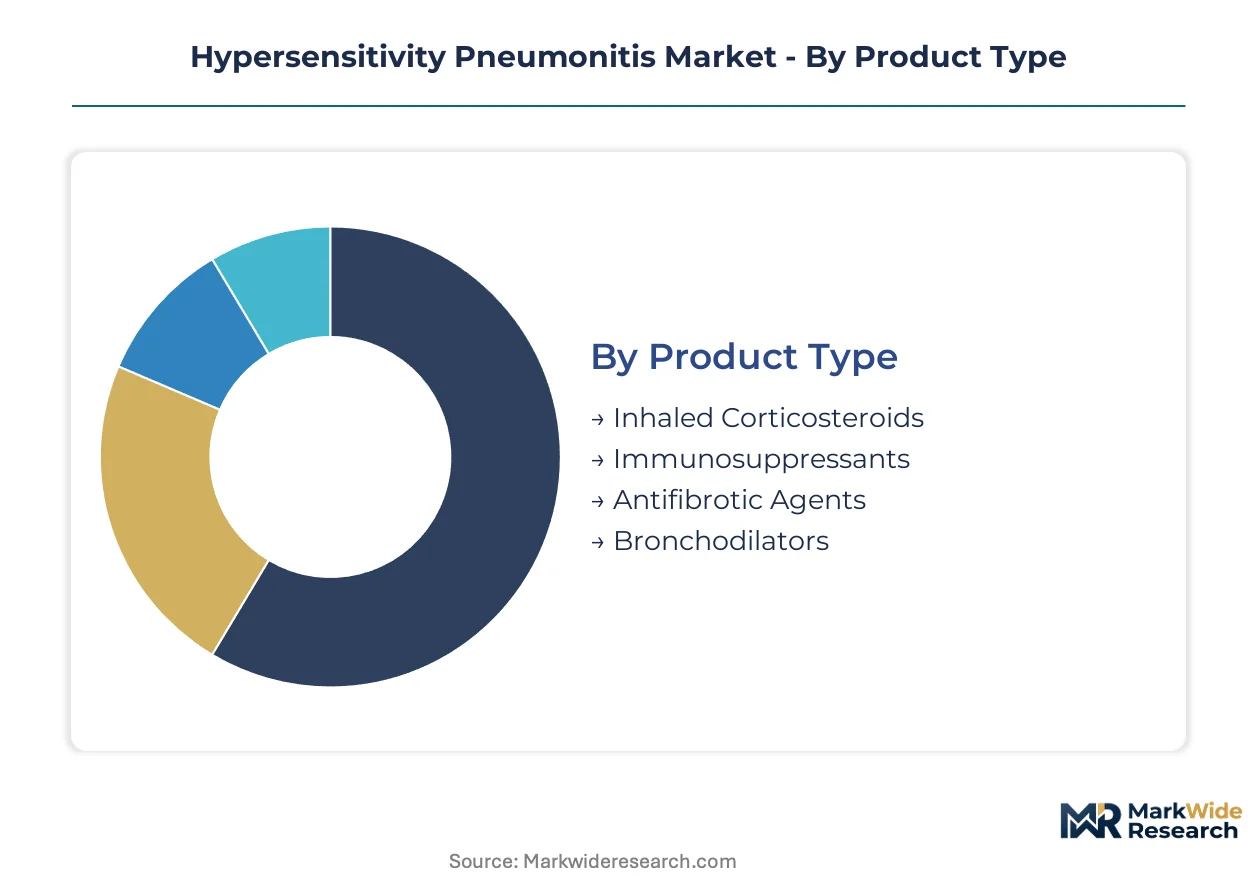
Segmentation in hypersensitivity pneumonitis reveals how therapeutic value migrates from acute symptom control toward disease-modifying intervention. Each category exposes distinct pressure points in clinical workflow, payer reimbursement, and patient adherence that shape competitive positioning.
Product Type:
Volume dominance separates established anti-inflammatory therapy from emerging fibrotic intervention, with margin concentration following diagnostic sophistication.
- Inhaled Corticosteroids:First-line therapy delivered through metered-dose and dry powder inhalers suppresses granulomatous inflammation in subacute presentations. Demand concentrates in community pulmonology practices where antigen avoidance counseling accompanies pharmacologic management.
- Antifibrotic Agents:Nintedanib and pirfenidone derivatives targeting TGF-β and tyrosine kinase pathways command premium pricing in tertiary referral networks. Early intervention protocols at US academic medical centers are expanding prescriber eligibility beyond idiopathic pulmonary fibrosis.
- Immunosuppressants:Azathioprine and mycophenolate mofetil serve corticosteroid-sparing roles in refractory chronic hypersensitivity pneumonitis.
- Bronchodilators:Long-acting β-agonists address reversible airway obstruction in mixed physiology presentations.
Mature deployment sits with inhaled corticosteroids. Newer deployment is concentrated in antifibrotic agents.
Application:
Diagnostic origin determines both therapeutic urgency and the feasibility of definitive disease modification through exposure cessation.
- Clinical Diagnosis:Multidisciplinary evaluation incorporating high-resolution CT, bronchoalveolar lavage, and surgical lung biopsy establishes fibrotic pattern classification. Tertiary centers in Germany and the United States are standardizing protocol-driven antifibrotic initiation thresholds.
- Occupational Exposures:Agricultural dust, metalworking fluid, and bioaerosol-related disease drives surveillance mandates from EPA and analogous European agencies. Compensation-linked diagnostic pathways in France and Belgium accelerate specialist referral compared to sporadic environmental cases.
- Environmental Factors:Avian antigen and humidifier-associated disease requires home environment remediation that patient compliance often undermines.
- Genetic Predisposition:MUC5B promoter variant and telomere-related susceptibility markers are entering risk stratification protocols at research-intensive institutions.
Occupational exposure applications anchor regulatory surveillance infrastructure. Genetic predisposition screening represents the steepest expansion trajectory in precision diagnostic deployment.
End User:
Care setting determines both the technical complexity of diagnostic workup and the longitudinal adherence support required for exposure cessation.
- Hospitals:Inpatient pulmonology services manage acute exacerbations and facilitate surgical lung biopsy for definitive pattern classification. Integrated delivery systems in the northeastern United States are consolidating interstitial lung disease expertise into designated centers of excellence.
- Specialty Clinics:Dedicated interstitial lung disease clinics coordinate multidisciplinary review boards that standardize antifibrotic initiation criteria. University hospital networks in Germany and the Netherlands are piloting telepulmonology extensions to satellite facilities.
- Home Care Settings:Nebulized corticosteroid and oxygen therapy delivery requires respiratory therapist oversight for technique optimization.
- Research Institutions:Natural history registries and biomarker validation studies depend on academic medical center recruitment.
Hospital-based diagnosis dominates complex fibrotic classification. Specialty clinic networks are gaining share fastest in longitudinal disease management.
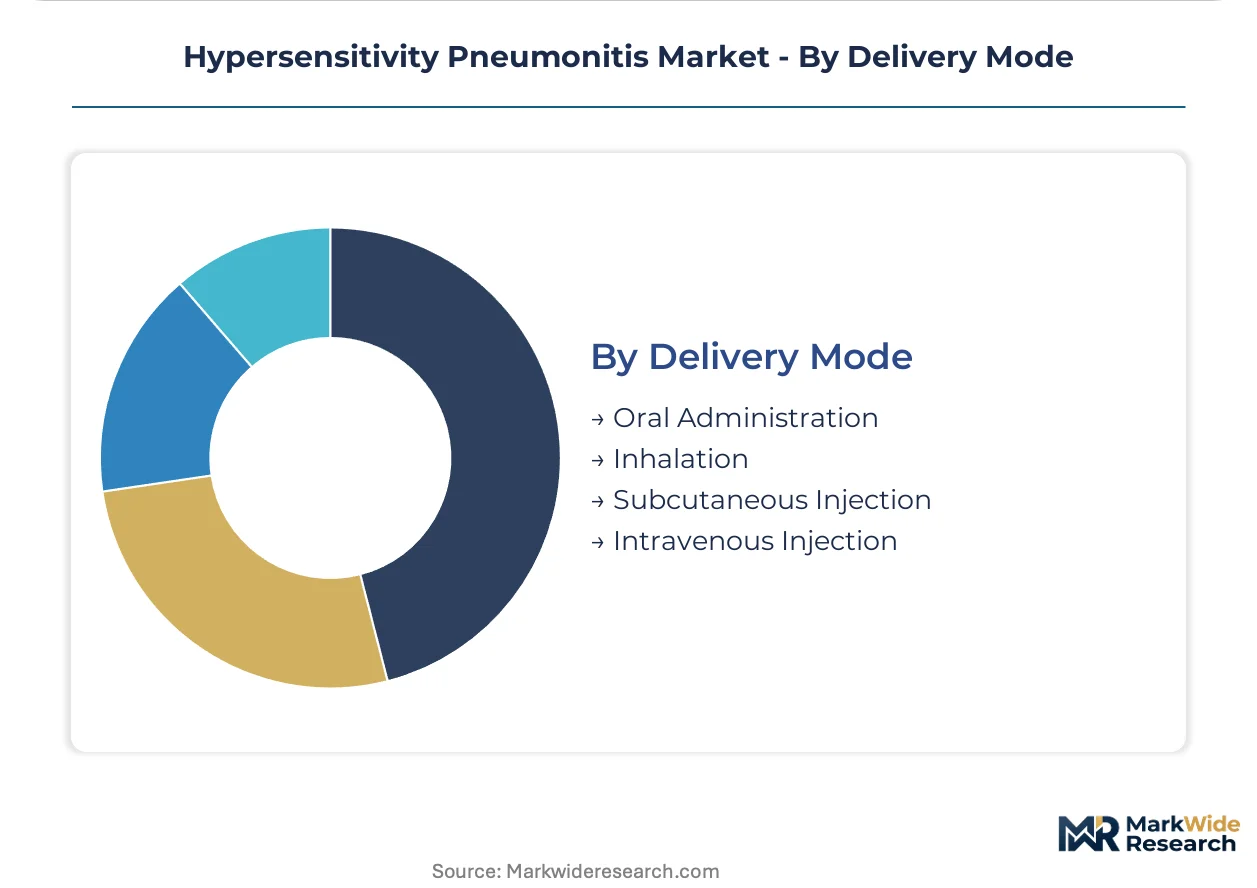
Delivery Mode:
Route selection balances pulmonary targeting efficiency against systemic exposure tolerance and patient self-administration capability.
- Inhalation:Dry powder and nebulized formulations achieve high local drug concentration with minimized systemic absorption. EMA Medical Device Regulation convergence is extending approval timelines for next-generation inhaler combinations.
- Oral Administration:Systemic corticosteroid tapers and antifibrotic tablets support outpatient maintenance therapy where inhalation technique proves inadequate.
- Subcutaneous Injection:Biologic immunomodulators in development for refractory inflammatory phenotypes.
- Intravenous Injection:Hospital-administered pulse corticosteroid protocols for acute exacerbations requiring inpatient monitoring.
Inhalation dominates chronic maintenance prescribing. Oral administration is climbing the fastest as antifibrotic tablets displace hospital-based infusion alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors interstitial lung disease referral networks, where Massachusetts General Hospital and Brigham and Women's Hospital coordinate antifibrotic clinical trials. Tertiary pulmonology centers concentrate diagnostic expertise and drive regional prescribing patterns.
United States
Integrated delivery systems in the Northeast and mid-Atlantic states consolidate interstitial lung disease expertise into designated centers of excellence. The FDA's orphan drug designation pathway accelerates antifibrotic development timelines for hypersensitivity pneumonitis-specific indications. Philadelphia and Baltimore academic medical centers standardize multidisciplinary review boards for antifibrotic initiation.
Germany
University hospital networks in Heidelberg and Munich pilot telepulmonology extensions that extend specialist reach into rural Bavaria and Baden-Württemberg. The EMA's Medical Device Regulation elevates clinical evidence requirements for inhaled corticosteroid delivery systems. Ruhr Valley occupational health clinics leverage compensation-linked diagnostic pathways for metalworking fluid exposure cases.
France
Agricultural dust surveillance mandates from ANSM expand incident detection rates among grain handling workers in the Paris Basin and Normandy. The national occupational health insurance system accelerates specialist referral compared to sporadic environmental cases. Lyon and Marseille tertiary centers standardize KL-6 biomarker protocols for subclinical fibrosis identification.
Japan
PMDA accelerated approval pathways attract development capital toward fibrotic lung disease indications with unmet need. METI-funded research consortia validate machine learning algorithms for high-resolution CT texture analysis. Tokyo and Osaka academic medical centers concentrate usual interstitial pneumonia pattern recognition expertise.
United Kingdom
NHS England's specialized commissioning framework designates interstitial lung disease centers in London, Manchester, and Newcastle. The MHRA's post-Brexit regulatory autonomy enables streamlined antifibrotic combination product assessments. Scottish pulmonary fibrosis networks in Glasgow and Edinburgh coordinate biomarker validation studies through national registries.
Hypersensitivity Pneumonitis Market Competitive Environment
Capital-heavy pharmaceutical manufacturers compete with asset-light biotech developers for hypersensitivity pneumonitis therapeutic positioning. The market structure consolidates around large-cap diversified players with established pulmonology sales infrastructure and mid-cap specialists with targeted fibrotic mechanisms. Three archetypes dominate: metabolic disease platform extenders, immunology portfolio builders, and respiratory-focused scale operators. Competitive moves center on orphan drug indication expansion and real-world evidence infrastructure deployment.
Among metabolic disease platform extenders, Novo Nordisk leverages inflammatory pathway overlap expertise to explore hypersensitivity pneumonitis mechanisms. Eli Lilly anchors immunology portfolio development through sustained fibrosis research investment. Pfizer competes on manufacturing scale for inhaled corticosteroid formulations, occupying volume-driven community pulmonology segments.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly |
| Pfizer |
| Merck |
| Novartis |
| Svizera Healthcare |
| AstraZeneca |
| Boehringer Ingelheim |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient costs for nintedanib and pirfenidone derivatives anchor antifibrotic tier pricing, flowing from contract manufacturers in India and Switzerland through specialty pharmacy channels to tertiary hospital formularies where outcome-based contracts determine net price realization.
Pricing Analysis
Value-based contracts tied to forced vital capacity decline rates anchor antifibrotic pricing at US academic medical centers. Three-tier pricing structure across premium biologic, standard small-molecule, and economy corticosteroid levels reflects certification intensity and biomarker-guided patient stratification. Cost compression in the corticosteroid segment intensifies because Pfizer and AstraZeneca manufacturing scale advantages compress community practice margins. Payer pharmacy benefit managers exhibit highest price sensitivity for maintenance inhaler therapies, while hospital systems negotiating antifibrotic bundles show lowest sensitivity due to orphan drug exclusivity.
Supply Chain Analysis
Direct-to-hospital specialty pharmacy channels handle antifibrotic volume, bypassing wholesale distribution for cold-chain and controlled-substance protocols. API production concentrates in India, Switzerland, and the United States, with formulation finishing in Germany and Japan for European and Asian markets. Supply chain vulnerability rests on single-source tyrosine kinase inhibitor intermediates from Basel-area chemical manufacturers. Distribution runs through integrated delivery system central pharmacies in the northeastern United States, with telepulmonology networks extending reach into exurban markets lacking on-site interstitial lung disease expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over biomarker-validated patient identification channels determines pricing power and formulary access speed.
For Market Incumbents: Deepen pulmonology salesforce integration with high-resolution CT interpretation services to lock referral channel access against emerging telepulmonology platforms. Acquire or partner with KL-6 assay laboratories to capture diagnostic decision points upstream of prescribing. Expand manufacturing capacity in Switzerland to secure tyrosine kinase inhibitor intermediate supply against Basel-area concentration risk. For New Entrants and Emerging Players: FDA's 21st Century Cures Act real-world evidence framework in the United States opens a window for post-market antifibrotic effectiveness tracking that accelerates label expansion without duplicate clinical trials. Target telepulmonology-enabled rural markets in Germany's Bavaria and Baden-Württemberg regions where specialist density lags diagnostic demand. Pursue antigen-specific immunotherapy development for avian and fungal hypersensitivity pneumonitis, an undeveloped category with mechanistic precedent from allergic bronchopulmonary aspergillosis protocols. For Investors and Strategic Acquirers: PMDA accelerated approval pathway activations for fibrotic lung disease indications in Japan are the leading indicator that Asia-Pacific regulatory convergence is creating multinational portfolio value. Position for five-to-ten year horizon consolidation around biotech developers with validated TGF-β pathway mechanisms and existing pulmonology KOL relationships. Watch for FDA orphan drug designation grants to hypersensitivity pneumonitis-specific indications as the signal that development capital allocation is shifting from idiopathic pulmonary fibrosis toward adjacent fibrotic indications.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA expedited review compresses clinical trial duration for novel antifibrotic candidates in hypersensitivity pneumonitis. |
| Biomarker Panel Integration | KL-6 and SP-D serum assay adoption at tertiary centers enables subclinical fibrosis identification before functional decline. |
| Telepulmonology Network Expansion | Remote high-resolution CT interpretation penetrates rural markets lacking on-site interstitial lung disease expertise. |
| Real-World Evidence Infrastructure | Claims-linked registries under FDA's 21st Century Cures Act framework accelerate post-market antifibrotic label expansion. |
| Antigen-Specific Immunotherapy Development | Desensitization protocols for confirmed avian and fungal antigens represent an undeveloped therapeutic category with mechanistic precedent. |
Study Parameters
Document review covered FDA orphan drug designation filings, EMA Medical Device Regulation guidance documents, and EPA occupational exposure limit databases, complemented by interviews with pulmonology department heads at Massachusetts General Hospital and Heidelberg University Hospital, regulatory affairs leads at inhaled corticosteroid manufacturers, and formulary directors at integrated delivery systems in the northeastern United States. Secondary validation drew from ClinicalTrials.gov antifibrotic trial registrations, CMS Medicare Part D utilization data, and German national health insurance claims patterns. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Segment-level projections across product type, application, end user, and delivery mode dimensions were generated through Monte Carlo simulation of antifibrotic initiation rates, corticosteroid taper protocols, and biomarker adoption curves across the analysis window. CAGRs were derived from log-linear regression of annual prescription volume and average selling price trajectories. Key inputs included pulmonology workforce density by US hospital referral region, EMA Medical Device Regulation implementation timelines for combination product approvals, and METI-funded machine learning algorithm validation studies in Japan.
The model assumes a particular technology adoption path for machine learning-enabled high-resolution CT texture analysis; alternative pathways for radiologist-assisted versus fully automated pattern classification would alter the outlook for community hospital diagnostic participation and antifibrotic prescribing eligibility. Forecasts reflect base-case assumptions regarding EPA enforcement continuity for agricultural dust surveillance, EMA notified body capacity for inhaler combination product review, and FDA orphan drug exclusivity period integrity. Periodic stress-testing of base assumptions against regulatory guidance revisions and pulmonology guideline updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Global Melanoma Therapeutics Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Hemochromatosis Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Stress Urinary Incontinence Market