
 Jet Nebulizers Market | 2026-2036
Jet Nebulizers Market Size, Share, and Industry Trends Forecast 2026-2036
Jet Nebulizers Market Foresight
Polycarbonate housings are rebalancing jet nebulizer economics as manufacturers trade metal assemblies for lighter, lower-cost polymer chassis. Omron Corporation leverages its Japanese manufacturing footprint to sustain precision compressor production at scale. PARI Respiratory Equipment, Inc. anchors its position through German-engineered medication delivery systems with pediatric specialization. Koninklijke Philips N.V. competes across hospital and home channels with integrated respiratory care portfolios.
A jet nebulizer converts liquid medication into respirable aerosol particles through compressed air driven across a baffle, typically producing droplets in the one-to-five-micrometer range for deep lung deposition. Portable jet nebulizers command expanding share as patients transition acute respiratory management from institutional settings to domestic environments, while tabletop systems retain dominance in hospital respiratory care centers where power reliability and treatment throughput remain paramount. Home healthcare end users represent the fastest-growing demand pool, though hospitals still capture the largest margin concentration due to bulk procurement and device-therapy bundling.
FDA 510(k) clearance requirements govern US market entry for jet nebulizers as Class II medical devices, while the EU Medical Device Regulation imposes stricter clinical evidence standards for aerosol delivery performance claims. ISO 27427 standards define nebulizer characterization protocols that manufacturers must satisfy for international commercialization. Stakeholders must monitor evolving reimbursement coding for home nebulization therapy as payors reassess preventive versus acute intervention economics.
Market Dynamics
Home healthcare migration is compressing institutional purchasing power while expanding portable device volumes, forcing manufacturers to reconfigure compressor durability standards for intermittent domestic use rather than continuous clinical operation.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:Streamlined conformity assessment pathways accelerate cross-border commercialization for German and Italian manufacturers seeking pan-European distribution.
- Chronic obstructive pulmonary disease home management protocols:Pulmonology practices in the United States are embedding nebulization into remote patient monitoring bundles, expanding prescription volumes for reimbursed portable systems.
- Polycarbonate chassis substitution:Polymer injection molding is displacing aluminum die-casting in compressor housings, cutting per-unit material costs and enabling color-coded pediatric product differentiation.
Market Restraints
- Compressor motor supply concentration:Precision electromagnetic component fabrication clusters in Shenzhen and Dongguan, exposing manufacturers to port congestion and tariff volatility.
- ISO 27427 testing burden:Aerosol particle size distribution validation requires specialized laser diffraction equipment and third-party laboratory capacity that creates six-to-nine-month certification queues.
- Ultrasonic nebulizer substitution:Piezoelectric mesh technologies are capturing pediatric antibiotic delivery segments where silent operation outweighs jet system durability advantages.
Strategic Opportunities
- Indian home healthcare expansion:CDSCO streamlined medical device registration and Ayushman Bharat reimbursement expansion create first-mover positioning for portable system manufacturers.
- Veterinary respiratory therapy:Equine and companion animal nebulization protocols are emerging in Australian and Brazilian agricultural veterinary practices with limited incumbent equipment suppliers.
- Smart inhaler-nebulizer convergence:Bluetooth dose tracking and mobile app adherence monitoring are creating premium product tiers that capture pharmacy benefit manager data integration incentives.
Industry Challenges
- Biocompatibility testing capacity:ISO 18562 cytotoxicity and sensitization studies face backlog at notified bodies, delaying pediatric product line extensions.
- Legacy compressor repair infrastructure:Home healthcare distributors lack technician networks for field servicing, forcing manufacturers to absorb warranty replacement costs or invest in remote diagnostic capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jet Nebulizers Market |
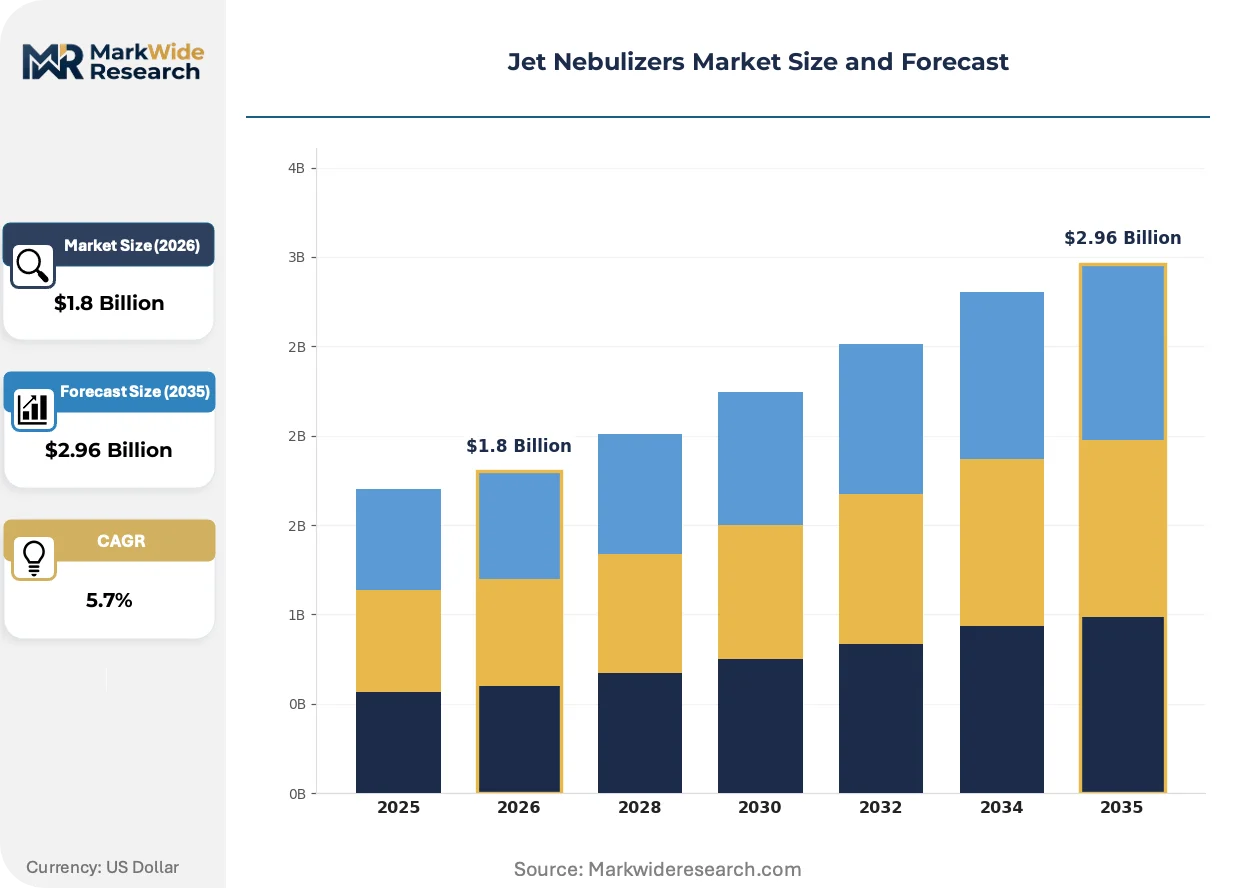
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Jet Nebulizers, Tabletop Jet Nebulizers, Compressor Nebulizers, Ultrasonic Nebulizers, Mesh Nebulizers Application: Respiratory Disorders, Pulmonary Therapy, Cystic Fibrosis Treatment, Bronchitis Management, Asthma Relief End User: Hospitals, Home Healthcare, Specialty Clinics, Respiratory Care Centers, Long-Term Care Facilities Technology: Compressed Air, Ultrasonic Waves, Vibrating Mesh, Flow Venturi, Electrostatic |
| Companies Covered | Omron Corporation, PARI Respiratory Equipment, Inc., Koninklijke Philips N.V., Drive DeVilbiss Healthcare, GE Healthcare, Aerogen, Vectura Group Plc., GF Health Products, Inc., Allied Healthcare Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jet Nebulizers Market Shifts & Advancements
Compressed-air nebulization architectures are fragmenting as manufacturers balance acoustic dampening against power efficiency, while regulatory evidence requirements for pediatric claims intensify clinical trial investment.
Breath-enhanced nebulizer designs with one-way valve mechanisms are overtaking conventional continuous-flow systems in United States pediatric pulmonology practices. The valve-triggered aerosol generation synchronizes medication release with patient inhalation, cutting waste and shortening treatment duration. Hospital respiratory therapy departments are consolidating purchasing around these systems despite per-unit premiums, compressing demand for basic compressor-nebulizer combinations.
FDA 510(k) predicate device pathways are narrowing for jet nebulizers claiming equivalent therapeutic performance to existing cleared systems. The agency's 2023 guidance on comparative aerosol characterization studies now requires mass median aerodynamic diameter data from specific reference formulations, not just saline. Manufacturers targeting United States commercialization are responding by acquiring legacy 510(k) clearances through asset purchases rather than de novo submissions.
Subscription-based device provisioning is displacing outright purchase models in United States durable medical equipment channels. Home healthcare suppliers bundle nebulizer hardware with consumable replenishment and remote monitoring services, capturing recurring revenue streams. This shift is most visible in Medicare Advantage plan networks where capitated respiratory care contracts incentivize equipment standardization and adherence data reporting.
Jet Nebulizers Market Segmentation
Jet nebulizer manufacturers configure product architectures around distinct clinical workflows and patient mobility requirements. Each segmentation axis reveals divergent margin structures, regulatory burdens, and supply chain configurations that shape competitive positioning.
Product Type:
Standardization dominates portable and tabletop systems where ISO 27427 compliance drives design convergence, while specialized mesh and ultrasonic platforms retain customization for pediatric and antibiotic delivery protocols.
- Portable Jet Nebulizers:Battery-powered compressor systems weighing under 500 grams deliver intermittent therapy for ambulatory COPD patients. Demand concentrates in United States Medicare Advantage networks where remote patient monitoring bundles reimburse home-based respiratory management.
- Tabletop Jet Nebulizers:AC-powered stationary units with continuous-duty compressors serve hospital respiratory therapy departments. German-engineered systems from PARI anchor clinical procurement in European pulmonology centers where treatment throughput determines equipment selection.
- Compressor Nebulizers:Piston-driven air compression remains the cost-optimized standard for emerging market home healthcare expansion.
- Ultrasonic Nebulizers:Piezoelectric crystal vibration generates aerosol without mechanical noise, capturing pediatric sleep therapy segments.
- Mesh Nebulizers:Perforated membrane technology from Omron enables silent, portable antibiotic delivery for cystic fibrosis patients.
Leading the category by volume: Compressor Nebulizers. Expanding most quickly: Portable Jet Nebulizers.
Application:
Volume scale concentrates in chronic disease management where recurring prescriptions sustain device utilization, while acute bronchitis applications exhibit seasonal demand fluctuation that complicates inventory planning.
- Respiratory Disorders:Broad-spectrum nebulization addresses COPD, asthma, and chronic bronchitis through bronchodilator and corticosteroid delivery. United States pulmonology practices embed these systems into value-based care contracts that penalize hospitalization events.
- Pulmonary Therapy:Post-operative respiratory rehabilitation and mechanical ventilation weaning protocols drive hospital purchasing. German and Italian manufacturers supply European respiratory care centers with breath-enhanced valve systems that synchronize aerosol release with patient inhalation.
- Cystic Fibrosis Treatment:High-frequency antibiotic nebulization demands specialized mesh technology with precise particle size control.
- Bronchitis Management:Acute viral and bacterial episodes generate episodic demand spikes concentrated in winter months.
- Asthma Relief:Pediatric and adult maintenance therapy splits between rescue inhalers and scheduled nebulization based on severity stratification.
Dominant by prescription volume: Respiratory Disorders. Steepest expansion trajectory: Pulmonary Therapy.
End User:
Procurement sophistication varies sharply across settings, with hospitals demanding ISO 18562 biocompatibility documentation while home healthcare distributors prioritize warranty replacement logistics over technical specifications.
- Hospitals:Bulk procurement through group purchasing organizations bundles nebulizer hardware with disposable circuits and medication protocols. United States health systems consolidate around FDA 510(k)-cleared systems with established predicate device pathways.
- Home Healthcare:Durable medical equipment suppliers provision portable systems through Medicare Part B reimbursement. Indian CDSCO registration expansion and Ayushman Bharat coverage growth are redirecting manufacturer attention toward South Asian home care channels.
- Specialty Clinics:Pediatric pulmonology and allergy practices prescribe breath-enhanced systems with shorter treatment duration.
- Respiratory Care Centers:Dedicated outpatient facilities maintain high-utilization compressor fleets for frequent patient visits.
- Long-Term Care Facilities:Nursing homes balance device durability against limited on-site technical support capacity.
Capturing highest margin concentration: Hospitals. Gaining share fastest: Home Healthcare.
Technology:
Patent thickets and component supply concentration differentiate mature compressed-air platforms from emerging electrostatic architectures still seeking clinical validation.
- Compressed Air:Piston or diaphragm compressors force air across a baffle to generate one-to-five-micrometer droplets. Shenzhen and Dongguan manufacturing clusters supply precision electromagnetic motors that determine system reliability and acoustic profile.
- Ultrasonic Waves:High-frequency piezoelectric vibration eliminates compressor noise for sleep-disturbed pediatric patients. Japanese manufacturers leverage domestic ceramic transducer expertise to maintain technology leadership.
- Vibrating Mesh:Perforated aperture plates driven by piezoelectric actuators enable portable, silent operation with minimal residual volume.
- Flow Venturi:Bernoulli-effect aerosol generation reduces medication waste through breath-synchronized delivery.
- Electrostatic:Charged particle deposition technology remains experimental, targeting enhanced lung periphery deposition.
Highest installed base: Compressed Air. Climbing the fastest: Vibrating Mesh.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement infrastructure and chronic respiratory disease prevalence concentrate demand-side pull, while manufacturing capacity clusters across German precision engineering centers and Chinese component fabrication hubs.
United States
Medicare Advantage capitated respiratory care contracts and remote patient monitoring bundles drive portable system procurement. FDA 510(k) predicate device pathways govern market entry for jet nebulizers as Class II medical devices. Minnesota and Massachusetts host durable medical equipment distributors consolidating purchasing around breath-enhanced valve systems.
Germany
Hospital respiratory therapy departments prioritize treatment throughput and German-engineered medication delivery precision. EU Medical Device Regulation harmonization streamlines conformity assessment for pan-European distribution. Starnberg and Gräfelfing anchor clinical procurement networks for pediatric-specialized nebulizer systems.
China
Domestic chronic obstructive pulmonary disease prevalence and expanding private health insurance coverage stimulate home healthcare device demand. NMPA medical device registration requirements shape product clearance timelines for imported systems. Shenzhen and Dongguan manufacturing clusters supply precision electromagnetic compressor motors determining system reliability.
India
Ayushman Bharat reimbursement expansion and CDSCO streamlined medical device registration redirect manufacturer attention toward South Asian home care channels. The national pharmaceutical regulator oversees quality standards for respiratory therapy equipment commercialization. Maharashtra and Gujarat host emerging distribution networks for portable compressor systems.
Japan
Aging demographics and government-promoted home healthcare transition expand domestic demand for silent, portable nebulization. PMDA medical device approval processes require local clinical evidence submission for therapeutic performance claims. Tokyo and Osaka metropolitan areas concentrate respiratory care equipment procurement for both institutional and domestic settings.
Jet Nebulizers Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance hospital and home channel exposure. The vendor base fragments across precision compressor specialists, integrated respiratory care conglomerates, and pediatric-focused medication delivery engineers. Three archetypes anchor competitive positioning: Japanese precision manufacturers leveraging domestic ceramic transducer expertise, German clinical-system engineers optimizing treatment throughput, and diversified health technology conglomerates spanning institutional and domestic channels. M&A activity and technology licensing agreements represent the dominant competitive moves, with manufacturers acquiring legacy 510(k) clearances to circumvent narrowing FDA predicate pathways.
Within the precision-manufacturing tier, Omron Corporation and PARI Respiratory Equipment, Inc. exemplify divergent geographic specialization strategies. Omron anchors Japanese domestic production of piezoelectric mesh and compressor systems, while PARI represents German-engineered clinical-system positioning. Koninklijke Philips N.V. occupies a position as a diversified health technology conglomerate competing across hospital and home channels with integrated respiratory care portfolios. These three entities collectively illustrate how geographic manufacturing footprints and regulatory clearance strategies determine competitive access to reimbursement-driven procurement networks.
| Leading Market Players |
|---|
| Omron Corporation |
| PARI Respiratory Equipment, Inc. |
| Koninklijke Philips N.V. |
| Drive DeVilbiss Healthcare |
| GE Healthcare |
| Aerogen |
| Vectura Group Plc. |
| GF Health Products, Inc. |
| Allied Healthcare Products, Inc. |
| Others |
Supply & Pricing Matrix
Polycarbonate chassis substitution in compressor housings simultaneously compresses per-unit manufacturing costs and concentrates molding capacity among polymer injection specialists in China and Taiwan. This materials transition redraws supplier power dynamics as metal fabrication expertise loses pricing leverage to polymer processors capable of color-coded pediatric differentiation.
Pricing Analysis
Volume concentration in compressor nebulizers runs against margin capture in portable jet systems. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered clinical systems from Medicare Advantage bundled offerings and emerging-market piston-driven units. Price differentiation hinges on ISO 27427 certification tier and pediatric biocompatibility documentation depth. Cost compression in economy tiers is intensifying because polycarbonate sourcing scales faster than precision motor capacity. Home healthcare distributors exhibit highest price sensitivity; hospital GPOs prioritize throughput reliability over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with precision electromagnetic compressor motor fabrication concentrated in Shenzhen and Dongguan. Component sourcing draws from Japanese ceramic transducers for piezoelectric mesh systems, German-engineered valve mechanisms for breath-enhanced platforms, and Chinese polymer processors for chassis molding. Supply chain risk centers on port congestion exposure at Shenzhen-Yantian and tariff volatility affecting electromagnetic component classifications. Distribution runs through durable medical equipment suppliers consolidating Medicare Part B provisioning and hospital GPO contracts bundling hardware with disposable circuits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision motor manufacturing capacity constraints prop pricing power for incumbent compressor suppliers as demand outstrips qualified electromagnetic component output. Supply bottlenecks at Shenzhen fabrication clusters sustain margin premiums for vertically integrated producers.
For Market Incumbents: Anticipate ultrasonic nebulizer substitution in pediatric sleep therapy by accelerating breath-enhanced valve R&D and acquiring legacy FDA 510(k) clearances to circumvent narrowing predicate pathways. Backward integration into polymer molding secures chassis cost control against Chinese processor consolidation. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian home healthcare channels offers white-space positioning beneath Omron and PARI tier-one pricing. CDSCO streamlined registration and Ayushman Bharat reimbursement expansion create accessible entry ramps. Veterinary respiratory therapy in Australian equine practices presents additional uncontested terrain with limited incumbent presence. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified health technology conglomerates seeking respiratory care portfolio completion. Five-to-ten-year viability favors manufacturers with captive compressor motor supply and established FDA predicate device libraries. The signal to monitor is FDA guidance expansion on comparative aerosol characterization studies, which would accelerate clearance asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acquisition | Legacy predicate device libraries circumvent narrowing agency pathways for aerosol performance claims. |
| Precision Compressor Capacity Expansion | Shenzhen and Dongguan manufacturing clusters anchor electromagnetic motor supply reliability. |
| Reimbursement Strategy Development | Medicare Advantage capitated contracts bundle hardware with remote monitoring adherence data. |
| Pediatric Biocompatibility Certification | ISO 18562 testing investment unlocks premium positioning in pulmonology practice networks. |
| Smart Inhaler-Nebulizer Convergence | Bluetooth dose tracking captures pharmacy benefit manager data integration incentives. |
Research Methodology
Independent corroboration across hospital respiratory therapy directors, biomedical equipment procurement managers, GPO contracts specialists, and home healthcare durable medical equipment distributors underwrites the qualitative findings. Primary fieldwork with German and Japanese precision manufacturers supplements secondary validation through FDA 510(k) clearance databases, EU MDR notified body registrations, CMS Medicare reimbursement coding records, and ISO 27427 testing laboratory capacity reports. Bottom-up demand modeling across patient population segments triangulates against top-down manufacturer shipment estimates.
Rate-of-change decomposition separates volume expansion in portable systems from value migration toward breath-enhanced and smart-connected platforms across the analysis window. Segmentation dimensions span product architecture, application severity, end-user procurement sophistication, and technology maturity. CAGRs derive from patient population epidemiology, prescription volume trends, and reimbursement policy trajectory. Forecast inputs incorporate compressor motor manufacturing capacity constraints and evolving FDA predicate device pathway accessibility.
Underlying measurement precision varies by segment; hospital procurement data carries tighter precision than emerging market home healthcare estimates. Forecasts reflect documented assumptions regarding reimbursement policy stability, regulatory clearance timelines, and materials substitution rates. Pandemic-era demand spikes, compressor supply disruptions, or FDA guidance revisions could materially revise trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
Low Vision Aids Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Interphalangeal Fusion Market