
 Contact Lens Lubricant Market | 2026-2036
Contact Lens Lubricant Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Lens Lubricant Market Insights
Market Context with Strategic Players
The price-performance gap between premium preservative-free formulations and commodity multi-purpose solutions is hardening as consumers trade up for ocular biocompatibility. Alcon leverages its surgical heritage to anchor credibility in post-operative lubricant segments. Johnson & Johnson Vision Care, Inc. dominates retail pharmacy shelf space through decades of brand equity in lens care ecosystems. Bausch & Lomb competes aggressively on unit economics in emerging markets with standardized multi-purpose drops.
Technical Definition and Structural Segments
Contact lens lubricants comprise sterile aqueous or viscoelastic solutions containing electrolytes, viscosity agents such as hyaluronic acid or carboxymethylcellulose, and optionally preservatives, engineered to restore tear film stability and reduce friction between the lens and corneal epithelium during wear. Preservative-free vials command the richest margin pools as regulatory scrutiny on benzalkonium chloride toxicity intensifies across ophthalmic portfolios. Rewetting drops delivered via single-use vials represent the fastest-growing delivery-end user intersection, while dropper bottles retain volume leadership in retail pharmacy channels where convenience and cost sensitivity coexist.
Regulatory Frame and Forward-Looking Close
The FDA's ophthalmic guidance documents and the European Medicines Agency's quality guidelines for multidose eye drops jointly elevate manufacturing compliance burdens for preservative-containing formulations. ISO 11980 standards for contact lens care products shape international market access protocols, particularly for manufacturers seeking entry into Japan's METI-regulated marketplace. Stakeholders must monitor evolving preservative safety thresholds and decide whether to accelerate reformulation investments or exit commodity tiers before regulatory deadlines eliminate legacy formulations.
Market Dynamics
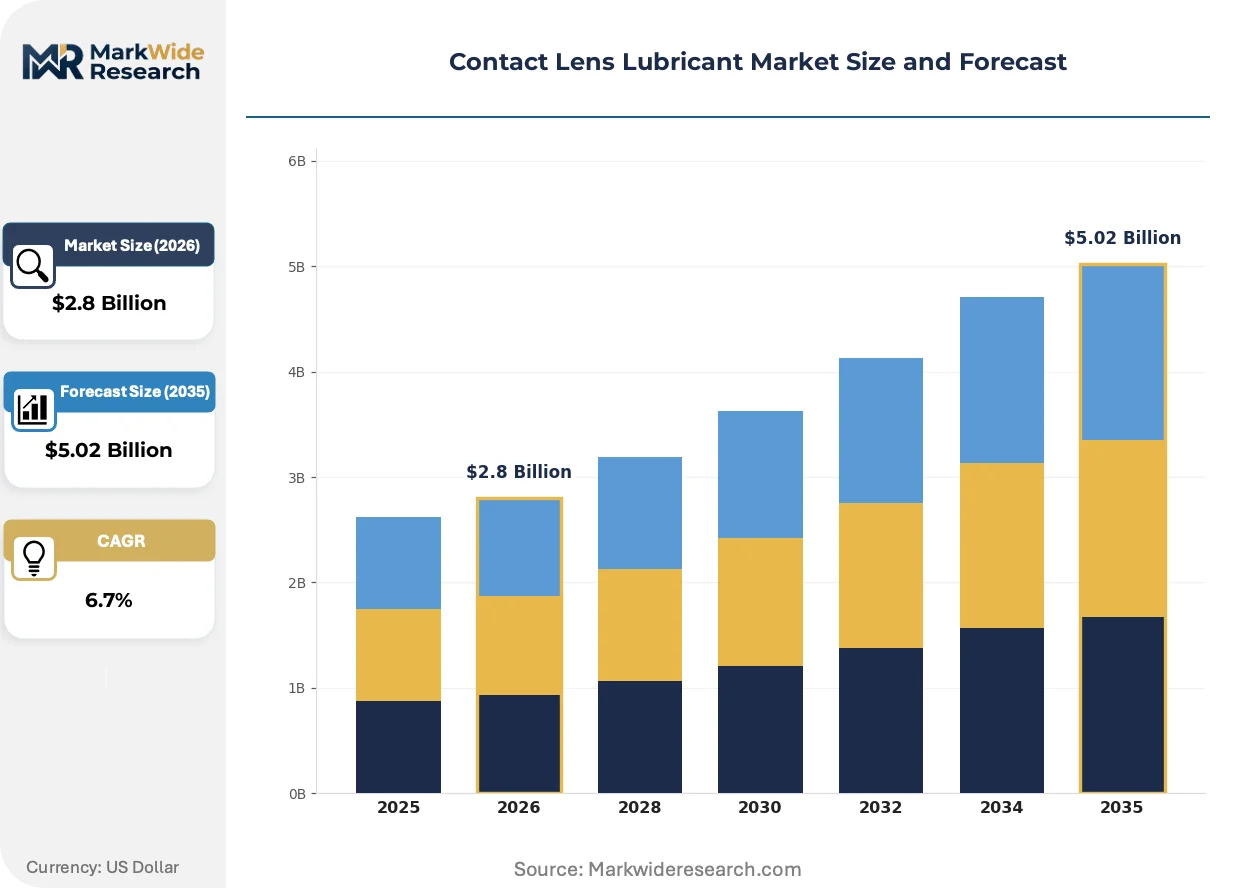
Preservative-free formulation chemistry is compressing legacy multi-purpose solution margins as FDA ophthalmic guidance tightens benzalkonium chloride safety thresholds and daily disposable lens wearers trade up for ocular biocompatibility.
Growth Catalysts
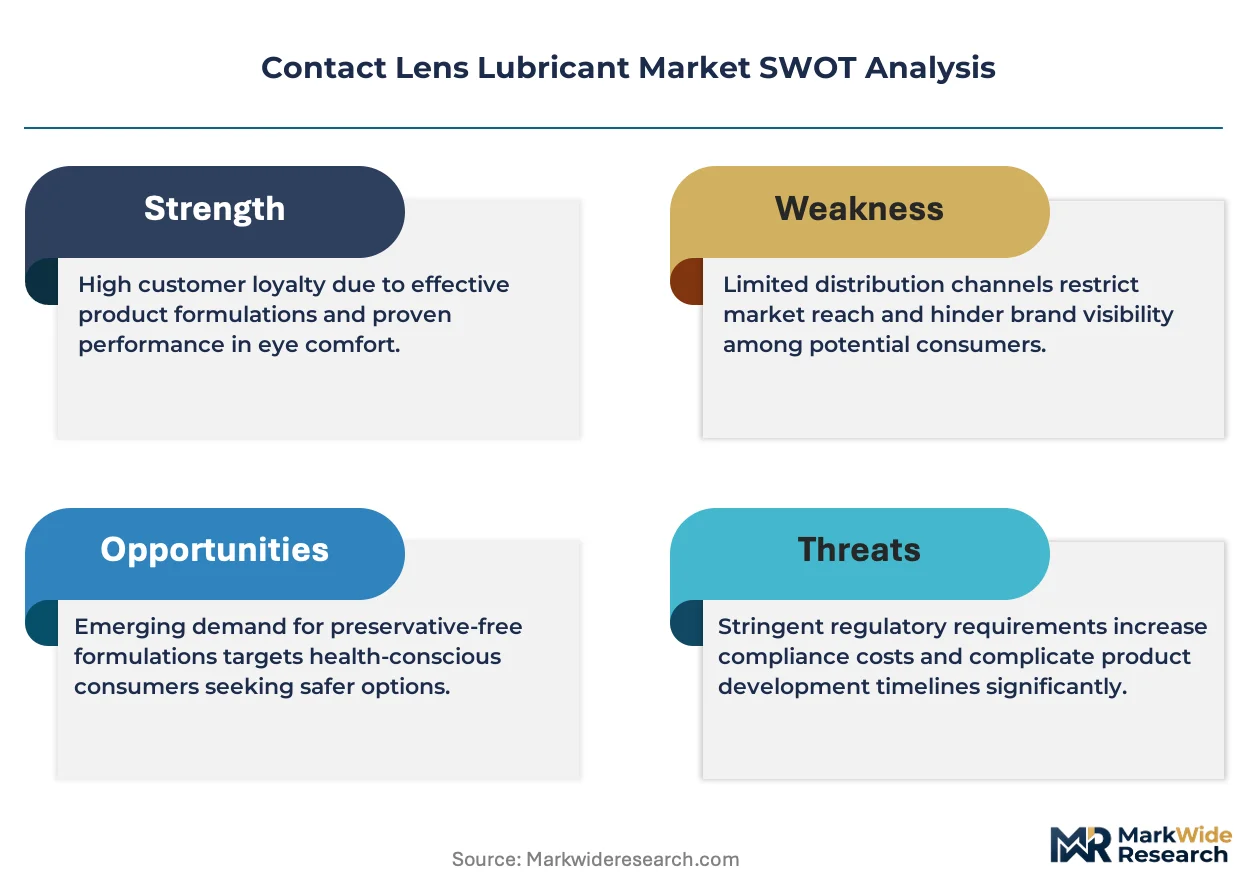
- FDA Ophthalmic Guidance:Updated preservative safety standards force incumbent manufacturers to reformulate toward benzalkonium chloride-free chemistry, accelerating premium segment expansion.
- Silicone Hydrogel Lens Chemistry:Advanced lens materials increase tear film evaporation rates during extended wear, elevating dependency on supplemental lubrication protocols among daily disposable users.
- Specialty Optometry Chains:Concentrated retail channels in the United States drive professional recommendation power toward premium preservative-free vial formats.
Market Restraints
- Hyaluronic Acid Supply Concentration:Pharmaceutical-grade sodium hyaluronate production clusters in Chinese fermentation facilities, exposing formulators to input cost volatility and geopolitical supply risk.
- Single-Use Vial Manufacturing Scale:Blow-fill-seal aseptic packaging requires capital-intensive dedicated lines that commodity multi-purpose producers cannot economically retrofit.
- Substitution by Artificial Tears:Generic dry-eye formulations without lens-specific viscosity profiles capture price-sensitive users seeking dual-purpose ocular surface therapy.
Strategic Opportunities
- Japanese METI-Regulated Marketplace:Stringent ISO 11980 compliance requirements create defensive moats for early entrants with validated preservative-free manufacturing protocols.
- Post-Surgical Recovery Protocols:Cataract and refractive surgery volumes expand addressable use cases beyond daily lens wear into acute ocular surface rehabilitation.
- E-Commerce Direct-to-Consumer Channels:Subscription-based replenishment models bypass pharmacy shelf-space gatekeepers and capture recurring revenue from established wearers.
Industry Challenges
- Aseptic Manufacturing Certification Timelines:FDA sterile drug product facility inspections for preservative-free lines extend validation cycles by 18-24 months versus conventional formulations.
- Cross-Functional Formulation Expertise:Shortage of ophthalmic polymer chemists with simultaneous contact lens material and tear film physiology competency constrains R&D pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Lens Lubricant Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservative-Free, Multi-Purpose, Rewetting Drops, Eye Wash Delivery Mode: Dropper Bottle, Tube, Spray, Vial End User: Optometrists, Ophthalmologists, Retail Pharmacies, Online Retailers Application: Dry Eye Relief, Contact Lens Care, Post-Surgery Recovery, Daily Moisturizing |
| Companies Covered | Johnson & Johnson Vision Care, Inc., Alcon, Bausch & Lomb, The Cooper Companies, Menicon Co., Ltd., Carl Zeiss Meditec AG, Hoya Corporation, EssilorLuxottica SA, Abbvie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Lens Lubricant Market Trends and Innovations
Electrolyte-matched tear film biomimetics are displacing simple saline-based rewetting chemistry as lens wearers and practitioners prioritize corneal epithelial compatibility over basic friction reduction.
Hyaluronic acid-carbomer hybrid viscosity systems is converging with ionic-buffered electrolyte matrices to create extended-duration tear film stability without preservative load. Specialty optometry practices in Germany and South Korea are piloting these formulations for silicone hydrogel extended-wear patients. The technology is converging with diagnostic tear osmolarity testing to enable personalized lubricant matching based on individual evaporative dry-eye severity.
EMA quality guidelines for multidose eye drops now mandate tighter extractables and leachables testing for plastic primary packaging materials used in contact lens care. European manufacturers face reformulation costs to qualify alternative preservative systems or transition entirely to unit-dose presentation. Preservative-containing multi-purpose solutions in France and Italy are experiencing accelerated share erosion as ANSM and AIFA inspection priorities align with EMA technical guidance.
Subscription auto-replenishment through vision insurance portals is replacing pharmacy counter purchasing among established monthly and bi-weekly lens wearers. United States-based managed vision care networks now integrate lubricant allowances into annual material benefits, redirecting volume from retail toward direct fulfillment. This channel migration concentrates most visibly in employer-sponsored vision plans covering manufacturing and technology sector workforces with high screen-time exposure profiles.
Contact Lens Lubricant Market Segmentation
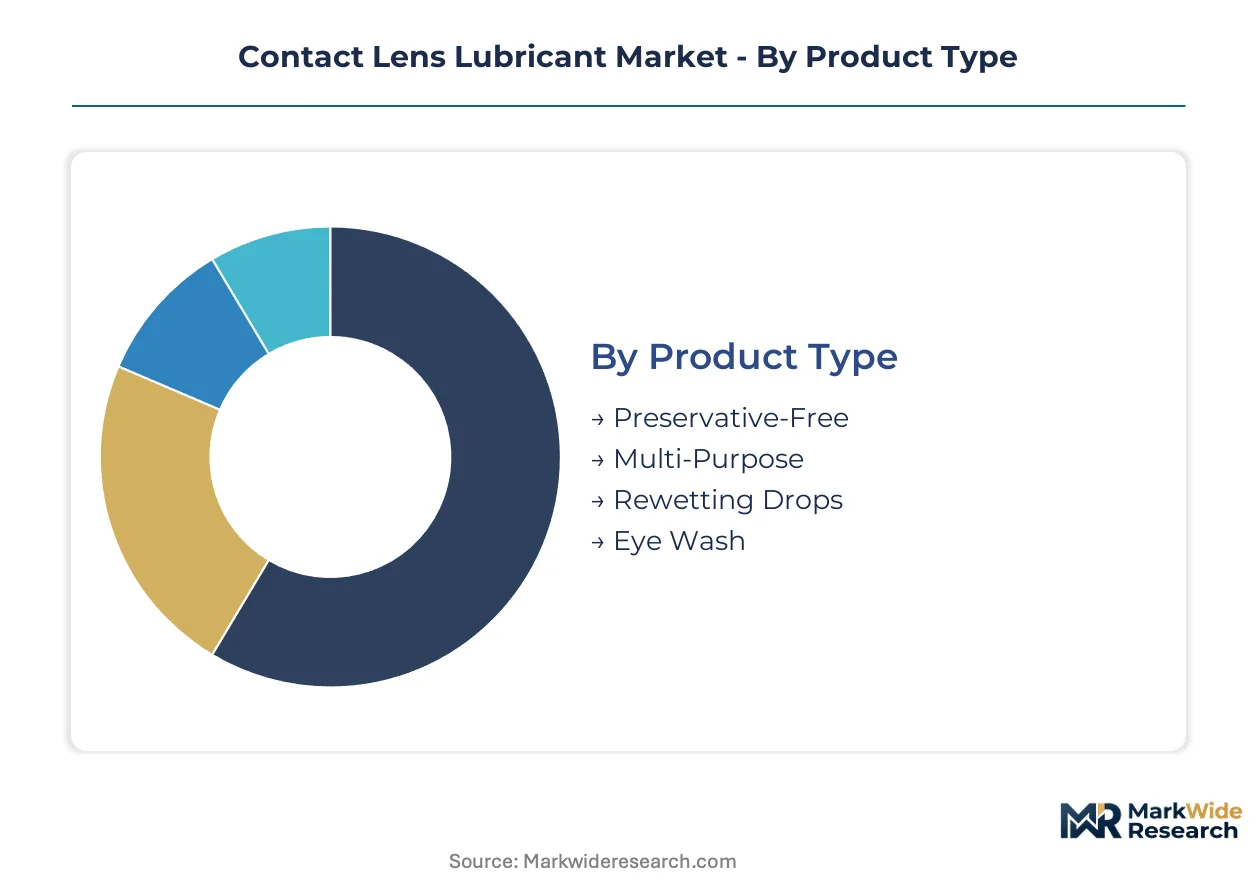
Segmentation in contact lens lubricants reveals how regulatory pressure and material innovation split demand across incompatible chemistry platforms. Manufacturers must choose which approval pathways to pursue, as FDA sterile drug certification, ISO 11980 validation, and Japan METI compliance each favor distinct product architectures.
Product Type:
FDA ophthalmic guidance on benzalkonium chloride toxicity and EMA quality guidelines for multidose eye drops impose divergent certification burdens across chemistry platforms, forcing portfolio specialization.
- Preservative-Free:Single-use vials or advanced filter technologies eliminate benzalkonium chloride and polyquaternium-1 entirely. These formulations command premium positioning in United States specialty optometry chains where FDA guidance drives professional recommendation power toward biocompatible chemistry.
- Multi-Purpose:All-in-one solutions combining cleaning, disinfection, and lubrication functions rely on preserved formulations. Regulatory deadlines in Europe and tightening FDA thresholds are compressing margin pools as reformulation costs escalate for legacy benzalkonium chloride-dependent lines.
- Rewetting Drops:Lens-specific viscosity profiles with hyaluronic acid or carboxymethylcellulose address friction during wear. Demand concentrates among silicone hydrogel daily disposable users experiencing elevated tear film evaporation.
- Eye Wash:Saline-based rinsing solutions for lens insertion and removal protocols. Standardized formulations face substitution pressure from generic sterile irrigants in price-sensitive retail channels.
Leading the category by volume: Multi-Purpose. Expanding most quickly: Preservative-Free.
Delivery Mode:
Packaging technology determines capital intensity and channel access, with aseptic blow-fill-seal lines creating barriers that commodity producers cannot cross.
- Dropper Bottle:Multi-dose presentation dominates retail pharmacy shelf space through convenience and unit economics. EMA extractables and leachables testing mandates for plastic primary packaging are elevating compliance costs for European manufacturers.
- Vial:Single-use sterile units enable preservative-free chemistry without complex filter systems. Blow-fill-seal aseptic packaging requires dedicated capital-intensive production lines that extend FDA validation cycles substantially.
- Tube:Squeeze formats for gel-based lubricants with extended residence time on the ocular surface. Limited adoption outside post-surgical recovery protocols where viscosity retention matters.
- Spray:Mist delivery for users with manual dexterity limitations or pediatric applications. Niche positioning constrained by dose consistency challenges versus drop-based systems.
Widest installed base: Dropper Bottle. Steepest expansion trajectory: Vial.
End User:
Channel structure determines pricing power, with professional recommendation driving premium uptake versus retail price competition.
- Optometrists:Primary gatekeepers for lens wearer education and product recommendation in United States specialty chains. Professional endorsement converts patients to preservative-free vial formats despite higher out-of-pocket cost.
- Ophthalmologists:Surgical specialists control post-operative recovery protocols including acute lubricant regimens. Alcon leverages surgical heritage to anchor credibility in this channel.
- Retail Pharmacies:Mass-market shelf space where Johnson & Johnson Vision Care dominates through decades of brand equity. Convenience and cost sensitivity coexist, favoring multi-purpose solutions.
- Online Retailers:Direct-to-consumer subscription models bypass pharmacy gatekeepers. United States managed vision care networks increasingly integrate lubricant allowances into annual material benefits, redirecting volume toward fulfillment centers.
Highest volume throughput: Retail Pharmacies. Gaining share fastest: Online Retailers.
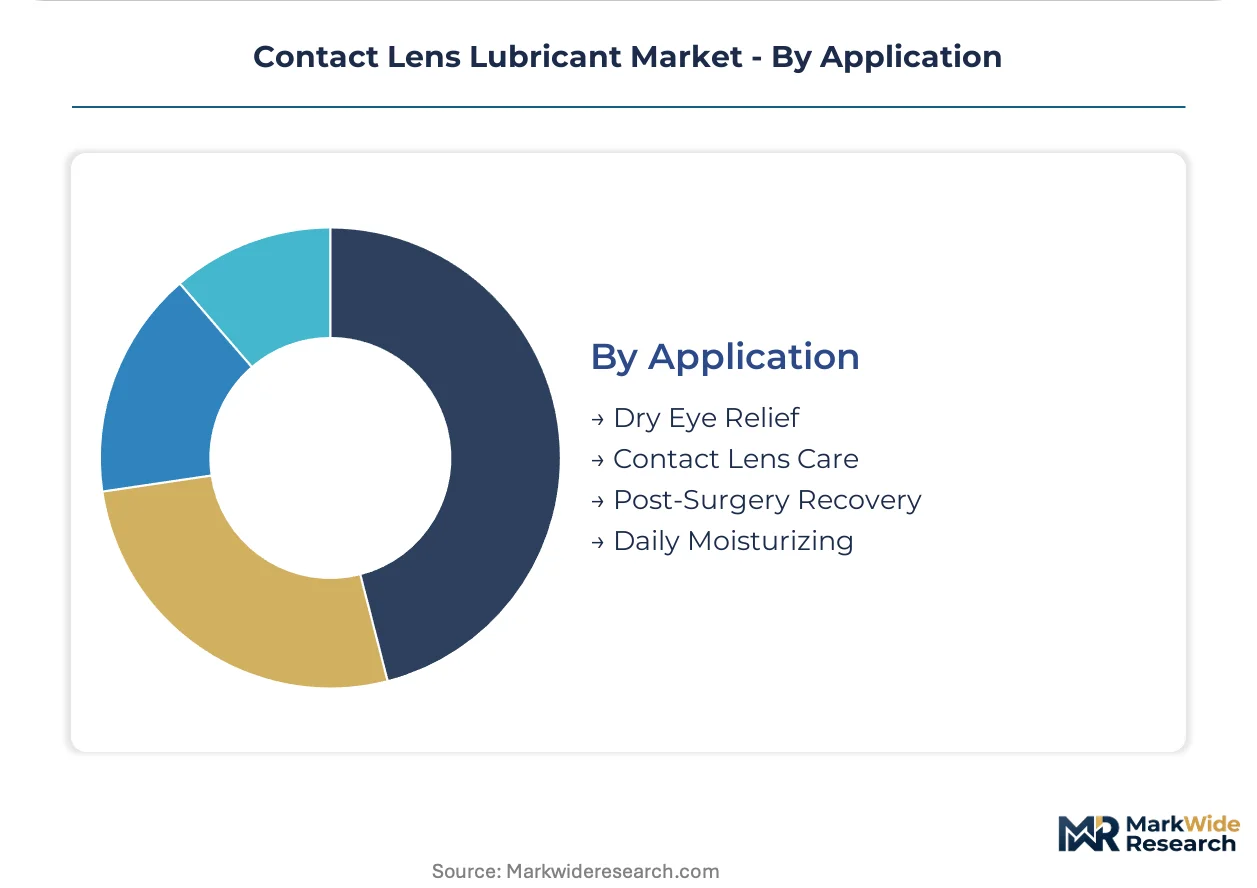
Application:
Use case specificity determines formulation requirements, with lens-specific chemistry diverging from general dry-eye therapy.
- Contact Lens Care:Core application requiring viscosity agents matched to silicone hydrogel surface properties. Daily disposable lens wearers represent the most dynamic demand cohort as wear frequency expands.
- Dry Eye Relief:Overlaps with artificial tears category, exposing lens-specific lubricants to substitution by generic ocular surface therapies lacking optimized rheology for lens wear.
- Post-Surgery Recovery:Acute protocols following cataract and refractive procedures. Cataract surgery volumes are expanding addressable use cases beyond chronic lens wear into time-limited rehabilitation regimens.
- Daily Moisturizing:Preventive use among asymptomatic wearers in high screen-time exposure profiles. Employer-sponsored vision plans in United States manufacturing and technology sectors increasingly cover this prophylactic application.
Largest addressable base: Contact Lens Care. Climbing the fastest: Post-Surgery Recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fort Worth anchors North American ophthalmic manufacturing through Alcon's surgical heritage and distribution infrastructure. Specialty optometry chains in Texas and neighboring states channel professional recommendation power toward premium preservative-free formulations.
United States
FDA ophthalmic guidance on benzalkonium chloride toxicity drives reformulation investments among multi-purpose solution producers. Managed vision care networks in employer-sponsored plans now integrate lubricant allowances into annual material benefits. The Dallas-Fort Worth corridor concentrates sterile drug manufacturing capacity serving domestic pharmacy and direct-to-consumer channels.
Germany
Specialty optometry practices in Bavaria and Baden-Württemberg pilot hyaluronic acid-carbomer hybrid formulations for silicone hydrogel extended-wear patients. EMA quality guidelines for multidose eye drops mandate tighter extractables testing for plastic primary packaging. The Rhine-Main cluster around Frankfurt hosts pharmaceutical packaging specialists developing blow-fill-seal aseptic lines for preservative-free vial production.
Japan
METI-regulated marketplace requirements under ISO 11980 standards create defensive entry barriers for validated preservative-free manufacturing protocols. Daily disposable lens penetration rates in Tokyo and Osaka metropolitan areas exceed Western benchmarks, elevating dependency on supplemental lubrication. The Kansai region hosts contact lens material research facilities advancing tear film biomimetic chemistry.
China
Pharmaceutical-grade sodium hyaluronate fermentation capacity clusters in Shandong and Jiangsu provinces, exposing formulators to input cost volatility. NMPA alignment with international sterile drug standards accelerates domestic facility upgrades for preservative-free lines. The Yangtze River Delta manufacturing belt supplies viscosity agents to regional multi-purpose solution producers competing on unit economics.
South Korea
Seoul-based specialty optometry chains drive rapid adoption of electrolyte-matched tear film biomimetics among high screen-time professional cohorts. MFDS enforcement of ophthalmic product quality standards tightens certification timelines for imported preservative-containing formulations. The Pangyo technology corridor integrates diagnostic tear osmolarity testing with personalized lubricant matching protocols.
Contact Lens Lubricant Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry and delivery technology dimensions. The market structures around three tiers: surgical heritage anchors commanding post-operative protocols, retail pharmacy incumbents dominating shelf-space economics, and emerging direct-to-consumer specialists capturing subscription replenishment flows. Consolidation pressure concentrates among multi-purpose solution producers facing regulatory deadline compression. Dominant competitive moves include preservative-free reformulation investments and aseptic manufacturing capacity expansion.
Within the surgical heritage tier, Alcon leverages its Fort Worth-rooted credibility to anchor post-operative lubricant segments. Johnson & Johnson Vision Care, Inc. exemplifies retail pharmacy dominance through decades of accumulated brand equity in lens care ecosystems. Bausch & Lomb occupies a position in emerging market commodity economics, competing aggressively on unit cost in standardized multi-purpose drop categories.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care, Inc. |
| Alcon |
| Bausch & Lomb |
| The Cooper Companies |
| Menicon Co., Ltd. |
| Carl Zeiss Meditec AG |
| Hoya Corporation |
| EssilorLuxottica SA |
| Abbvie |
| Others |
Pricing and Supply Chain Analysis
Blow-fill-seal aseptic packaging technology is simultaneously elevating capital barriers for preservative-free entrants and compressing legacy multi-purpose margins as FDA sterile drug certification requirements extend validation timelines. This production-method transition concentrates pricing power with validated manufacturers while forcing commodity producers toward unsustainable unit economics.
Pricing Analysis
Outcome-based pricing anchored to ocular biocompatibility metrics commands substantial premiums over basic friction-reduction formulations. Three-tier pricing structure across preservative-free vials, multi-purpose solutions, and generic rewetting drops separates certification-grade products from commodity alternatives. Pricing pressure stems from EMA extractables testing mandates elevating compliance costs for European plastic packaging. Retail pharmacy channels exhibit highest price sensitivity, while specialty optometry chains absorb premiums through professional recommendation power.
Supply Chain Analysis
Regional distribution centers in the Dallas-Fort Worth corridor and Rhine-Main cluster anchor North American and European fulfillment networks for sterile ophthalmic products. Pharmaceutical-grade sodium hyaluronate production concentrates in Shandong and Jiangsu provinces of China, with viscosity agent supply resting on fermentation capacity at a limited number of qualified facilities. Single-source vulnerability in hyaluronic acid feedstock exposes formulators to geopolitical disruption. Distribution runs through specialty optometry chains and managed vision care portals, bypassing traditional pharmacy wholesale in premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preservative-free formulation chemistry is displacing benzalkonium chloride-dependent legacy lines as the dominant technology platform, creating asymmetric restructuring pressure across manufacturer tiers.
For Market Incumbents: To counter margin compression from regulatory deadline acceleration, accelerate aseptic manufacturing capacity expansion in FDA-inspected facilities and secure backward integration into pharmaceutical-grade sodium hyaluronate supply through long-term offtake agreements with Chinese fermentation specialists. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting employer-sponsored vision plans in United States manufacturing and technology sectors, where managed care networks integrate lubricant allowances into annual material benefits and bypass entrenched pharmacy shelf-space gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with preservative-free specialists possessing validated ISO 11980 compliance and blow-fill-seal production lines given Japanese METI regulatory barriers creating defensive moats. Long-term viability favors acquisition targets with dual FDA-EMA certification and established specialty optometry channel relationships. Monitor FDA sterile drug facility inspection queue depth as inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Reformulation Investment | FDA ophthalmic guidance on benzalkonium chloride toxicity accelerates chemistry transition timelines. |
| Aseptic Manufacturing Scale-Up | Blow-fill-seal line expansion extends sterile drug certification capacity for single-use vial production. |
| Specialty Optometry Chain Partnership | Professional recommendation channels in United States drive premium preservative-free uptake. |
| Direct-to-Consumer Subscription Launch | Managed vision care portal integration captures recurring revenue from established lens wearers. |
| Hyaluronic Acid Supply Agreement | Long-term offtake with Chinese fermentation facilities mitigates pharmaceutical-grade input volatility. |
Research Methodology
FDA guidance documents, EMA quality guidelines, and ISO 11980 standards formed the secondary backbone, supplemented by trade data from ophthalmic product customs classifications and SEC filings from publicly traded lens care manufacturers. Primary interviews with specialty optometry chain procurement directors, pharmaceutical formulation chemists, sterile manufacturing facility managers, and managed vision care network administrators combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis across formulation chemistry transitions and packaging technology adoption curves informed projection modeling. Segmentation dimensions included product type, delivery mode, end-user channel, and application use case across the projection horizon. CAGRs derived from regression analysis of premium segment expansion rates and regulatory-driven substitution patterns, with forecast inputs incorporating silicone hydrogel lens penetration trajectories and cataract surgery volume growth.
Preservative safety threshold revisions, hyaluronic acid supply disruptions, and sterile manufacturing inspection delays are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory timeline adherence and channel migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Latin America General Surgical Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Stool Management Systems Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Hybrid Microcirculation Detector Market
Medical Devices
United States Organ Preservation Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Hip Kits Market