
 Liposuction Devices Market | 2026-2036
Liposuction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Liposuction Devices Market Outlook
Modular platform bundling is restructuring how cosmetic clinics evaluate capital expenditures, with single-vendor suites replacing standalone device purchases. Alma Lasers leverages integrated handpiece ecosystems to sustain recurring revenue streams. Solta Medical anchors its position through geographic dominance in North American dermatology practices. MicroAire Surgical Instruments differentiates via precision-engineered power-assisted cannulas that occupy the premium surgical tier.
Liposuction devices are electromechanical or energy-based instruments designed to aspirate subcutaneous adipose tissue through cannula insertion, typically operating at vacuum pressures between 1 and 0.8 atmospheres and incorporating tumescent fluid delivery systems for hemostasis and anesthesia. These systems serve the commercial purpose of body sculpting in aesthetic medicine, enabling tissue removal with minimized trauma to surrounding structures. Laser liposuction platforms command the highest margin pools due to consumable handpiece attach rates, while ultrasound-assisted liposuction competes on fibrous tissue efficacy in secondary revision cases. Power-assisted liposuction sustains volume leadership in hospital settings where throughput economics favor mechanical reliability over energy-based sophistication.
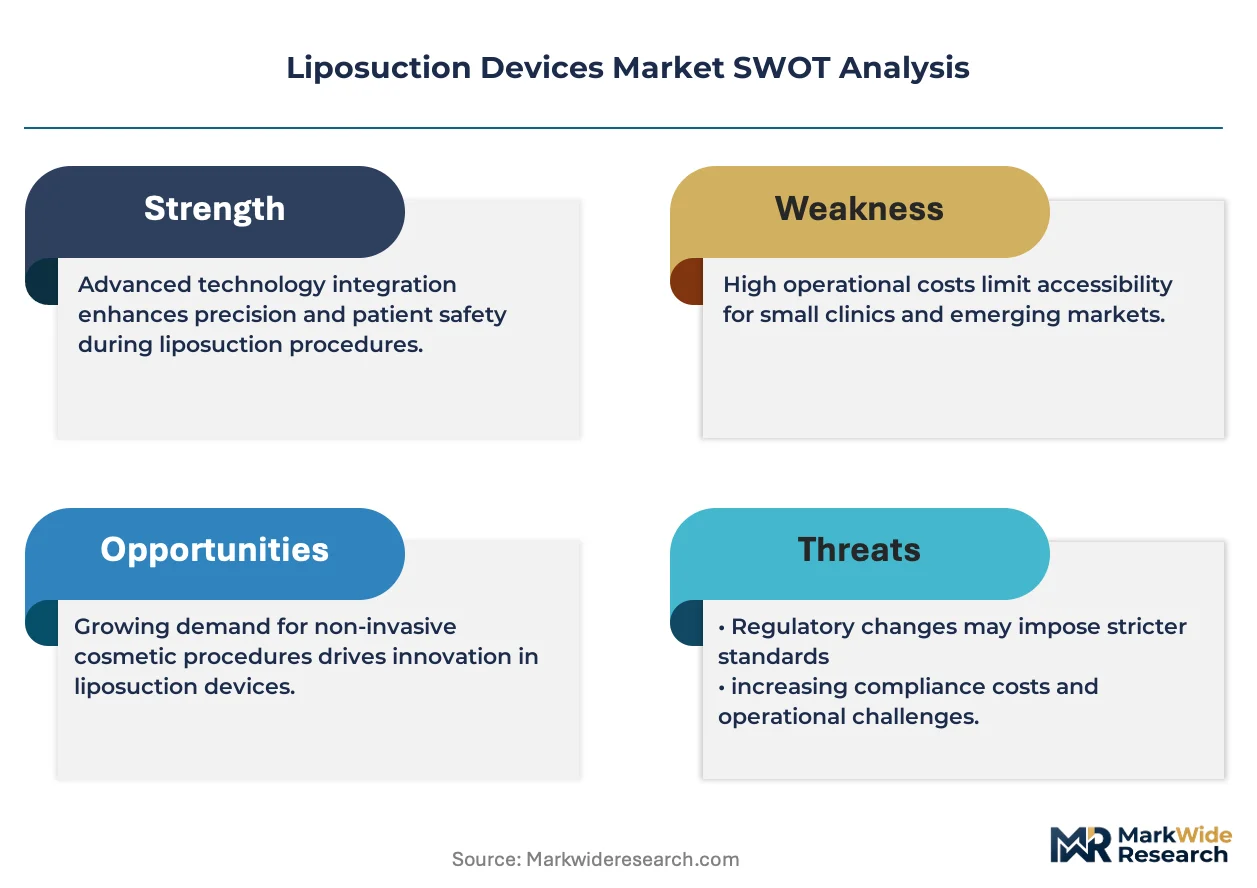
FDA premarket notification requirements and the EU Medical Device Regulation shape product standards by mandating biocompatibility testing and post-market surveillance for all energy-based liposuction platforms. The EPA and OSHA frameworks govern waste handling and operator exposure limits for tumescent fluid aerosols in ambulatory settings. Stakeholders must monitor how evolving MDR technical documentation requirements will reshape market access timelines for hybrid technology devices combining multiple energy modalities.
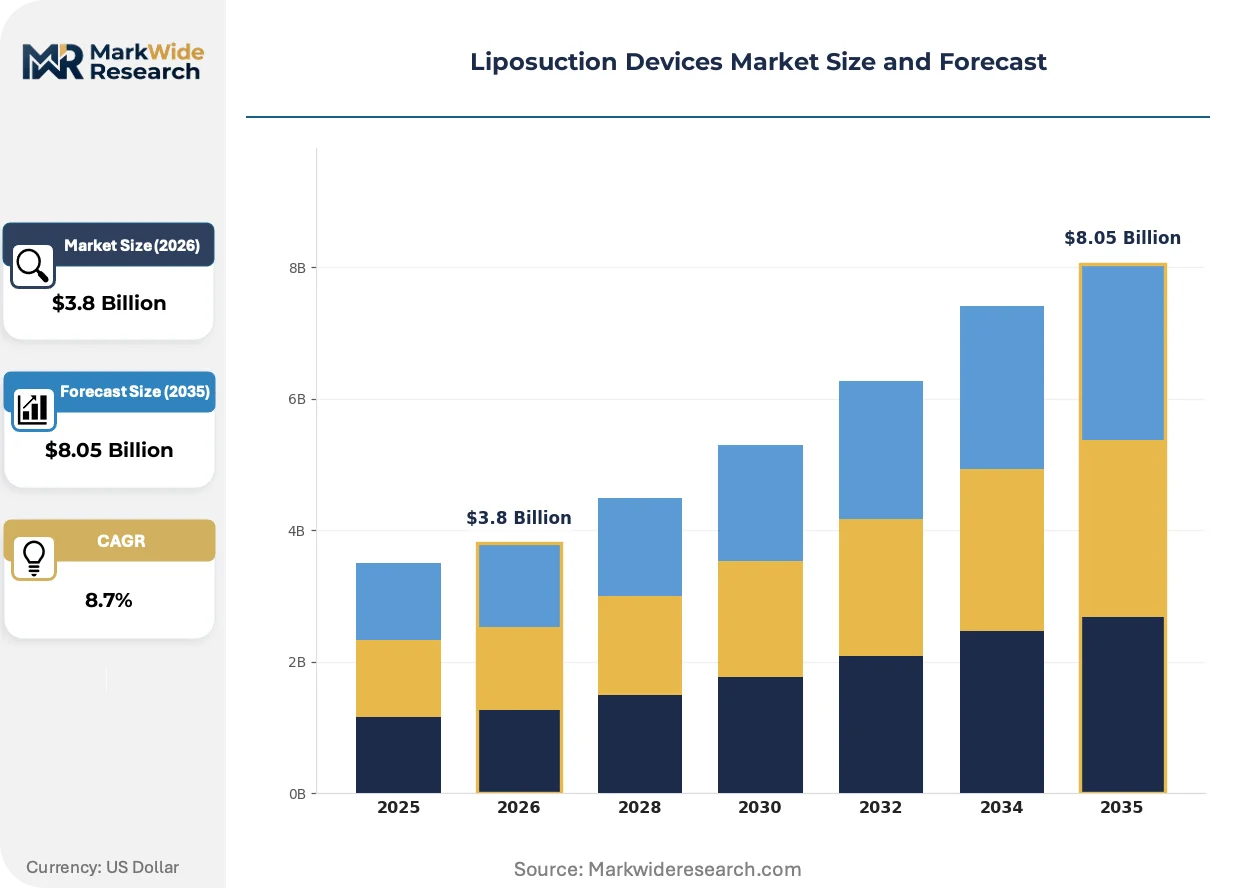
Market Dynamics
Modular platform bundling is compressing standalone device margins as cosmetic clinics consolidate purchasing power around single-vendor suites with integrated handpiece ecosystems and consumable lock-in.
Growth Catalysts
- FDA premarket notification tightening:Stricter documentation requirements for laser-assisted platforms are filtering out marginal competitors and concentrating procurement among certified vendors in US dermatology practices.
- Minimal invasive device upgrades:South Korean dermatology practices are replacing conventional suction systems with energy-based platforms at scale, creating concentrated demand pull for radiofrequency and laser modalities.
- Tumescent fluid delivery integration:Combined anesthesia-hemostasis systems are reducing procedure time and operator training thresholds, expanding addressable clinician base in ambulatory surgical centers.
Market Restraints
- Consumable attach rate dependency:Laser liposuction profitability requires sustained handpiece replacement cycles, creating revenue volatility when clinics extend reuse intervals during capital conservation periods.
- EU MDR technical documentation burden:Extended market access timelines for hybrid energy devices are delaying product launches and compressing effective patent life for multi-modality platforms.
- Secondary revision case concentration:Ultrasound-assisted systems dominate fibrous tissue applications but address a narrower procedure volume, limiting addressable market expansion relative to mechanical alternatives.
Strategic Opportunities
- Brazilian cosmetic clinic procurement expansion:Body contouring mainstreaming is driving device replacement cycles in São Paulo and Rio de Janeiro metro markets with above-average capital expenditure allocation.
- Power-assisted cannula premium tier:Precision-engineered mechanical systems occupy underserved surgical tier where hospital throughput economics favor reliability over energy sophistication.
- EPA waste handling compliance services:Tumescent fluid aerosol management mandates create recurring revenue potential for device manufacturers bundling filtration and disposal infrastructure.
Industry Challenges
- Operator exposure limit compliance:OSHA tumescent fluid aerosol thresholds require engineering controls and monitoring infrastructure that ambulatory centers lack capital to deploy.
- Post-market surveillance integration:EU MDR vigilance reporting obligations for energy-based platforms demand data infrastructure that mid-tier manufacturers struggle to operationalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liposuction Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Liposuction, Tumescent Liposuction, Ultrasound-Assisted Liposuction, Power-Assisted Liposuction Application: Body Contouring, Fat Removal, Breast Augmentation, Liposuction for Face End User: Cosmetic Clinics, Hospitals, Ambulatory Surgery Centers, Dermatology Practices Technology: Smart Liposuction Systems, Minimal Invasive Devices, Traditional Devices, Hybrid Technology |
| Companies Covered | Alma Lasers, Sciton, Solta Medical, Genesis Biosystems, Wells Johnson Company, Cynosure, MicroAire Surgical Instruments, Apyx Medical Corporation, InMode, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liposuction Devices Market Strategic Shifts
Device architecture is converging around closed-loop feedback systems that synchronize energy delivery with real-time tissue impedance monitoring, collapsing the performance gap between surgical and non-surgical modalities.
Radiofrequency-assisted liposuction is automating adipose tissue liquefaction through temperature-controlled energy delivery algorithms that eliminate operator-dependent thermal injury risk. Academic medical centers in Germany are piloting these platforms for high-volume revision cases. The technology is automating procedure standardization and compressing training curves for new clinical adopters.
EU Medical Device Regulation post-market surveillance mandates are extending technical documentation lifecycles and forcing manufacturers to maintain clinical evidence registries beyond initial clearance. Hybrid platforms combining laser and ultrasound modalities face disproportionate scrutiny due to multiple energy classification uncertainties. South Korean manufacturers are responding by segregating product registrations by single-modality configurations to accelerate timeline predictability.
Service contract unbundling is separating device maintenance from consumable supply agreements, allowing cosmetic clinics to negotiate component pricing independently. Independent dermatology groups in California and Texas are driving this fragmentation, pressuring vendor consolidation strategies. This pattern is most visible in North American private practice settings where group purchasing organizations lack enforcement power over individual clinic procurement autonomy.
Liposuction Devices Market Segmentation
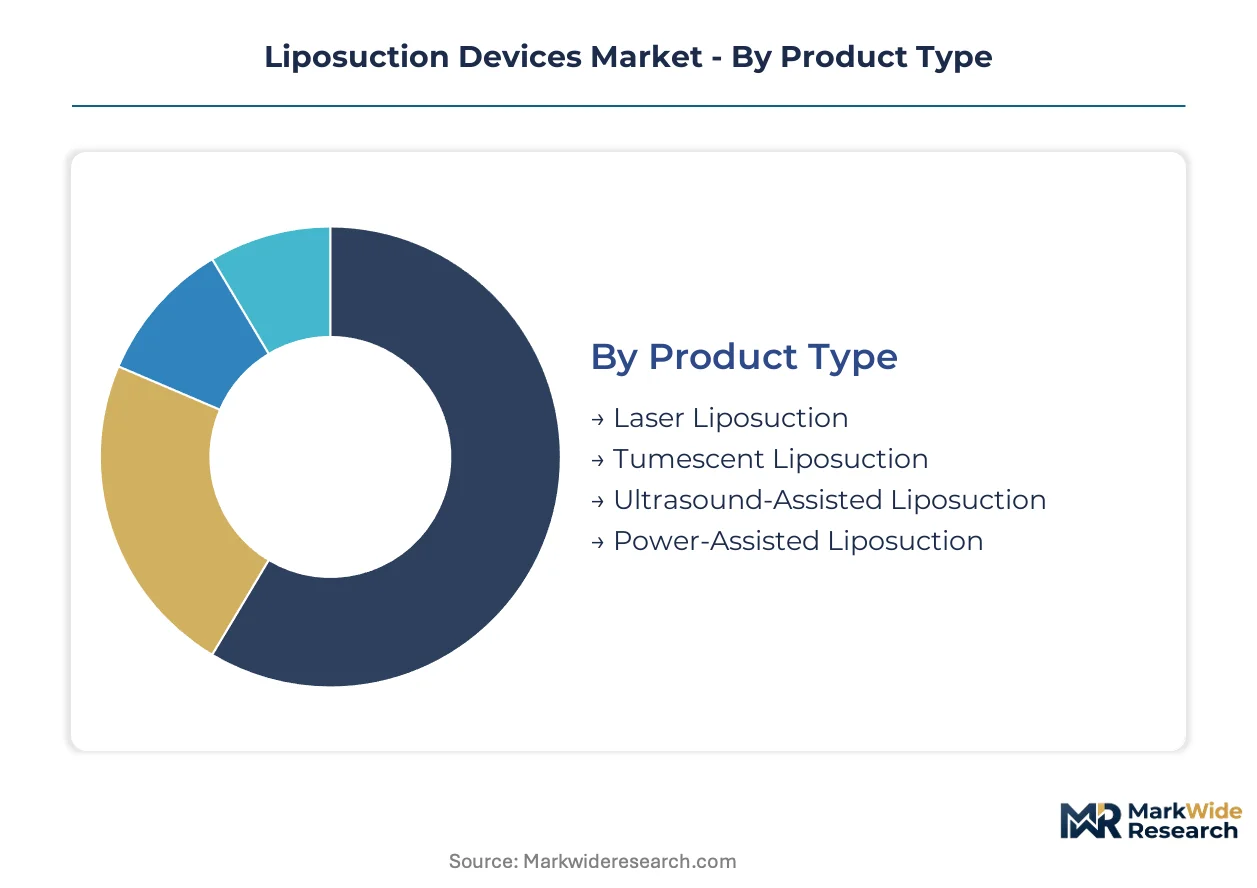
Segmentation in liposuction devices reveals how regulatory pathways, clinical settings, and energy modalities fragment procurement patterns across aesthetic medicine. Understanding these divisions exposes where certification burdens concentrate and which technology tiers command premium positioning.
Product Type:
FDA premarket notification requirements fall heaviest on energy-based platforms, while mechanical systems navigate streamlined clearance pathways through traditional device classifications.
- Laser Liposuction:Thermal adipose liquefaction platforms operate at specific wavelengths with integrated temperature monitoring. Demand concentrates in South Korean dermatology practices upgrading to minimal invasive modalities, though consumable handpiece dependency creates revenue volatility during capital conservation cycles.
- Tumescent Liposuction:Conventional suction-assisted systems incorporate fluid delivery for hemostasis and anesthesia. Brazilian cosmetic clinics in São Paulo and Rio de Janeiro metro markets are replacing aging units as body contouring achieves mainstream acceptance.
- Ultrasound-Assisted Liposuction:Cavitation-based platforms excel in fibrous tissue applications for secondary revision cases. Academic medical centers in Germany pilot these systems for high-volume revision workflows.
- Power-Assisted Liposuction:Reciprocating cannula mechanisms reduce operator fatigue in extended procedures. Hospital settings favor these systems where throughput economics prioritize mechanical reliability over energy sophistication.
Leading the category by volume: Power-Assisted Liposuction. Expanding most quickly: Laser Liposuction.
Application:
Procedure type determines reimbursement pathways and capital allocation priorities across ambulatory and institutional settings.
- Body Contouring:Comprehensive trunk and extremity sculpting procedures generate the highest device utilization rates. Brazilian cosmetic clinics allocate above-average capital expenditure to body contouring platforms as aesthetic demand mainstreams.
- Fat Removal:Targeted adipose reduction for functional or cosmetic indications. North American dermatology practices in California and Texas drive service contract unbundling for these systems.
- Breast Augmentation:Fat transfer and contour refinement procedures. European academic centers face EU MDR documentation burdens for multi-modality platforms used in complex cases.
- Liposuction for Face:Precision submental and facial sculpting with smaller cannula gauges. South Korean dermatology practices lead adoption of minimal invasive devices for facial applications.
Dominant by procedure volume: Body Contouring. Gaining share fastest: Liposuction for Face.
End User:
Facility type dictates purchasing autonomy, with independent practices fragmenting vendor consolidation strategies through component-level negotiation.
- Cosmetic Clinics:Private aesthetic practices with concentrated body contouring caseloads. Independent dermatology groups in Texas and California are separating device maintenance from consumable agreements to negotiate pricing independently.
- Hospitals:Institutional settings where throughput economics and capital budgeting cycles favor mechanical reliability. Power-assisted systems dominate procurement due to lower training thresholds and standardized maintenance protocols.
- Ambulatory Surgery Centers:Freestanding facilities requiring OSHA-compliant tumescent fluid aerosol management. EPA waste handling mandates create recurring revenue potential for manufacturers bundling filtration infrastructure.
- Dermatology Practices:Physician-owned settings driving minimal invasive device upgrades. South Korean dermatology practices are replacing conventional suction systems with energy-based platforms at scale.
Highest capital deployment: Cosmetic Clinics. Fastest technology refresh: Dermatology Practices.
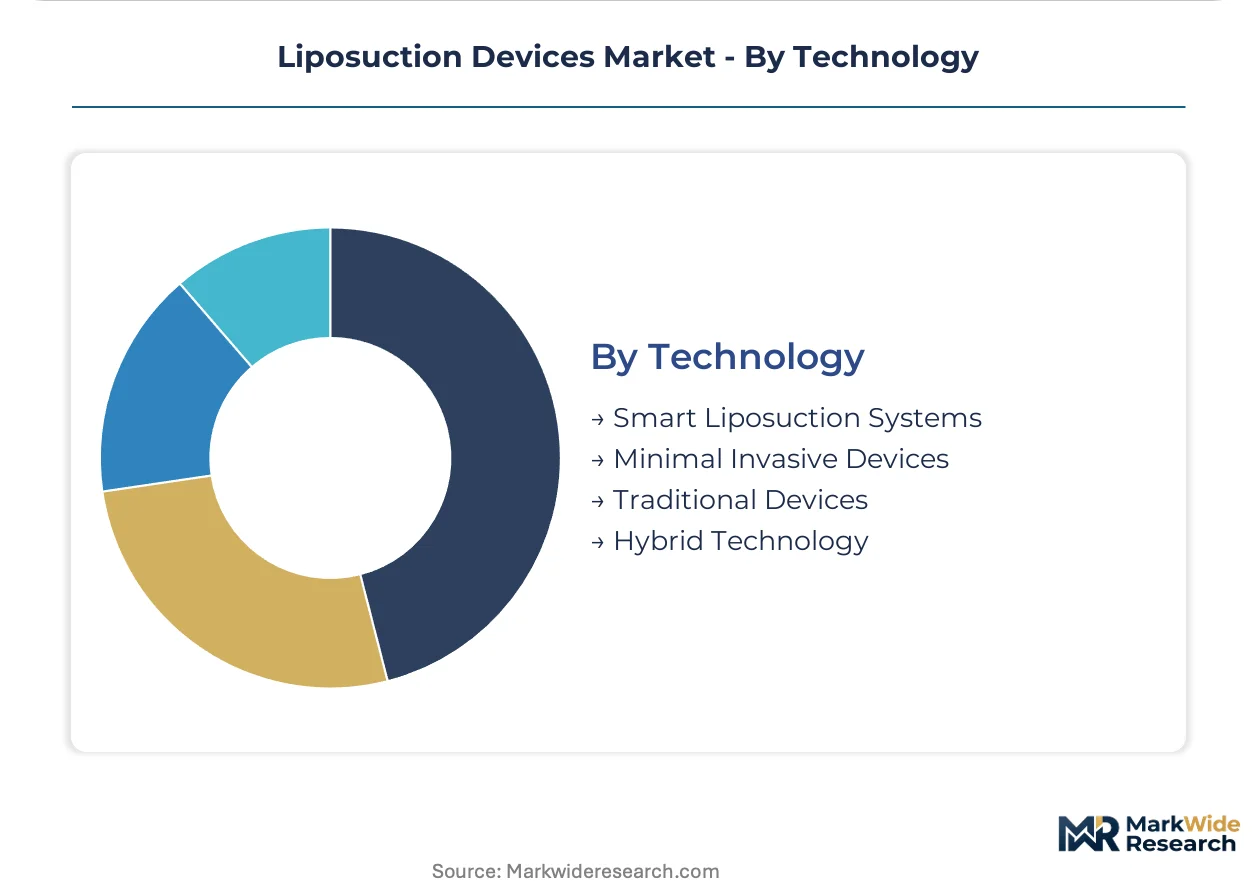
Technology:
Automation level and energy integration determine regulatory classification complexity and post-market surveillance obligations.
- Smart Liposuction Systems:Closed-loop feedback platforms synchronizing energy delivery with real-time tissue impedance monitoring. German academic medical centers pilot these systems for procedure standardization and training compression.
- Minimal Invasive Devices:Reduced-trauma platforms with smaller incision requirements and faster recovery profiles. South Korean manufacturers dominate this tier with concentrated demand from dermatology practice upgrades.
- Traditional Devices:Conventional suction-assisted systems without energy integration. Brazilian cosmetic clinics continue procuring these units for cost-sensitive expansion into secondary markets.
- Hybrid Technology:Multi-modality platforms combining laser and ultrasound energy. EU MDR technical documentation burdens and classification uncertainties delay market access, prompting South Korean manufacturers to segregate registrations by single-modality configurations.
Widest installed base: Traditional Devices. Steepest expansion trajectory: Minimal Invasive Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Israel and the United States, while consumption clusters in Brazil, South Korea, and Germany where aesthetic procedure volumes drive procurement. Regulatory divergence between FDA pathways and EU MDR timelines shapes regional market access strategies. Capital deployment patterns reflect this geographic split between production centers and high-volume clinical settings.
United States
FDA premarket notification tightening for laser-assisted platforms filters marginal competitors and concentrates procurement among certified vendors. OSHA tumescent fluid aerosol exposure limits mandate engineering controls that ambulatory surgery centers struggle to deploy. Independent dermatology groups in California and Texas drive service contract unbundling, separating device maintenance from consumable agreements.
Brazil
Cosmetic clinics in São Paulo and Rio de Janeiro metro markets expand device procurement as body contouring achieves mainstream acceptance. ANVISA medical device registration requirements create compliance thresholds for imported energy-based platforms. Brazilian practices allocate above-average capital expenditure to aesthetic platforms, replacing aging suction-assisted units with modern systems.
South Korea
Dermatology practices replace conventional suction systems with energy-based platforms at scale, creating concentrated demand pull for radiofrequency and laser modalities. MFDS medical device approval pathways favor minimal invasive device categories with established safety profiles. Seoul Capital Area clinics lead technology refresh cycles, upgrading to smaller-gauge cannula systems for facial applications.
Germany
Academic medical centers pilot radiofrequency-assisted platforms for high-volume revision cases and procedure standardization. EU MDR technical documentation burdens extend market access timelines for hybrid energy devices combining multiple modalities. Bavarian and North Rhine-Westphalian hospital networks favor power-assisted mechanical systems where throughput economics prioritize reliability.
Israel
Device manufacturers anchor production of energy-based aesthetic platforms serving export markets across Europe and North America. Israeli Ministry of Health medical device regulations align with CE marking requirements, facilitating parallel EU market entry. Tel Aviv-area technology clusters concentrate R&D capabilities for laser and radiofrequency system development.
Liposuction Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale advantages clash with segment depth. The vendor base organizes around three strategic archetypes: integrated platform vendors bundling consumables, precision mechanical specialists occupying surgical tiers, and energy-technology innovators monetizing through handpiece attach rates. Consolidation pressure operates through modular platform bundling that compresses standalone device margins. Geographic expansion and technology licensing represent the dominant competitive moves as manufacturers seek to circumvent EU MDR documentation burdens.
Within the integrated platform tier, Alma Lasers and Solta Medical exemplify vendors leveraging handpiece ecosystems to sustain recurring revenue streams. MicroAire Surgical Instruments occupies a position among precision-engineered mechanical specialists, anchoring the premium surgical tier where hospital throughput economics favor reliability. These three companies represent the competitive spectrum from consumable-dependent energy platforms to durable mechanical systems, with each archetype responding differently to regulatory tightening and procurement consolidation.
| Leading Market Players |
|---|
| Alma Lasers |
| Sciton |
| Solta Medical |
| Genesis Biosystems |
| Wells Johnson Company |
| Cynosure |
| MicroAire Surgical Instruments |
| Apyx Medical Corporation |
| InMode |
| Others |
Value Chain & Pricing Dynamics
Closed-loop feedback system integration is compressing production economics for precision cannula assemblies while concentrating supply leverage among Israeli and US-based energy platform manufacturers. This technology transition simultaneously elevates R&D amortization burdens and locks in component sourcing from specialized semiconductor foundries.
Pricing Analysis
Margin tightening in laser-assisted tiers reflects consumable handpiece dependency and extended reuse intervals at capital-constrained cosmetic clinics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared energy platforms from CE-marked mechanical systems and unbundled service contracts. Price differentiation hinges on certification tier and after-sales bundling intensity. Brazilian cosmetic clinics demonstrate highest price sensitivity, while South Korean dermatology practices absorb premium positioning for minimal invasive modalities.
Supply Chain Analysis
Direct-to-hospital channels handle power-assisted device demand, while distributor networks serve fragmented cosmetic clinic procurement. Manufacturing concentrates in Israel, the United States, and South Korea. Precision cannula fabrication draws from medical-grade stainless steel and ceramic bearing suppliers. Single-source vulnerability in solid-state laser diode sourcing creates exposure. Distribution runs through specialized aesthetic device distributors with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR documentation burdens are forcing mid-tier manufacturers toward exit or acquisition, consolidating viable vendor ranks around integrated platform specialists with compliance infrastructure.
For Market Incumbents: Hedge regulatory concentration risk by segregating hybrid technology registrations into single-modality configurations, mirroring South Korean manufacturer tactics. Deepen backward integration into consumable handpiece production to defend attach rate economics against service contract unbundling pressures from independent dermatology groups. For New Entrants and Emerging Players: Launch via ambulatory surgery center partnerships targeting EPA-compliant tumescent fluid management bundles. Brazilian secondary metro markets outside São Paulo and Rio de Janeiro present penetrable white space with above-average capital allocation but lower vendor saturation. Anchor positioning through power-assisted mechanical reliability rather than energy-based sophistication. For Investors and Strategic Acquirers: Exit pathways concentrate in platform bundling plays with established FDA 510(k) clearance portfolios and recurring consumable revenue. Five-to-ten year viability favors precision mechanical specialists with hospital throughput relationships over pure energy-technology innovators. Watch MFDS and ANVISA approval timeline acceleration as inflection signals for geographic demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | EU MDR technical documentation streamlining accelerates hybrid device market access timelines. |
| Consumable Handpiece Ecosystem Lock-in | Integrated platform bundling sustains recurring revenue against service contract unbundling pressures. |
| Hospital System Partnership Expansion | Power-assisted device penetration leverages throughput economics in institutional procurement cycles. |
| Software Companion Development | Closed-loop feedback algorithms compress training curves and standardize procedure outcomes. |
| Reimbursement Strategy Alignment | Tumescent fluid delivery integration expands addressable clinician base in ambulatory settings. |
Study Parameters
Multi-period observation of FDA 510(k) clearance volumes, EU MDR technical documentation filings, and ANVISA registration trends anchored the trend analysis, supplemented by interviews with aesthetic device procurement managers at hospital systems, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs leads at energy-platform manufacturers. Secondary validation drew from FDA 510(k) premarket notification database, EUDAMED vigilance reports, MFDS medical device approval records, and SEC 10-K equipment revenue disclosures. Bottom-up procedure volume estimates triangulated against top-down capital expenditure surveys across the analysis window.
Input-output matrices modeled unit shipments and average selling prices across product type, application, end user, and technology segmentation dimensions. CAGRs derived from logarithmic trend fitting of annual volume trajectories. Forecast inputs incorporated tumescent fluid delivery adoption curves and laser handpiece replacement cycle elasticity assumptions throughout the projection horizon.
Regulatory pathway delays, consumable attach rate volatility, and ambulatory center capital conservation cycles are the dominant revision risks. Forecasts reflect documented assumptions on technology refresh cadence and geographic demand concentration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Spirometers Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Italy Spinal Surgery Devices Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Brachytherapy Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Ocular Implants Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
EEG and EMG Equipment Market