
 Laryngeal Airway Mask Market | 2026-2036
Laryngeal Airway Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Laryngeal Airway Mask Market Foresight
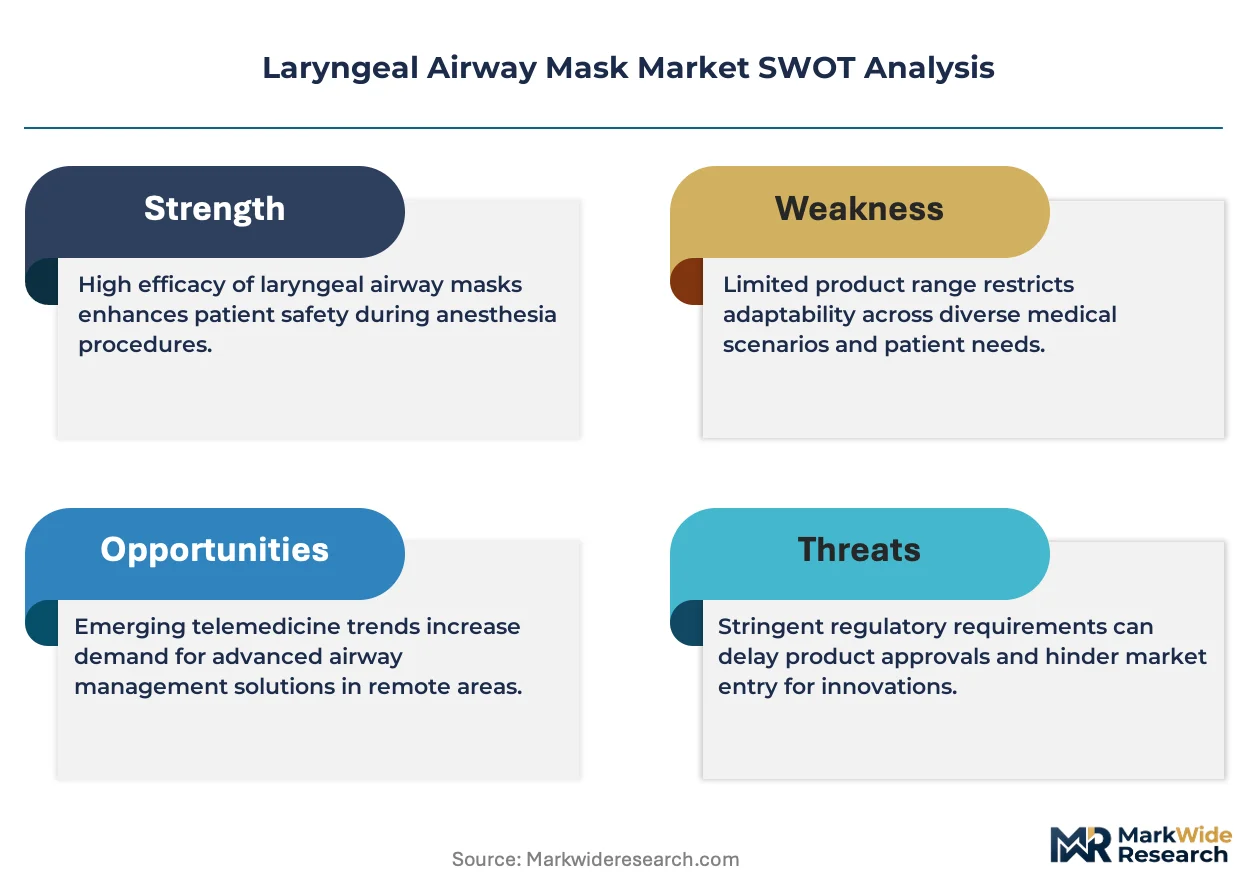
EU MDR is rebalancing the cost-of-entry calculus for laryngeal airway mask manufacturers by mandating extensive clinical evidence and quality management system upgrades. Teleflex Incorporated anchors North American hospital contracts through its intensive care airway portfolio. Medtronic Plc. dominates advanced material R&D, leveraging its silicone polymer expertise to differentiate performance under positive-pressure ventilation. Ambu A/S specializes in single-use anesthesia devices, competing aggressively on infection prevention value propositions.
A laryngeal airway mask is a supraglottic airway device consisting of an inflatable silicone or PVC cuff attached to a ventilation tube, designed to seal the perilaryngeal structures without endotracheal intubation during spontaneous or controlled ventilation. The device typically incorporates a gastric access channel for decompression and operates at cuff inflation pressures between 20 and 60 cm H₂O to maintain airway patency while minimizing mucosal perfusion compromise. Disposable silicone variants command premium positioning in anesthesia workflows due to their combination of thermal stability and elimination of cross-contamination risk. Reusable devices face structural pressure from hospital infection control committees prioritizing single-patient use, while customizable masks for difficult airway anatomy capture concentrated margin pools in tertiary surgical centers.
FDA 510(k) clearance pathways and ISO 10993 biocompatibility standards govern material safety validation for US-bound laryngeal masks, with FDA reviewers scrutinizing cuff seal reliability data under simulated vomiting scenarios. EMA's Medical Device Regulation imposes post-market surveillance obligations that extend liability across the distribution chain, compelling manufacturers to maintain European Authorized Representative infrastructure. Health Canada aligns with ISO 18562 biocompatibility testing for respiratory gas pathway devices, creating partial regulatory harmonization that simplifies multi-jurisdiction filings. Stakeholders must monitor evolving national reimbursement codes for single-use airway devices, as coverage determinations increasingly influence procurement committee decisions over capital equipment budgets.
Market Dynamics
Single-use device mandates from hospital infection control committees are compressing reusable mask economics and forcing manufacturers to reconfigure production lines toward disposable silicone variants with full lot traceability.
Growth Catalysts
- Ambulance service expansion:Emergency medical services in Germany and France are standardizing single-use supraglottic airways to eliminate cross-contamination during pre-hospital intubation scenarios.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations are accelerating documentation investments that favor established manufacturers with robust quality management systems.
- Silicone polymer thermal stability:Advanced cuff materials now maintain seal integrity across broader temperature ranges, enabling reliable performance in austere field environments.
Market Restraints
- Medical-grade silicone price volatility:Petrochemical feedstock fluctuations directly impact cuff manufacturing costs and squeeze margin structures for mid-tier producers.
- German procurement consortium concentration:Hospital buying groups in Bavaria and North Rhine-Westphalia extract volume discounts that compress pricing power across the value chain.
- Reusable device residual demand:Budget-constrained secondary care facilities in Southern Europe continue deploying autoclavable masks, fragmenting standardization efforts.
Strategic Opportunities
- Difficult airway customization:Tertiary surgical centers in Switzerland and Austria are commissioning patient-specific mask geometries based on preoperative imaging.
- Gastric access channel innovation:Dual-lumen designs incorporating active suction capabilities are capturing premium positioning in bariatric surgery workflows.
- Health Canada ISO 18562 harmonization:Aligned biocompatibility testing standards are reducing regulatory filing costs for North American market entry.
Industry Challenges
- Polymer engineering talent scarcity:Specialized silicone rheology expertise required for cuff inflation dynamics remains concentrated among a narrow cohort of materials scientists.
- EMA Authorized Representative infrastructure:Non-European manufacturers face sustained operational overhead maintaining European liability coverage and post-market surveillance capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laryngeal Airway Mask Market |
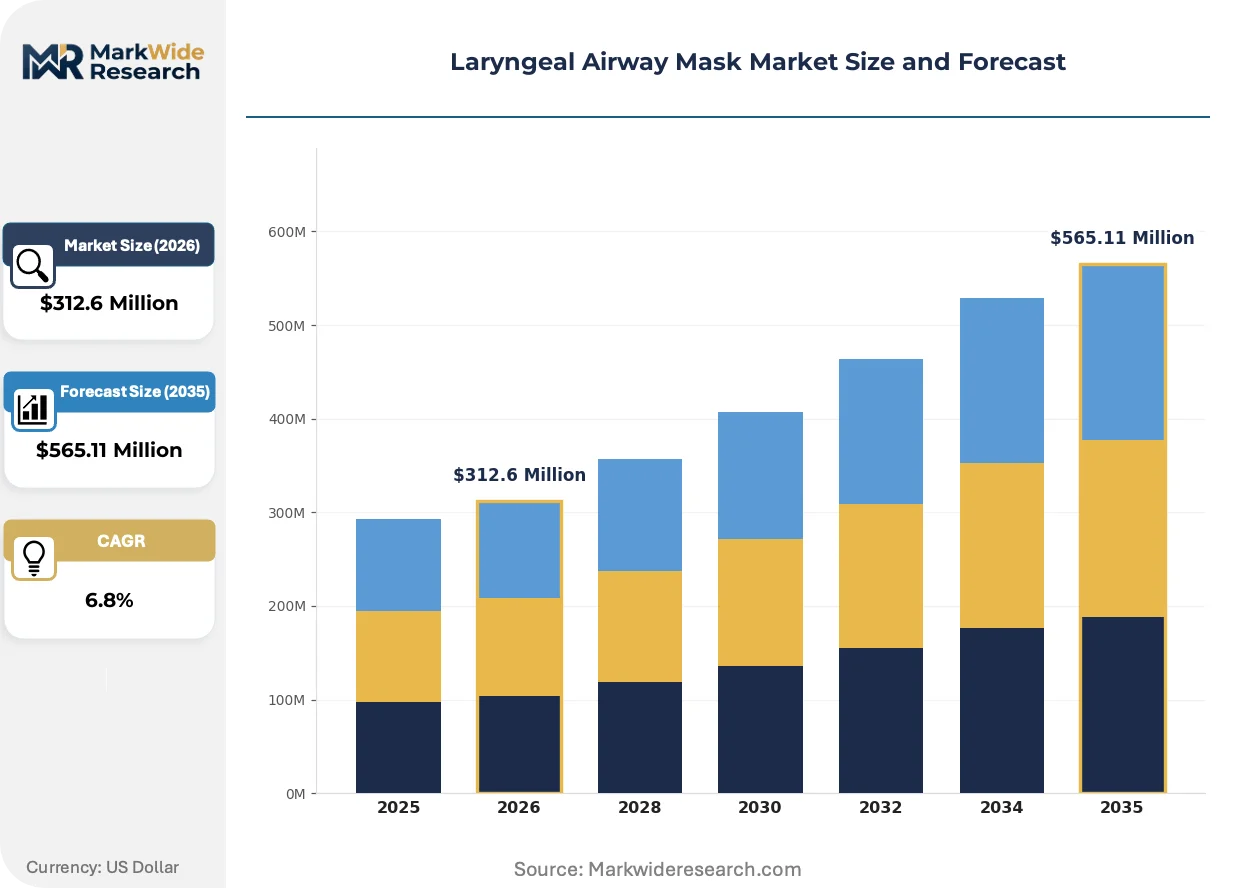
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Disposable, Customizable, Combitube Use Case: Emergency Care, Anesthesia, Resuscitation, Airway Management Material: Latex, Silicone, PVC, Thermoplastic End User: Hospitals, Clinics, Ambulance Services, Surgical Centers |
| Companies Covered | Intersurgical Ltd., Medline Industries, Inc., Teleflex Incorporated, Asid Bonz GmbH, Vyaire Medical Limited, Ambu A/S, Smiths Medical, SunMed, Medtronic Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laryngeal Airway Mask Market Shifts & Advancements
Digital manufacturing and regulatory data harmonization are restructuring how laryngeal mask specifications propagate from design benches to sterilization facilities.
3D-printed patient-specific mask molds are converging with preoperative CT segmentation workflows to produce anatomically matched supraglottic devices for anticipated difficult airways. Tertiary anesthesia departments in Zurich and Vienna are piloting these personalized fittings. The technology is converging with existing reusable silicone supply chains to compress customization lead times from weeks to days.
EMA's Medical Device Regulation post-market surveillance obligations are mandating systematic clinical follow-up data collection across the European distribution chain. Manufacturers must now maintain traceable adverse event reporting infrastructure that extends liability to authorized representatives. German hospital procurement consortia are prioritizing suppliers with demonstrated MDR compliance documentation over lower-cost alternatives.
Subscription-based device replenishment contracts are displacing traditional capital equipment purchasing in North American ambulatory surgery centers. Anesthesia groups in Texas and Florida are unbundling device supply from service agreements to capture per-procedure cost transparency. This model is most visible in multi-site outpatient networks seeking to standardize infection control protocols across geographically dispersed facilities.
Laryngeal Airway Mask Market Segmentation
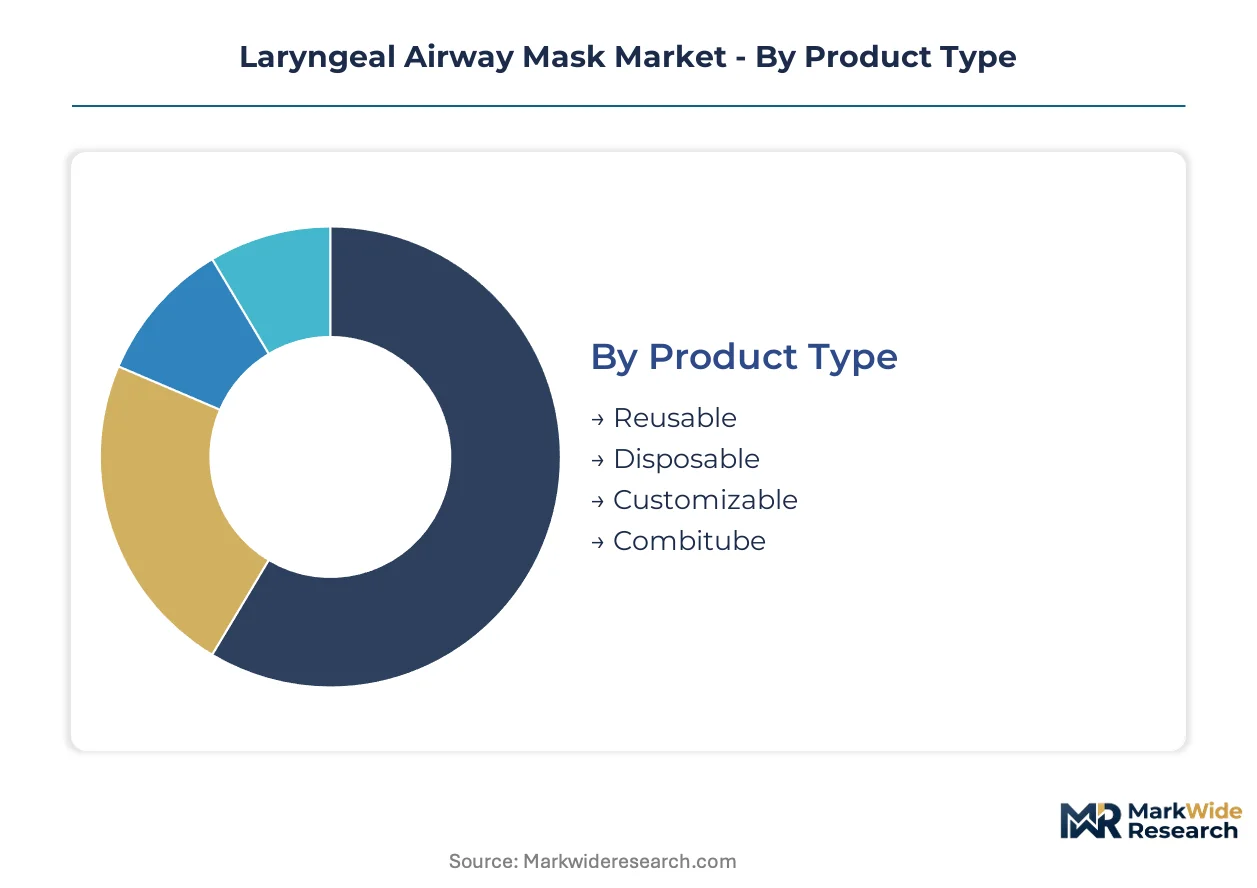
Segmentation in laryngeal airway masks reveals how procurement priorities diverge across clinical settings and regulatory environments. Manufacturers configure production capacity around infection control mandates, material biocompatibility requirements, and the procedural specificity of end-use applications.
Product Type:
Supply concentration clusters around manufacturers with validated sterilization infrastructure and polymer engineering capabilities that satisfy diverging hospital procurement standards.
- Disposable:Single-use silicone variants eliminate cross-contamination risk in anesthesia workflows. German hospital procurement consortia in Bavaria and North Rhine-Westphalia mandate full lot traceability for these devices, compressing pricing power for mid-tier producers.
- Reusable:Autoclavable masks constructed from medical-grade silicone withstand repeated sterilization cycles. Budget-constrained secondary care facilities in Southern Europe continue deploying these devices, fragmenting standardization efforts across the continent.
- Customizable:Patient-specific geometries based on preoperative imaging address anticipated difficult airways. Tertiary surgical centers in Switzerland and Austria commission these devices.
- Combitube:Dual-lumen esophageal-tracheal designs serve as rescue airways in failed intubation scenarios. Emergency medical services stock these for pre-hospital deployment.
Disposable variants absorb the bulk of installed capacity; customizable masks are expanding most quickly.
Use Case:
Cost tier stratification separates high-volume routine anesthesia from premium-priced emergency interventions requiring specialized device configurations.
- Anesthesia:Elective surgical procedures drive consistent demand for standard supraglottic airways with gastric access channels. Ambulatory surgery centers in Texas and Florida favor subscription-based replenishment contracts for these devices.
- Emergency Care:Pre-hospital intubation scenarios require rapid-deployment devices with reliable seal integrity across temperature extremes. Ambulance services in Germany and France standardize single-use supraglottic airways.
- Airway Management:Planned difficult airway protocols incorporate advanced cuff materials and imaging-compatible designs. Tertiary anesthesia departments stock these for anticipated complications.
- Resuscitation:Cardiac arrest protocols prioritize devices with minimal training requirements and high first-attempt success rates. Bystander-accessible public access defibrillator programs rarely include these specialized airways.
Anesthesia applications command the largest revenue share; emergency care is climbing the fastest as ambulance service standardization accelerates.
Material:
Volume concentration in silicone production reflects its thermal stability and EU MDR biocompatibility documentation advantages over alternative polymers.
- Silicone:Medical-grade polymer maintains cuff seal integrity across broad temperature ranges. Advanced silicone rheology expertise required for inflation dynamics remains concentrated among narrow cohorts of materials scientists.
- PVC:Lower-cost thermoplastic serves budget-sensitive procurement in emerging markets. Environmental disposal regulations constrain adoption in European healthcare systems.
- Thermoplastic:Injection-moldable alternatives enable rapid prototyping and design iteration. Device startups favor these for initial market testing.
- Latex:Natural rubber variants persist in limited legacy installations. Allergy prevalence has eliminated new adoption in regulated markets.
Silicone dominates current manufacturing throughput; thermoplastic formulations are gaining share fastest among prototype-stage manufacturers.
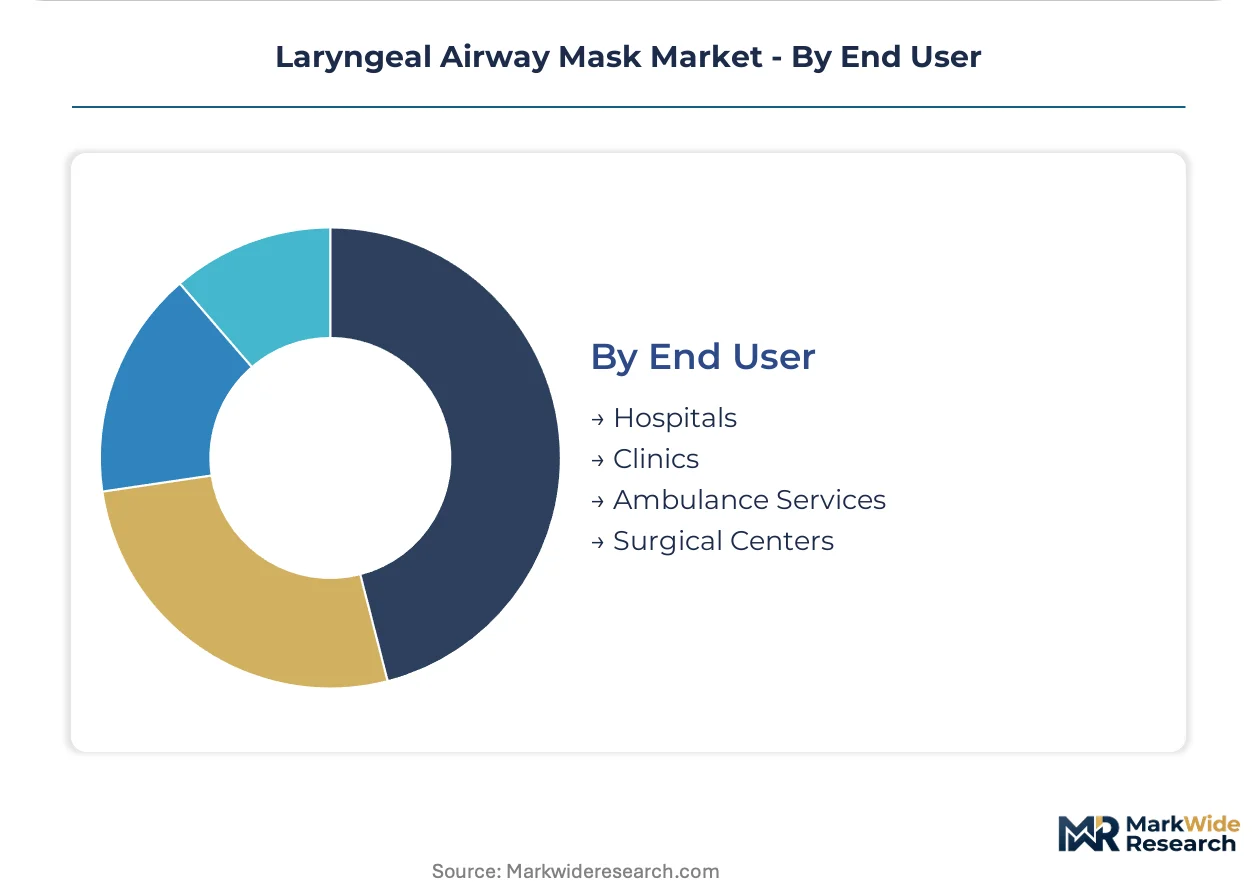
End User:
Customer type determines packaging configurations, regulatory documentation depth, and contracting structure from direct sales to group purchasing organizations.
- Hospitals:Inpatient surgical departments drive procurement of full-featured devices with gastric access and pressure monitoring ports. German hospital procurement consortia extract volume discounts that compress margin structures.
- Ambulance Services:Pre-hospital providers prioritize compact packaging and rapid deployment characteristics. French and German emergency medical services standardize single-use supraglottic airways.
- Surgical Centers:Ambulatory facilities favor subscription-based replenishment contracts over capital equipment purchasing. Multi-site outpatient networks in North America seek standardized infection control protocols.
- Clinics:Office-based procedures generate intermittent demand for basic supraglottic devices. Reimbursement coding uncertainties constrain procurement committee willingness to invest.
Hospitals account for the majority of installed base; ambulance services are expanding most quickly as pre-hospital standardization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device free trade zones in Costa Rica and Malaysia concentrate sterile manufacturing capacity for North American and Asian hospital supply chains respectively. These zones attract producers seeking tariff advantages and FDA-aligned quality infrastructure.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia mandate full lot traceability for disposable silicone masks. EU MDR post-market surveillance obligations compel manufacturers to maintain European Authorized Representative infrastructure. Tertiary surgical centers in Zurich and Vienna commission patient-specific geometries from German suppliers.
United States
Ambulatory surgery centers in Texas and Florida favor subscription-based replenishment contracts over capital equipment purchasing. FDA 510(k) clearance pathways govern material safety validation with scrutiny of cuff seal reliability data. Multi-site outpatient networks standardize infection control protocols across geographically dispersed facilities.
France
Emergency medical services standardize single-use supraglottic airways to eliminate cross-contamination during pre-hospital intubation. ANSM enforces biocompatibility documentation aligned with EU MDR requirements. Paris-region anesthesia departments pilot 3D-printed patient-specific mask molds converging with CT segmentation workflows.
Switzerland
Tertiary surgical centers commission customizable masks for anticipated difficult airway anatomy based on preoperative imaging. Swissmedic maintains stringent device registration requirements that favor established manufacturers with robust quality management systems. The Zurich medical technology cluster concentrates advanced polymer engineering talent for cuff inflation dynamics.
Canada
Health Canada aligns with ISO 18562 biocompatibility testing for respiratory gas pathway devices, simplifying multi-jurisdiction filings for North American market entry. Ontario and Quebec hospital networks prioritize suppliers with demonstrated MDR compliance documentation. Canadian ambulance services evaluate single-use device standardization for pre-hospital deployment.
Laryngeal Airway Mask Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. Tier-1 manufacturers leverage validated sterilization infrastructure and polymer engineering capabilities to satisfy diverging hospital procurement standards. Three archetypes dominate: diversified medical technology conglomerates with intensive care portfolios, single-use anesthesia device specialists, and regional contract manufacturers serving emerging markets. Consolidation pressures favor M&A activity among mid-tier producers lacking EU MDR compliance infrastructure, while technology licensing agreements proliferate for advanced silicone rheology expertise.
Within the diversified conglomerate tier, Teleflex Incorporated and Medtronic Plc. occupy positions anchored by intensive care airway portfolios and silicone polymer expertise respectively. Ambu A/S exemplifies the pure-play specialist archetype competing on infection prevention value propositions. Asid Bonz GmbH represents European mid-cap fabricators navigating procurement consortium pricing pressure. These named entities illustrate how geographic origin and company structure correlate with strategic positioning across disposable, reusable, and customizable product categories.
| Leading Market Players |
|---|
| Intersurgical Ltd. |
| Medline Industries, Inc. |
| Teleflex Incorporated |
| Asid Bonz GmbH |
| Vyaire Medical Limited |
| Ambu A/S |
| Smiths Medical |
| SunMed |
| Medtronic Plc. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EU MDR-compliant silicone masks and non-compliant alternatives manifests in both pricing premiums and supply chain restructuring. German hospital procurement consortia in Bavaria extract volume discounts that compress mid-tier margins, while manufacturers with validated sterilization infrastructure capture pricing power through lot-traceability guarantees.
Pricing Analysis
Short lead-time premiums distinguish emergency procurement from scheduled replenishment contracts in anesthesia workflows. Three-tier pricing structure across premium, standard, and economy levels separates customizable patient-specific geometries from disposable silicone variants and reusable autoclavable masks. Pricing pressure stems from German procurement consortium concentration extracting volume discounts. Budget-constrained secondary care facilities in Southern Europe exhibit highest price sensitivity; tertiary surgical centers in Switzerland demonstrate lowest sensitivity due to difficult-airway premium positioning.
Supply Chain Analysis
Specialized silicone rheology expertise availability concentrates in the Zurich medical technology cluster and select German polymer engineering hubs. Medical-grade silicone feedstock draws from petrochemical suppliers in Germany and Switzerland, with cuff manufacturing anchored in Costa Rica's medical device free trade zones and Malaysian sterile production facilities. Single-source vulnerability persists for advanced silicone polymer formulations. Distribution runs through hospital procurement consortia and group purchasing organizations in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR post-market surveillance obligations force weaker manufacturers lacking European Authorized Representative infrastructure toward exit or acquisition.
For Market Incumbents: Anticipate procurement committee demands for full lot traceability by deepening backward integration into medical-grade silicone compounding. Capture margin pools in customizable difficult-airway segments through preoperative imaging partnerships with tertiary anesthesia departments. Defend against mid-tier price compression by accelerating MDR compliance documentation investments that German hospital consortia now mandate. For New Entrants and Emerging Players: Launch via subscription-based replenishment contracts targeting North American ambulatory surgery centers in Texas and Florida. Penetrate the emergency care segment through compact-packaging single-use designs for German and French ambulance services. Exploit white space in thermoplastic prototype-stage manufacturing before silicone scale-up requirements crystallize. For Investors and Strategic Acquirers: Re-rating potential sits with EU MDR-compliant mid-cap fabricators given post-market surveillance infrastructure becoming a scarce, non-replicable asset. Long-term viability favors manufacturers with validated sterilization infrastructure and polymer engineering capabilities across the 5-10 year regulatory consolidation window. Watch German procurement consortium contract awards as inflection indicators for pricing power redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Infrastructure | European Authorized Representative capabilities satisfy post-market surveillance obligations across German hospital networks. |
| Silicone Polymer Backward Integration | In-house compounding of medical-grade silicone reduces cuff manufacturing cost volatility from petrochemical feedstock fluctuations. |
| Preoperative Imaging Partnership | CT segmentation workflows enable patient-specific mask geometries for tertiary surgical centers in Zurich and Vienna. |
| Ambulance Service Standardization | Single-use supraglottic airway contracts with French and German emergency medical services eliminate cross-contamination risk. |
| Subscription-Based Replenishment | Per-procedure cost transparency appeals to multi-site outpatient networks in Texas and Florida seeking infection control standardization. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, biomedical engineer consultations, and GPO contracts manager discussions underwrites the qualitative findings. Primary fieldwork engaged anesthesia department heads, infection control officers, and silicone polymer specialists. Secondary validation drew from FDA 510(k) filings, EMA Medical Device Regulation guidance documents, ISO 10993 biocompatibility standards, and hospital procurement database extracts. Bottom-up demand modeling triangulated against top-down manufacturer capacity assessments.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, use case, material composition, and end-user category. CAGRs were derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated EU MDR implementation timelines and ambulance service standardization trajectories.
The model assumes a particular technology adoption path; alternative pathways for 3D-printed patient-specific mask molds would alter the outlook. Forecasts reflect assumptions about silicone polymer thermal stability maintenance and German procurement consortium pricing discipline. Regulatory enforcement intensity and medical-grade silicone supply disruptions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Transilluminators Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Global Esophageal Catheters Market