
 Brazil Respiratory Devices Market | 2026-2036
Brazil Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Respiratory Devices Market Outlook
Respiratory therapist staffing shortages across Brazil's public health system is rotating investment toward automated ventilator platforms and remote patient monitoring tools. ResMed Inc. leverages its cloud-connected CPAP ecosystem to capture recurring revenue from home care channels. Koninklijke Philips NV sustains manufacturing scale through its Campinas facility, anchoring regional supply for Latin American markets. Medtronic differentiates via its intensive care ventilator portfolio, competing directly for contracts within Brazil's Unified Health System procurement cycles.
Brazil respiratory devices encompass mechanical apparatus engineered to assist, monitor, or restore pulmonary function through controlled gas delivery, pressure modulation, or aerosolized medication administration, with specifications typically spanning flow rates of 1–60 L/min and pressure ranges of 5–40 cm H₂O for acute care ventilators. These systems serve primarily to manage obstructive and restrictive lung pathologies across clinical and domiciliary environments. Inhalers occupy the largest volume position due to asthma and COPD prevalence, while oxygen concentrators generate expanding margin pools as home-based reimbursement broadens. Sleep apnea applications within the application dimension are attracting device makers seeking higher-attachment-rate therapy platforms.
ANVISA governs product registration, Good Manufacturing Practice certification, and post-market surveillance for all respiratory devices commercialized in Brazil, with import licensing requirements shaping market entry timelines for foreign suppliers. The Brazilian Health Regulatory Agency's alignment with International Medical Device Regulators Forum technical standards is compressing approval gaps versus FDA and EMA benchmarks. ANVISA's forthcoming risk-classification updates for software-enabled respiratory devices will reshape compliance obligations for manufacturers embedding AI-driven diagnostic algorithms. Stakeholders must monitor how ANVISA's digital health framework intersects with INMETRO certification requirements to anticipate competitive positioning shifts.
Market Dynamics
ANVISA's risk-classification overhaul for software-enabled respiratory devices is compressing approval timelines while elevating compliance burdens, forcing manufacturers to restructure their Brazil market entry strategies around embedded AI capabilities and cloud-connectivity requirements.
Growth Catalysts
- Home care reimbursement expansion:Brazil's Unified Health System is broadening coverage for domiciliary oxygen therapy and sleep apnea management, channeling demand toward portable concentrators and CPAP platforms.
- ANVISA-IMDRF alignment:The regulator's adoption of International Medical Device Regulators Forum technical standards is reducing registration gaps versus FDA and EMA benchmarks, accelerating foreign manufacturer market access.
- Southeastern hospital network concentration:São Paulo state's dense private clinic chains and public hospital procurement hubs generate concentrated demand pull for ventilator and nebulizer systems.
Market Restraints
- Import licensing friction:ANVISA's product registration and Good Manufacturing Practice certification requirements extend market entry timelines for foreign suppliers lacking established Brazil-based quality systems.
- Respiratory therapist scarcity:Staffing shortages across Brazil's public health system limit operational capacity for advanced ventilator platforms requiring specialized clinical oversight.
- INMETRO certification layering:Electrical safety and metrology standards add parallel compliance tracks to ANVISA medical device pathways, compounding certification costs for oxygen concentrator manufacturers.
Strategic Opportunities
- Northeastern underpenetration:Ceará and Pernambuco states exhibit lower device density per capita than São Paulo, creating whitespace for portable oxygen system distributors establishing regional service networks.
- Telemedicine-integrated monitoring:Remote patient monitoring tools converging with cloud-connected CPAP ecosystems enable recurring revenue models and therapy adherence tracking for home care channels.
- AI diagnostic algorithm embedding:ANVISA's forthcoming software-enabled device framework will reward manufacturers embedding predictive ventilation analytics with differentiated positioning in intensive care procurement cycles.
Industry Challenges
- Biomedical engineering talent gap:Brazil produces insufficient specialized technicians for ventilator maintenance and calibration, forcing manufacturers to build captive training infrastructure or absorb elevated service costs.
- Legacy system integration complexity:Hospital IT networks in Minas Gerais and Rio de Janeiro public facilities run fragmented electronic health record architectures, complicating cloud-connected device deployment and data interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Respiratory Devices Market |
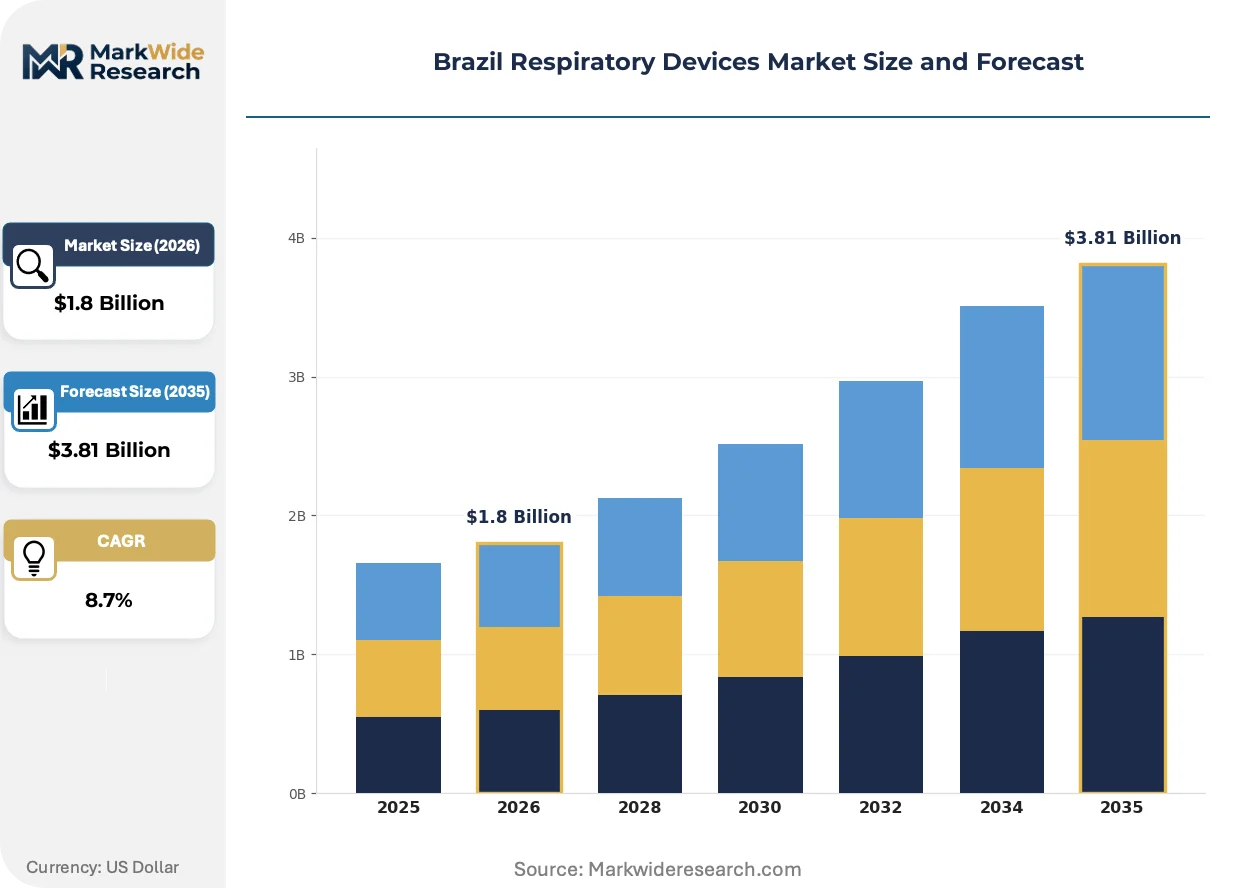
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, Ventilators Application: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Pulmonary Rehabilitation End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Delivery Mode: Metered Dose Inhaler, Dry Powder Inhaler, Jet Nebulizer, Ultrasonic Nebulizer |
| Companies Covered | ResMed Inc., Koninklijke Philips NV, Medtronic, Masimo, General Electric Company (GE HealthCare), Drägerwerk AG & Co. KGaA, Fisher & Paykel Healthcare Limited, Hamilton Medical, Chart Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Respiratory Devices Market Strategic Shifts
Cloud-connected respiratory platforms are restructuring competitive economics around recurring revenue streams rather than discrete equipment sales, while ANVISA's digital health framework is redrawing compliance boundaries for algorithm-enabled devices.
Modular ventilator architectures are decomposing traditional intensive care equipment into interoperable subsystems for ventilation, monitoring, and data analytics. Hospital networks in São Paulo are piloting component-swappable platforms to reduce capital outlays and accelerate upgrade cycles. This decomposition is compressing replacement timelines and enabling vendor-agnostic procurement strategies that fragment supplier lock-in.
ANVISA's alignment with International Medical Device Regulators Forum technical standards is harmonizing Brazil's registration pathways with FDA and EMA benchmarks. Foreign manufacturers now face reduced documentation duplication and accelerated timeline predictability for software-enabled respiratory devices. The sleep apnea and home oxygen therapy segments are responding by accelerating product portfolio submissions previously deferred due to regulatory uncertainty.
After-sales service unbundling is disrupting traditional device-plus-maintenance bundling in private clinic chains. Southeastern Brazil's diagnostic center networks are separating equipment acquisition from calibration contracts, sourcing maintenance from third-party biomedical service providers. This pattern is most visible in Rio de Janeiro's independent pulmonary function testing facilities, where procurement teams negotiate hardware and service contracts through distinct vendor relationships.
Brazil Respiratory Devices Market Segmentation
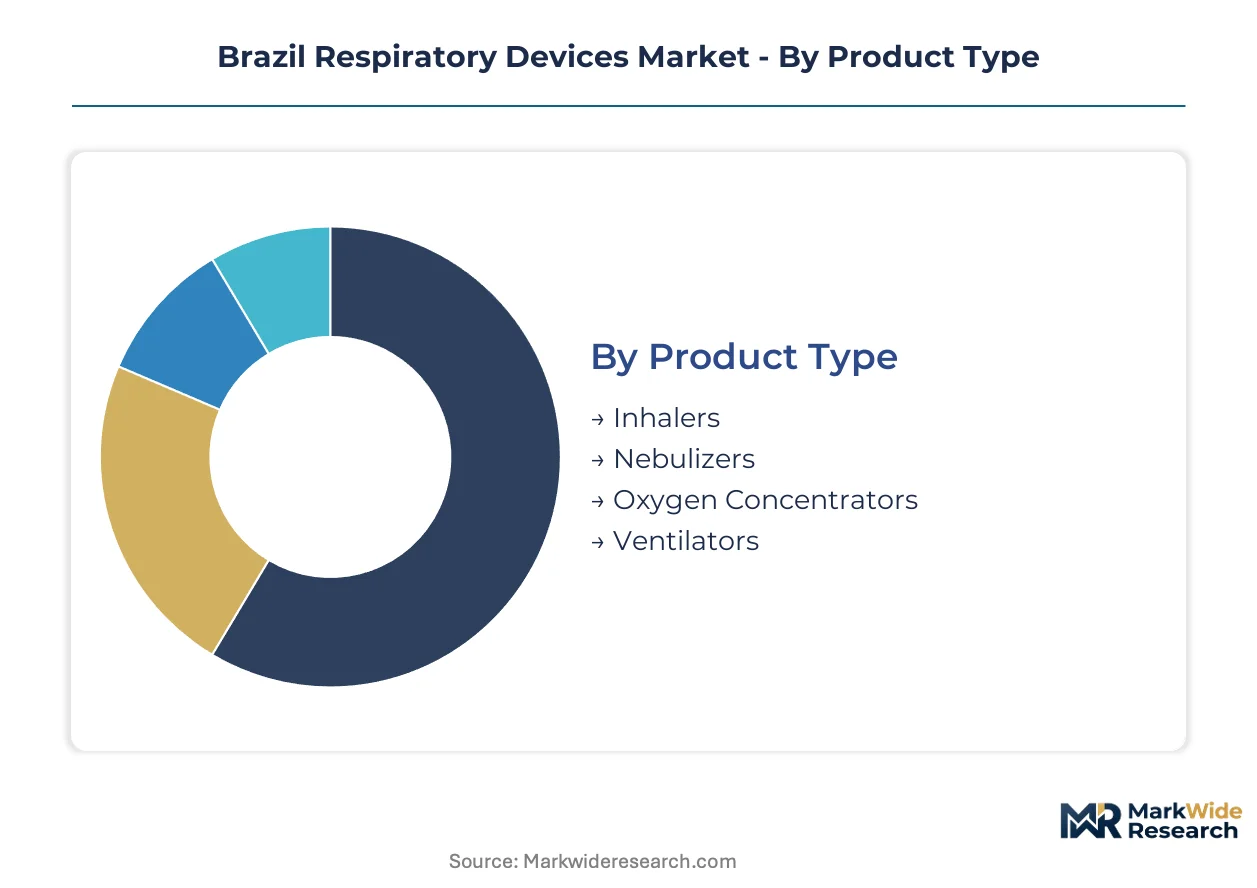
Respiratory device segmentation in Brazil tracks reimbursement pathways, clinical workflow requirements, and patient mobility needs across public and private healthcare channels. ANVISA's risk-classification tiers and INMETRO certification requirements create divergent compliance economics across product categories. Manufacturers configure portfolios around São Paulo state's procurement concentration while building service networks for northeastern expansion.
Product Type:
Margin pools concentrate in oxygen concentrators and ventilators, where technical complexity and after-service dependencies sustain premium pricing.
- Oxygen Concentrators:Electromechanical systems separate nitrogen from ambient air to deliver 90-95% oxygen purity at flow rates of 1-10 L/min for stationary units and 1-5 L/min for portable variants. São Paulo's home care reimbursement expansion is channeling procurement toward portable systems, though INMETRO electrical safety certification adds parallel compliance costs for manufacturers.
- Ventilators:Microprocessor-controlled platforms deliver volume-cycled or pressure-cycled ventilation across intensive care, emergency, and transport applications with typical pressure ranges of 5-40 cm H₂O. Brazil's public hospital network faces respiratory therapist scarcity, rotating investment toward automated platforms with embedded weaning protocols.
- Inhalers:Pressurized metered-dose and dry-powder devices for bronchodilator and corticosteroid delivery dominate prescription volume due to asthma and COPD prevalence.
- Nebulizers:Jet and ultrasonic systems aerosolize liquid medication for patients unable to coordinate inhaler technique, serving pediatric and geriatric populations.
The dominant share belongs to Inhalers, while Oxygen Concentrators is closing the gap fastest.
Application:
Volume distribution follows chronic disease burden patterns, with reimbursement policy shifts redirecting investment toward domiciliary management platforms.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requiring long-acting bronchodilator therapy, oxygen supplementation, and acute exacerbation management drives device procurement across Brazil's Unified Health System hospital networks. The disease burden concentrates in southeastern industrial corridors.
- Sleep Apnea:Obstructive sleep apnea diagnosis and continuous positive airway pressure therapy represent high-attachment-rate platforms with recurring consumable revenue. Cloud-connected CPAP ecosystems from manufacturers like ResMed are capturing home care channel loyalty through remote adherence monitoring.
- Asthma:Reversible airway obstruction in pediatric and adult populations sustains inhaler volume leadership despite lower per-patient device revenue.
- Pulmonary Rehabilitation:Post-acute and chronic respiratory failure recovery programs utilize oxygen concentrators and ventilatory support in supervised and home-based settings.
COPD commands the installed base, yet Sleep Apnea is expanding most quickly on recurring revenue economics.
End User:
Procurement authority and reimbursement eligibility split across facility types, with home care channels gaining policy support for cost-containment objectives.
- Hospitals:São Paulo state's dense network of public and private acute care facilities generates concentrated demand for intensive care ventilators and high-flow oxygen systems. ANVISA registration and Good Manufacturing Practice certification requirements shape vendor selection.
- Home Care:Domiciliary oxygen therapy and sleep apnea management reimbursement expansion is accelerating portable concentrator and CPAP adoption. Third-party biomedical service providers are unbundling maintenance from equipment acquisition in southeastern clinic chains.
- Clinics:Independent pulmonary function testing and diagnostic centers in Rio de Janeiro negotiate hardware and service contracts through distinct vendor relationships.
- Long-term Care Facilities:Post-acute and chronic care institutions utilize nebulizers and basic oxygen delivery for stable respiratory patients.
Hospitals retain procurement volume leadership, though Home Care is gaining share fastest on reimbursement policy tailwinds.
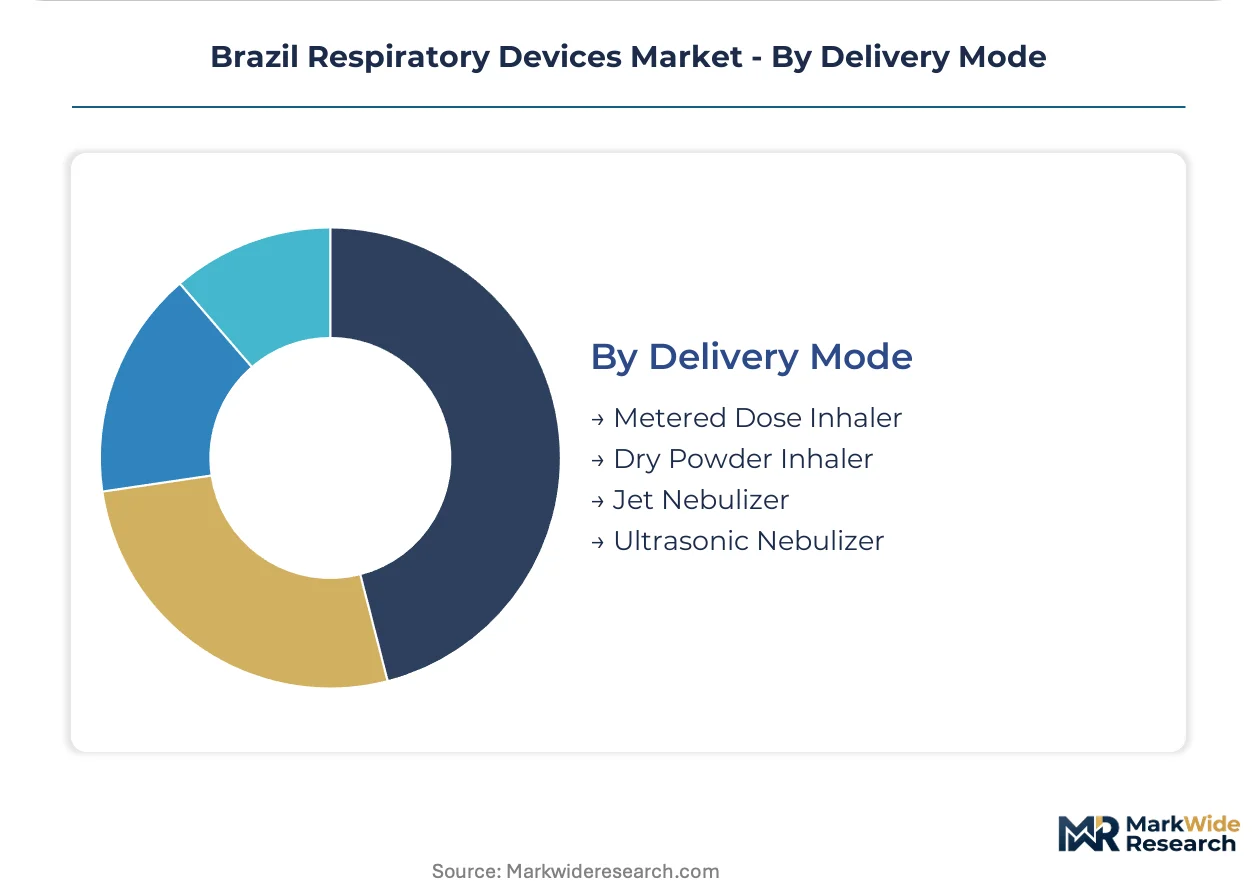
Delivery Mode:
Technology selection reflects patient coordination capability, medication formulation compatibility, and cost-tier positioning across public and private channels.
- Metered Dose Inhaler:Pressurized hydrofluoroalkane-propelled devices requiring hand-breath coordination dominate asthma maintenance therapy. Brazil's pharmaceutical supply chain ensures broad availability.
- Jet Nebulizer:Compressed-air systems generating 1-5 micron particle size for deep lung deposition serve patients with inadequate inhaler technique. Lower device cost sustains penetration in public health facilities.
- Dry Powder Inhaler:Breath-actuated systems eliminate coordination requirements but depend on sufficient inspiratory flow, limiting use in severe COPD.
- Ultrasonic Nebulizer:Piezoelectric crystal vibration produces finer aerosol with faster treatment times, commanding premium positioning in private clinic networks.
Metered Dose Inhaler holds prescription volume dominance, while Jet Nebulizer maintains cost-accessibility leadership in public procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's regulatory framework anchors demand concentration in southeastern Brazil, where São Paulo state's hospital networks and manufacturing infrastructure generate procurement gravity for ventilator and oxygen concentrator suppliers.
São Paulo
The state's dense network of public and private acute care facilities drives intensive care ventilator procurement through Brazil's Unified Health System tenders. ANVISA's Good Manufacturing Practice certification requirements shape vendor selection for equipment contracts. Campinas anchors regional manufacturing scale, with multinational producers sustaining Latin American supply distribution from this industrial cluster.
Minas Gerais
Belo Horizonte's hospital networks face respiratory therapist scarcity, accelerating investment toward automated ventilator platforms with embedded weaning protocols. The state's fragmented electronic health record architectures complicate cloud-connected device deployment in public facilities. Regional procurement hubs concentrate in the capital's metropolitan health district.
Rio de Janeiro
Independent pulmonary function testing facilities in the metropolitan area unbundle equipment acquisition from maintenance contracts, sourcing calibration through third-party biomedical service providers. Private clinic chains negotiate hardware and service agreements through distinct vendor relationships. The state's diagnostic center networks drive nebulizer and portable oxygen system demand.
Rio Grande do Sul
Porto Alegre's hospital networks participate in southern Brazil's medical device procurement consortia, aggregating ventilator and high-flow oxygen system purchases. The state's aging population demographic expands domiciliary oxygen therapy eligibility under reimbursement policy expansions. Regional distributors build service networks to capture home care channel growth.
Bahia
Salvador's public health system exhibits lower respiratory device density per capita than southeastern states, creating whitespace for portable oxygen system distributors establishing regional presence. Northeastern underpenetration attracts manufacturers seeking volume expansion beyond São Paulo's saturated procurement environment. State-level health secretariats pilot telemedicine-integrated monitoring programs for remote patient management.
Brazil Respiratory Devices Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Brazil's respiratory devices sector. The market structure consolidates around multinational manufacturers with established ANVISA registration pathways and captive service infrastructure, while regional distributors compete on logistics proximity and maintenance responsiveness. Three strategic archetypes dominate: integrated device-plus-service providers, component-specialist manufacturers, and cloud-connected platform vendors. Competitive moves center on after-sales service unbundling in private clinic chains and AI diagnostic algorithm embedding for intensive care procurement differentiation.
Among the integrated device-plus-service tier, ResMed Inc. and Koninklijke Philips NV exemplify archetypes competing through recurring revenue ecosystems and regional manufacturing scale respectively. Medtronic occupies a position within the intensive care ventilator segment, anchoring procurement competition for Brazil's Unified Health System contracts. These three manufacturers represent distinct strategic postures: cloud-connected platform dominance, captive regional production, and critical care portfolio depth.
| Leading Market Players |
|---|
| ResMed Inc. |
| Koninklijke Philips NV |
| Medtronic |
| Masimo |
| General Electric Company (GE HealthCare) |
| Drägerwerk AG & Co. KGaA |
| Fisher & Paykel Healthcare Limited |
| Hamilton Medical |
| Chart Industries |
| Others |
Value Chain & Pricing Dynamics
ANVISA's Good Manufacturing Practice certification gates both supplier qualification and price differentiation in Brazil's respiratory device sector, compressing margins for uncertified imports while rewarding established manufacturers with premium positioning in São Paulo's hospital procurement cycles.
Pricing Analysis
São Paulo state's private clinic chains command 15-20% price premiums over northeastern Brazil's public health facilities for identical ventilator platforms. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected intensive care systems from basic transport ventilators and refurbished emergency units. Cost compression in the economy tier is intensifying because third-party biomedical service providers are unbundling maintenance from equipment acquisition. Public hospital procurement committees exhibit highest price sensitivity, while home care channels accepting recurring revenue CPAP models show lowest sensitivity.
Supply Chain Analysis
China and Mexico anchor component manufacturing for Brazil's respiratory device importers, supplying piezoelectric sensors, microprocessor controllers, and compressor assemblies. Brazil-based assembly draws from these inputs plus domestic molded plastics and electrical harnesses. Single-source vulnerability concentrates in semiconductor chips for ventilator control systems, exposing manufacturers to allocation delays. Distribution runs through São Paulo state's medical device distributors, with regional logistics partners extending coverage to Salvador and Porto Alegre.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's respiratory device sector presents a defensive-moat story anchored in regulatory entrenchment: ANVISA's multi-year registration pathways and Good Manufacturing Practice certification requirements create switching costs that protect established vendors from rapid competitive displacement.
For Market Incumbents: Consolidate service infrastructure in southeastern Brazil to capture after-sales revenue unbundling trends in Rio de Janeiro's diagnostic center networks. Deepen backward integration into compressor manufacturing to offset import licensing friction for foreign components. Threat: Cloud-connected platform vendors like ResMed are capturing home care channel loyalty through recurring revenue ecosystems, displacing traditional equipment-plus-maintenance bundling. For New Entrants and Emerging Players: Lead with portable oxygen concentrator distribution in Ceará and Pernambuco states, where device density per capita trails São Paulo by 40-60%. Target telemedicine-integrated monitoring programs piloting in Bahia's state health secretariats. Go-to-market angle: Partner with third-party biomedical service providers to bypass captive training infrastructure requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap distributors holding ANVISA registration portfolios but lacking cloud-connected platform capabilities. Long-term viability over a 5-10 year window hinges on AI diagnostic algorithm embedding for intensive care procurement differentiation. Signal to watch: ANVISA's forthcoming software-enabled device framework adoption rates among portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Acceleration | Compresses market entry timelines for software-enabled ventilator platforms versus FDA-aligned documentation. |
| Cloud-Connected CPAP Ecosystem Development | Captures recurring revenue from home care channels through remote adherence monitoring in São Paulo state. |
| Regional Service Network Expansion | Enables portable oxygen system penetration in northeastern Brazil's underpenetrated Ceará and Pernambuco markets. |
| AI Diagnostic Algorithm Embedding | Differentiates intensive care ventilator positioning in Brazil's Unified Health System procurement cycles. |
| Third-Party Biomedical Service Partnership | Addresses respiratory therapist scarcity through outsourced calibration and maintenance in Minas Gerais public facilities. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with respiratory device executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through ANVISA registration databases, hospital procurement records, and INMETRO certification filings. Bottom-up triangulation cross-checked distributor shipment data against top-down reconciliation with Brazil's Unified Health System expenditure reports.
Across the projection horizon, the analytical framework modeled volume and value outputs across product type, application, end user, and delivery mode segmentation dimensions. CAGRs were derived from regression analysis of historical procurement cycles and reimbursement policy trajectories. Forecast inputs incorporated respiratory therapist staffing ratios, home care reimbursement expansion rates, and cloud-connected device adoption curves.
The analysis sits within stated boundaries; outcomes outside ANVISA's risk-classification overhaul timeline or northeastern telemedicine pilot scaling would require recalibration. Forecasts reflect assumptions around import licensing efficiency and INMETRO certification harmonization. Recalibration cycles align with material shifts in ANVISA digital health framework implementation and Unified Health System procurement policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
PET Injectors Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Allografts Market
Medical Devices
Urometer Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Small Bowel Enteroscopes Market