
 UK Surgical Devices Market | 2026-2036
UK Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
UK Surgical Devices Market Insights
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape between legacy manufacturers with notified body relationships and newer entrants facing extended conformity assessment timelines. Medtronic leverages its vertically integrated supply chain to sustain margin pressure from notified body backlogs. CMR Surgical specializes in domestic robotic platform development, anchoring its position within NHS England's innovation procurement frameworks. Smith & Nephew navigates the transition by extending its UK-based manufacturing footprint to reduce third-party certification dependencies.
Surgical devices encompass precision-engineered instruments, powered equipment, and integrated systems designed for tissue manipulation, hemostasis, and visualization during operative procedures, typically manufactured from medical-grade stainless steel, titanium alloys, or polymer composites with tolerances measured in micrometers. Electrosurgical devices and surgical robotics represent the fastest-expanding product categories, with margin pools concentrating in capital equipment bundled with multi-year service contracts. Hospitals dominate end-user procurement, though ambulatory surgical centers are capturing volume as NHS England pushes day-case surgery targets through minimally invasive technology adoption.
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit, while NHS England's MedTech Funding Mandate shapes reimbursement-accessible innovation pathways for device manufacturers. The General Data Protection Regulation, retained in UK law, imposes additional constraints on connected surgical devices transmitting patient data to cloud-based analytics platforms. Stakeholders must monitor divergence between UK and EU regulatory frameworks when allocating R&D budgets across certification pathways.
Market Dynamics
NHS England's centralized commissioning is consolidating procurement volume into specialist surgical hubs, forcing manufacturers to reconfigure distribution networks around fewer, higher-volume accounts while navigating divergent UKCA and CE marking pathways.
Growth Catalysts
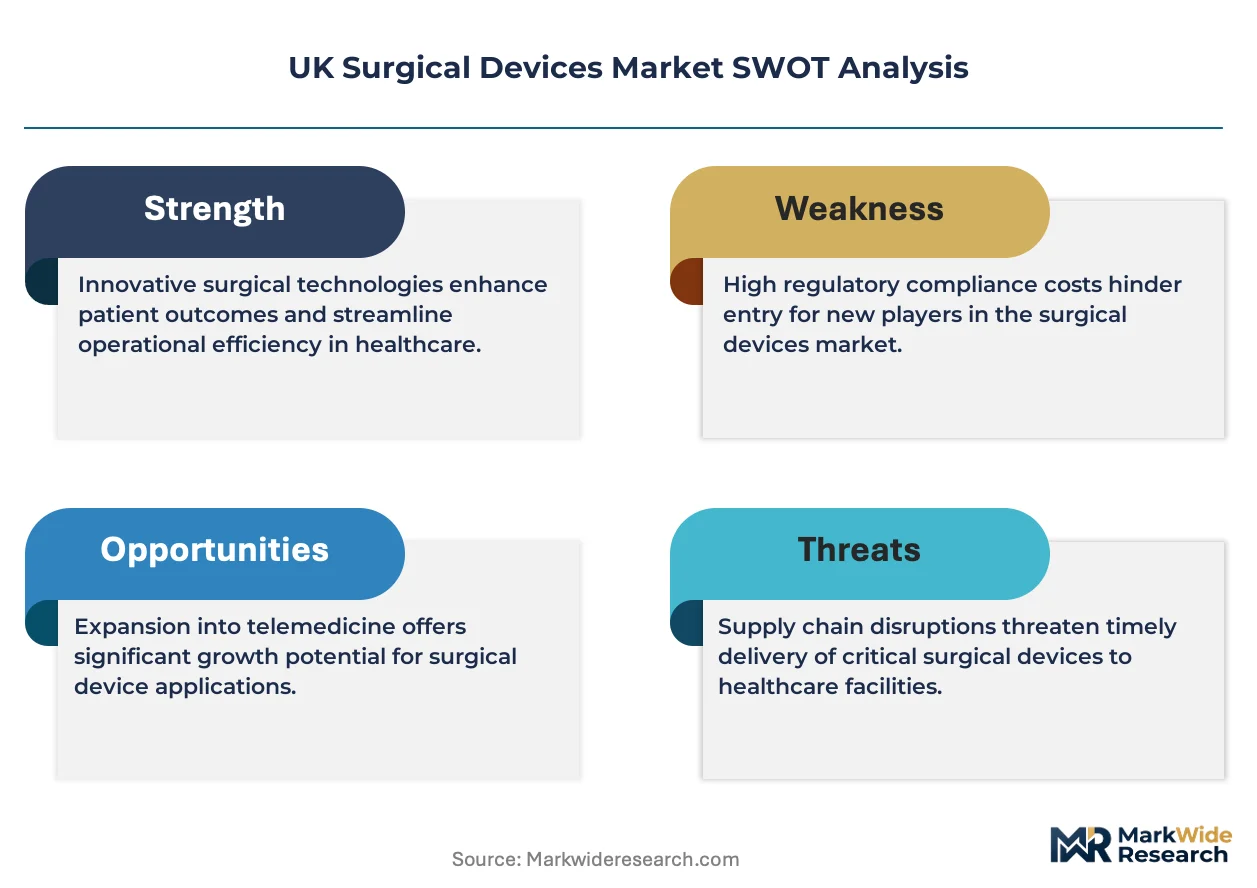
- MedTech Funding Mandate:NHS England's reimbursement-accessible innovation pathway accelerates adoption of breakthrough surgical technologies in specialist hubs.
- Robotic-assisted surgery:Precision tissue manipulation capabilities expand addressable procedure volumes across oncology and orthopedic verticals.
- Day-case surgery targets:England's ambulatory surgical centers capture volume through minimally invasive technology deployment.
Market Restraints
- Notified body backlogs:Extended UKCA conformity assessment timelines delay market entry for emerging device categories.
- Medical-grade titanium supply:Concentrated global smelter capacity exposes manufacturers to input cost volatility and allocation risk.
- GDPR-retained constraints:Cloud-connected surgical devices face additional compliance burdens for patient data transmission to analytics platforms.
Strategic Opportunities
- Scotland and Wales expansion:Underpenetrated regional health boards outside England's hub concentration offer volume growth potential.
- Multi-year service bundling:Capital equipment contracts with captive maintenance revenue streams deepen customer lock-in.
- AI-integrated visualization:Convergence of machine learning and surgical optics creates premium pricing tiers for real-time tissue analysis.
Industry Challenges
- Robotic surgery technician scarcity:NHS England's specialist hubs compete for limited trained personnel to operate complex capital equipment.
- Dual certification burden:Manufacturers must maintain parallel UKCA and CE marking processes as UK-EU regulatory divergence widens.
- Legacy system integration:New robotic platforms require costly interoperability workarounds with existing hospital IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Surgical Devices Market |
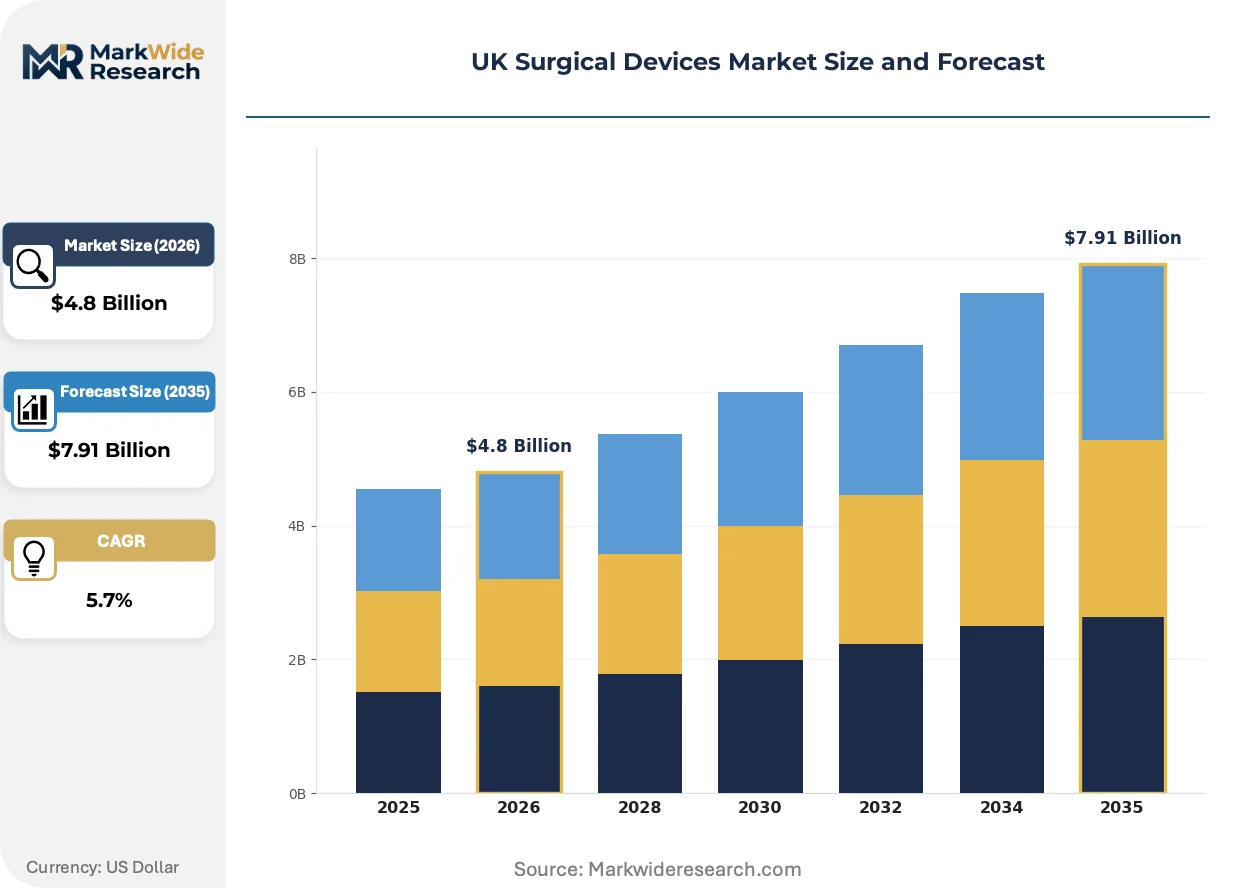
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Electrosurgical Devices, Imaging Systems, Surgical Robotics Application: Orthopedic, Cardiac, Gastrointestinal, Neurological End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Minimally Invasive Surgery, Laser Surgery, Robotic-Assisted Surgery, Computer-Assisted Surgery |
| Companies Covered | Medtronic, Stryker, Johnson & Johnson, Boston Scientific, Smith & Nephew, CMR Surgical, B. Braun, Olympus, ConvaTec Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Surgical Devices Market Trends and Innovations
Surgical robotics and electrosurgical platforms are fragmenting traditional instrument categories while regulatory divergence between UK and EU frameworks forces parallel certification investments from device manufacturers.
Single-port robotic systems are decomposing the conventional multi-arm surgical robot architecture into compact, modular configurations. NHS England's specialist hubs in London and Manchester are piloting these platforms for colorectal and gynecological procedures. The technology is decomposing capital equipment procurement into smaller, procedure-specific investments rather than hospital-wide system commitments.
The Medicines and Healthcare products Regulatory Agency's tightened post-market surveillance requirements are extending clinical evidence obligations for high-risk surgical devices. Manufacturers must now maintain active safety monitoring beyond initial UKCA certification. Electrosurgical devices with novel energy modalities face the steepest compliance burden as MHRA scrutinizes thermal spread data.
Hospital procurement teams are consolidating vendor relationships around integrated platform suppliers capable of spanning capital equipment, disposables, and multi-year service contracts. Traditional instrument distributors lose share to direct manufacturer engagements in England's hub structure. The shift is most pronounced in Greater Manchester's consolidated surgical network, where single-source negotiations replace fragmented specialty purchasing.
UK Surgical Devices Market Segmentation
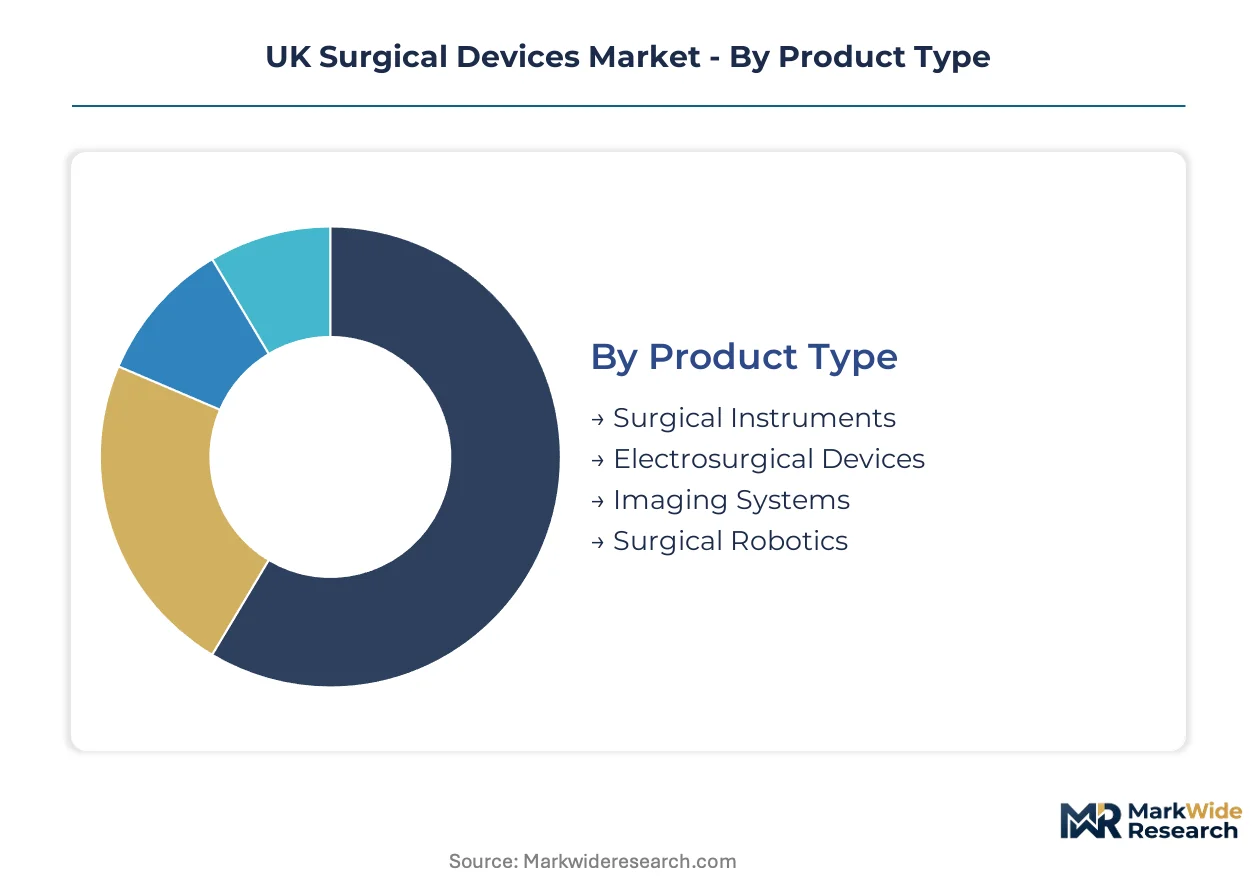
Segmentation in the UK surgical devices market reveals how NHS England's hub consolidation and post-Brexit regulatory divergence reshape procurement patterns across product categories. Understanding these divides exposes where manufacturers must reconfigure distribution networks and certification investments.
Product Type:
Domestic demand concentrates in capital equipment categories serving England's specialist surgical hubs, while export-oriented instrument segments face margin pressure from notified body backlogs.
- Surgical Instruments:Precision-engineered scalpels, forceps, and retractors manufactured from medical-grade stainless steel or titanium alloys with micrometer tolerances. NHS hospital procurement teams in London and Manchester consolidate volume around instrument sets bundled with sterilization validation services.
- Electrosurgical Devices:Radiofrequency and ultrasonic energy platforms for tissue cutting and coagulation. The Medicines and Healthcare products Regulatory Agency's tightened post-market surveillance extends clinical evidence obligations for novel energy modalities.
- Imaging Systems:Intraoperative visualization hardware for real-time anatomical navigation.
- Surgical Robotics:Capital equipment platforms with multi-year service contracts dominating procurement negotiations in Greater Manchester's consolidated network.
Surgical Instruments commands the established base. The steepest expansion runs through Surgical Robotics.
Application:
Procedure volume distribution tracks NHS England's day-case surgery targets and the geographic concentration of specialist surgical expertise.
- Orthopedic:Joint replacement and trauma fixation procedures. Ambulatory surgical centers in England capture volume through minimally invasive arthroscopic techniques aligned with NHS day-case targets.
- Cardiac:Coronary bypass and valve repair interventions requiring high-complexity infrastructure. London's specialist hubs maintain concentration of cardiothoracic surgical capacity and associated device procurement.
- Gastrointestinal:Colorectal resections and upper GI procedures.
- Neurological:Cranial and spinal interventions demanding precision navigation systems.
Orthopedic anchors procurement volume through ambulatory expansion. Cardiac retains premium pricing power through hub concentration.
End User:
Customer-type segmentation exposes the procurement power shift from distributed specialty purchasing to centralized hub negotiations.
- Hospitals:Acute NHS trusts and private hospital groups. England's specialist surgical hubs in London and Manchester consolidate vendor relationships around integrated platform suppliers capable of spanning capital equipment, disposables, and service contracts.
- Ambulatory Surgical Centers:Day-case facilities capturing volume from NHS England's push toward minimally invasive outpatient procedures. Procurement teams here prioritize compact, procedure-specific capital investments over hospital-wide system commitments.
- Specialty Clinics:Ophthalmology and dermatology-focused outpatient facilities.
- Research Laboratories:Academic medical centers and translational research institutes.
Hospitals dominate absolute spend. Ambulatory Surgical Centers are climbing the fastest as day-case targets redirect procedure volume.
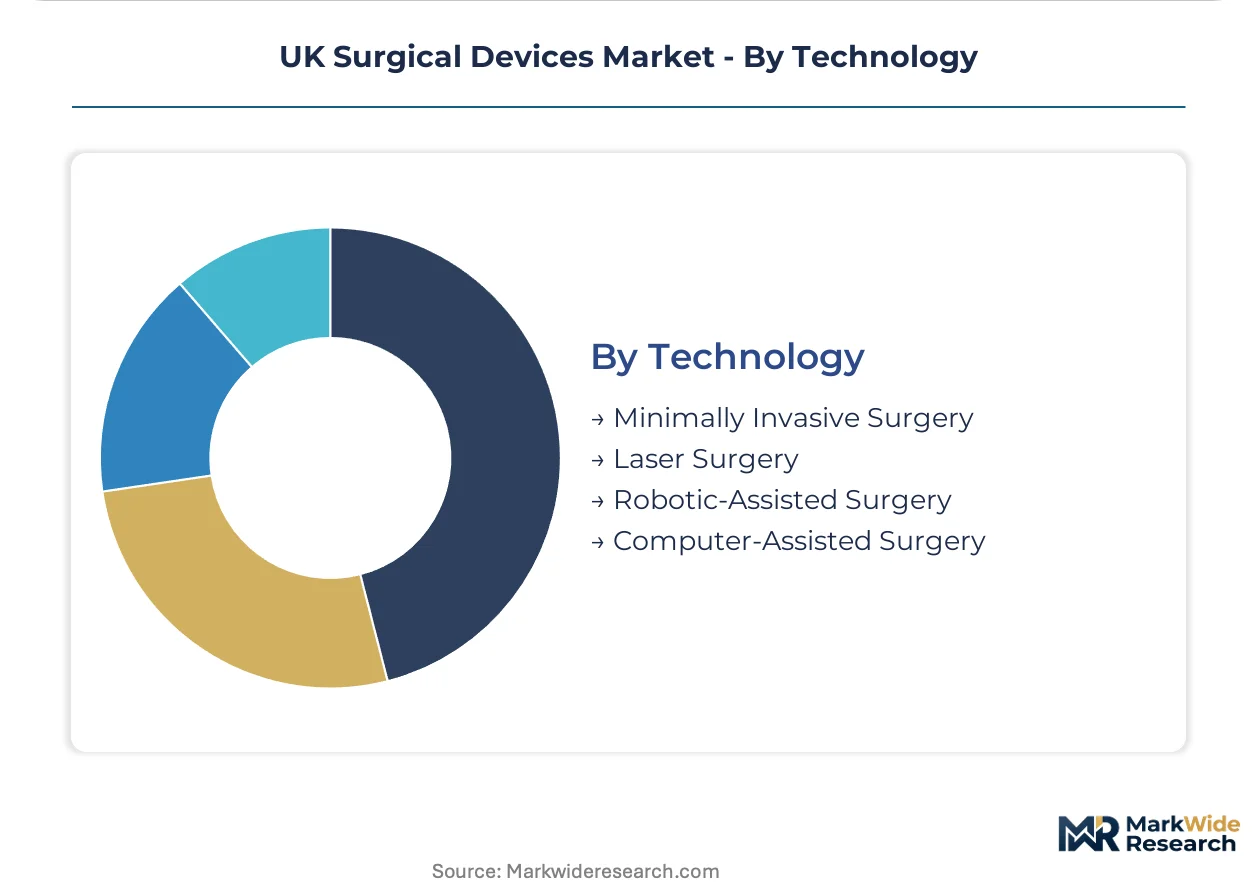
Technology:
Technology-based segmentation reveals where AI convergence and regulatory divergence create parallel certification burdens for manufacturers.
- Minimally Invasive Surgery:Laparoscopic and endoscopic techniques reducing tissue trauma. Scotland and Wales health boards outside England's hub concentration offer underpenetrated expansion potential for MIS platform deployment.
- Robotic-Assisted Surgery:Automated precision platforms for tissue manipulation. The General Data Protection Regulation, retained in UK law, imposes constraints on cloud-connected devices transmitting patient data to analytics platforms.
- Laser Surgery:Photonic energy delivery systems for soft tissue procedures.
- Computer-Assisted Surgery:Navigation and planning software integrated with imaging systems.
Minimally Invasive Surgery holds the installed base. Robotic-Assisted Surgery is gaining share fastest through NHS innovation procurement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East Coast Main Line electrification and Crossrail infrastructure anchor England's concentration of specialist surgical capacity, while devolved health administrations in Scotland and Wales operate distinct procurement frameworks outside NHS England's hub consolidation model.
London and Southeast England
Specialist surgical hubs in London concentrate robotic-assisted procedure volumes for oncology and cardiothoracic interventions. NHS England's MedTech Funding Mandate prioritizes innovation procurement through these capital-rich trusts. Guy's and St Thomas' NHS Foundation Trust anchors the capital's robotic surgery network, negotiating direct manufacturer engagements that bypass traditional distribution channels.
Greater Manchester and North England
Consolidated commissioning across Greater Manchester's integrated care system drives single-source negotiations for capital equipment bundles. The region's specialist surgical hub captures orthopedic and gastrointestinal procedure volumes from surrounding catchment areas. Manchester University NHS Foundation Trust leads platform standardization efforts, reducing vendor fragmentation across its hospital network.
Scotland
NHS Scotland operates separate procurement through National Procurement, with health boards maintaining independent device evaluation pathways. The country's concentration of medical research institutes in Edinburgh and Glasgow creates demand for translational surgical platforms. NHS Greater Glasgow and Clyde manages the largest surgical volume outside England, piloting minimally invasive technologies through its academic medical center infrastructure.
Wales
Health Technology Wales conducts distinct health technology assessments for surgical device adoption, operating parallel to NICE guidance applicable in England. The country's smaller hospital network limits capital equipment procurement scale, favoring multi-site shared service arrangements. Cardiff and Vale University Health Board coordinates specialized surgical capacity for South Wales populations.
Midlands
University Hospitals Birmingham NHS Foundation Trust anchors robotic surgery deployment in England's second-largest city, serving as a referral center for complex procedures from surrounding regions. The Midlands' manufacturing heritage supports local sterilization services and instrument reprocessing infrastructure. Birmingham's specialist hub status attracts day-case surgery volume through ambulatory surgical center partnerships.
UK Surgical Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital equipment financing structures, creating a tiered vendor landscape where publicly traded manufacturers leverage balance sheet capacity for multi-year service contracts while private firms pursue niche platform development. The market consolidates around integrated platform suppliers capable of spanning disposables, capital equipment, and captive maintenance revenue. Three archetypes dominate: diversified medtech conglomerates with vertical supply chains, domestic robotic specialists leveraging NHS innovation frameworks, and European instrument manufacturers with notified body relationships. Competitive positioning hinges on multi-year service bundling and backward integration into medical-grade material supply.
Among the diversified conglomerates, Medtronic and Stryker occupy positions as archetypal integrated platform suppliers, while CMR Surgical exemplifies the domestic specialist model anchored in NHS England's innovation procurement pathways. Smith & Nephew represents the European instrument manufacturer archetype navigating dual UKCA and CE marking certification burdens. These three patterns illustrate how scale, geographic origin, and regulatory positioning stratify competitive access to England's consolidating specialist surgical hubs.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Boston Scientific |
| Smith & Nephew |
| CMR Surgical |
| B. Braun |
| Olympus |
| ConvaTec Group |
| Others |
Pricing and Supply Chain Analysis
Capital equipment utilization rates in England's specialist surgical hubs create procurement leverage that compresses price floors for instrument manufacturers while elevating margin capture for integrated platform suppliers. NHS England's consolidated commissioning concentrates volume into fewer accounts, enabling these buyers to extract steeper volume discounts from fragmented instrument vendors.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations across NHS England's hub network, with three-tier pricing separating robotic platform bundles from standard instrument sets and commodity disposables. Price differentiation rests on UKCA certification status and multi-year service bundling depth, with notified body backlogs intensifying cost compression in emerging device categories. Ambulatory surgical centers exhibit acute price sensitivity due to capital constraints, while London's specialist trusts maintain pricing power through innovation procurement mandates.
Supply Chain Analysis
Strategic stockpiling of medical-grade titanium and polymer composites supersedes just-in-time preferences as manufacturers buffer against smelter allocation risk and notified body certification delays. Supply draws from Germany, Switzerland, and the United States for precision-machined components, with medical-grade titanium feedstock anchored in concentrated global smelter capacity. Single-source vulnerability in robotic servo motor supply creates structural exposure, while distribution runs through direct manufacturer engagements in Greater Manchester's consolidated network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against single-port robotic systems that decompose traditional multi-arm architecture into modular, procedure-specific investments. Incumbents must navigate this technology fragmentation while preserving service contract capture.
For Market Incumbents: Fortify platform stickiness through captive maintenance revenue streams and backward integration into medical-grade material supply. Deepen UKCA certification investments ahead of regulatory divergence to extend conformity assessment timelines for emerging competitors. Prioritize interoperability workarounds that lock robotic platforms into existing hospital IT infrastructure.
For New Entrants and Emerging Players: MHRA's innovation pathway fast-track offers regulatory arbitrage for breakthrough surgical technologies targeting underpenetrated Scotland and Wales health boards. Scotland's National Procurement operates distinct evaluation frameworks outside England's hub concentration. Pursue compact, procedure-specific capital investments aligned with ambulatory surgical center procurement priorities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic robotic specialists with NHS innovation framework anchoring over diversified conglomerates facing margin pressure from notified body backlogs. Long-term viability hinges on multi-year service contract depth rather than hardware shipment volume. Monitor MHRA post-market surveillance enforcement intensity as inflection indicator for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Certification Fast-Track | MHRA's innovation pathway accelerates market entry for breakthrough surgical technologies in specialist hubs. |
| Multi-Year Service Bundling | Captive maintenance revenue streams deepen customer lock-in across Greater Manchester's consolidated network. |
| Backward Integration | In-house production of medical-grade titanium components reduces third-party certification dependencies and input volatility. |
| Ambulatory Partnership | Direct engagements with day-case facilities capture volume from NHS England's minimally invasive surgery targets. |
| AI-Integrated Visualization | Machine learning convergence with surgical optics creates premium pricing tiers for real-time tissue analysis. |
Research Methodology
Operator-level perspectives from NHS procurement directors, biomedical engineers, GPO contracts managers, and robotic surgery technicians anchored the qualitative base for this study. Primary interviews combined with secondary validation against hospital procurement databases, GPO contracts, MHRA device registrations, and CMS Medicare data. Bottom-up procedure volume modeling triangulated with top-down market sizing across product type, application, end user, and technology segmentation dimensions.
Sensitivity analysis tested forecast robustness across notified body backlog scenarios, titanium price volatility bands, and regulatory divergence pathways. The analytical framework modeled surgical robotics, electrosurgical devices, imaging systems, and precision instruments across the projection horizon. CAGRs derived from procedure volume elasticity, replacement cycle analysis, and innovation adoption curves, with NHS England's MedTech Funding Mandate penetration serving as primary demand driver input.
Underlying assumptions cover UKCA-CE marking divergence pace, specialist hub consolidation trajectory, and day-case surgery target achievement, with deviation risk concentrated in MHRA enforcement intensity and robotic technician supply constraints. Revision becomes warranted when regulatory backlog duration or titanium allocation disruption crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Embolization Plugs Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Chest Drainage System Market
Medical Devices
Global Ventilators Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Artificial Eye Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market