
 Medical Washer Disinfector Market | 2026-2036
Medical Washer Disinfector Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Washer Disinfector Market Analytics
Automated wash-cycle validation with integrated data-logging is rewriting how medical washer disinfectors integrate into hospital quality systems. STERIS leverages its installed base of sterilization platforms to cross-sell connected washer-disinfector lines with digital compliance dashboards. Getinge anchors its position through captive supply of detergent chemistries and OEM consumables that lock in recurring revenue per installed unit. MELAG Medizintechnik GmbH & Co. KG specializes in compact, benchtop thermal disinfection systems tailored to German dental and ophthalmic outpatient clinics.
A medical washer disinfector is a closed-chamber mechanical device that cleans and thermally or chemically disinfects reusable medical instruments through programmed cycles of pre-wash, enzymatic cleaning, rinse, and thermal disinfection at defined A0 values, typically 60–3000 depending on pathogen lethality requirements. Its primary purpose is to render instruments safe for handling by sterile processing staff and suitable for subsequent sterilization or immediate use in semi-critical applications. Front-loading configurations dominate hospital central sterile departments due to ergonomic instrument transfer and validated load patterns, while rack systems are gaining share in high-throughput ambulatory surgery centers where standardized instrument sets require rapid turnover. Automated systems with barcode traceability and electronic batch records command premium positioning as facilities face Joint Commission and DEKRA audits of reprocessing documentation.
The FDA's guidance on reprocessing of reusable medical devices and the EU Medical Device Regulation's Annex I general safety and performance requirements shape validation protocols, forcing manufacturers to submit clinical evidence of protein residue removal and bioburden reduction. ISO 15883 series standards for washer-disinfectors establish thermal and chemical performance benchmarks that determine market access in regulated jurisdictions. Stakeholders must monitor how evolving sustainability mandates from the EU Green Deal affect water consumption limits and detergent chemistry approvals, as these specifications will determine which platform generations remain compliant without costly engineering retrofits.
Market Dynamics
Automated data-logging and electronic batch record systems are restructuring how hospitals validate washer-disinfector cycles, shifting procurement criteria from standalone equipment performance to integrated compliance infrastructure that satisfies Joint Commission and DEKRA audit requirements.
Growth Catalysts
- Ambulatory surgery center expansion:German outpatient clinics are replacing aging thermal disinfection equipment with compact automated systems to handle rising endoscope and minor surgical instrument volumes.
- EU Medical Device Regulation Annex I:Tightened general safety and performance requirements are compelling healthcare facilities to upgrade to washer-disinfectors with validated protein residue removal documentation.
- Barcode traceability integration:Central sterile supply departments are mandating connected devices that generate electronic records for each processed instrument load.
Market Restraints
- Capital intensity of automated lines:Full reprocessing automation with integrated data systems requires substantial upfront investment that constrains mid-sized hospital budgets.
- Detergent chemistry supply concentration:Captive supply relationships between major manufacturers and proprietary chemistries limit third-party reagent options and lock in recurring costs.
- Water consumption regulatory limits:EU Green Deal sustainability mandates are imposing stricter effluent and freshwater use caps that threaten compliance margins for older platform generations.
Strategic Opportunities
- Indian hospital infrastructure buildout:Greenfield medical cities and expanding tertiary care networks present first-mover openings for thermal disinfection equipment with localized service support.
- Chemical-thermal hybrid systems:Convergence of enzymatic cleaning chemistries with advanced thermal monitoring enables single-pass processing of complex endoscope lumens.
- Digital compliance dashboard bundling:Sterilization platform vendors can cross-sell washer-disinfector lines with integrated quality management software to capture hospital IT budgets.
Industry Challenges
- ISO 15883 validation expertise scarcity:Facilities struggle to recruit sterile processing technicians capable of interpreting thermal performance benchmarks and A0 value documentation.
- Legacy equipment integration friction:Retrofitting existing central sterile departments with connected data systems requires costly engineering modifications to physical plant and workflow layouts.
- FDA reprocessing guidance compliance timelines:Extended validation study periods for new washer-disinfector submissions delay market entry and compress commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Washer Disinfector Market |
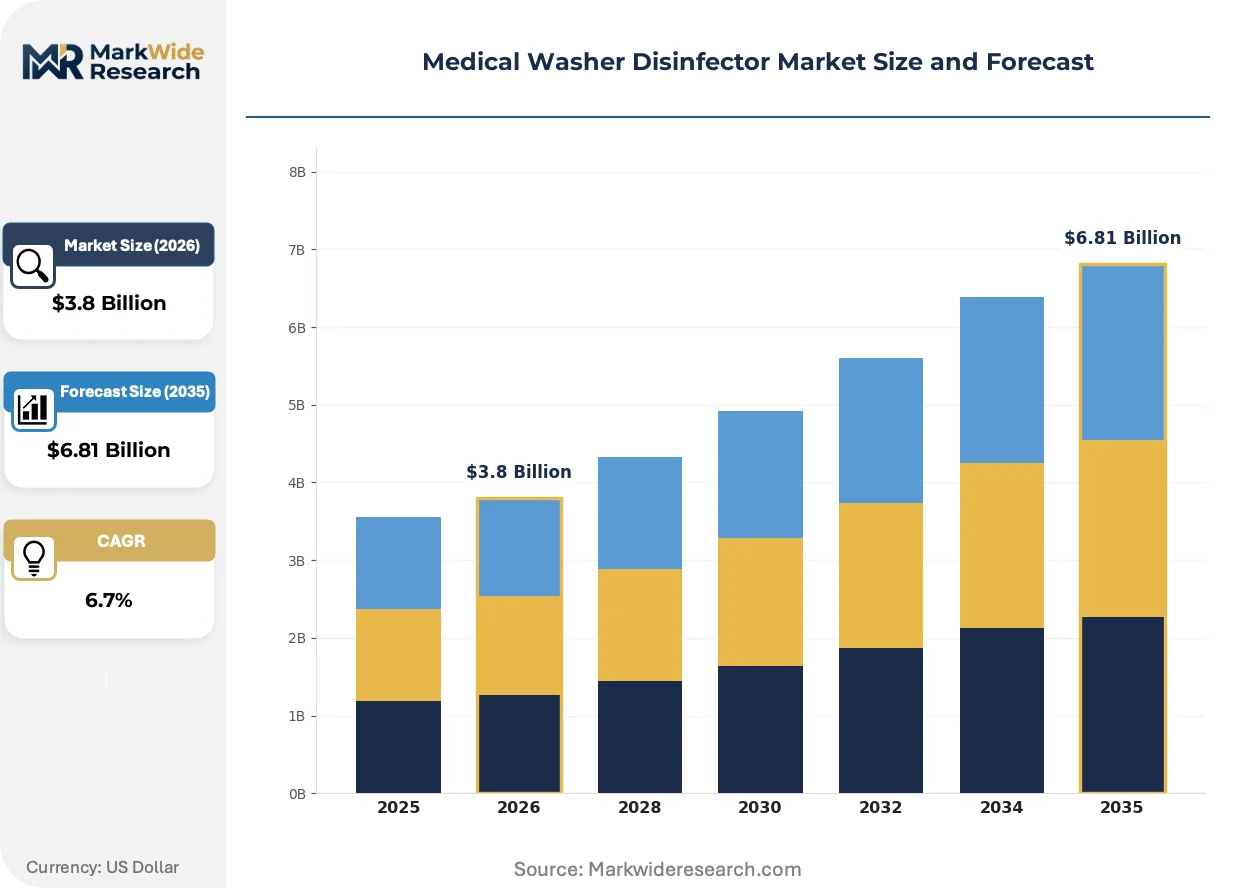
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front-Loading, Top-Loading, Rack System, Modular System Technology: Thermal Disinfection, Chemical Disinfection, Ultrasonic Cleaning, Automated Systems End User: Hospitals, Clinics, Dental Offices, Laboratories Installation: In-Room, Centralized, Mobile Units, Standalone |
| Companies Covered | STERIS, Getinge, Belimed, Olympus Corporation, Tuttnauer, MELAG Medizintechnik GmbH & Co. KG, ECOLAB, Steelco S.p.A., Skytron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Washer Disinfector Market Evolving Landscape
Digital traceability and closed-loop water systems are redefining equipment specifications, with buyers prioritizing platforms that simultaneously reduce environmental footprint and satisfy tightening documentation mandates for reusable device reprocessing.
Thermal disinfection monitoring with real-time A0 value calculation is migrating from standalone dataloggers to embedded chamber sensors. German university hospitals are piloting these integrated systems to eliminate manual temperature verification steps. This migration from peripheral instrumentation to native machine intelligence is compressing validation labor costs and reducing human error in batch documentation.
The FDA's updated guidance on reprocessing of reusable medical devices now requires clinical evidence of bioburden reduction beyond mechanical cleaning efficacy. Manufacturers must submit protein residue and endotoxin removal data as part of 510(k) submissions. High-throughput central sterile departments in the United States are responding by specifying washer-disinfectors with automated residual soil detection capabilities.
Hospital purchasing consortia are consolidating vendor relationships to secure standardized service contracts across sterilization and disinfection platforms. Group purchasing organizations are displacing individual facility negotiations with enterprise pricing frameworks that bundle equipment, consumables, and validation support. This concentration is most visible in integrated delivery networks across the United States, where procurement committees now mandate single-source accountability for entire reprocessing workflows.
Medical Washer Disinfector Market Segmentation
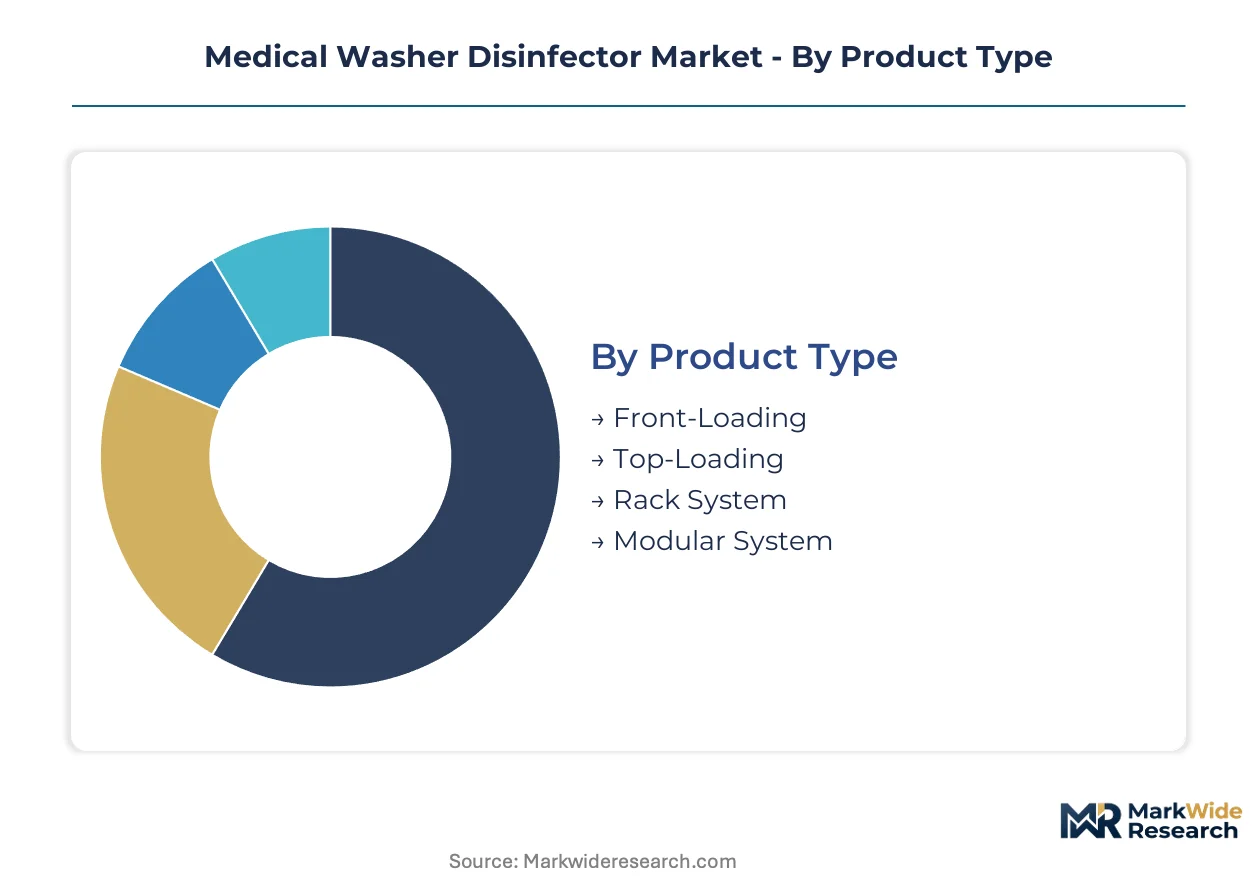
Segmentation in medical washer disinfectors maps directly to reprocessing workflow architecture and regulatory compliance burden. Equipment specifications vary sharply between high-throughput central sterile departments and compact outpatient settings where space constraints and instrument volumes diverge.
Product Type:
Front-loading configurations dominate hospital central sterile supply departments due to validated load patterns and ergonomic instrument transfer, while rack systems concentrate in ambulatory surgery centers requiring rapid standardized-set turnover.
- Front-Loading:Chamber design with horizontal door access supports validated instrument racks and ergonomic loading heights for sterile processing technicians. Demand concentrates in German university hospitals replacing aging thermal disinfection lines under EU Medical Device Regulation compliance timelines.
- Rack System:Standardized instrument-set carriers enable rapid batch turnover and traceable load configurations. German outpatient surgery centers favor these configurations for endoscope and minor surgical instrument reprocessing where throughput velocity determines equipment selection.
- Top-Loading:Vertical chamber access suits compact installation footprints in space-constrained facilities.
- Modular System:Scalable chamber configurations allow capacity expansion without complete platform replacement.
Established volume favors front-loading platforms in tertiary care; emerging adoption favors rack systems in ambulatory networks.
Technology:
Cost tiers separate validated thermal disinfection from chemical and ultrasonic alternatives, with automated systems commanding premium positioning through integrated compliance documentation.
- Thermal Disinfection:Programmed A0 value achievement (60–3000) delivers pathogen lethality through controlled temperature-time exposure. German dental and ophthalmic clinics specify compact benchtop thermal units for immediate-use instrument processing.
- Automated Systems:Embedded sensors calculate real-time A0 values and generate electronic batch records for Joint Commission and DEKRA audit trails. High-throughput central sterile departments in the United States mandate these capabilities under FDA reprocessing guidance documentation requirements.
- Chemical Disinfection:Low-temperature chemistries preserve heat-sensitive endoscope materials.
- Ultrasonic Cleaning:Cavitation action removes soil from complex instrument geometries before disinfection.
Margin concentration sits with automated systems bundling software and validation support; volume leadership remains with thermal disinfection platforms.
End User:
Application severity determines specification intensity, with surgical instrument reprocessing demanding higher validation standards than dental or laboratory equipment.
- Hospitals:Central sterile supply departments require multi-chamber platforms with barcode traceability and closed-loop water systems. Demand concentrates in India where greenfield medical cities are installing first-generation automated reprocessing infrastructure.
- Clinics:Outpatient surgical facilities prioritize compact footprints and rapid cycle times over maximum load capacity. German ambulatory care expansion drives replacement demand for aging thermal equipment.
- Dental Offices:Benchtop thermal disinfection suffices for handpiece and instrument reprocessing volumes.
- Laboratories:Glassware and research instrument cleaning requires adapted chemistries and lower temperature specifications.
Procurement scale favors hospital systems with enterprise purchasing frameworks; growth velocity favors clinic networks expanding procedural capacity.
Installation:
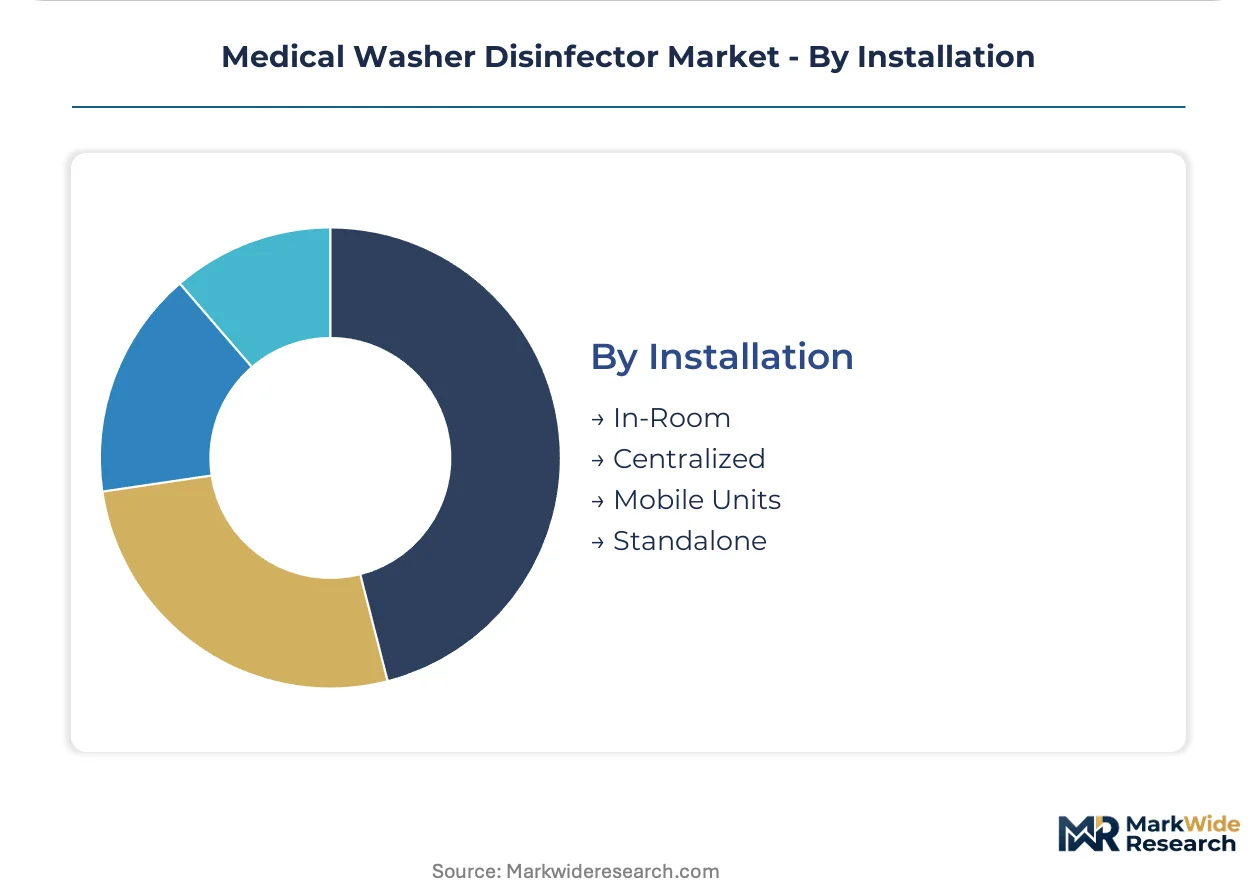
Physical plant integration determines capital expenditure structure and workflow redesign requirements for sterile processing departments.
- Centralized:Dedicated reprocessing facilities serve multiple clinical departments through pneumatic tube or cart-based instrument logistics. Integrated delivery networks in the United States consolidate procurement around centralized installation models to standardize service contracts.
- Mobile Units:Self-contained platforms enable temporary reprocessing capacity during facility renovation or emergency surge response. These configurations are gaining traction in German hospital networks managing distributed care sites.
- In-Room:Point-of-use installation at procedure locations for immediate instrument turnaround.
- Standalone:Independent equipment placement without integration into building utilities or data systems.
Capital efficiency favors centralized installations with shared infrastructure; operational flexibility favors mobile units in distributed care networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in medical washer disinfectors favor established European and North American manufacturers supplying high-validation equipment to emerging hospital infrastructure in Asia and the Middle East. German producers dominate cross-border shipments of thermal disinfection platforms. Indian and Chinese facilities remain net importers of automated systems with integrated compliance documentation.
United States
Hospital purchasing consortia and integrated delivery networks drive centralized procurement of multi-chamber platforms with barcode traceability. FDA reprocessing guidance mandates clinical evidence of bioburden reduction for 510(k) submissions, accelerating replacement of legacy equipment. The Cleveland Clinic and Mayo Clinic networks standardize reprocessing workflows across multi-site sterile processing departments.
Germany
Ambulatory surgery center expansion and dental clinic network growth generate replacement demand for compact thermal disinfection systems. EU Medical Device Regulation Annex I compliance timelines force university hospitals in Berlin and Munich to upgrade aging platforms with validated protein residue removal documentation. Baden-Württemberg's medical technology cluster anchors domestic production of benchtop units.
India
Greenfield medical cities and tertiary care network expansion create first-mover openings for automated reprocessing infrastructure. CDSCO medical device rules require thermal performance documentation for imported washer-disinfectors, favoring vendors with localized service support. Apollo Hospitals and Max Healthcare chains in Delhi-NCR and Maharashtra deploy centralized sterile processing facilities across multi-hospital networks.
China
Public hospital infrastructure upgrades and private medical group consolidation drive demand for high-throughput central sterile systems. NMPA medical device registration requirements for thermal disinfection efficacy documentation filter lower-tier domestic suppliers. Shanghai and Beijing tertiary hospitals prioritize connected platforms with electronic batch record capabilities for Joint Commission International accreditation.
Japan
Aging hospital infrastructure and surgical volume concentration in metropolitan centers necessitate replacement of first-generation thermal disinfection equipment. METI sustainability guidelines and PMDA quality system requirements push adoption of water-efficient platforms with closed-loop systems. Osaka and Nagoya medical clusters specify compact rack systems for space-constrained sterile processing departments.
Medical Washer Disinfector Market Competitive Landscape
On the supply side, the industry is consolidating around sterilization platform vendors with captive detergent chemistries and integrated compliance software capabilities. Three strategic archetypes dominate: full-system integrators bundling equipment with consumables and validation support; regional specialists in compact benchtop configurations for outpatient settings; and sterilization equipment incumbents cross-selling connected washer-disinfector lines. Competitive moves center on M&A to secure detergent chemistry supply chains and strategic partnerships with hospital IT vendors for digital compliance dashboard integration.
Within the full-system integrator tier, STERIS and Getinge exemplify archetypes leveraging installed sterilization bases to cross-sell connected washer-disinfector platforms with recurring consumables revenue. MELAG Medizintechnik GmbH & Co. KG occupies a specialist position among German fabricators focused on compact thermal disinfection systems for dental and ophthalmic outpatient clinics. These three anchors represent divergent scale vectors: enterprise hospital systems versus distributed ambulatory networks.
| Leading Market Players |
|---|
| STERIS |
| Getinge |
| Belimed |
| Olympus Corporation |
| Tuttnauer |
| MELAG Medizintechnik GmbH & Co. KG |
| ECOLAB |
| Steelco S.p.A. |
| Skytron |
| Others |
Value Network & Pricing Analysis
EU dual-use export controls on embedded sensor technology and real-time A0 calculation firmware determine both the pricing gap between connected and legacy washer-disinfector platforms and the geographic shape of component sourcing networks. Facilities in India and China face extended lead times for automated systems with native machine intelligence, compressing margin structures for vendors serving price-sensitive greenfield hospital infrastructure.
Pricing Analysis
Next-generation washer-disinfectors with embedded thermal monitoring and electronic batch record capabilities command substantial premiums over prior-generation standalone units and economy-tier manual systems. Pricing stratifies across premium automated platforms with FDA-validated documentation, standard thermal disinfection lines with basic data-logging, and economy benchtop units for dental clinics. Price differentiation rests on ISO 15883 certification tier and after-sales validation support bundling. Cost compression in the economy tier is intensifying because German outpatient clinics are consolidating procurement around standardized rack configurations. Ambulatory surgery centers exhibit highest price sensitivity; integrated delivery networks in the United States show lowest sensitivity due to enterprise IT budget absorption.
Supply Chain Analysis
Export control restrictions on precision temperature sensors and industrial IoT chipsets limit component flows to non-EU assembly facilities, concentrating finished equipment production in Germany, the United States, and Sweden. Stainless steel chamber fabrication and proprietary detergent chemistry formulation anchor manufacturing in these jurisdictions. Raw material dependencies include medical-grade 316L stainless steel, precision thermocouples, and enzymatic cleaning formulations. Single-source vulnerability sits with German captive supply networks for validated chemistries. Distribution runs through hospital purchasing consortia and group purchasing organizations that bundle equipment with consumables and service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use sterile instrument adoption in ambulatory settings threatens replacement demand for reusable device reprocessing infrastructure, forcing incumbents to defend installed base relationships through consumables lock-in and validation expertise bundling.
For Market Incumbents: Build captive chemistry moats through exclusive supply agreements with detergent formulators that embed proprietary surfactant packages into validated wash-cycle protocols. STERIS and Getinge should deepen backward integration into sensor calibration services to capture recurring revenue per installed automated unit. Defend against emerging regional fabricators in India by pre-positioning localized validation support teams before CDSCO enforcement of thermal performance documentation intensifies.
For New Entrants and Emerging Players: Greenfield medical cities in Maharashtra and Delhi-NCR present the most penetrable hospital infrastructure for first-mover automated reprocessing platform installation. Target compact rack system configurations for German ophthalmic and dental clinic networks where MELAG's benchtop dominance leaves mid-sized ambulatory surgery centers underserved. Pursue joint venture structures with Indian hospital chains to embed service capabilities before Apollo and Max Healthcare consolidate vendor relationships.
For Investors and Strategic Acquirers: Regional specialists with validated compact thermal disinfection platforms and established GPO contracts in German outpatient networks represent prime acquisition targets. Long-term viability hinges on regulatory validation asset durability rather than equipment replacement cycles alone. Monitor EU Green Deal water consumption limit enforcement as the signal for which platform generations require costly engineering retrofits versus full replacement.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Clinical evidence requirements for protein residue removal are extending validation timelines and compressing commercialization windows for new entrants. |
| Hospital System Partnership | Integrated delivery networks in the United States are consolidating procurement around single-source accountability for entire sterile processing workflows. |
| Software Companion Development | Digital compliance dashboard bundling with sterilization platforms captures hospital IT budgets and locks in recurring validation support revenue. |
| CE Marking Pathway | EU Medical Device Regulation Annex I general safety requirements are forcing replacement cycles for aging thermal disinfection equipment in German university hospitals. |
| Reimbursement Strategy | Joint Commission and DEKRA audit documentation requirements are mandating barcode traceability and electronic batch record capabilities as procurement prerequisites. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sterile processing department managers, biomedical engineers, hospital purchasing committee members, GPO contracts managers, and washer-disinfector manufacturer product directors. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, ISO 15883 certification registries, hospital procurement contract disclosures, and trade flow records for thermal disinfection equipment. Bottom-up installation base modeling and top-down healthcare capital expenditure triangulation anchored volume and value estimates.
Calibration against historical replacement cycles in German hospital infrastructure and ambulatory surgery center expansion trajectories in India shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product configuration, disinfection technology tier, end-user facility type, and installation architecture. CAGRs were derived from equipment shipment tracking and consumables revenue per installed unit analysis. Forecast inputs incorporated EU Green Deal water efficiency mandate compliance timelines and CDSCO medical device rule enforcement phasing.
Practitioners should monitor regulatory validation requirement shifts and sustainability mandate enforcement for early signals of platform obsolescence risk. Forecasts reflect assumptions about replacement cycle timing and hospital capital expenditure prioritization. Material shifts in FDA reprocessing guidance documentation requirements or EU MDR Annex I enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antimicrobial Suture Market
Infection Control
Sterility Indicators Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Global Disinfection Robots Market
Infection Control
Antiseptic Bathing Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Global Hospital Disinfectant Products and Services Market