
 North America Vagus Nerve Stimulation Market | 2026-2036
North America Vagus Nerve Stimulation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vagus Nerve Stimulation Market Analytics
Buyer concentration across North American neurology clinics is rebalancing as independent specialty practices consolidate into regional networks while academic medical centers expand their in-house neurostimulation programs. LivaNova PLC anchors its position through deep integration with epilepsy surgical workflows across major US hospital systems. Boston Scientific Corporation leverages its broader neuromodulation platform to cross-sell vagus nerve systems alongside spinal cord stimulators. ElectroCore Inc specializes in non-invasive delivery formats that compete for outpatient migraine and depression indications outside traditional implantable channels.
Vagus nerve stimulation encompasses electrical neuromodulation delivered to the cervical vagus nerve through implantable pulse generators or external transcutaneous devices, typically operating at frequencies between 20-30 Hz with current outputs calibrated to patient tolerance thresholds, primarily indicated for drug-resistant epilepsy and treatment-resistant depression. Implantable devices sustain the dominant revenue position due to higher unit values and recurring battery replacement cycles, though non-surgical delivery modes are capturing faster growth as transcutaneous systems expand into anxiety and inflammatory disorder applications. The epilepsy application segment leads in procedure volume while depression and emerging heart disorder indications concentrate margin pools where payers reimburse at premium rates for patients who have failed multiple pharmaceutical lines.
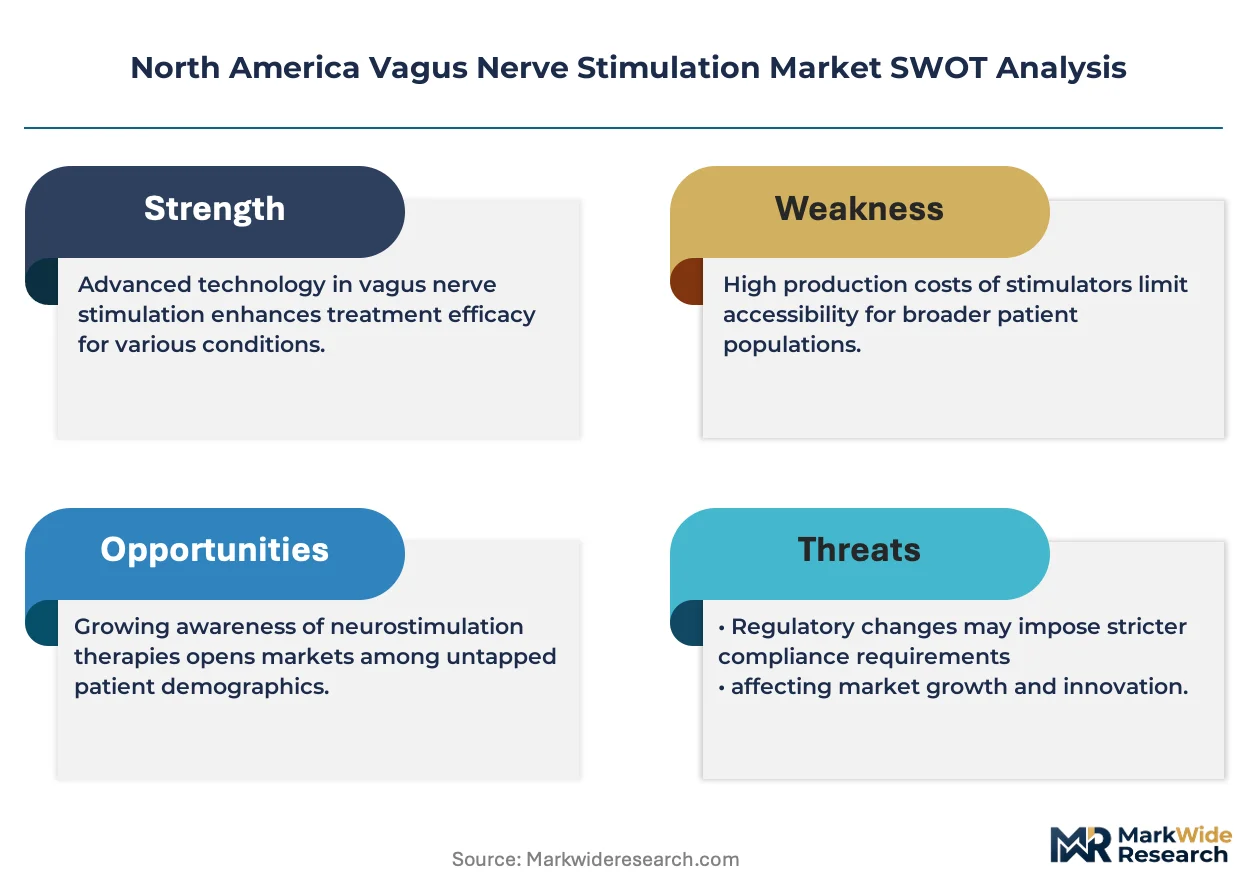
FDA premarket approval requirements and CMS national coverage determinations shape product development timelines and commercial launch sequencing across the United States, while Health Canada's medical device licensing framework governs market access in Canada with parallel but distinct clinical evidence standards. The FDA's breakthrough devices program and evolving Category III CPT codes for neurostimulation procedures directly influence manufacturer R&D prioritization and physician training investments. Stakeholders must monitor CMS technology add-on payment decisions and state-level Medicaid coverage variations that will determine whether non-invasive formats achieve parity reimbursement with implantable systems.
Market Dynamics
FDA breakthrough device designations and CMS reimbursement pathway expansions are compressing commercialization timelines, forcing manufacturers to synchronize clinical evidence generation with parallel regulatory and payer engagement strategies.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement pathways for neurostimulation procedures reduce out-of-pocket exposure for patients with drug-resistant epilepsy, accelerating procedure volume in academic medical centers.
- Neurology clinic consolidation:Independent specialty practices merging into regional networks standardize vagus nerve therapy protocols and streamline physician training investments across multi-site operations.
- Transcutaneous delivery formats:Non-invasive systems bypass surgical implantation requirements, opening outpatient channels for migraine and depression indications previously reserved for implantable devices.
Market Restraints
- Implantable device cost structure:Pulse generator hardware and recurring battery replacement cycles impose cumulative cost burdens that limit penetration in Medicaid-dominant patient populations.
- Clinical evidence requirements:FDA premarket approval mandates for novel indications demand multi-year pivotal trials, extending capital lockup periods before commercial revenue realization.
- Pharmaceutical substitution:Next-generation antiepileptic drugs and ketamine-based depression therapies retain first-line prescriber preference despite vagus nerve stimulation efficacy in refractory cases.
Strategic Opportunities
- Texas and Florida sub-markets:Underpenetrated metropolitan hospital networks in these states present whitespace for epilepsy treatment center expansion beyond saturated California and New York clusters.
- Inflammatory disorder applications:Emerging indications in rheumatoid arthritis and Crohn's disease leverage vagus nerve modulation of cytokine production, opening autoimmune patient pools outside neurology.
- Category III CPT code evolution:CMS technology add-on payment decisions for non-invasive formats could achieve reimbursement parity with implantable systems, rebalancing competitive economics.
Industry Challenges
- Electrophysiology specialist scarcity:Qualified surgical teams for implantable device placement concentrate in major academic centers, constraining procedure capacity expansion into community hospital settings.
- Legacy EHR integration:Vagus nerve stimulation programming data and patient outcome tracking require custom interoperability builds with existing hospital information systems, delaying deployment timelines.
- Patent landscape complexity:Overlapping intellectual property claims on stimulation waveforms and electrode geometries complicate freedom-to-operate assessments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vagus Nerve Stimulation Market |
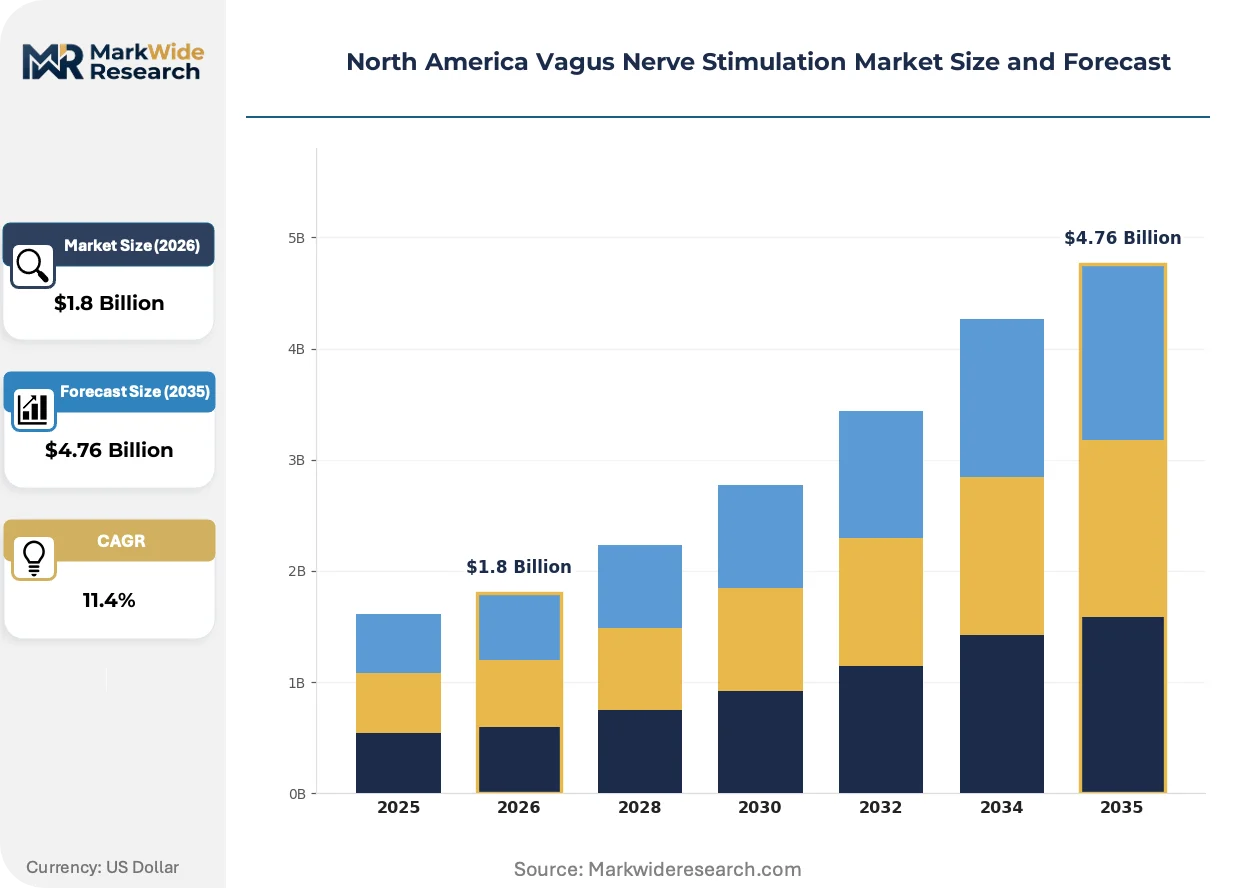
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, External Devices, Accessories, Software End User: Hospitals, Neurology Clinics, Home Care, Research Institutions Delivery Mode: Surgical, Non-Surgical, Outpatient, Inpatient Application: Epilepsy, Depression, Heart Disorders, Others |
| Companies Covered | Cerebral, Boston Scientific Corporation, LivaNova PLC, Inspire Medical Systems, Inc., SetPoint Medical Corporation, ElectroCore Inc, Parasym, NeuroMetrix Inc., MicroTransponder, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vagus Nerve Stimulation Market Evolving Landscape
Closed-loop stimulation algorithms and artificial intelligence-driven patient selection tools are compressing trial-and-error programming cycles, while reimbursement policy evolution restructures how manufacturers prioritize invasive versus non-invasive platform investments.
Adaptive stimulation systems that sense autonomic biomarkers and automatically adjust therapeutic output are automating previously manual titration protocols. Major epilepsy treatment centers in California and New York are piloting these platforms for drug-resistant patient cohorts, reducing specialist consultation frequency while maintaining seizure control efficacy.
FDA breakthrough device designations for novel vagus nerve indications are accelerating premarket approval timelines, compressing the traditional gap between clinical trial completion and commercial launch. Manufacturers are responding by front-loading health economics evidence to support simultaneous CMS national coverage determination submissions, particularly for depression and emerging inflammatory disorder applications.
Hospital procurement committees are consolidating neurostimulation vendor contracts under single-source agreements that bundle vagus nerve systems with spinal cord and deep brain stimulation platforms. This contract consolidation displaces standalone purchasing autonomy previously exercised by individual neurology departments, concentrating negotiating leverage with integrated health systems in Texas and Illinois.
North America Vagus Nerve Stimulation Market Segmentation
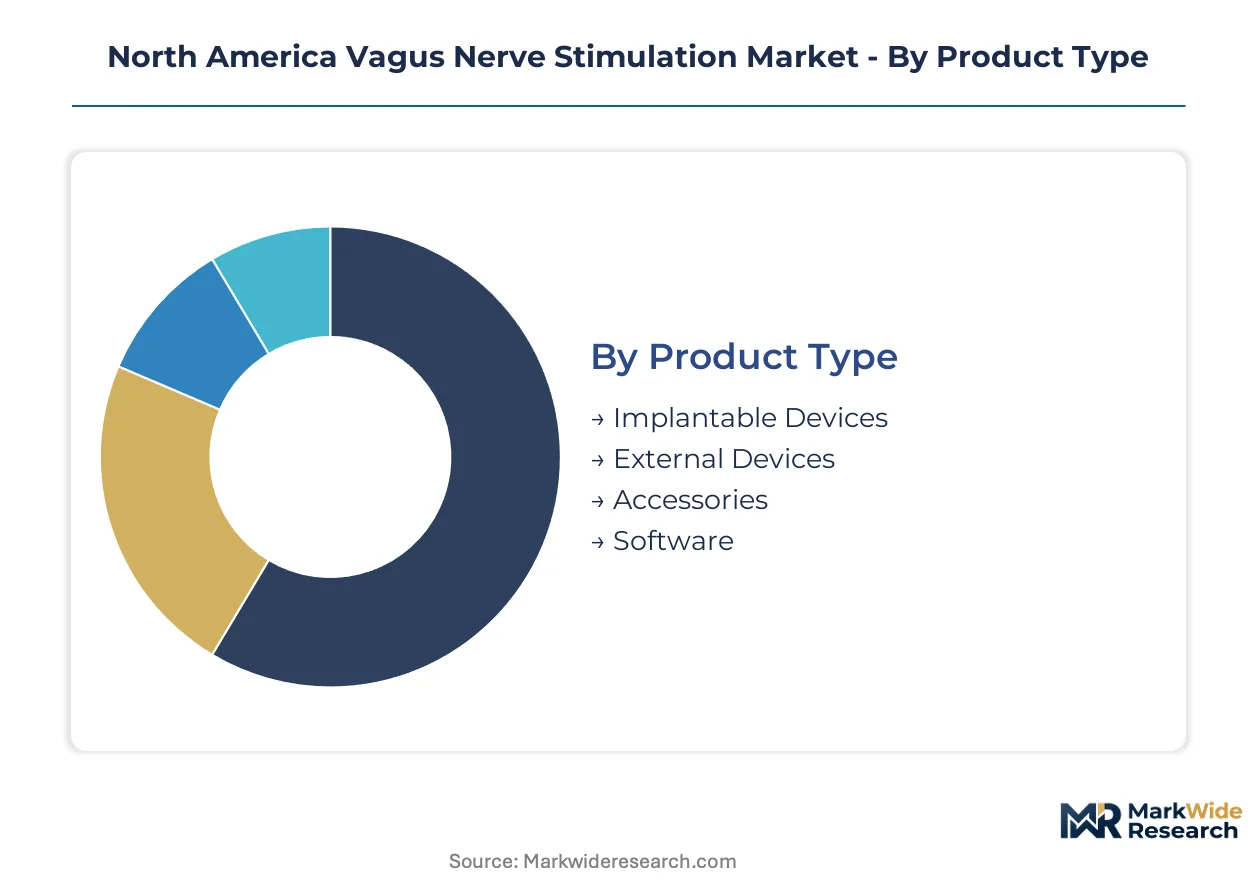
Segmentation in vagus nerve stimulation reveals how device form factors, care settings, and clinical indications partition revenue pools differently. Understanding these splits illuminates where manufacturers must align R&D investments with reimbursement pathways and surgical capacity constraints.
Product Type:
Implantable pulse generators anchor the revenue base with recurring battery replacement cycles, while external transcutaneous systems compete for outpatient channels that bypass surgical infrastructure requirements.
- Implantable Devices:These systems deliver electrical pulses through surgically implanted lead electrodes wrapped around the cervical vagus nerve, typically operating at 20-30 Hz frequencies calibrated to patient tolerance. Demand concentrates in academic medical centers across California and New York where specialized epilepsy surgical teams manage device programming and battery replacement protocols. FDA premarket approval requirements and CMS national coverage determinations shape manufacturer investment prioritization for hardware durability and biocompatibility improvements.
- External Devices:Transcutaneous delivery systems apply electrical stimulation through surface electrodes positioned on the neck or tragus, eliminating surgical implantation requirements entirely. Neurology clinics in Texas and Florida are expanding these platforms for migraine and depression indications where patients resist invasive procedures, though reimbursement parity with implantable formats remains contingent on evolving Category III CPT code decisions.
- Accessories:Lead extensions, replacement electrodes, and programming wands support device maintenance and troubleshooting workflows.
- Software:Stimulation programming interfaces and patient outcome tracking platforms require custom EHR integration builds.
Implantable devices lead volumes today; external devices are gaining share fastest.
End User:
Care setting economics diverge sharply between capital-intensive hospital implantation suites and distributed outpatient neurology practices seeking lower-overhead delivery models.
- Hospitals:Academic medical centers and metropolitan hospital networks dominate implantable device placement, leveraging integrated operating room capacity and electrophysiology specialist teams. Texas and Illinois health systems are consolidating neurostimulation procurement under single-source vendor agreements that bundle vagus nerve systems with spinal cord and deep brain stimulation platforms.
- Neurology Clinics:Independent specialty practices merging into regional networks standardize vagus nerve therapy protocols across multi-site operations. These clinics drive external device adoption for migraine and depression indications where surgical referral friction limits implantable penetration.
- Home Care:Patient-managed transcutaneous stimulation for chronic conditions expands addressable populations beyond clinic-dependent models.
- Research Institutions:Pilot programs for inflammatory disorder applications generate clinical evidence for emerging indications.
Hospitals capture the dominant revenue share; neurology clinics are expanding most quickly as consolidation creates standardized protocol deployment.
Delivery Mode:
Surgical versus non-surgical pathways determine capital requirements, specialist scarcity constraints, and reimbursement coding structures that shape manufacturer commercial strategies.
- Surgical:Implantable device placement requires specialized electrophysiology teams concentrated in major academic centers, constraining procedure capacity expansion into community hospital settings across Medicaid-dominant patient populations.
- Non-Surgical:Transcutaneous delivery bypasses operating room scheduling and specialist availability bottlenecks entirely.
- Outpatient:Ambulatory surgical centers and neurology clinics capture lower-acuity procedures with reduced facility fees.
- Inpatient:Complex cases with comorbidities require overnight monitoring following device implantation or adjustment.
Surgical delivery dominates implantable volumes; non-surgical formats are climbing the fastest as outpatient channels expand.
Application:
Indication-specific reimbursement rates and clinical evidence maturity create divergent margin profiles across neurology, psychiatry, and emerging autoimmune therapeutic areas.
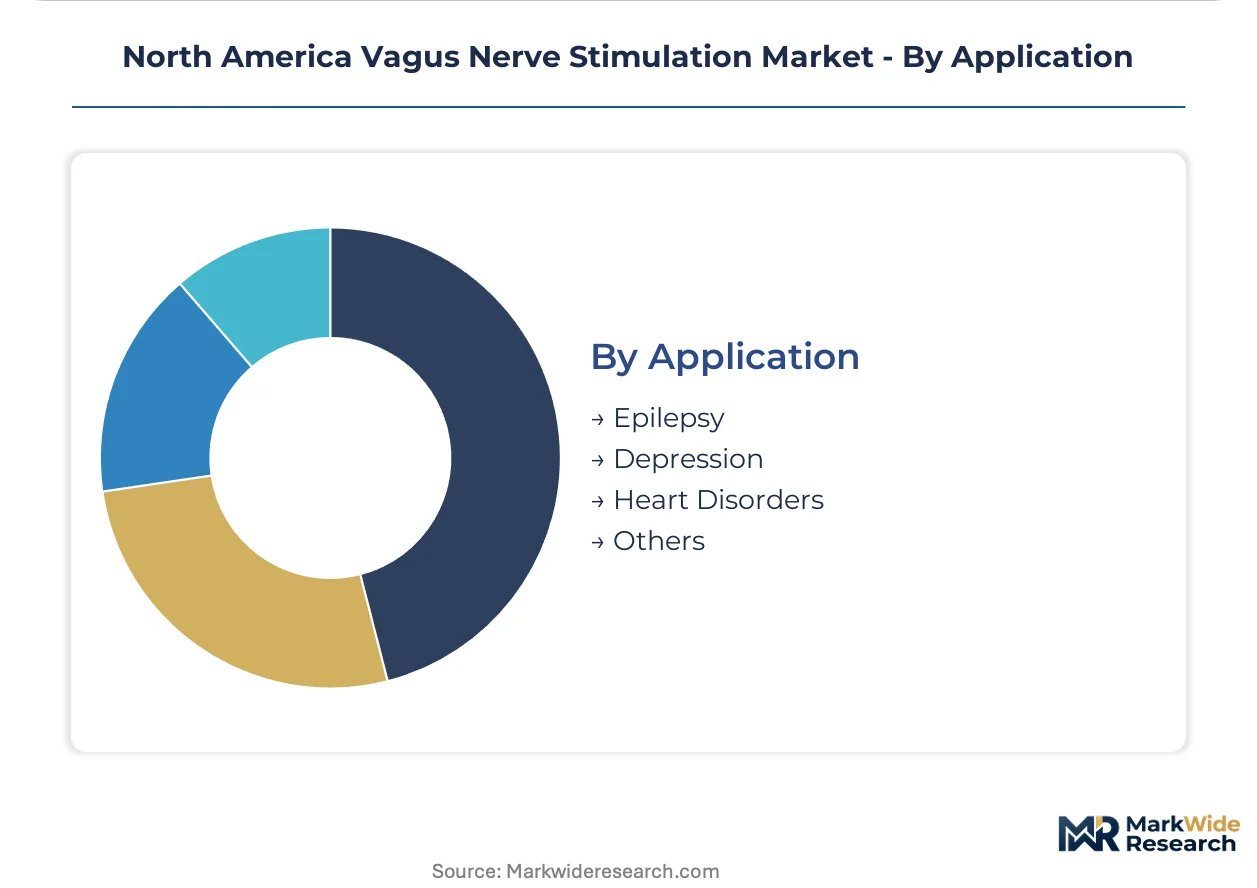
- Epilepsy:Drug-resistant epilepsy represents the most established indication with mature CMS national coverage determinations and standardized surgical workflows. Major metropolitan hospital networks in California, Texas, and New York concentrate procedure volume where specialized epilepsy treatment centers manage patient selection and long-term device management.
- Depression:Treatment-resistant depression commands premium reimbursement rates for patients who have failed multiple pharmaceutical lines, though prescriber preference for ketamine-based therapies and next-generation antiepileptic drugs limits first-line adoption. FDA breakthrough device designations are accelerating premarket approval timelines for novel delivery formats in this segment.
- Heart Disorders:Emerging applications in heart failure and arrhythmia modulation leverage autonomic nervous system regulation.
- Others:Inflammatory disorders including rheumatoid arthritis and Crohn's disease represent experimental indications targeting cytokine production modulation.
Epilepsy leads procedure volumes today; depression and emerging inflammatory applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized epilepsy surgical teams concentrate in major metropolitan hospital networks across the United States, Canada, and Mexico, anchoring procedure capacity and driving regional market dynamics. FDA premarket approval pathways and CMS reimbursement frameworks in the United States establish the regulatory template that Canadian and Mexican market participants reference for clinical evidence standards and commercial strategy.
United States
Academic medical centers in California, Texas, and New York manage the highest implantable device placement volumes, with specialized epilepsy treatment centers standardizing patient selection protocols. FDA breakthrough device designations compress premarket approval timelines for novel indications, while CMS national coverage determinations shape manufacturer investment in health economics evidence. Texas health systems are consolidating neurostimulation procurement under single-source vendor agreements that bundle multiple neuromodulation platforms.
California
Metropolitan hospital networks in Los Angeles and the San Francisco Bay Area pilot closed-loop stimulation algorithms with artificial intelligence-driven patient selection tools. FDA premarket approval requirements for hardware durability improvements concentrate R&D investment in biocompatibility engineering. Major epilepsy treatment centers in these clusters reduce specialist consultation frequency while maintaining seizure control efficacy through automated titration protocols.
Texas
Underpenetrated metropolitan hospital networks in Houston and Dallas-Fort Worth present whitespace for epilepsy treatment center expansion beyond saturated coastal markets. State-level Medicaid coverage variations influence whether non-invasive formats achieve penetration in publicly insured patient populations. Health systems here are consolidating vendor contracts under single-source agreements that bundle vagus nerve systems with spinal cord and deep brain stimulation platforms.
New York
Academic medical centers in New York City and surrounding metropolitan areas concentrate electrophysiology specialist teams for complex implantable device placement. CMS technology add-on payment decisions for non-invasive formats are monitored closely here as these institutions often pilot novel reimbursement coding structures. Major hospital networks in this cluster drive depression indication adoption where premium reimbursement rates apply for treatment-resistant patients.
Canada
Health Canada's medical device licensing framework governs market access with clinical evidence standards that parallel but remain distinct from FDA requirements. Neurology clinics in Ontario and Quebec are expanding transcutaneous delivery platforms for migraine indications where patients resist surgical referral. Provincial health authority reimbursement decisions determine whether non-invasive formats achieve parity coverage with implantable systems in publicly funded healthcare delivery.
North America Vagus Nerve Stimulation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North America vagus nerve stimulation market, creating a tiered competitive structure where scale advantages clash with indication-specific expertise. The vendor base clusters around three strategic archetypes: diversified neuromodulation platforms leveraging cross-selling synergies, implantable device specialists anchored in epilepsy surgical workflows, and non-invasive delivery innovators competing for outpatient channels. Dominant competitive moves include health system procurement consolidation under bundled vendor agreements and parallel regulatory-payer engagement strategies that synchronize FDA submissions with CMS coverage determinations.
Within the diversified platform tier, Boston Scientific Corporation represents the archetype of cross-selling leverage across spinal cord and deep brain stimulation portfolios. LivaNova PLC occupies a position exemplifying deep integration with epilepsy surgical workflows in major academic medical centers. ElectroCore Inc anchors the non-invasive specialist segment, competing for outpatient migraine and depression indications outside traditional implantable channels. These three companies illustrate how competitive positioning diverges based on delivery mode specialization and care setting targeting.
| Leading Market Players |
|---|
| Cerebral |
| Boston Scientific Corporation |
| LivaNova PLC |
| Inspire Medical Systems, Inc. |
| SetPoint Medical Corporation |
| ElectroCore Inc |
| Parasym |
| NeuroMetrix Inc. |
| MicroTransponder |
| Others |
Value Network & Pricing Analysis
Captive production of implantable pulse generators and electrode assemblies in Minnesota and Massachusetts anchors both supply security and pricing power for established manufacturers. This backward integration into biocompatible materials and precision-machined components insulates tier-one suppliers from commodity volatility while concentrating margin capture with vendors who control FDA-validated manufacturing lines.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for external transcutaneous devices as neurology clinic networks expand standardized procurement protocols. Three-tier pricing structure across premium implantable systems, mid-range external devices, and economy accessories segments the market by surgical necessity and reimbursement tier. Cost compression in the external device category is intensifying because ElectroCore and Parasym compete for outpatient migraine volume without implantable hardware overhead. Medicaid-dominant patient populations in Texas demonstrate highest price sensitivity, while academic medical centers in California and New York absorb premium implantable pricing for drug-resistant epilepsy cases.
Supply Chain Analysis
Electrophysiology specialist scarcity in Puerto Rico and Costa Rica constrains contract manufacturing expansion for lead electrode assemblies. Component sourcing draws from titanium alloy suppliers in Pennsylvania, biocompatible polymer producers in Germany, and microelectronic foundries in Taiwan. Single-source vulnerability around FDA-validated cleanroom facilities in the upper Midwest threatens supply continuity if regulatory inspections trigger production pauses. Distribution runs through GPO-negotiated contracts with hospital procurement committees and direct-to-clinic shipments for external device replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America vagus nerve stimulation market functions as a regulatory compounder where FDA breakthrough device designations and CMS national coverage determinations create accelerating returns for evidence-generation investments. The FDA's 2023 expansion of Category III CPT codes for neurostimulation procedures exemplifies this dynamic, compressing commercialization timelines for manufacturers who synchronize clinical trials with parallel payer engagement.
For Market Incumbents: Deepen integration with epilepsy surgical workflows by acquiring specialized electrophysiology training platforms and embedding device programming expertise within academic medical center residency programs. Consolidate vendor contracts under single-source agreements that bundle vagus nerve systems with spinal cord and deep brain stimulation platforms to defend against Boston Scientific's cross-selling leverage. Threaten margin compression from non-invasive delivery formats demands counterinvestment in closed-loop algorithm development that differentiates implantable systems on efficacy durability. For New Entrants and Emerging Players: Enter via the inflammatory disorder application segment where rheumatoid arthritis and Crohn's disease indications lack established neuromodulation competitors and FDA breakthrough pathways remain underexploited. Target Texas and Florida metropolitan hospital networks where epilepsy treatment center density lags California and New York clusters, creating whitespace for external device penetration before implantable vendors consolidate procurement relationships. Pursue direct-to-employer contracting for migraine management programs that bypass traditional pharmaceutical benefit structures and capture self-insured patient populations. For Investors and Strategic Acquirers: Roll-up economics work for non-invasive delivery specialists because reimbursement parity decisions by CMS technology add-on payment committees create binary valuation inflection points that concentrate returns in platform-integrated portfolios. Five-to-ten year viability hinges on manufacturers achieving Category I CPT code status for transcutaneous depression indications, transitioning from pilot reimbursement to durable revenue streams. Acquisition target archetype: external device developers with Health Canada licensing and pilot provincial contracts in Ontario and Quebec that establish clinical evidence templates for US payer expansion. Signal to watch: state-level Medicaid coverage variations in Texas and Florida that indicate whether non-invasive formats achieve penetration in publicly insured populations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket approval timelines for novel inflammatory disorder indications. |
| CMS National Coverage Determination | Expands reimbursement pathways for treatment-resistant depression in academic medical centers. |
| Hospital System Partnership | Bundles vagus nerve systems with spinal cord stimulation platforms under single-source contracts. |
| Software Companion Development | Integrates AI-driven patient selection tools with EHR systems to automate titration protocols. |
| Reimbursement Strategy | Achieves Category III CPT code parity for external devices with implantable systems. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national regulatory cluster and distinct reimbursement framework. The analysis combines structured interviews with epilepsy treatment center directors, hospital procurement committee chairs, biomedical engineers specializing in neurostimulation programming, and GPO contracts managers with secondary validation against FDA premarket approval databases, CMS national coverage determination records, Health Canada medical device licensing filings, and hospital procurement database extracts. Bottom-up procedure volume estimates triangulate with top-down manufacturer revenue attribution across implantable pulse generator, external device, and accessory categories.
Rate-of-change decomposition separates volume expansion from price evolution across the projection horizon, with segmentation modeling across device form factor, delivery mode, clinical indication, and care setting. CAGRs derive from logistic diffusion curves fitted to historical procedure adoption patterns and adjusted for regulatory milestone timing. Industry-specific forecast inputs include FDA breakthrough device designation trajectories, CMS technology add-on payment decisions, and electrophysiology specialist training pipeline capacity in named state clusters.
The model holds under stable FDA-CMS coordination timelines and continued epilepsy surgical team concentration in academic medical centers; deviation in reimbursement parity decisions for non-invasive formats or sudden electrophysiology specialist supply constraints would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Transradial Access Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Heel Incision Devices Market