
 Clear Aligners Market | 2026-2036
Clear Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Aligners Market Analysis
Modular treatment bundling is expanding across the clear aligners industry, with providers packaging initial scans, refinement trays, and retention devices into single-price offerings that simplify patient decision-making. Align Technology leverages its iTero scanner ecosystem to anchor digital workflow control from chairside to fabrication. Institut Straumann AG sustains its position through specialist channel depth in European dental markets. Henry Schein competes by extending distribution reach across general dentistry practices that previously referred orthodontics outward.
Clear aligners are transparent, removable orthodontic devices fabricated from medical-grade thermoplastic polymers such as polyethylene terephthalate glycol (PETG) or multilayer polyurethane blends, engineered to apply calibrated sequential force for tooth repositioning. Their primary commercial purpose is to deliver aesthetic orthodontic correction without fixed brackets or wires. Removable aligners occupy the dominant volume position due to patient preference for lifestyle flexibility, while AI Integration represents the fastest-growing technology segment as machine learning optimizes treatment planning accuracy and reduces refinement cycles. Dental Clinics retain the largest margin pool through professional supervision fees, though Online Retail channels erode that capture in price-sensitive patient segments.
The FDA regulates clear aligners as Class II medical devices requiring 510(k) premarket notification, while the EU MDR imposes stricter clinical evidence and post-market surveillance obligations through notified body certification. ISO 13485 quality management standards govern manufacturing consistency across multinational supply chains. Stakeholders must monitor how regulatory divergence between the FDA pathway and EU MDR timelines affects product launch sequencing and geographic revenue concentration.
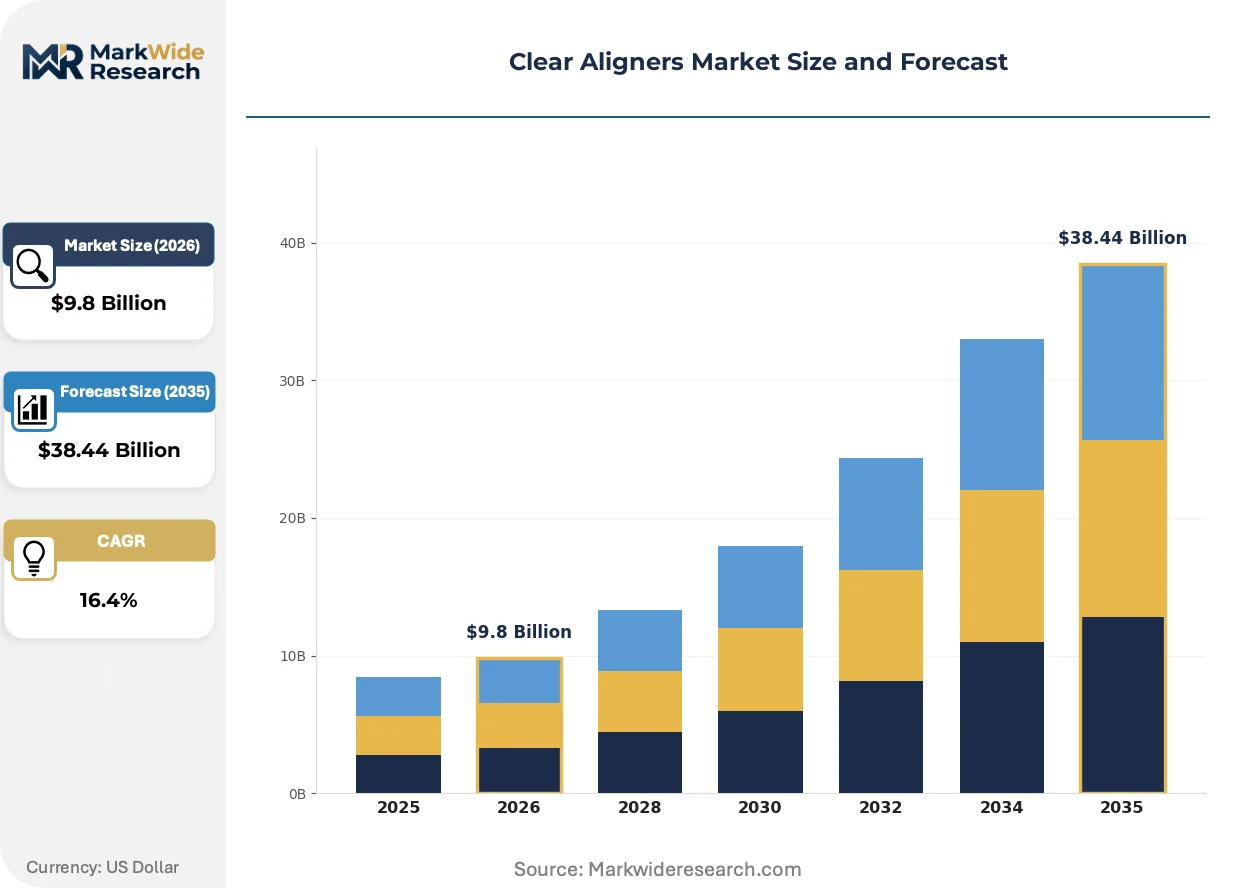
Market Dynamics
AI-powered treatment planning software is compressing orthodontic workflow timelines from weeks to days, forcing incumbents to rebuild their digital infrastructure or cede chairside control to technology-native competitors.
Growth Catalysts
- FDA 510(k) pathway efficiency:Streamlined premarket notification for Class II medical devices accelerates product iteration cycles for US manufacturers relative to European notified body timelines.
- Teen aesthetic preference:Adolescent patients increasingly reject fixed appliances, driving parental purchasing decisions toward removable alternatives that preserve social confidence during schooling years.
- Polymer science advances:Multilayer polyurethane blends with shape-memory properties now deliver force profiles previously achievable only through sequential metal archwires.
Market Restraints
- EU MDR clinical evidence burden:Stricter post-market surveillance obligations through notified body certification extend European launch timelines by 12-18 months versus FDA clearance.
- Thermoplastic resin price volatility:Medical-grade PETG feedstock costs fluctuate with petrochemical supply chains, compressing fabrication margins for high-volume producers.
- Orthodontist supply concentration:Specialist licensing bottlenecks in Germany and France limit treatment capacity expansion despite patient queue growth.
Strategic Opportunities
- Direct-to-consumer channel maturation:Remote monitoring platforms enable asynchronous orthodontist oversight, capturing price-sensitive young adults who bypass traditional clinic gatekeeping.
- Retention device bundling:Post-treatment Vivera-style retainers generate recurring revenue streams with minimal incremental manufacturing complexity.
- China NMPA registration acceleration:Domestic manufacturers leverage streamlined Class II device pathways to displace imported aligners in tier-one city dental chains.
Industry Challenges
- Digital workflow integration:Legacy practice management systems require costly middleware development to interface with cloud-based treatment planning platforms.
- IP landscape fragmentation:Overlapping patents on sequential staging algorithms force licensing negotiations or design-around engineering that delays product releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Aligners Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-ligating Aligners, Traditional Aligners, Removable Aligners, Fixed Aligners End User: Orthodontists, General Dentists, Cosmetic Dentists, Patients Technology: 3D Printing, Computer-Aided Design, Digital Scanning, AI Integration Distribution Channel: Online Retail, Dental Clinics, Referral Networks, Direct Sales |
| Companies Covered | Institut Straumann AG, Argen Corporation, Align Technology, Inc., Solventum, Angel Aligner, Envista Holdings Corporation, Henry Schein, Inc., 3M Company, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Aligners Market Emerging Trajectories
Computational orthodontics is redefining competitive advantage, with software-driven precision now mattering more than manufacturing scale in capturing specialist loyalty and patient outcomes.
Machine learning algorithms trained on millions of completed cases now predict tooth movement with sub-millimeter accuracy, reducing refinement tray requirements by half. Specialist orthodontists in the United States and Germany are adopting these platforms fastest, demanding predictive confidence intervals before approving treatment plans. Conventional staging protocols are overtaking experience-based intuition in determining which practices retain high-complexity case referrals.
The EU MDR's clinical evidence requirements for orthodontic devices are forcing manufacturers to maintain prospective patient registries spanning multi-year follow-up periods. This surveillance obligation raises compliance costs disproportionately for mid-sized European competitors. German notified bodies are processing certification applications slowest, pushing some manufacturers to sequence US launches ahead of European market entry.
Young adult patients increasingly initiate treatment through smartphone-based scanning apps before selecting a supervising provider, reversing the traditional referral funnel. Dental clinics in urban China and the United States are responding by unbundling initial consultations from comprehensive treatment quotes. This channel fragmentation concentrates marketing spend on social media patient acquisition rather than specialist referral networks.
Clear Aligners Market Segmentation
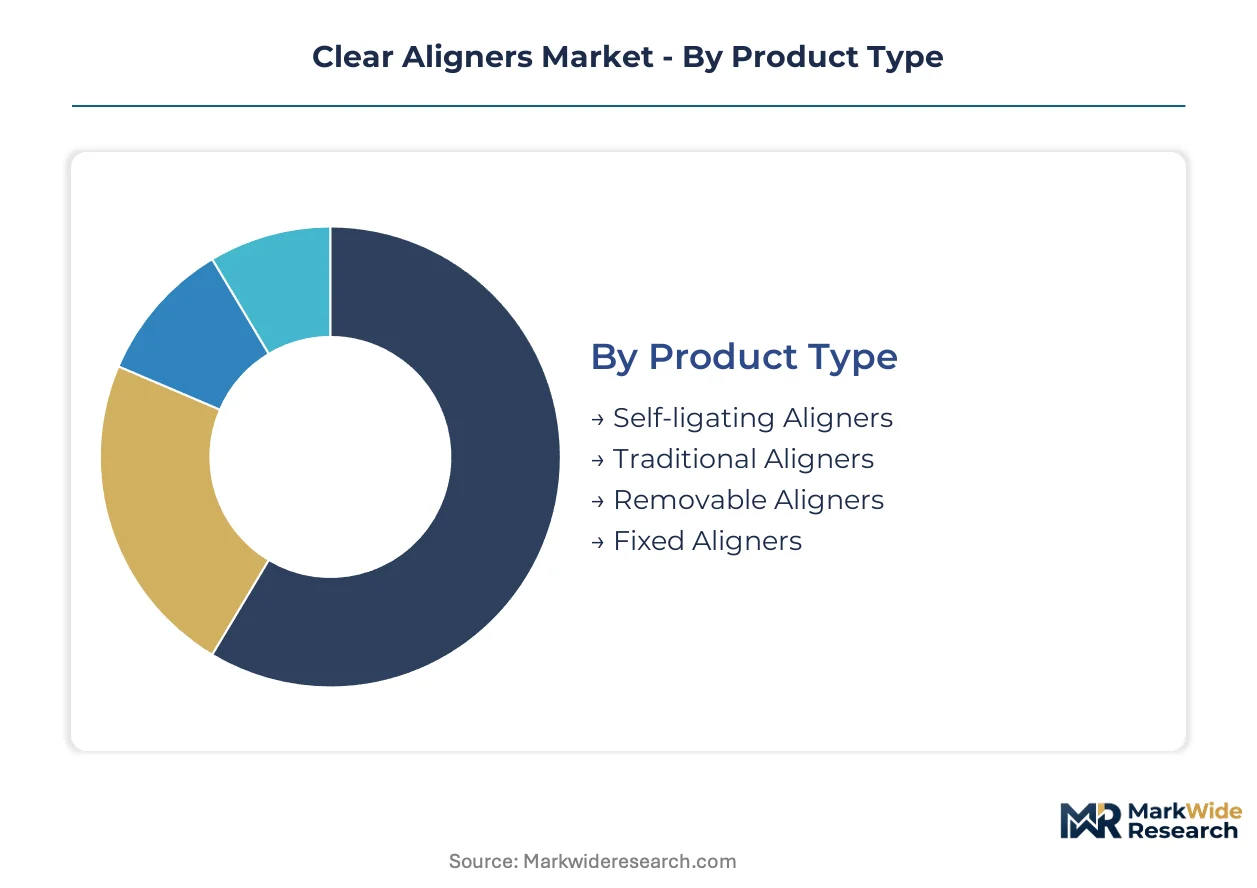
Segmentation in the clear aligners market reveals where capital deployment, regulatory exposure, and margin capture concentrate across product architectures and patient access pathways. Manufacturers and distributors calibrate resource allocation differently depending on which segment combinations they target.
Product Type:
Capital intensity varies sharply across fabrication methods and material science requirements, with multilayer polymer development demanding sustained R&D commitment.
- Removable Aligners:Medical-grade thermoplastic polymers such as PETG or polyurethane blends enable sequential force application without fixed hardware. Demand clusters in the United States and China where direct-to-consumer channels and urban clinic networks compete for young adult patients prioritizing lifestyle flexibility.
- Fixed Aligners:Bonded or semi-permanent attachment systems require precision bracket engineering and specialist placement protocols. Orthodontist practices in Germany and France retain tighter control over this segment due to specialist licensing bottlenecks that constrain treatment capacity expansion.
- Self-ligating Aligners:Integrated clip mechanisms reduce friction during tooth movement, appealing to practices seeking shorter appointment intervals.
- Traditional Aligners:First-generation staging protocols still serve price-sensitive markets and complex malocclusion cases requiring hybrid treatment approaches.
Most installed capacity flows through Removable Aligners. Expansion is steepest in Fixed Aligners as specialist practices defend high-complexity case referrals.
End User:
Margin distribution follows professional credential requirements, with specialist oversight commanding premium pricing against direct patient access models.
- Orthodontists:Specialist-certified practitioners manage complex malocclusion cases requiring predictive staging confidence intervals. Practices in the United States and Germany are adopting AI-powered treatment planning platforms fastest, demanding sub-millimeter accuracy guarantees before case approval.
- General Dentists:Primary care dental practices increasingly retain mild-to-moderate orthodontic cases previously referred outward, supported by simplified digital workflow tools. Henry Schein distribution networks extend reach across this segment in North American markets.
- Cosmetic Dentists:Aesthetic-focused practices bundle aligner therapy with whitening and veneer procedures, capturing premium pricing in urban centers.
- Patients:Direct-to-consumer channels enable asynchronous orthodontist oversight through smartphone scanning apps, reversing traditional referral funnels in China and the United States.
Revenue concentration remains highest with Orthodontists. Patient-direct channels are climbing the fastest as remote monitoring platforms mature.
Technology:
Technology differentiation now determines competitive positioning more than manufacturing scale, with software infrastructure investments outpacing physical plant expansion.
- AI Integration:Machine learning algorithms trained on millions of completed cases predict tooth movement with calibrated precision, reducing refinement tray requirements. Specialist orthodontists in the United States and Germany demand predictive confidence intervals before treatment plan approval, compressing workflow timelines from weeks to days.
- 3D Printing:Stereolithography and multi-jet fusion systems enable same-day aligner fabrication for in-house production models, lowering logistics costs for high-volume clinic networks.
- Digital Scanning:Intraoral scanner ecosystems anchor chairside-to-fabrication workflow control, with iTero platforms locking in proprietary data pipelines.
- Computer-Aided Design:Staging software platforms interface with practice management systems through costly middleware development for legacy infrastructure.
Deployment is deepest for Digital Scanning. AI Integration is gaining share fastest as algorithmic accuracy reduces clinical revision cycles.
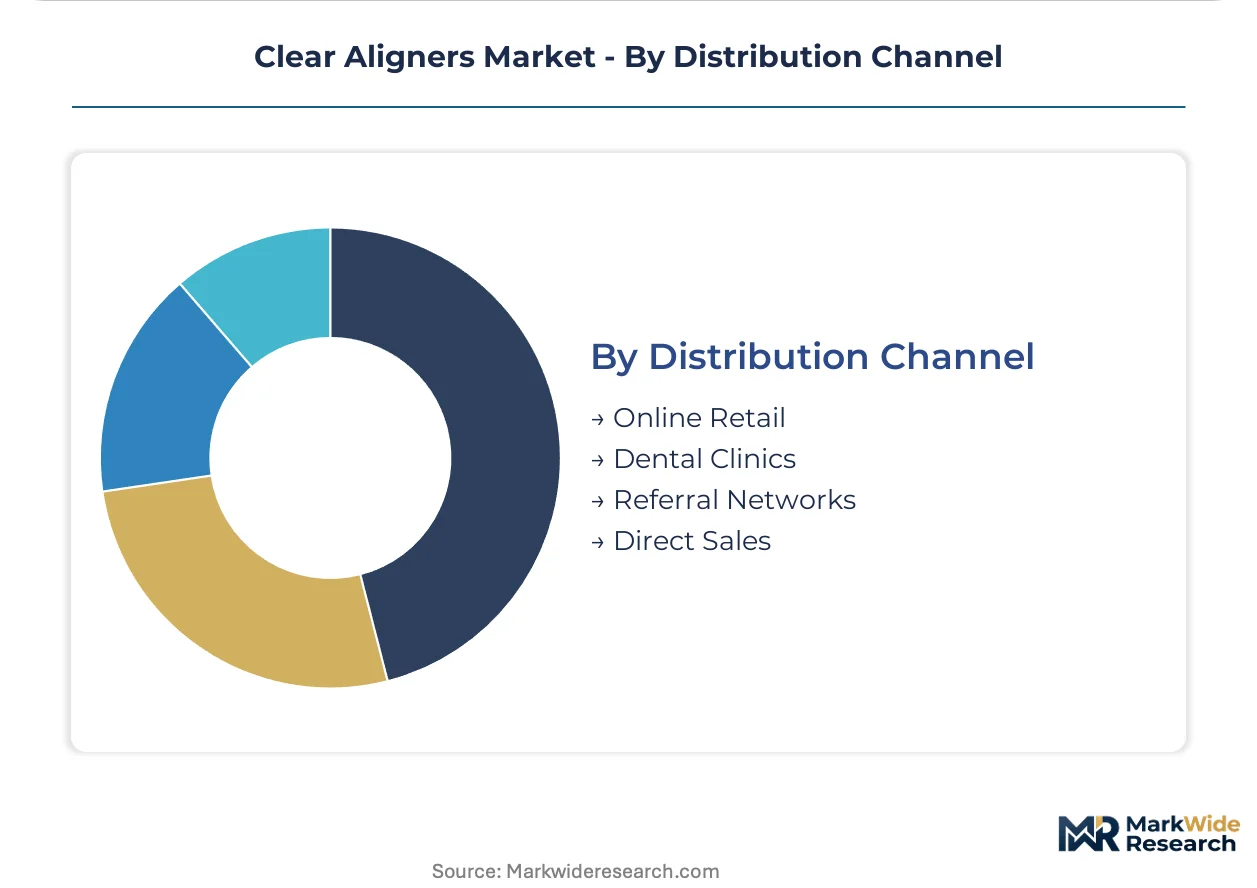
Distribution Channel:
Channel selection dictates regulatory exposure and patient acquisition economics, with asynchronous oversight models challenging traditional clinic gatekeeping.
- Dental Clinics:Professional supervision through brick-and-mortar practices retains the largest margin pool via chairside fees and comprehensive treatment bundling. Urban chains in China and the United States are unbundling initial consultations from full treatment quotes to compete with remote entry points.
- Online Retail:Direct-to-consumer platforms capture price-sensitive young adults through smartphone-based scanning apps before provider selection. FDA 510(k) pathway efficiency enables faster US product iteration compared to European notified body timelines.
- Referral Networks:Specialist-to-generalist case routing persists for complex malocclusions, though AI staging tools erode traditional referral dependencies.
- Direct Sales:Manufacturer field teams target high-volume orthodontic practices with bundled scanner-aligner-retainer packages.
Patient volume still concentrates in Dental Clinics. Online Retail shows the steepest expansion trajectory as remote monitoring platforms enable asynchronous oversight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clear aligner technology originated in Silicon Valley during the late 1990s before spreading to specialist orthodontic clusters in Western Europe and East Asia. Today the industry concentrates in five national markets where regulatory pathways, specialist density, and direct-to-consumer channel maturation diverge sharply.
United States
FDA 510(k) premarket notification enables faster product iteration cycles than European alternatives, attracting venture-backed startups to California and Massachusetts. The agency's Class II medical device classification allows asynchronous orthodontist oversight models to proliferate. Los Angeles and New York City host the densest concentrations of cosmetic dental practices bundling aligner therapy with aesthetic procedures.
Germany
Specialist licensing bottlenecks in Bavaria and North Rhine-Westphalia constrain treatment capacity despite queue growth from teen aesthetic preference. EU MDR notified body certification through German regulators imposes 12-18 month launch delays versus FDA timelines. Berlin and Munich anchor the largest European orthodontic specialist networks, where AI-powered treatment planning platforms achieve fastest adoption.
China
NMPA streamlined Class II device registration allows domestic manufacturers to displace imported aligners in tier-one city dental chains. Beijing and Shanghai dental clinics unbundle initial consultations from comprehensive quotes to compete with smartphone-based scanning apps. Shenzhen's hardware ecosystem supports intraoral scanner manufacturing for chairside-to-fabrication workflow control.
Japan
PMDA marketing authorization requirements favor established multinationals with clinical evidence portfolios over domestic entrants. Tokyo and Osaka orthodontic practices retain conservative staging protocols, slowing AI integration relative to German or American peers. METI industrial policy supports precision manufacturing of shape-memory polymer blends for regional supply.
Switzerland
Swissmedic certification aligns with EU MDR standards but processes applications faster than German notified bodies, creating a regulatory arbitrage window. Basel and Zurich host precision polymer research clusters serving orthodontic device fabrication. The country's dental insurance reimbursement structure favors premium-tier removable aligners over economy alternatives.
Clear Aligners Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software infrastructure and specialist channel depth. The vendor base stratifies into three tiers: technology-native platforms with AI-driven treatment planning, established dental conglomerates with distribution scale, and regional fabricators competing on price. Strategic moves concentrate on scanner-aligner ecosystem lock-in and direct-to-consumer channel capture.
Within the technology-native tier, Align Technology, Inc. exemplifies vertical control from digital scanning to fabrication. Among dental conglomerates, Institut Straumann AG and Henry Schein, Inc. occupy positions defined by specialist channel depth versus general practice reach respectively. These three anchors represent divergent bets on whether software precision or distribution scale captures greater value in orthodontic workflow compression.
| Leading Market Players |
|---|
| Institut Straumann AG |
| Argen Corporation |
| Align Technology, Inc. |
| Solventum |
| Angel Aligner |
| Envista Holdings Corporation |
| Henry Schein, Inc. |
| 3M Company |
| Dentsply Sirona |
| Others |
Supply Flow & Price Mechanics
Orthodontic software engineers concentrated in California and Massachusetts command salary premiums that widen the spread between premium AI-integrated aligner tiers and economy alternatives lacking predictive staging capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AI-powered treatment planning from conventional staging protocols and direct-to-consumer remote monitoring offerings. Price differentiation hinges on FDA 510(k) clearance tier and bundled scanner ecosystem access, with specialist practices absorbing premium chairside fees while price-sensitive young adults gravitate toward asynchronous oversight models. Pricing pressure stems from domestic Chinese manufacturers leveraging NMPA streamlined pathways to undercut imported aligners in tier-one cities. General dentistry practices show highest price sensitivity due to margin compression from retained mild-to-moderate cases, whereas orthodontic specialists prioritize predictive confidence intervals over per-unit cost.
Supply Chain Analysis
China's NMPA domestic-content preferences for Class II device registration are reshaping sourcing patterns, pushing multinational manufacturers toward local polymer compounding partnerships in Shenzhen and Shanghai. Medical-grade PETG feedstock draws from petrochemical complexes in the United States, Germany, and Saudi Arabia, while shape-memory polyurethane blends rest on specialty chemical production in Switzerland and Japan. Single-source vulnerability concentrates in German notified body certification bottlenecks that delay European launches. Distribution runs through specialist clinic networks in Germany, direct-to-consumer platforms in the United States, and tier-one city dental chains in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where teen and young adult patients now demand sub-millimeter predictive accuracy as a baseline specification rather than a premium upgrade.
For Market Incumbents: Cement scanner-aligner ecosystem lock-in through iTero-style proprietary data pipelines that cloud-native competitors cannot replicate without costly middleware development. Expand backward integration into shape-memory polymer research clusters in Basel and Zurich to defend fabrication margins against PETG price volatility. Prioritize CE marking pathway acceleration through Swissmedic regulatory arbitrage to offset German notified body delays. For New Entrants and Emerging Players: Begin with remote monitoring platform development targeting price-sensitive young adults in urban China and the United States who initiate treatment through smartphone scanning apps before provider selection. White-space concentration sits in general dentistry practices previously referring orthodontics outward, where simplified digital workflow tools enable mild-to-moderate case retention. Go-to-market leverage centers on asynchronous orthodontist oversight models that bypass traditional clinic gatekeeping. For Investors and Strategic Acquirers: Dental conglomerates with distribution scale represent the most active acquirer category in this space, seeking AI-native treatment planning capabilities to compress workflow timelines. Long-term viability favors technology platforms with proprietary staging algorithms and chairside scanner penetration rather than pure-play fabricators. Signal to monitor: FDA 510(k) clearance velocity divergence between asynchronous oversight models and traditional clinic-supervised pathways.| Strategic Initiative | Industry Significance |
|---|---|
| AI Treatment Planning Platform Development | Machine learning algorithms trained on millions of completed cases reduce refinement tray requirements by half for specialist orthodontists. |
| Intraoral Scanner Ecosystem Integration | iTero-style proprietary data pipelines anchor chairside-to-fabrication workflow control against cloud-native competitors. |
| Remote Monitoring Platform Launch | Asynchronous orthodontist oversight captures price-sensitive young adults bypassing traditional clinic gatekeeping in China and the United States. |
| Retention Device Bundling Strategy | Vivera-style post-treatment retainers generate recurring revenue streams with minimal incremental manufacturing complexity. |
| CE Marking Pathway Optimization | Swissmedic certification arbitrage offsets German notified body delays that extend European launch timelines by 12-18 months. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with orthodontic practice owners, AI treatment planning software developers, dental distribution channel managers, and polymer materials scientists with secondary validation against FDA 510(k) filings, NMPA registration databases, EU MDR notified body certification records, and intraoral scanner shipment disclosures. Bottom-up patient volume estimates by segment and geography triangulated against top-down manufacturer capacity and revenue disclosures.
Segment-weighting approaches distributed value and volume across product type, end user, technology, and distribution channel dimensions, with additional calibration for regulatory pathway efficiency differentials between FDA, EU MDR, and NMPA jurisdictions. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating teen aesthetic preference shift trajectories, orthodontist supply concentration constraints in Germany and France, and direct-to-consumer channel maturation velocity in the United States and China.
Caveats apply where EU MDR clinical evidence burden escalation, thermoplastic resin price volatility, or orthodontist licensing bottleneck relaxation could materially shift the outlook. Forecasts reflect assumptions about asynchronous oversight model regulatory acceptance and AI staging algorithm patent landscape stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peripheral Interventions Market
Medical Devices
Recanalization System Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Otoscope Devices Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Heating Pads Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Endoprosthesis Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market