
 Sweden Bariatric Surgery Market | 2026-2036
Sweden Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Bariatric Surgery Market Analytics
Modular procedure bundling is consolidating buyer choice across Sweden's bariatric surgery landscape. Capio Healthcare AB leverages its nationwide hospital network to anchor volume in standardized gastric bypass pathways. Aleris Healthcare AB competes through differentiated ambulatory offerings that reduce inpatient stays. Medtronic Plc sustains technology leadership in laparoscopic stapling systems deployed across Nordic surgical suites.
Bariatric surgery encompasses metabolic and gastrointestinal procedures that modify stomach anatomy or digestive pathways to induce sustained weight reduction, typically involving stapling, banding, or intestinal rerouting with specialized instrumentation designed for minimally invasive access. Sleeve gastrectomy now dominates procedure-type volumes due to its technical reproducibility and lower complication profile relative to gastric bypass. Laparoscopic technique leads the modality mix, though robotic surgery represents the fastest-growing segment as capital investment spreads through Sweden's university-affiliated centers. Hospitals capture the largest end-user margin pool, while ambulatory surgical centers gain traction for band adjustments and revision cases.
The Swedish Medical Products Agency (Läkemedelsverket) regulates device safety and clinical evidence requirements for implanted bariatric instruments, while the National Board of Health and Welfare (Socialstyrelsen) sets care guidelines that shape regional reimbursement thresholds. Sweden's adherence to EU MDR transition timelines tightens conformity assessment burdens for device suppliers serving Swedish hospitals. Stakeholders must monitor how the Health and Social Care Inspectorate (IVO) intensifies outcome-based oversight of volume-to-outcome relationships in high-throughput surgical centers.
Market Dynamics
Sweden's bariatric surgery market is consolidating around standardized care pathways that bundle pre-operative assessment, surgical intervention, and long-term metabolic monitoring into single reimbursement contracts. This shift compresses vendor choice while elevating centers that demonstrate superior volume-to-outcome ratios under the Swedish Association of Local Authorities and Regions framework.
Growth Catalysts
- EU MDR Compliance Deadlines:Sweden's accelerated conformity assessment timeline for legacy bariatric devices is clearing marginal suppliers from hospital procurement lists. High-compliance manufacturers gain preferential contracting positions.
- Metabolic Disease Burden:Rising type 2 diabetes prevalence in Stockholm and Gothenburg corridors is expanding eligibility criteria for surgical intervention under regional health authority protocols.
- Robotic Platform Diffusion:Capital investment cycles at university-affiliated centers are installing da Vinci systems that enable complex revision procedures previously referred abroad.
Market Restraints
- Specialized Surgeon Scarcity:Sweden's bariatric fellowship pipeline produces fewer than fifteen qualified specialists annually, capping procedure volume expansion regardless of demand.
- Reimbursement Compression:The national DRG tariff for gastric bypass has declined in real terms across three consecutive negotiation cycles, squeezing hospital margin pools.
- Device Concentration Risk:Nordic distribution networks for laparoscopic staplers depend on single-source logistics hubs in Denmark, exposing Swedish centers to cross-border supply interruptions.
Strategic Opportunities
- Skåne County Expansion:Malmö-Lund corridor remains underserved relative to per-capita obesity rates, presenting greenfield center development potential.
- Telehealth Integration:Remote patient monitoring platforms can extend post-surgical follow-up reach to northern Norrland counties with sparse specialist density.
- Ambulatory Migration:Band adjustments and port revisions are shifting to freestanding surgical centers eligible for simplified billing codes under Socialstyrelsen guidelines.
Industry Challenges
- MDR Technical Documentation:Legacy gastric band suppliers face costly clinical evidence regeneration to maintain Swedish market access, with several exiting rather than complying.
- Interoperability Friction:Robotic surgical systems from competing manufacturers utilize incompatible instrument mounts, complicating multi-vendor procurement strategies at consolidated hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Bariatric Surgery Market |
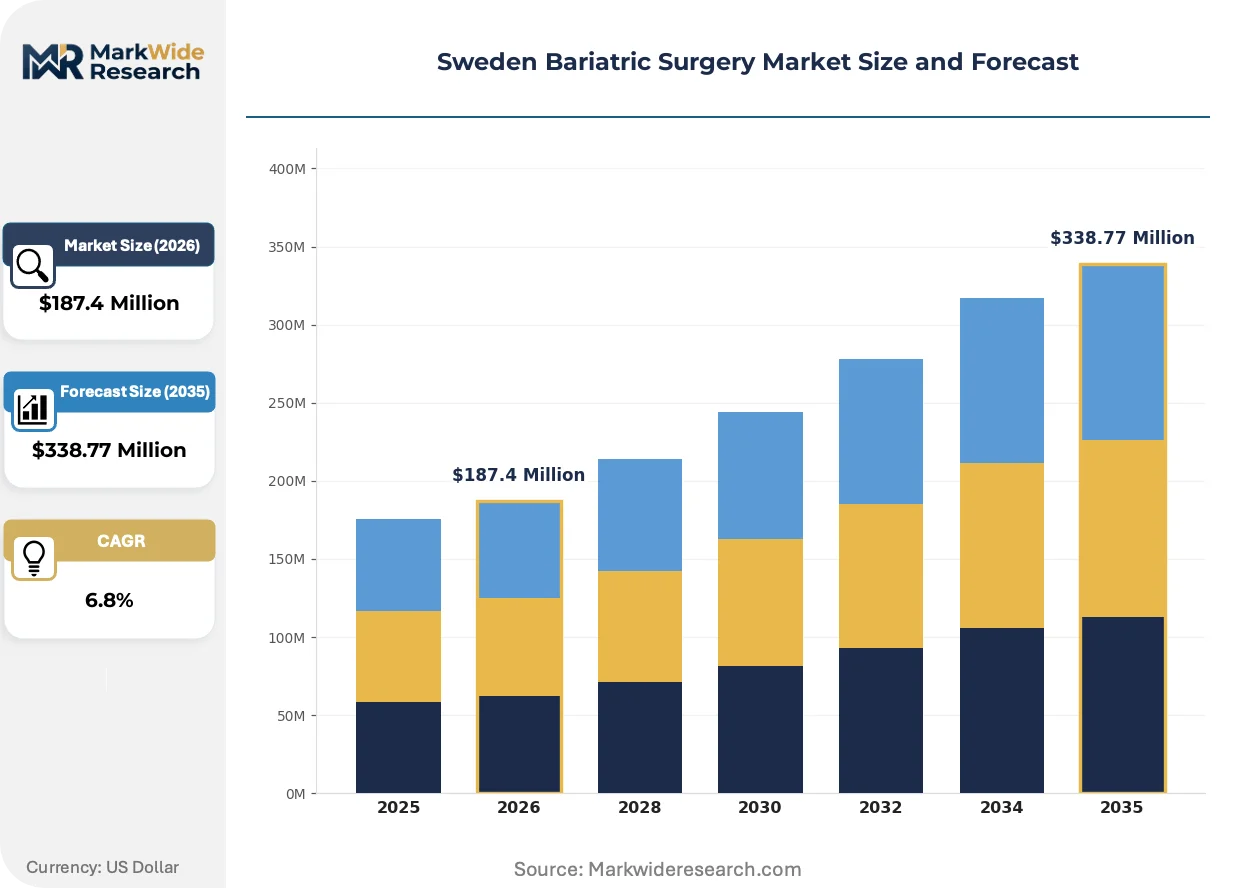
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Centers Technique: Open Surgery, Laparoscopic Surgery, Robotic Surgery, Endoscopic Approach Patient Demographics: Adults, Adolescents, Seniors, Obese Individuals |
| Companies Covered | Capio Healthcare AB, Aleris Healthcare AB, GHP Specialty Care AB, Svenska Kirurgkliniken AB, Team Olmed AB, Medtronic Plc, Johnson & Johnson, Nordic Gastric Balloon, Mölnlycke Health Care AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Bariatric Surgery Market Evolving Landscape
Swedish bariatric surgery is pivoting toward precision metabolic intervention, where anatomical modification integrates with pharmacological adjuvants and digital behavior modification. This convergence demands new competencies from surgical teams and reshapes vendor relationships across the care continuum.
Single-anastomosis duodeno-ileal bypass with sleeve gastrectomy (SADI-S) is overtaking conventional Roux-en-Y gastric bypass in high-volume Swedish centers. Karolinska University Hospital and Sahlgrenska Academy are adopting SADI-S for super-obese patients with insulin-resistant diabetes. The technique's reduced malabsorption profile is compressing nutritional complication rates and shortening average length of stay.
Socialstyrelsen revised national care guidelines in 2023 to mandate centralized reporting of bariatric outcomes to the Scandinavian Obesity Surgery Registry. This regulatory tightening is forcing smaller county hospitals to affiliate with designated high-volume centers or exit metabolic surgery entirely. Device suppliers must now support dual-tier service models: direct-to-university relationships and indirect support through contracted hub hospitals.
County council procurement offices are unbundling device supply from procedure reimbursement, creating separate competitive tenders for staplers, energy devices, and suture materials. Stockholm County Council pioneered this split in 2022; Västra Götaland and Skåne have adopted variants. The shift exposes manufacturers to pure price competition on commodity categories while preserving premium positioning for integrated robotic platforms.
Sweden Bariatric Surgery Market Segmentation
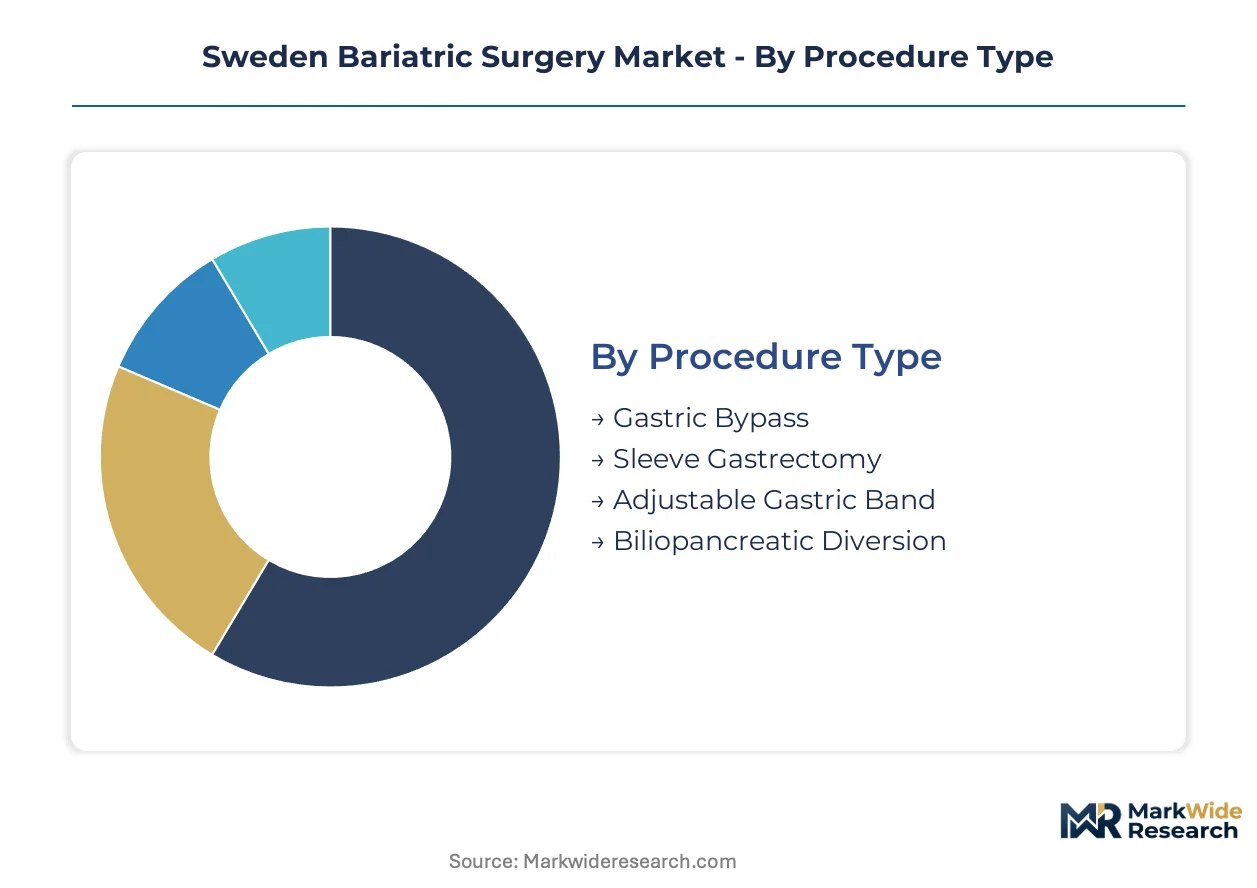
Sweden's bariatric surgery market fragments across four structural dimensions that determine procurement patterns and reimbursement pathways. Procedure type and technique selection drive capital allocation, while end-user concentration shapes vendor contracting power.
Procedure Type:
Supply concentration among high-volume university hospitals favors techniques with reproducible outcomes and shorter learning curves.
- Sleeve Gastrectomy:Partial stomach resection creates a tubular gastric pouch without intestinal rerouting. Stockholm and Gothenburg corridors concentrate demand where Karolinska and Sahlgrenska Academy surgeons achieve sub-30-minute operative times through standardized pathways.
- Gastric Bypass:Roux-en-Y configuration partitions the stomach and reroutes the small intestine. Regional health authorities in Västra Götaland and Skåne steer complex diabetic patients toward this metabolic-intensive option despite longer operative duration.
- Adjustable Gastric Band:Silicone band placement with subcutaneous port for saline adjustment. Malmö-Lund corridor retains limited volume for revision-tolerant patients declining irresectional alternatives.
- Biliopancreatic Diversion:Malabsorptive technique with distal gastrectomy and long-limb bypass. Norrland counties occasionally refer super-obese cases southward given nutritional complication management requirements.
Today's leader: Sleeve Gastrectomy. Tomorrow's challenger: Gastric Bypass as SADI-S modifications gain Socialstyrelsen protocol acceptance.
End User:
Reimbursement tiering separates inpatient facilities from ambulatory settings under Swedish Association of Local Authorities and Regions contracts.
- Hospitals:Academic medical centers and county hospitals capture complex primary procedures and emergency revisions. Stockholm County Council's bundled payment models consolidate volume at designated high-throughput sites.
- Ambulatory Surgical Centers:Freestanding facilities exploit simplified billing codes for band adjustments and port revisions. Aleris Healthcare AB operates specialized metabolic day-surgery units in metropolitan corridors.
- Clinics:Private practice settings handle pre-operative assessment and long-term follow-up. Pre-surgical multidisciplinary evaluation concentrates in obesity medicine clinics affiliated with surgical hubs.
- Specialty Centers:Dedicated bariatric units within larger hospital networks. Capio Healthcare AB maintains standardized gastric bypass pathways across its nationwide facility footprint.
Procurement gravity: Hospitals command premium device pricing through volume aggregation. Margin compression: Clinics face unbundling of assessment services from surgical reimbursement.
Technique:
Capital intensity and surgeon training requirements stratify adoption across Sweden's regional health authorities.
- Laparoscopic Surgery:Minimally invasive abdominal access through trocar placement. The Swedish Medical Products Agency's EU MDR compliance timeline favors established stapling and energy device suppliers with Nordic distribution infrastructure.
- Robotic Surgery:da Vinci platform utilization for complex revision and super-obese cases. Sahlgrenska and Uppsala University Hospital investment cycles are installing systems enabling procedures previously referred to Denmark or Germany.
- Open Surgery:Conventional laparotomy for conversion cases and emergent complications. Rural county hospitals retain capability for hemodynamically unstable patients unsuitable for pneumoperitoneum.
- Endoscopic Approach:Transoral techniques including gastric balloon placement and outlet reduction. Socialstyrelsen guidelines restrict reimbursement to investigational protocols limiting commercial scale.
Installed base dominance: Laparoscopic Surgery. Steepest expansion trajectory: Robotic Surgery as university-affiliated centers complete capital refresh cycles.
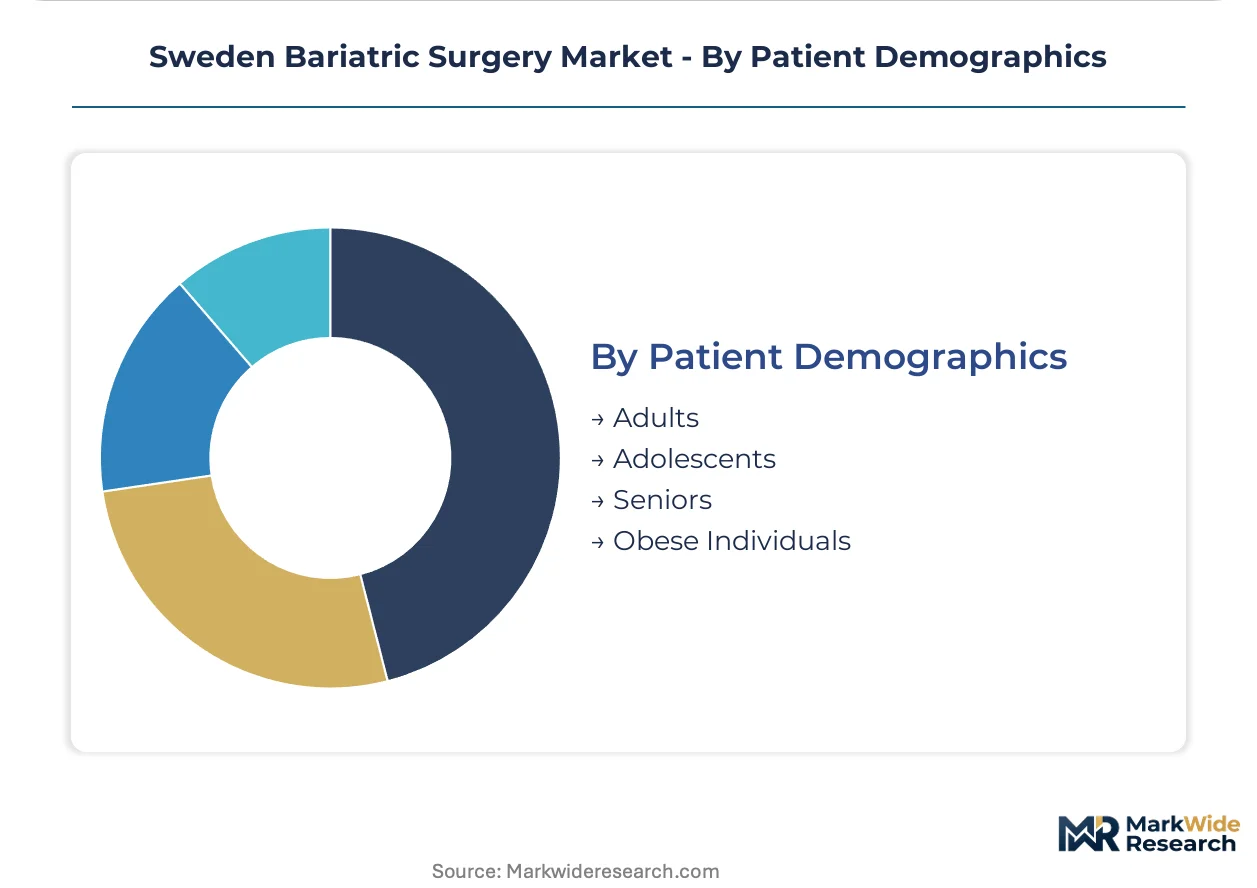
Patient Demographics:
Eligibility criteria under National Board of Health and Welfare protocols segment addressable population by metabolic risk profile.
- Adults:Ages 18-65 with BMI thresholds and comorbidity documentation. Metropolitan Stockholm generates highest per-capita surgical volume through integrated primary care referral networks.
- Seniors:Patients over 65 with cardiovascular risk stratification. Regional variation in frailty assessment protocols creates eligibility inconsistency across county councils.
- Adolescents:Ages 13-17 with severe obesity and failed lifestyle intervention. Restricted to designated pediatric surgical centers at Astrid Lindgren Children's Hospital and equivalent university sites.
- Obese Individuals:Super-obese category with BMI exceeding 50 kg/m² requiring specialized anesthetic and critical care infrastructure. Concentrated at Karolinska and Sahlgrenska given ICU bed availability.
Volume concentration: Adults. Regulatory expansion candidate: Adolescents if pediatric center designation protocols broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's bariatric surgery infrastructure emerged from university hospital networks established in the 1970s, with Karolinska Institutet pioneering metabolic surgical protocols that diffused through Scandinavian medical education. The national healthcare system's county council structure concentrates advanced procedures at designated high-volume centers.
Stockholm County
Metropolitan Stockholm generates the highest per-capita surgical volume through integrated primary care referral networks. Karolinska University Hospital anchors the corridor with specialized SADI-S adoption for super-obese patients. The Swedish Association of Local Authorities and Regions steers complex cases to designated high-throughput sites here.
Västra Götaland
Sahlgrenska Academy in Gothenburg competes for volume leadership through robotic platform investment and revision surgery specialization. Regional health authorities here steer insulin-resistant diabetic patients toward metabolic-intensive bypass options. The county's bundled payment models consolidate procurement power.
Skåne County
The Malmö-Lund corridor remains underserved relative to per-capita obesity rates, presenting greenfield center development potential. Socialstyrelsen guidelines restrict adolescent procedures to designated sites, limiting Malmö's pediatric expansion. Private operators exploit simplified billing codes for ambulatory band adjustments.
Uppsala County
Uppsala University Hospital investment cycles are installing da Vinci systems enabling complex procedures previously referred abroad. The county's rural catchment demands telehealth integration for post-surgical follow-up. Academic affiliation attracts fellowship-trained surgeons from Stockholm's training pipeline.
Sweden Bariatric Surgery Market Competitive Landscape
The competitive structure tilts toward integrated hospital networks with standardized care pathways. Two strategic archetypes dominate: nationwide facility operators bundling pre-operative assessment through long-term monitoring, and technology suppliers with EU MDR-compliant device portfolios. Consolidation pressures favor scale players capable of volume-to-outcome documentation under national reimbursement frameworks. Strategic moves center on hub-and-spoke affiliations with smaller county hospitals and telehealth platform integration for geographic expansion.
Within the integrated provider tier, Capio Healthcare AB and Aleris Healthcare AB represent contrasting operational models. Capio leverages its nationwide hospital footprint to anchor standardized gastric bypass pathways, while Aleris competes through differentiated ambulatory offerings. Medtronic Plc occupies a technology leadership position in laparoscopic systems deployed across Nordic surgical suites. These three exemplify how vendor relationships reshape around bundled contracting and outcome-based procurement.
| Leading Market Players |
|---|
| Capio Healthcare AB |
| Aleris Healthcare AB |
| GHP Specialty Care AB |
| Svenska Kirurgkliniken AB |
| Team Olmed AB |
| Medtronic Plc |
| Johnson & Johnson |
| Nordic Gastric Balloon |
| Mölnlycke Health Care AB |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up hospital networks in Sweden anchor procurement discipline through standardized gastric bypass pathways, compressing vendor margins while concentrating purchasing leverage at designated high-throughput centers under the Swedish Association of Local Authorities and Regions framework.
Pricing Analysis
Procedure-based bundled contracting dominates Swedish bariatric surgery reimbursement, with county councils unbundling device supply from surgical tariffs to create separate competitive tenders. Price differentiation hinges on EU MDR compliance tier and robotic platform integration level, with university-affiliated centers commanding premium positioning for complex revision cases. Cost compression in laparoscopic stapler categories intensifies as Stockholm County Council's split-tender model spreads to Västra Götaland and Skåne. Ambulatory surgical centers exhibit highest price sensitivity for band adjustments, while academic medical centers prioritize outcome documentation over unit cost.
Supply Chain Analysis
EU MDR technical documentation requirements gate Swedish market access for legacy gastric band suppliers, with several manufacturers exiting rather than regenerating clinical evidence. Device supply concentrates in Denmark, Germany, and Switzerland, with Nordic distribution networks for laparoscopic staplers resting on single-source logistics hubs across the Øresund. Raw material dependencies span medical-grade silicone for adjustable bands, surgical stainless steel for stapling cartridges, and specialized polymers for trocar seals. Single-source vulnerability in cross-border logistics exposes Swedish centers to Danish customs delays. Distribution runs through hospital procurement consortia and GPO contracts managed at county council level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's bariatric surgery market compounds steadily as metabolic disease burden expands eligibility criteria and robotic platform diffusion enables complex procedures previously referred abroad.
For Market Incumbents: To counter reimbursement compression across three consecutive DRG negotiation cycles, Capio Healthcare AB and Aleris Healthcare AB should deepen backward integration into telehealth-enabled post-surgical monitoring platforms and secure exclusive da Vinci service contracts at university-affiliated centers before competitor capital refresh cycles complete. For New Entrants and Emerging Players: Specialist ambulatory operators represent the most penetrable channel partner type for band adjustment and port revision services, with Skåne County's Malmö-Lund corridor offering greenfield center development potential given underserved per-capita obesity rates and simplified Socialstyrelsen billing codes for freestanding facilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap device suppliers facing EU MDR compliance cost burdens, with long-term viability hinging on successful conformity assessment completion and Karolinska University Hospital contracting relationships. The signal to watch is Socialstyrelsen protocol acceptance for SADI-S modifications accelerating gastric bypass volume recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Installation | da Vinci system deployment at Sahlgrenska and Uppsala enables complex revision procedures previously referred to Denmark. |
| Telehealth Integration | Remote patient monitoring platforms extend post-surgical follow-up reach to northern Norrland counties with sparse specialist density. |
| EU MDR Compliance Pathway | Accelerated conformity assessment timelines for legacy bariatric devices clear marginal suppliers from hospital procurement lists. |
| Hub-and-Spoke Affiliation | Smaller county hospitals affiliate with designated high-volume centers under Socialstyrelsen outcome reporting mandates. |
| Ambulatory Migration Strategy | Band adjustments and port revisions shift to freestanding surgical centers eligible for simplified billing codes. |
Research Methodology
Direct dialogue with bariatric surgeons, hospital procurement managers, biomedical engineers, and county council health economists grounded qualitative insights, validated against Scandinavian Obesity Surgery Registry outcomes data, Swedish Medical Products Agency device filings, Socialstyrelsen care guideline revisions, and EU MDR transition timelines. Bottom-up procedure volume modeling triangulated with top-down reimbursement flow analysis.
Segmented outputs across procedure type, technique modality, end-user setting, and patient demographic cohort drove the analytical framework throughout the projection horizon. CAGRs derived from historical volume trajectories at Karolinska and Sahlgrenska, robotic platform installation pipelines, and regional health authority reimbursement negotiation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to specialized surgeon fellowship pipeline output, EU MDR compliance cost pass-through success, and IVÖ intensification of volume-to-outcome oversight. A model refresh is warranted upon material change in Socialstyrelsen protocol acceptance for SADI-S or robotic surgery reimbursement tiering.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
United Kingdom Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Bariatric Medical Chairs Market