
 Children's Oral Care Market | 2026-2036
Children's Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
Children's Oral Care Market Insights
The gap between premium natural formulations and mass-market fluoride-based products is recalibrating how parents allocate spending across income brackets. Colgate-Palmolive Company leverages its pediatric toothpaste portfolio to anchor shelf presence in emerging markets, while Procter & Gamble competes through omnichannel distribution density for its electric toothbrush lines. Haleon plc differentiates via pharmacist-driven recommendation networks for its specialty children's rinse products.
Children's oral care encompasses toothpaste, toothbrushes, mouthwash, and dental floss formulated with age-appropriate active ingredients such as controlled fluoride concentrations below 500 ppm for infants and toddlers, delivered through low-abrasivity silica bases and soft-bristle nylon configurations designed for developing enamel and gingival tissue. Its primary purpose is preventing early childhood caries and establishing durable hygiene habits before permanent dentition emerges. Toothpaste dominates value contribution due to replenishment frequency, while fluoride-free and natural formulations within the formulation dimension are expanding fastest as clean-label preferences migrate from adult to pediatric categories. The age group dimension shows school-age children generating the highest absolute volume, though infant-specific products command disproportionate margin pools through premium positioning.
The FDA governs active ingredient safety and labeling claims for children's oral care products sold in the United States, while the EPA regulates fluoride discharge from manufacturing facilities producing fluoridated formulations. ISO 11609 sets global physical and chemical requirements for dentifrices, including abrasivity limits that constrain formulation choices for pediatric variants. Stakeholders must monitor how evolving state-level restrictions on per- and polyfluoroalkyl substances intersect with existing fluoride debates to reshape acceptable ingredient palettes.
Market Dynamics
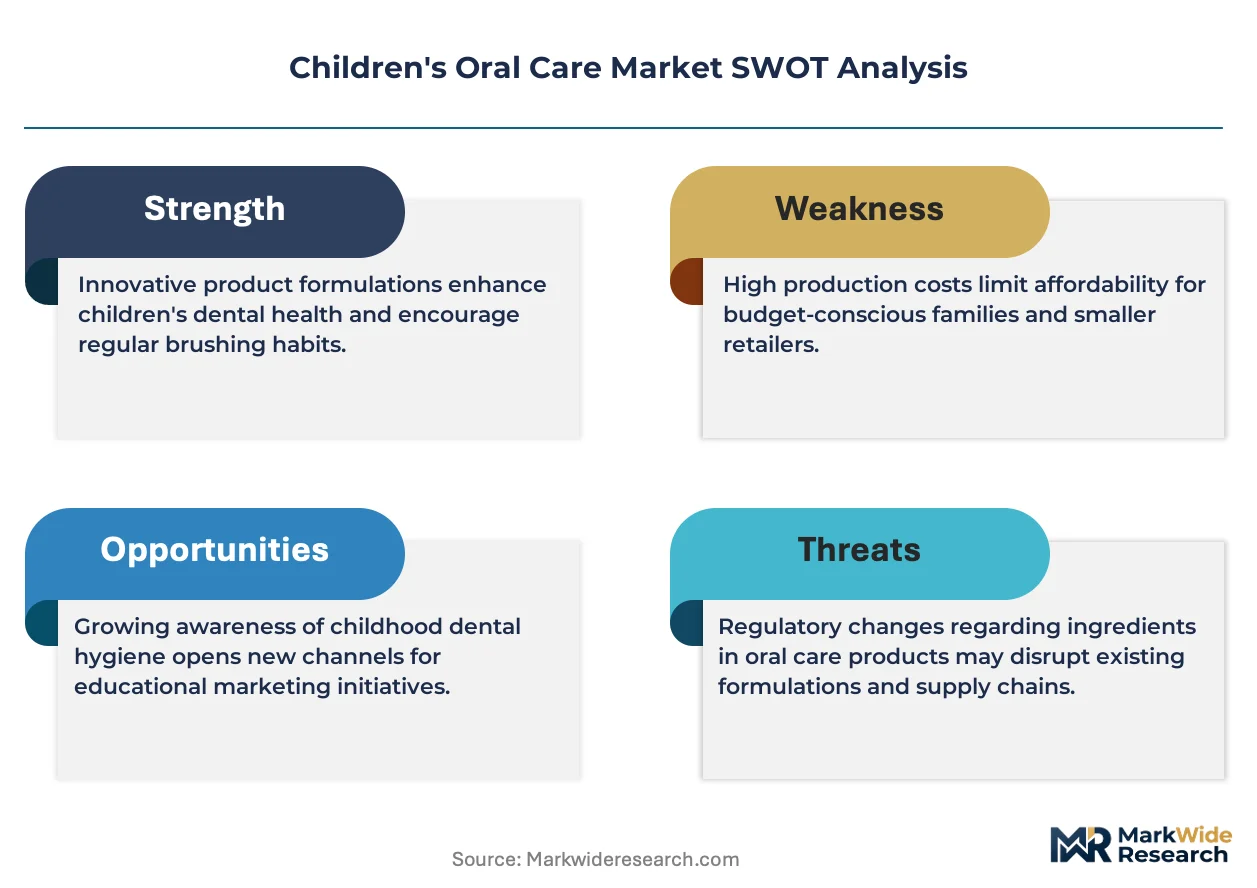
The FDA's monograph system for over-the-counter oral care products is compressing formulation flexibility while simultaneously elevating compliance costs for pediatric-specific claims and active ingredient concentrations. This regulatory architecture is forcing manufacturers to revalidate existing portfolios and fragment R&D budgets across multiple approval pathways.
Growth Catalysts
- Pediatric Dental Clinic Expansion:Preventive service menus for young patients are broadening across the United States, creating institutional pull for professional-grade home care products and patient education materials.
- Clean-Label Migration:ISO 11609 abrasivity standards for dentifrices are enabling fluoride-free and natural formulations to achieve performance parity with conventional options, accelerating parent acceptance.
- EPA Fluoride Discharge Rules:Manufacturing compliance investments for fluoridated formulations are concentrating production capacity among capitalized players, indirectly stabilizing supply security for major brands.
Market Restraints
- Silica Base Volatility:Low-abrasivity silica supply for infant formulations faces input cost pressure from construction and electronics demand competing for refined grades.
- Active Ingredient Concentration Limits:FDA-mandated fluoride ceilings below 500 ppm for toddlers constrain efficacy differentiation and compress margin pools in the infant segment.
- Biodegradable Nylon Bristle Substitution:Plant-based alternatives to petroleum-derived nylon 6,12 for soft-bristle configurations exhibit durability gaps that limit full material transitions.
Strategic Opportunities
- Pharmacist-Driven Recommendation Networks:Specialty children's rinse products are penetrating pharmacy channels through trained staff consultation, bypassing saturated mass retail shelf competition.
- School-Age Preventive Programs:Institutional procurement contracts for oral health education kits present volume anchors for toothbrush and toothpaste bundling in the United States.
- State-Level PFAS Restrictions:Emerging prohibitions on per- and polyfluoroalkyl substances in packaging and formulations are creating first-mover advantage windows for PFAS-free certification claims.
Industry Challenges
- Pediatric Toxicology Expertise Scarcity:Formulation chemists with specific training in age-appropriate active ingredient metabolism and accidental ingestion risk modeling command premium compensation and extended hiring timelines.
- Dual Certification Complexity:Products claiming both FDA monograph compliance and natural/organic certification face conflicting documentation requirements that extend launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children's Oral Care Market |
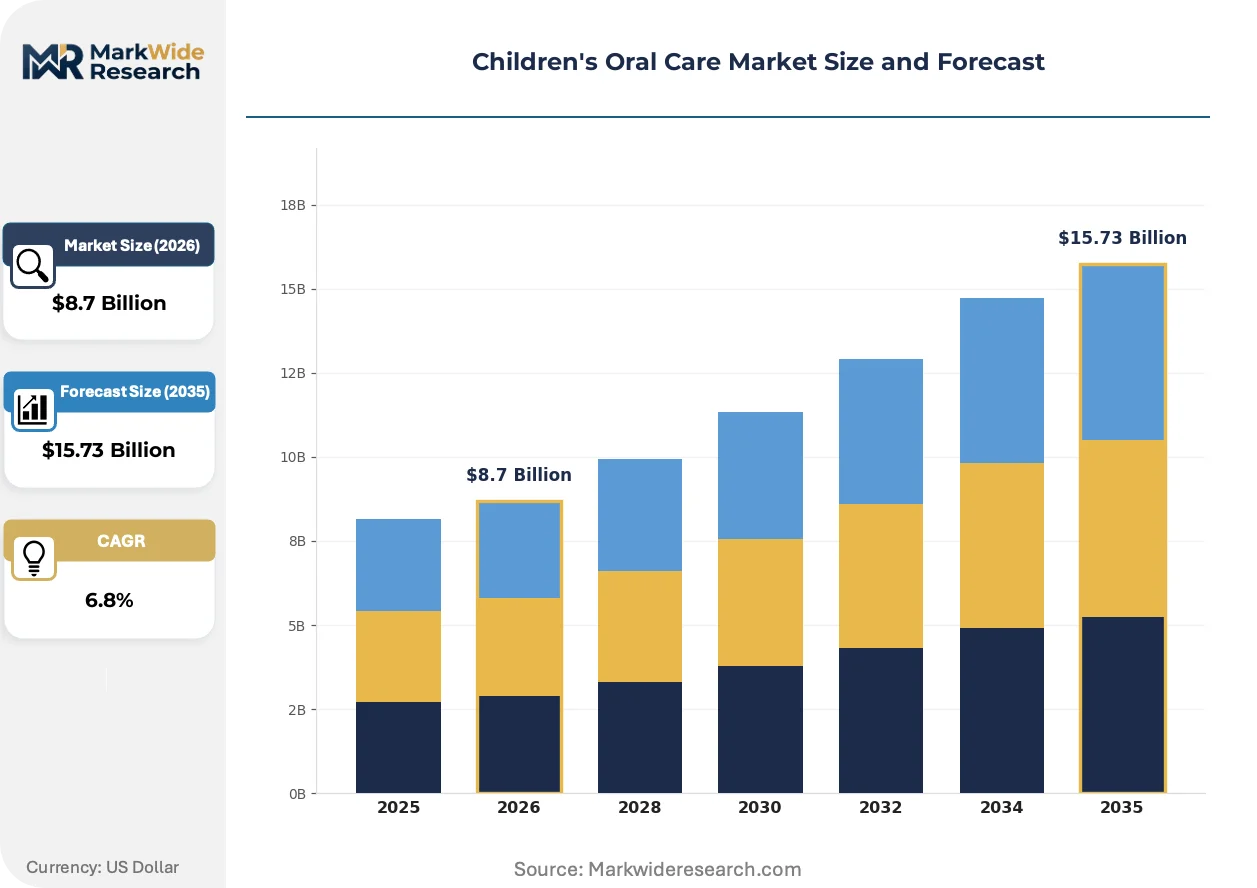
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Toothbrush, Mouthwash, Dental Floss Age Group: Infants, Toddlers, Preschoolers, School Age Formulation: Fluoride-Free, Fluoridated, Natural, Gel Distribution Channel: Supermarkets, Online Retail, Pharmacies, Specialty Stores |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble, Johnson & Johnson Services, Inc., Haleon plc, Unilever plc, Church & Dwight Co., Inc., Pigeon Corporation, Lion Corporation, Sunstar Suisse S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children's Oral Care Market Trends and Innovations
Smart dispensing technologies and connected hygiene devices are penetrating the children's oral care segment, shifting competitive focus from chemical formulation to behavioral data capture and habit-formation algorithms. These innovations are reshaping how parents monitor compliance and how brands secure recurring revenue.
Connected electric toothbrush systems with pressure sensors and brushing timers are automating parental oversight of children's technique and duration. Pediatric dental practices in the United States are bundling these devices with preventive care packages, creating institutional endorsement channels that bypass traditional retail gatekeepers. The technology is automating habit formation by delivering real-time feedback that previously required direct adult supervision.
The EPA's evolving framework for fluoride discharge from manufacturing facilities is tightening effluent standards for facilities producing fluoridated pediatric formulations. Compliance investments are pushing smaller contract manufacturers toward tolling arrangements with capitalized partners or exit from the pediatric category entirely. Infant-specific toothpaste production is consolidating among multi-site operators with dedicated wastewater treatment infrastructure.
Subscription-based replenishment models for children's toothpaste and brush heads are displacing episodic retail purchasing among higher-income households in the United States. Direct-to-consumer channels are capturing recurring revenue through age-staged product curation that automatically advances formulations as children develop. This shift is most visible in urban coastal markets where pharmacy visit frequency has declined and delivery logistics density supports reliable replenishment cycles.
Children's Oral Care Market Segmentation
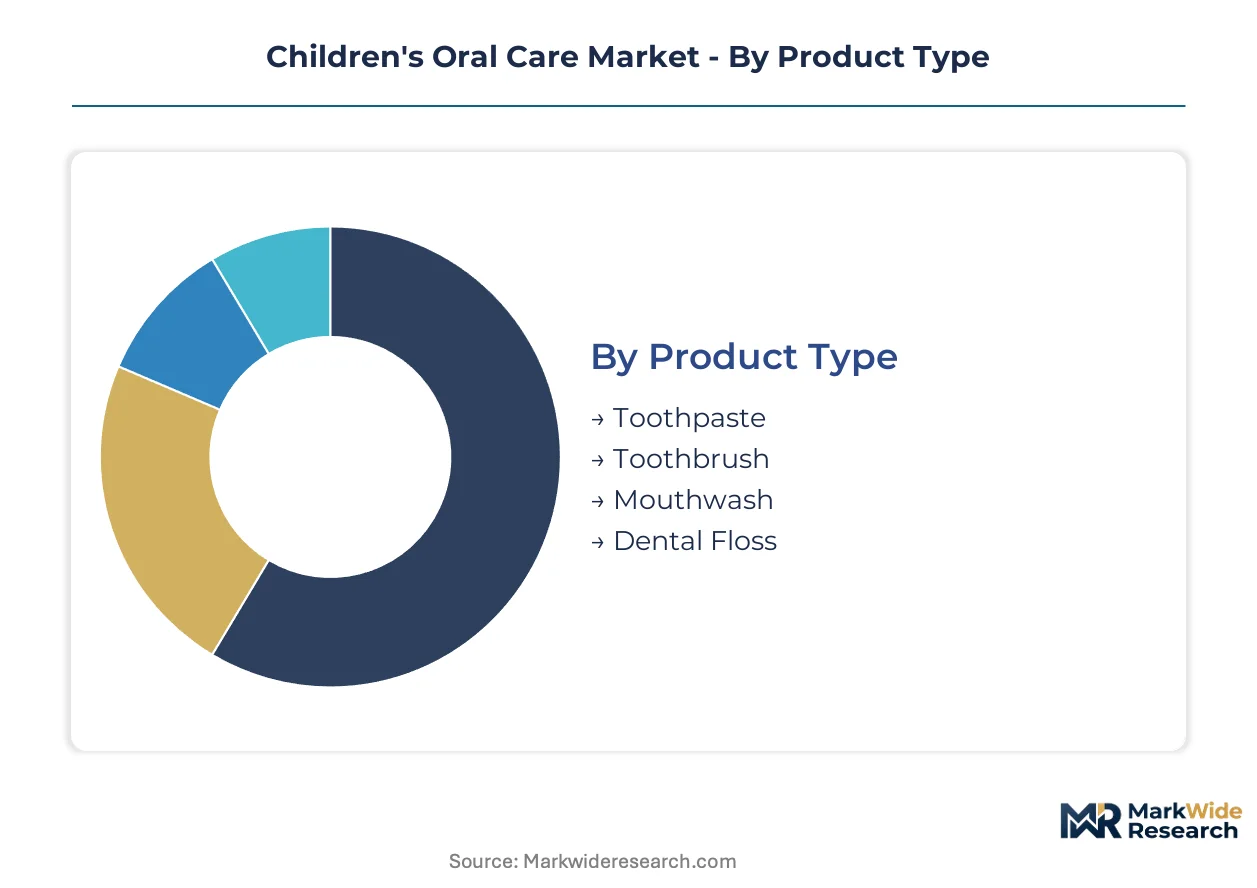
Children's oral care manufacturers configure product portfolios across four intersecting dimensions. Each dimension carries distinct margin profiles and regulatory exposure, forcing strategic prioritization in R&D allocation and channel partnerships.
Product Type:
Parents allocate spending differently by product based on replenishment cadence and perceived clinical necessity.
- Toothpaste:Formulated with low-abrasivity silica bases below ISO 11609 limits and controlled fluoride concentrations under 500 ppm for toddlers. Replenishment frequency drives absolute value contribution in the United States, where subscription models now capture urban coastal households.
- Toothbrush:Soft-bristle nylon 6,12 configurations dominate manual segments, while connected electric systems with pressure sensors penetrate pharmacy and dental practice bundling. School-age children generate highest unit volumes through institutional procurement programs.
- Mouthwash:Specialty rinse products leverage pharmacist consultation networks for differentiation. Concentrated demand among school-age children with orthodontic appliances.
- Dental Floss:Flavored and textured variants target habit formation in preschoolers. Lowest absolute value but highest margin percentage in specialty retail.
Volume sits with toothpaste; growth tilts toward connected toothbrush systems.
Age Group:
Developmental stages dictate active ingredient metabolism, accidental ingestion risk, and parental price sensitivity.
- School Age:Independent brushing capability expands product complexity to include whitening-adjacent formulations and electric device compatibility. United States demand concentrates here through school-based preventive program procurement.
- Infants:Fluoride-free and swallow-safe formulations command premium positioning. FDA concentration limits below 500 ppm constrain efficacy claims and compress margin pools.
- Toddlers:Transition formulations bridge training toothpaste and standard pediatric products. Flavor acceptance drives repeat purchase decisions.
- Preschoolers:Character licensing and gamification features influence selection. Pharmacy channels capture higher conversion than mass retail for this segment.
Absolute volume concentrates with school-age children; steepest expansion trajectory appears in infant-specific certified organic lines.
Formulation:
Clean-label preferences migrate from adult categories, fragmenting R&D budgets across certification pathways.
- Natural:Plant-derived surfactants and preservative systems replacing synthetic alternatives. Parent acceptance accelerates as ISO 11609 abrasivity parity with conventional options improves.
- Fluoridated:Standard-of-care for caries prevention with EPA discharge compliance costs concentrating production among capitalized manufacturers. Institutional endorsement remains strongest here.
- Fluoride-Free:Positioned for infant safety and parental anxiety segments. State-level water fluoridation debates indirectly drive regional demand variation.
- Gel:Texture preference among children resistant to paste consistencies. Lower abrasivity suits toddlers with developing enamel.
Revenue weight rests with fluoridated formulations; clean-label migration is gaining share fastest.
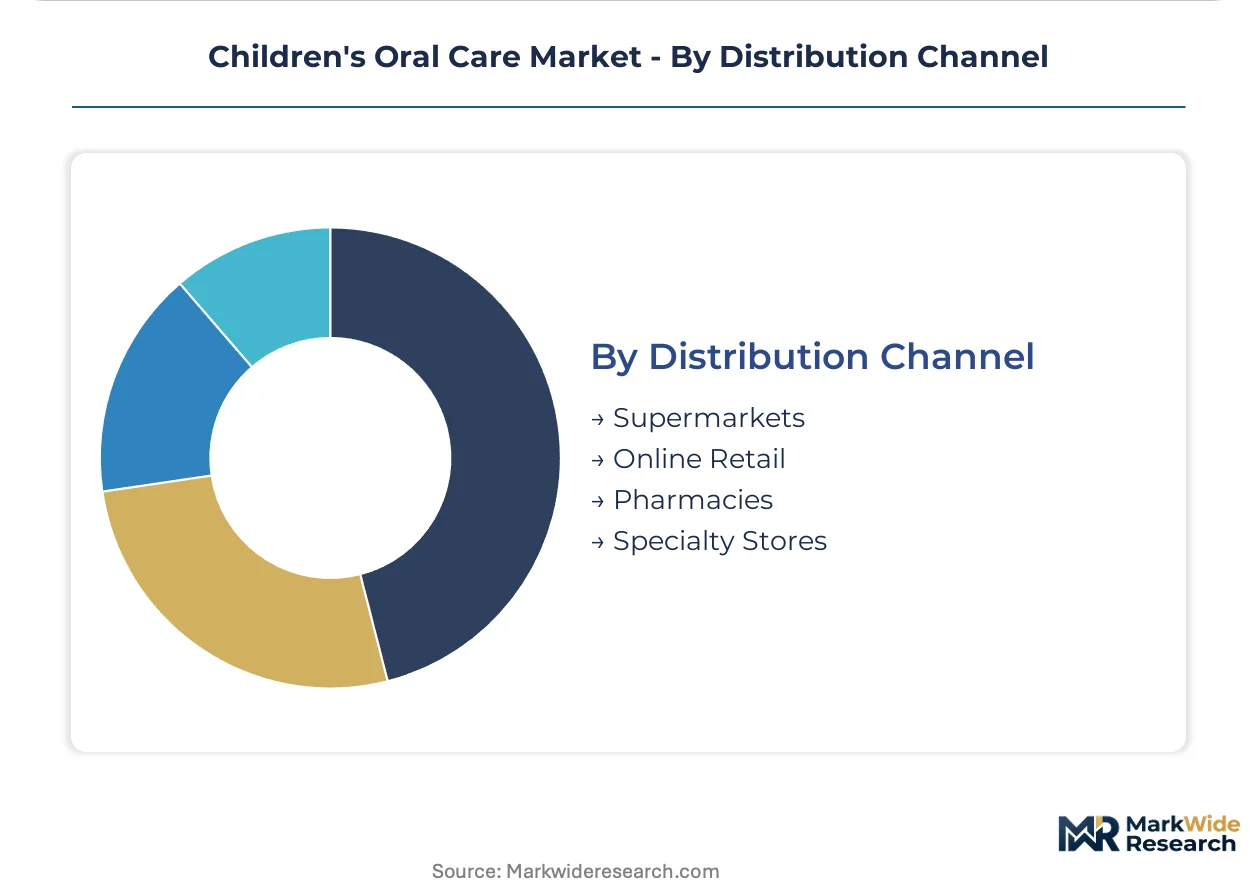
Distribution Channel:
Channel selection determines margin structure and access to professional endorsement networks.
- Pharmacies:Trained staff consultation drives specialty rinse and infant formulation conversion. Haleon plc and comparable operators prioritize this channel for recommendation-dependent products.
- Online Retail:Subscription replenishment and age-staged curation displace episodic purchasing. Direct-to-consumer brands capture recurring revenue through automatic formulation advancement.
- Supermarkets:Mass-market fluoride-based products compete on shelf presence and price promotion. Colgate-Palmolive Company anchors positioning here.
- Specialty Stores:Premium natural and organic certifications justify price positioning. Lower volume but highest margin percentage across channels.
Transaction volume flows through supermarkets; value capture is climbing fastest in online subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors pediatric dental service expansion in the United States, with major hospital systems operating specialized children's oral health centers that drive institutional procurement of professional-grade home care products.
United States
Pediatric dental clinics in Texas and Florida are broadening preventive service menus, creating pull for patient education materials and home care kits. The FDA's monograph system governs over-the-counter oral care active ingredients and labeling claims. Manufacturing of fluoridated formulations concentrates in New Jersey and Pennsylvania corridors with dedicated EPA-compliant wastewater infrastructure.
Germany
Pharmacy channel penetration for specialty children's rinse products runs deeper than mass retail, with trained staff consultation driving conversion in Bavaria and North Rhine-Westphalia. ECHA REACH regulations constrain preservative system choices for natural formulations. The Stuttgart industrial cluster hosts precision molding operations for soft-bristle toothbrush components serving European distribution networks.
China
Domestic demand for infant-specific fluoride-free formulations is expanding in Shanghai and Guangzhou as clean-label preferences migrate from adult categories. NMPA oversight of cosmetic-grade oral care ingredients intersects with GB standards for product safety. The Yangtze River Delta concentration of silica processing facilities supplies low-abrasivity bases for regional pediatric toothpaste production.
Japan
School-based preventive oral health programs in Tokyo and Osaka generate institutional procurement volume for toothbrush and toothpaste bundling. METI guidelines on product labeling for children's goods shape marketing compliance requirements. The Chubu region around Nagoya maintains specialized polymer facilities for nylon 6,12 bristle production with pediatric softness specifications.
India
Urban coastal households in Maharashtra and Karnataka are adopting subscription replenishment models for children's oral care, displacing episodic pharmacy purchasing. BIS standards for dentifrice safety and quality create certification requirements for imported and domestic formulations. The Gujarat pharmaceutical corridor is expanding contract manufacturing capacity for fluoride-free pediatric lines targeting export markets.
Children's Oral Care Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the children's oral care landscape, with integrated manufacturing operations holding cost advantages in fluoridated formulations while brand-centric operators outsource production to focus on distribution density. The market structure tilts toward consolidation at the premium tier and fragmentation in natural-certified niches. Three archetypes dominate: multinational FMCG conglomerates with pediatric portfolio extensions, regional pharmacy-channel specialists leveraging professional endorsement networks, and direct-to-consumer brands built on subscription replenishment mechanics. Competitive moves concentrate on pharmacist consultation program expansion and age-staged product curation systems that automate formulation advancement as children develop.
Among the multinational FMCG tier, Colgate-Palmolive Company and Procter & Gamble occupy positions defined by shelf presence density and omnichannel reach respectively, while Haleon plc exemplifies the pharmacy-channel specialist archetype through recommendation-dependent rinse products. These three entities represent distinct strategic vectors: mass-market anchoring, connected device bundling, and professional endorsement capture.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble |
| Johnson & Johnson Services, Inc. |
| Haleon plc |
| Unilever plc |
| Church & Dwight Co., Inc. |
| Pigeon Corporation |
| Lion Corporation |
| Sunstar Suisse S.A. |
| Others |
Pricing and Supply Chain Analysis
Premium natural certification tiers diverge from mass-market fluoride formulations through ingredient sourcing requirements and EPA compliance infrastructure investments. This bifurcation concentrates pricing power among capitalized manufacturers while fragmenting procurement strategies across organic-certified and conventional supply bases.
Pricing Analysis
Subscription-based recurring revenue anchors value capture in the children's oral care market. Three-tier pricing structure across premium natural, standard fluoridated, and economy private-label levels separates buyers by certification grade and clinical endorsement intensity. Cost compression in infant-specific formulations intensifies because FDA-mandated fluoride ceilings below 500 ppm constrain efficacy differentiation. Mass-market supermarket buyers exhibit highest price sensitivity; pharmacy-channel purchasers of specialty rinse products show lowest elasticity due to professional recommendation dependence.
Supply Chain Analysis
Dual-sourcing requirements for low-abrasivity silica bases mandate multi-supplier qualification across China, Germany, and the United States. Raw material dependencies center on refined silica grades, nylon 6,12 polymer feedstocks, and plant-derived surfactant alternatives. Single-source vulnerability concentrates in EPA-compliant wastewater treatment capacity for fluoridated formulation production. Distribution runs through supermarket mass retail for volume, pharmacy consultation networks for margin, and direct-to-consumer subscription platforms for recurring revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The children's oral care market functions as a cost-of-compliance story where the FDA's monograph system erects barrier-to-entry moats favoring manufacturers with validated pediatric toxicology expertise and multi-site EPA infrastructure.
For Market Incumbents: Extend pharmacist consultation program coverage to defend specialty rinse positioning against direct-to-consumer subscription entrants. Deepen backward integration into low-abrasivity silica processing to secure input cost stability amid construction and electronics demand competition. Prioritize dual-certification capacity investment to compress launch timelines for natural-organic hybrid formulations. For New Entrants and Emerging Players: Subscription-fatigued urban coastal households represent an underserved buyer archetype vulnerable to pharmacy-channel recapture with trained staff consultation. White-space concentration appears in infant-specific certified organic lines and school-based preventive program procurement contracts. Penetrate through institutional endorsement bundling with pediatric dental clinic expansion in Texas and Florida. For Investors and Strategic Acquirers: Re-rating potential sits with pharmacy-channel specialists given pharmacist-driven recommendation network scalability across fragmented regional markets. Long-term viability favors operators with captive EPA-compliant manufacturing infrastructure and age-staged product curation systems. Watch state-level PFAS restriction adoption velocity as inflection indicator for PFAS-free certification claim valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacist Consultation Program Expansion | Haleon plc's recommendation-dependent rinse products demonstrate professional endorsement capture at margin premiums above mass retail. |
| Direct-to-Consumer Subscription Launch | Age-staged automatic formulation advancement displaces episodic purchasing in urban coastal United States households. |
| Premium Natural Tier Introduction | ISO 11609 abrasivity parity enables clean-label migration from adult to pediatric categories with certification price premiums. |
| Distribution Channel Expansion | School-based preventive program procurement in Texas and Florida creates volume anchors for toothbrush-toothpaste bundling. |
| Sustainability Repositioning | PFAS-free certification claims exploit emerging state-level prohibitions on per- and polyfluoroalkyl substances in packaging. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pediatric dental clinic directors, pharmacy category managers, formulation chemists, and contract manufacturing executives combined with FDA monograph documentation, EPA discharge compliance records, and ISO 11609 certification databases. Bottom-up product-level volume builds triangulated against top-down category spend estimates from retail audit providers.
Granularity-level modeling operated at product-type, age-group, formulation, and distribution-channel intersections with geographic disaggregation to country level. CAGRs derived from segment-level growth rate convergence across the projection horizon. Forecast inputs incorporated pediatric dental clinic expansion rates, clean-label preference migration velocity, and EPA effluent standard tightening schedules.
Revisions become necessary when FDA monograph amendments, state-level PFAS restriction cascades, or silica supply disruptions materialize. Deviation in pharmacist consultation program penetration or subscription adoption curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Japan Oral Hygiene Market
Oral Care
Oral Health Ingredient Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
Oral Care Market
Oral Care
China Oral Care Market
Oral Care
Oral Rinse Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Europe Oral Care Market
Oral Care
LED Oral Care Kits Market
Oral Care
Oral Thin Films Market
Oral Care
Oral Mucositis Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
North America Oral Care Market
Oral Care
Halitosis Treatment Market
Oral Care
Baby Oral Care Market
Oral Care
Kids Toothpaste Market